
 Africa Soy Beverages Market | 2026-2036
Africa Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Soy Beverages Market Outlook
ISO 22000 food safety management certification is rotating as the primary gating standard for commercial-scale soy beverage manufacturing across African markets. Danone S.A. leverages its existing dairy distribution infrastructure to extend shelf-stable soy drinks into West African retail networks. Clover S.A. (Pty) Ltd anchors its competitive position through backward integration into domestic soybean crushing and localized carton filling operations. PepsiCo, Inc. competes through aggressive pricing in Nigeria's informal trade channels where pouch formats dominate volume.
Soy beverages constitute aqueous extracts of whole soybeans or soy protein isolates, typically formulated to contain 2.5–3.5% protein content and homogenized at 150–200 bar to ensure colloidal stability during ambient distribution. The product serves as a functional dairy alternative for lactose-intolerant populations and as a cost-competitive protein source in food manufacturing applications. Soy milk leads product type revenue due to established consumer familiarity and lower per-unit production complexity, while soy yogurt captures faster trajectory among health-focused urban demographics in Nairobi and Cape Town. Tetra Pak aseptic carton packaging dominates the structural margin pool by reducing cold-chain dependency across regions with unreliable refrigeration infrastructure.
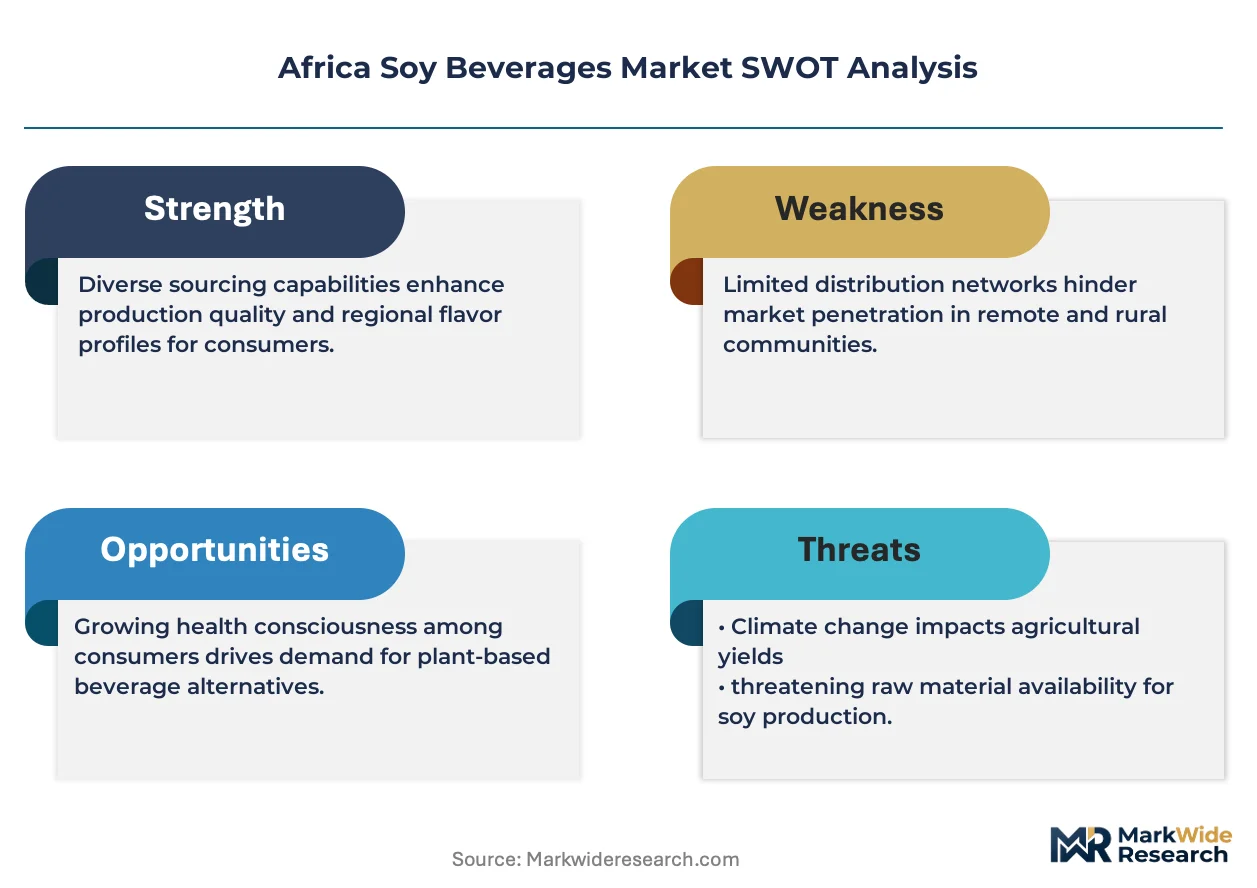
South Africa's Department of Health enforces food fortification mandates that shape soy milk nutritional labeling requirements, while Kenya's Bureau of Standards (KEBS) regulates maximum aflatoxin thresholds in imported soybean inputs. Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) imposes registration protocols that delay market entry for unbranded imports. Stakeholders must monitor harmonization progress under the African Continental Free Trade Area's mutual recognition agreements, as tariff alignment between regional blocs will determine which manufacturing configurations achieve sustainable cross-border scale.
Market Dynamics
ISO 22000 certification requirements are compressing manufacturing scale thresholds across Africa's soy beverage sector, forcing mid-tier processors to consolidate or exit as food safety compliance costs escalate.
Growth Catalysts
- Lactose intolerance prevalence:Urban households in Nigeria and South Africa are driving soy milk consumption as a functional dairy alternative, with diagnostic rates climbing among middle-income demographics.
- KEBS aflatoxin standards:Kenya's Bureau of Standards enforcement on imported soybean inputs is accelerating domestic crushing investments and shortening supply chains for local processors.
- Tetra Pak aseptic technology:Ambient-stable carton packaging is reducing cold-chain dependency across regions with unreliable refrigeration, extending distribution reach into secondary cities.
Market Restraints
- Soybean input volatility:Weather-driven yield fluctuations in South Africa's Free State province create margin compression for processors lacking forward-contracting capabilities.
- NAFDAC registration timelines:Nigeria's National Agency for Food and Drug Administration and Control protocols impose 12-18 month delays for unbranded import market entry, freezing capital.
- Animal milk price competition:Powdered dairy imports from European Union trade preferences undercut soy beverage pricing in informal retail channels.
Strategic Opportunities
- AfCFTA tariff alignment:African Continental Free Trade Area mutual recognition agreements will enable cross-border manufacturing scale for compliant processors.
- Soy yogurt white space:Health-focused urban demographics in Nairobi and Cape Town present underdeveloped demand for fermented soy protein formats.
- Pouch format penetration:Single-serve flexible packaging is capturing volume in Nigeria's informal trade channels where price-point sensitivity dominates.
Industry Challenges
- ISO 22000 implementation gap:Certified food safety management expertise remains scarce among mid-scale African processors, extending compliance timelines.
- Backward integration capex:Captive soybean crushing and localized carton filling require capital deployment that exceeds traditional dairy equipment financing thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Soy Beverages Market |
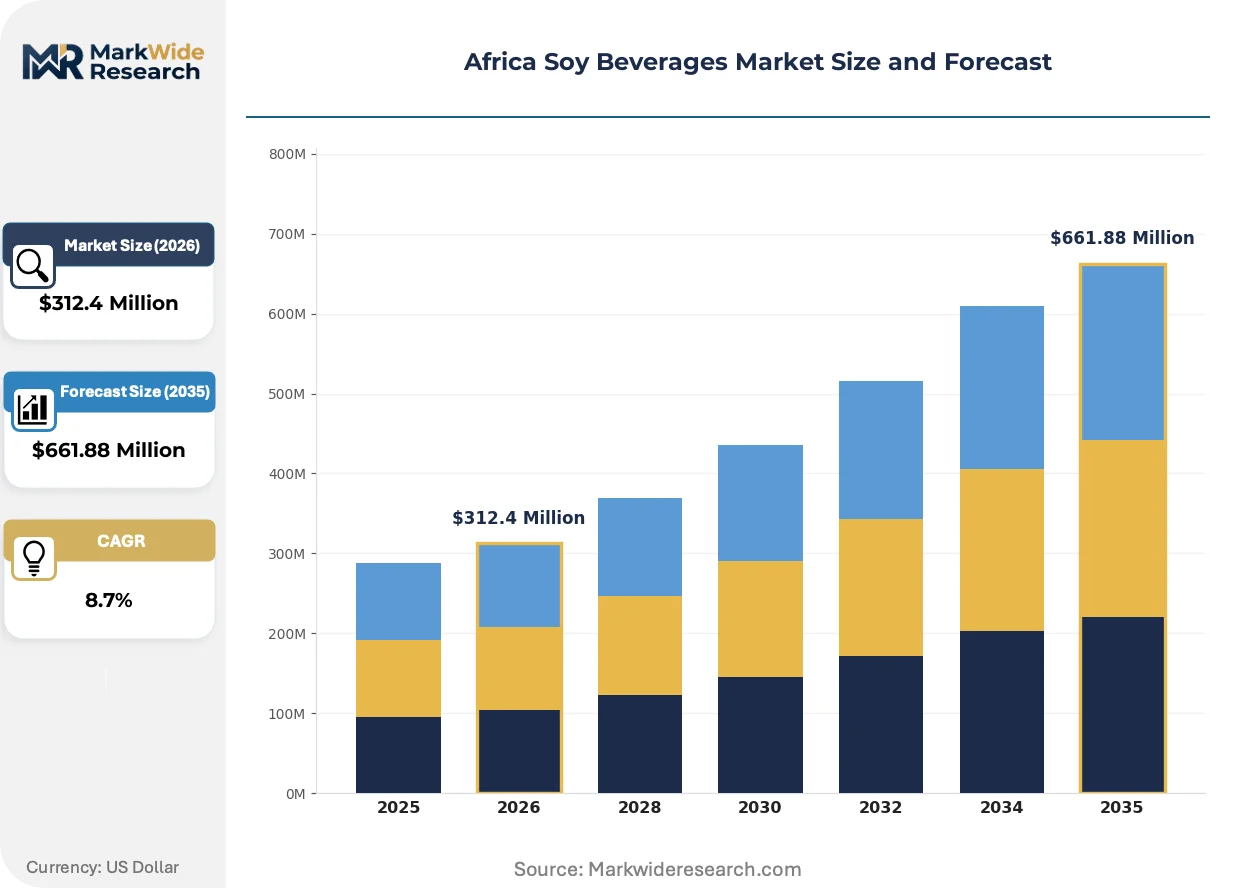
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Soy Protein Isolate, Soy Yogurt, Soy Drinks End User: Households, Restaurants, Food Manufacturers, Fitness Centers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Wet Markets Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Nestlé S.A., Clover S.A. (Pty) Ltd, The Coca-Cola Company, Eden Foods, Inc., Groupe Lactalis, Danone S.A., The Hain Celestial Group, Inc., Pulmuone Holdings Co., Ltd., PepsiCo, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Soy Beverages Market Strategic Shifts
Processing technology and packaging formats are converging to reshape competitive positioning across Africa's soy beverage value chain, with certification standards and distribution infrastructure acting as the primary vectors of change.
UHT aseptic processing combined with Tetra Pak carton systems is supplanting refrigerated supply chains in West and East African markets. Nigerian distributors operating in the Lagos-Abuja corridor are adopting ambient-stable formats at accelerating rates. This technology compression is enabling national-brand penetration into secondary cities previously served only by informal dairy vendors.
South Africa's Department of Health fortification mandates are reshaping soy milk nutritional labeling requirements and protein content thresholds. Manufacturers must reformulate to meet vitamin and mineral enrichment standards before retail distribution authorization. The Gauteng province retail network is responding fastest, with compliant products capturing shelf space in formal supermarket channels.
Urban household purchasing is rotating toward functional health claims and lactose-free positioning in Nigeria and Kenya. Traditional loose-vendor milk channels are losing share to branded soy alternatives with certified safety credentials. Nairobi's middle-income suburbs exhibit the strongest visible shift, with supermarket soy beverage velocity climbing fastest among health-conscious family segments.
Africa Soy Beverages Market Segmentation
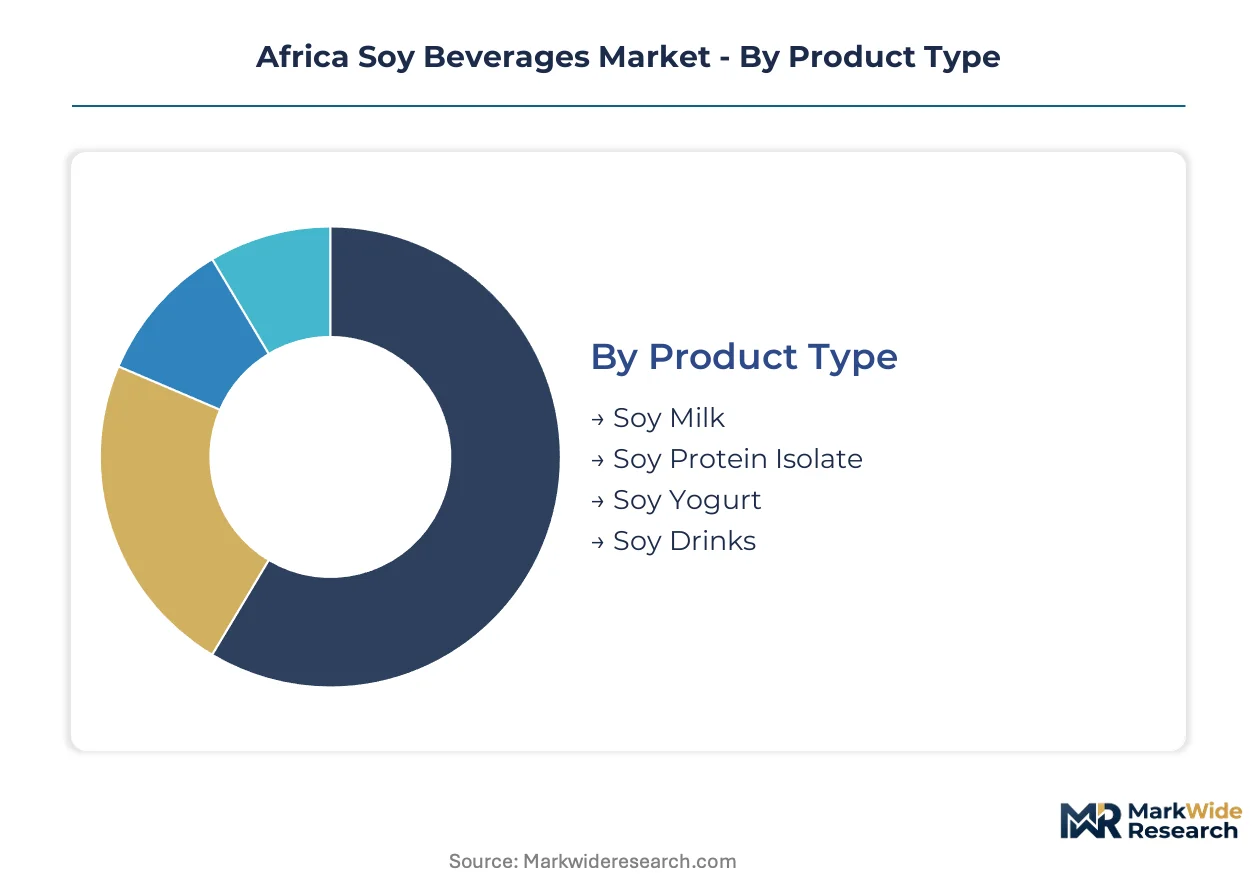
Regulatory differentiation across African markets fragments addressable demand into distinct compliance tiers, with ISO 22000 certification and national fortification mandates creating non-uniform product specifications. Segmentation reveals where capital deployment achieves scale versus where localized formulation wins shelf space.
Product Type:
South Africa's Department of Health fortification mandates and Kenya's KEBS aflatoxin thresholds split product categories by compliance burden and protein content thresholds.
- Soy Milk:Aqueous extracts of whole soybeans containing 2.5–3.5% protein, homogenized at 150–200 bar for colloidal stability. Lagos-Abuja corridor households drive volume as lactose intolerance diagnostic rates climb among middle-income demographics. Tetra Pak aseptic cartons dominate this segment's margin pool by eliminating cold-chain dependency.
- Soy Yogurt:Fermented soy protein formats with live cultures, requiring controlled fermentation infrastructure. Nairobi and Cape Town health-focused urban demographics present underdeveloped demand with steepest expansion trajectory among functional dairy alternatives.
- Soy Protein Isolate:Concentrated protein extracts for food manufacturing applications and sports nutrition formulations.
- Soy Drinks:Flavored and sweetened ready-to-consume beverages targeting informal retail channels.
Soy milk handles the majority of throughput; soy yogurt is expanding most quickly on share.
End User:
Cost tier stratification separates premium-positioned channels from price-sensitive bulk procurement.
- Households:Urban family units purchasing through formal retail for daily consumption. Gauteng province supermarkets and Lagos-Abuja corridor distributors capture the highest velocity as certified safety credentials displace traditional loose-vendor milk channels.
- Restaurants:Food service operators sourcing bulk formats for recipe integration.
- Food Manufacturers:Industrial buyers requiring consistent protein specifications for processed food applications.
- Fitness Centers:Health clubs and gyms distributing ready-to-drink formats to member bases seeking post-workout protein delivery.
Households absorb the dominant share of finished product volume; fitness centers are climbing fastest as a customer acquisition channel.
Distribution Channel:
Volume concentration tracks refrigeration infrastructure reliability and formal retail penetration rates.
- Supermarkets:Formal retail networks with ambient-stable shelf space and nutritional labeling compliance. South Africa's Gauteng province and Nigeria's urban centers concentrate throughput as NAFDAC-registered products secure authorization.
- Online Retail:E-commerce platforms serving middle-income suburbs with delivery-dependent fulfillment.
- Health Food Stores:Specialty retailers targeting functional health claims and organic positioning in Nairobi and Cape Town.
- Wet Markets:Traditional informal trading venues where pouch formats and aggressive pricing compete with powdered dairy imports.
Supermarkets command the largest revenue share; online retail is gaining traction fastest among urban professional segments.
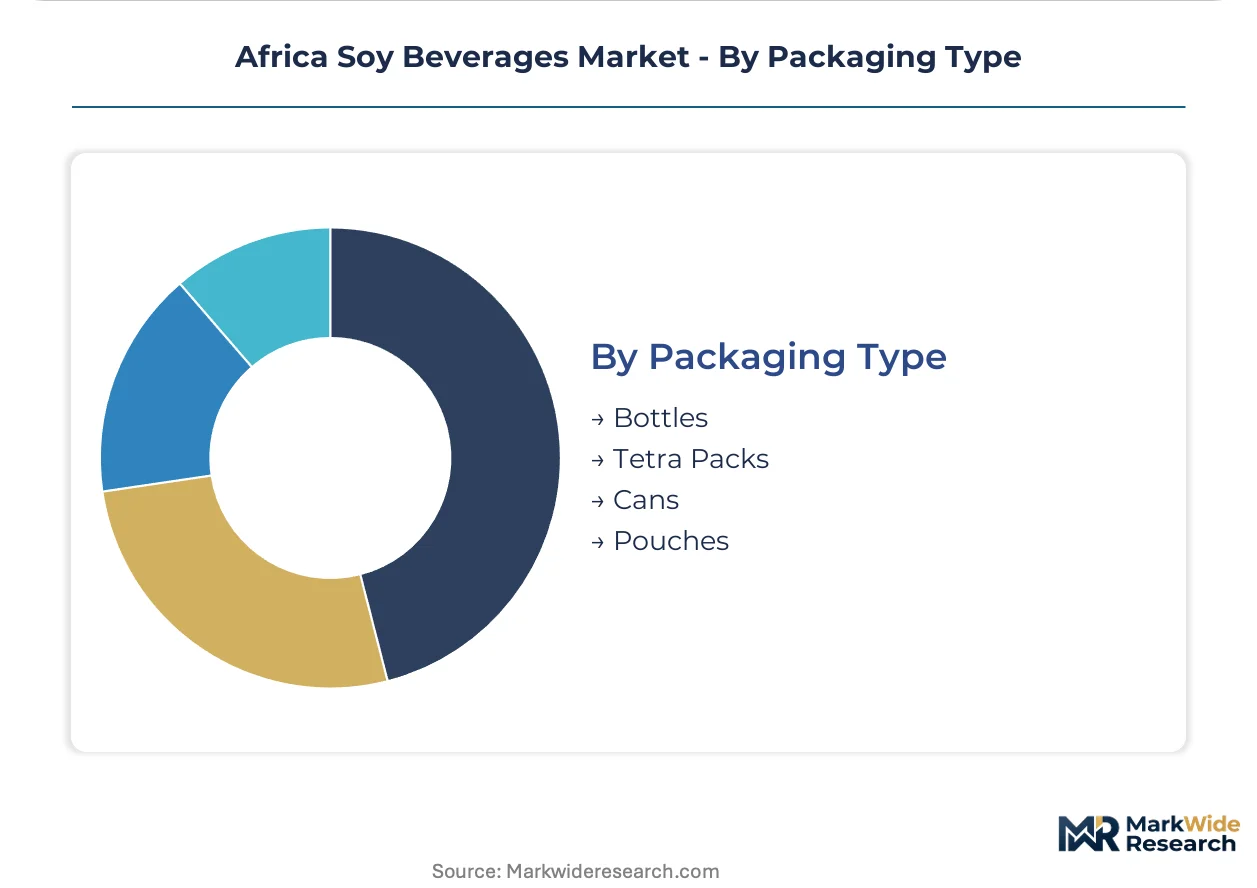
Packaging Type:
Margin structure follows cold-chain dependency and material cost differentials.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without refrigeration. West and East African distributors adopt these formats at accelerating rates to penetrate secondary cities previously served only by informal dairy vendors.
- Pouches:Single-serve flexible packaging capturing volume in Nigeria's informal trade channels where price-point sensitivity dominates purchasing decisions.
- Bottles:PET and HDPE containers for refrigerated distribution networks with established cold-chain infrastructure.
- Cans:Metal packaging for extended shelf-life applications and export-oriented production.
Tetra packs carry the structural margin advantage; pouches are scaling fastest in informal channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban households with lactose intolerance dominate purchasing decisions across Africa's soy beverage corridors. Distribution networks concentrate in metropolitan clusters where formal retail penetration and cold-chain reliability diverge sharply. National regulators enforce divergent fortification and safety standards that fragment manufacturing scale.
Nigeria
Lagos-Abuja corridor households drive volume as diagnostic rates for lactose intolerance climb among middle-income demographics. NAFDAC registration protocols impose 12-18 month delays for unbranded imports, freezing capital for new entrants. Tetra Pak aseptic cartons are penetrating secondary cities previously served only by informal dairy vendors.
South Africa
Gauteng province supermarkets capture the highest velocity as certified safety credentials displace traditional loose-vendor milk channels. The Department of Health enforces food fortification mandates that reshape soy milk nutritional labeling requirements. Localized carton filling operations in Johannesburg anchor backward integration strategies for domestic processors.
Kenya
Nairobi's middle-income suburbs exhibit the strongest visible shift toward branded soy alternatives with certified safety credentials. KEBS enforcement on maximum aflatoxin thresholds in imported soybean inputs accelerates domestic crushing investments. Health food stores in the capital target functional health claims and organic positioning for fermented soy protein formats.
Egypt
Cairo metropolitan households absorb significant volume through informal trade channels where price-point sensitivity dominates purchasing decisions. The country's national food safety regulator tightens ingredient sourcing rules for commercial-scale manufacturing. Alexandria's port infrastructure handles soybean import flows that supply Red Sea coastal processing clusters.
Ghana
Accra-Tema metropolitan demand concentrates among urban professionals seeking post-workout protein delivery through ready-to-drink formats. National standards authorities align with ECOWAS mutual recognition agreements for cross-border trade facilitation. Kumasi's emerging retail networks adopt ambient-stable packaging to extend distribution reach without refrigeration dependency.
Africa Soy Beverages Market Competitive Environment
Player mix skews toward multinational beverage conglomerates with existing dairy distribution infrastructure and regional African processors with captive soybean supply. Market structure exhibits tiered consolidation: global FMCG majors leverage scale economies at the premium shelf-stable tier, while mid-scale domestic operators compete on price in informal channels. Two strategic archetypes dominate: infrastructure-heavy integrators controlling crushing-to-carton value chains, and brand-marketing specialists outsourcing production to licensed co-manufacturers. Competitive moves center on geographic expansion through distributor partnerships and portfolio diversification into fermented protein formats.
Among the multinational tier, Danone S.A. and PepsiCo, Inc. exemplify divergent channel strategies—Danone extending shelf-stable soy drinks through West African retail networks, PepsiCo deploying aggressive pricing in Nigeria's informal trade where pouch formats dominate volume. Clover S.A. (Pty) Ltd occupies a position as the infrastructure-integrated archetype, with backward control over domestic soybean crushing and localized filling operations. Nestlé S.A. and The Coca-Cola Company sit within the brand-marketing specialist tier, leveraging existing beverage distribution muscle without captive production assets.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Clover S.A. (Pty) Ltd |
| The Coca-Cola Company |
| Eden Foods, Inc. |
| Groupe Lactalis |
| Danone S.A. |
| The Hain Celestial Group, Inc. |
| Pulmuone Holdings Co., Ltd. |
| PepsiCo, Inc. |
| Others |
Value Chain & Pricing Dynamics
Soybean meal substitution for imported dairy proteins is redrawing procurement geography across West African processors while compressing formulation cost structures. This input swap simultaneously elevates domestic crushing capacity valuations and erodes the premium commanded by European milk powder imports.
Pricing Analysis
Cost-plus contracts indexed to South African Futures Exchange soybean prices dominate procurement agreements for processors lacking captive crushing assets. Three-tier pricing structure across premium ISO 22000-certified cartons, standard KEBS-compliant formats, and economy pouch lines separates formal supermarket channels from informal wet markets. Pricing pressure stems from EU dairy trade preferences undercutting soy alternatives in Nigeria's unbranded import segment. Households in Lagos-Abuja corridor exhibit highest price sensitivity, while Gauteng province health-food retailers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Durban port congestion acts as the primary logistics chokepoint for soybean imports serving South Africa's Free State crushing plants and Gauteng filling operations. Supply concentration centers on Argentina, Brazil, and domestic South African harvests for raw bean inputs, with Tetra Pak aseptic carton systems and flexible pouch substrates drawing from European and Asian converters. Single-source vulnerability in aflatoxin-tested ingredient streams exposes processors to KEBS enforcement delays. Distribution runs through Danone and Clover's dairy-aligned cold-chain networks for formal retail, with independent distributors handling ambient-stable pouch volumes into Nigeria's informal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and regional fortification mandates creates specialist niches for processors with targeted compliance capabilities. Urban lactose intolerance diagnostics climbing among middle-income households splinters demand into functional health, economy nutrition, and industrial ingredient segments.
For Market Incumbents: Compound defensive moats by deepening backward integration into domestic crushing and securing exclusive Tetra Pak filling line capacity in Johannesburg and Lagos. ISO 22000 certification investment blocks mid-tier challengers from formal retail authorization, while pouch format co-manufacturing partnerships defend volume share against PepsiCo's informal channel pricing.
For New Entrants and Emerging Players: Fermented soy protein service-layer gaps in Nairobi and Cape Town health-food channels offer white-space penetration with live-culture production capabilities. Soy yogurt formats remain underdeveloped relative to milk alternatives, presenting the most penetrable premium tier. Go-to-market execution should anchor in specialty retail partnerships with organic positioning before supermarket authorization.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors infrastructure-integrated processors with captive supply and localized filling assets. Long-term viability across the projection horizon rests on AfCFTA tariff alignment enabling cross-border manufacturing scale. Acquisition screening should prioritize KEBS and NAFDAC pre-certified operators; the signal to watch is harmonization progress under mutual recognition agreements as inflection indicator for regional roll-up economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Crushing | Captive supply from Free State farms insulates processors from Durban port congestion and currency volatility. |
| ISO 22000 Certification Investment | Food safety credentials unlock formal supermarket shelf space in Nigeria's NAFDAC-regulated channels. |
| Aseptic Carton Format Expansion | Tetra Pak ambient-stable packaging eliminates cold-chain dependency for secondary city distribution. |
| Soy Yogurt Portfolio Diversification | Fermented protein formats capture health-focused urban demographics in Nairobi and Cape Town. |
| AfCFTA Cross-Border Manufacturing Scale | Tariff alignment enables Gauteng production to serve Kenya and Ghana under mutual recognition. |
Study Parameters
The analysis maps soy milk, soy yogurt, protein isolate, and flavored drink sub-sectors, each validated through procurement directors at beverage processors, category buyers at South African supermarket chains, and regulatory affairs specialists navigating NAFDAC and KEBS protocols. Primary interview insights triangulated against secondary sources including UN Comtrade soybean import records, Tetra Pak processing equipment deployment databases, and national fortification mandate filings. Bottom-up volume builds from named city corridor consumption patterns cross-checked with top-down value estimates from retail audit data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-user cost tier, distribution channel refrigeration dependency, and packaging format cold-chain requirements. CAGRs derived from segment-level growth rate synthesis with urbanization and lactose intolerance diagnostic trends as industry-specific demand inputs.
Forecasts assume regulatory continuity in Nigeria's NAFDAC registration protocols and Kenya's KEBS aflatoxin enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as AfCFTA harmonization timelines and South African drought frequency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Vegan Food Market
Plant Based Food
France Plant Protein Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Soy Protein Market
Plant Based Food
South America Soy Beverages Market