
 Soy Beverage Market | 2026-2036
Soy Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Beverage Market Analysis
EU Green Deal sustainability benchmarks are rebalancing the cost-of-entry calculus for European soy beverage manufacturers, forcing reformulation investments and supply chain audits. Alpro leverages its Danone parent infrastructure to sustain organic sourcing networks across Benelux processing hubs. Vitasoy International anchors its position through vertical control over Asian soybean procurement corridors. SunOpta competes via specialized aseptic packaging capabilities that extend shelf stability for private-label clients.
Soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically standardized to protein concentrations between 2.5% and 4.0% and fortified with calcium, vitamin D, and vitamin B12 to mimic nutritional parity with cow's milk. The extraction process involves soaking, grinding, enzymatic treatment, and ultra-high-temperature pasteurization to eliminate beany off-flavors and ensure microbial safety. Flavored and organic product types command premium positioning as health food stores and online retail channels capture margin pools from convenience-oriented consumers. Tetra Pak packaging dominates ambient distribution while bottles anchor chilled segments in supermarket dairy alternatives aisles.
FDA nutrition labeling rules and USDA organic certification requirements govern product claims and interstate commerce in the United States, while EFSA health claim assessments and REACH chemical safety protocols shape European formulation standards and packaging material selections. China's SAMR national food safety standards and GB labeling codes impose additional compliance layers for exporters targeting domestic retail channels. Stakeholders must monitor evolving protein-content thresholds and sustainability disclosure mandates across these jurisdictions to preserve market access and premium positioning.
Market Dynamics
Protein-content standardization across export jurisdictions is forcing simultaneous reformulation cycles, as manufacturers must reconcile divergent FDA, EFSA, and SAMR thresholds without fragmenting production lines.
Growth Catalysts
- EFSA Protein Benchmarks:Germany's enforcement of minimum protein thresholds for dairy-alternative labeling is pulling higher-concentration formulations into mainstream retail, elevating perceived nutritional parity.
- Enzymatic Debittering:Lipoxygenase inhibition protocols are eliminating beany off-flavors that previously constrained repeat purchase rates among Western palates.
- Benelux Organic Sourcing:Concentrated organic soybean procurement networks across Belgium and the Netherlands are reducing input cost volatility for premium-tier producers.
Market Restraints
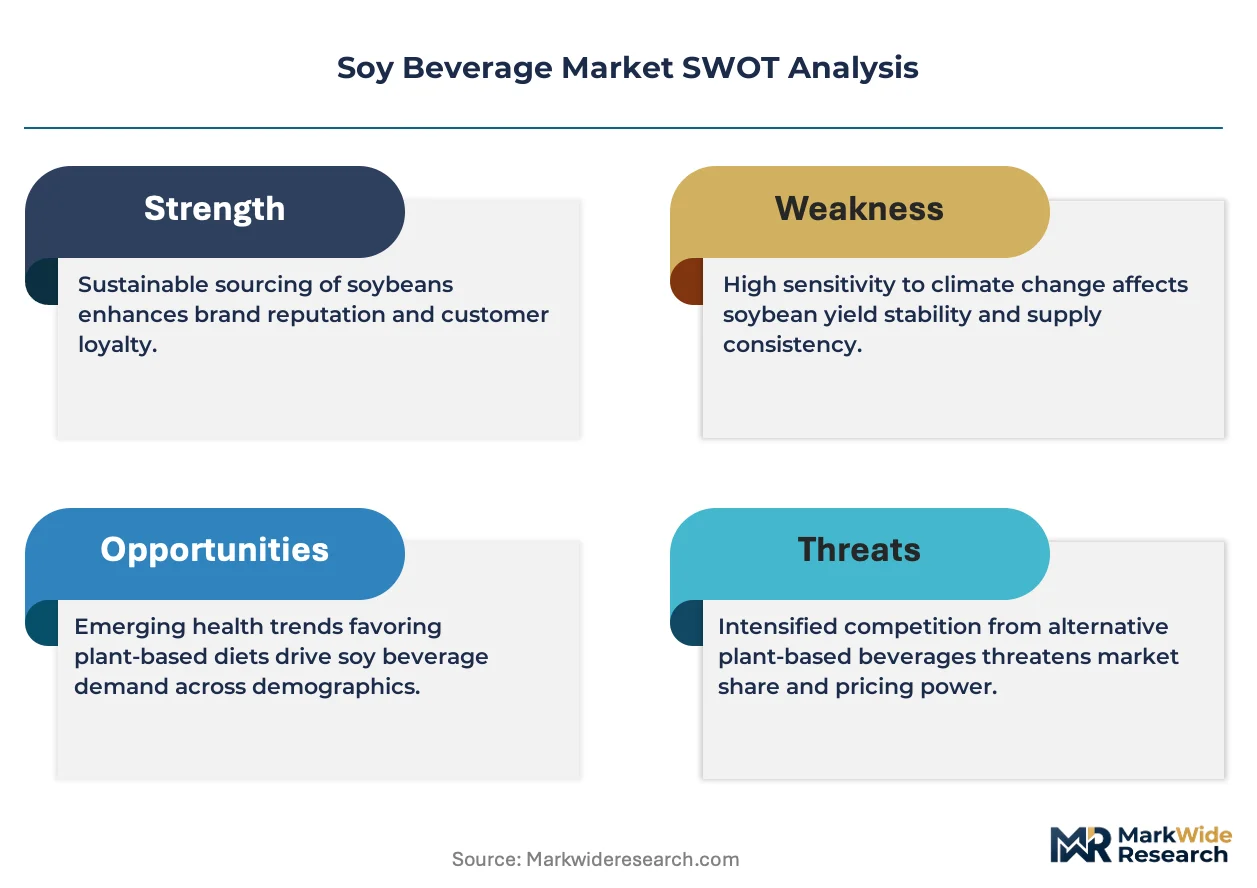
- Input Cost Volatility:Non-GMO soybean premiums fluctuate with Brazilian harvest cycles, compressing margin stability for organic-certified processors.
- Supply Concentration Risk:Aseptic packaging substrate production clusters in Swedish and Finnish forest-product corridors, creating single-source vulnerability for ambient-stable formats.
- Substitution Threat:Oat and pea protein isolates are capturing shelf space in German and UK retail, fragmenting plant-based beverage demand.
Strategic Opportunities
- Underpenetrated Geography:India's FSSAI regulatory clarity on plant-based protein fortification is opening formulation pathways previously blocked by ambiguous standards.
- Regulatory Tailwind:The EU Green Deal's sustainability disclosure mandates are creating first-mover advantage for processors with verified deforestation-free supply chains.
- Channel Innovation:Direct-to-subscription models through specialized health platforms are bypassing traditional dairy-alternative aisle congestion in France and Italy.
Industry Challenges
- Certification Timeline Compression:USDA organic and EU organic dual-certification audits now require 14-18 month synchronization, delaying product launches.
- Skill Scarcity in Enzymology:Food biochemists capable of optimizing protease treatments for texture modification command premium compensation, constraining R&D scaling.
- Legacy System Integration:Tetra Pak filling lines require substantial retrofitting to handle higher-viscosity fortified formulations, demanding capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Beverage Market |
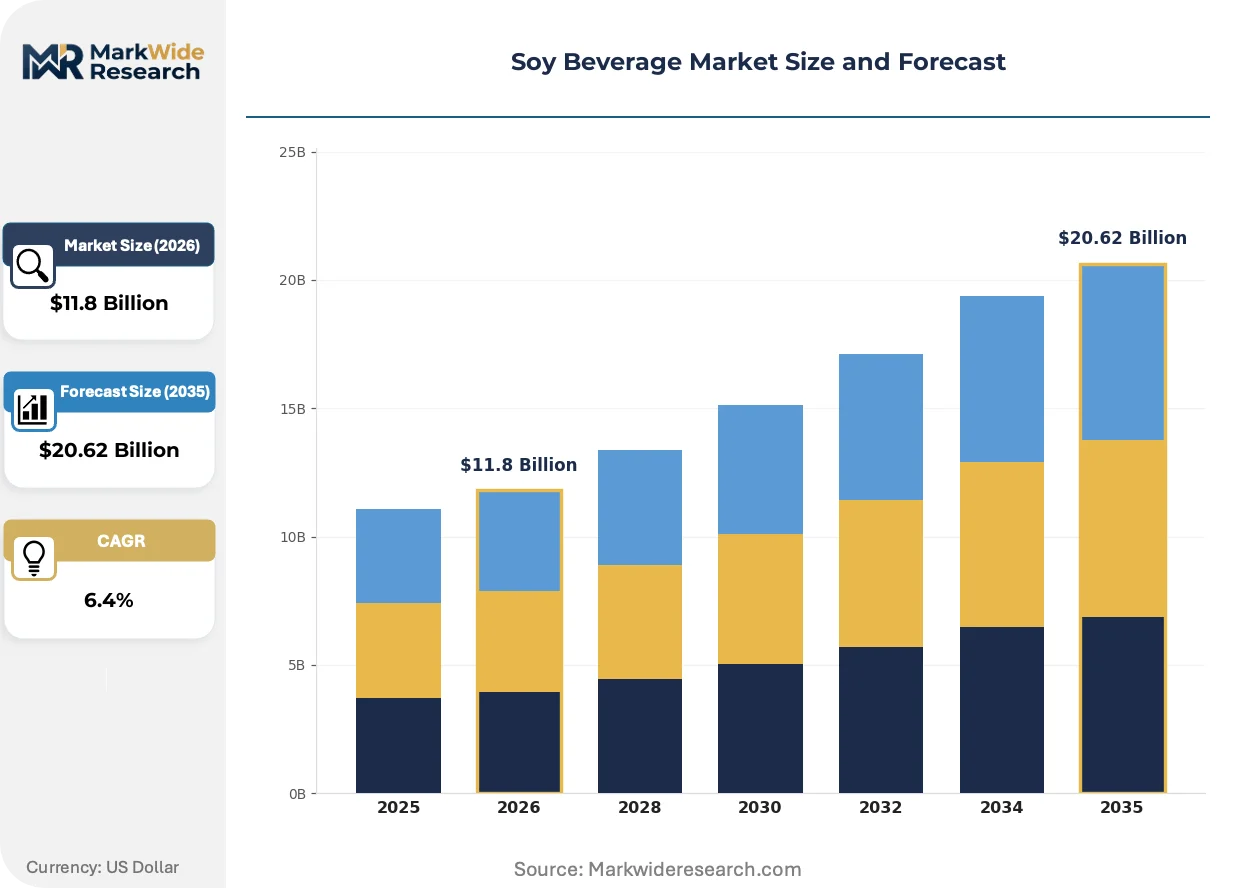
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Organic, Non-Dairy Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores End User: Fitness Enthusiasts, Lactose Intolerant Consumers, Vegans, Health-Conscious Individuals Packaging Type: Bottles, Tetra Paks, Cans, Pouches |
| Companies Covered | Vitasoy International Holdings Ltd., Alpro (Danone S.A.), Earth's Own Food Company Inc., SunOpta Inc., Pacific Foods of Oregon LLC, Kikkoman Corporation, Eden Foods Inc., Morinaga Milk Industry Co., Ltd., Pulmuone Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Beverage Market Emerging Trajectories
Enzymatic processing advances and packaging material innovations are compressing the sensory gap between plant-based and conventional dairy, while procurement patterns shift toward verified sustainable sourcing.
High-pressure processing is rewriting the shelf-stability calculus for chilled soy beverages. Premium supermarket chains in France and Italy are adopting HPP-treated SKUs at accelerating rates. This technology is rewriting the geographic reach of regional processors, enabling chilled distribution beyond traditional 200-kilometer radius constraints.
REACH chemical safety protocols are forcing migration from epoxy-based can linings to polyester alternatives in European ambient packaging. Reformulation costs concentrate among mid-tier private-label suppliers lacking parent-company R&D scale. Organic and premium-branded segments are absorbing compliance premiums fastest, converting regulatory burden into positioning differentiation.
Buyer concentration among specialized health-food platforms is disintermediating conventional wholesale-distributor relationships. German and Dutch e-commerce aggregators now command direct allocation from processors, compressing traditional retail margin stacks. This pattern is most visible in organic-flavored variants, where subscription lock-in rates exceed conventional channel loyalty metrics.
Soy Beverage Market Segmentation
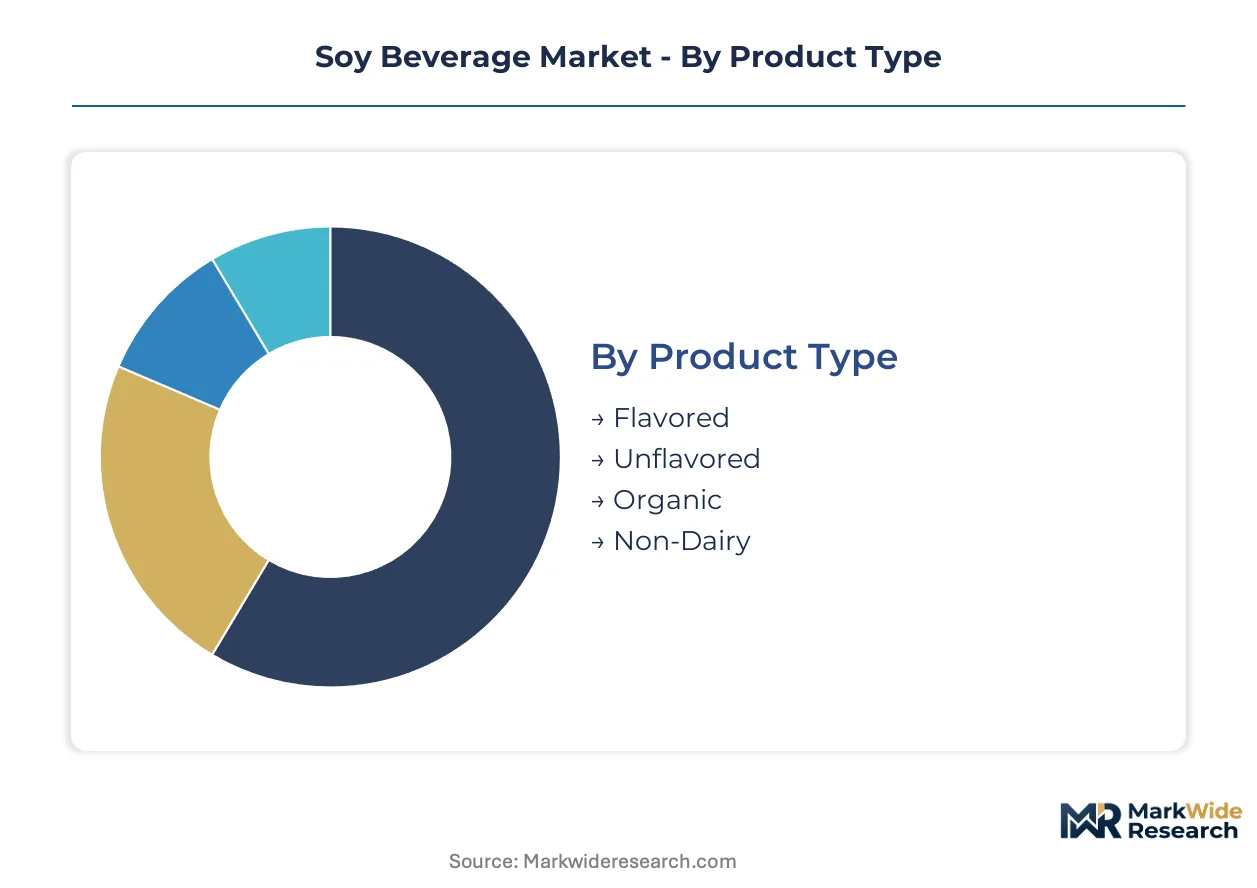
Segmentation in soy beverages reveals how protein-content thresholds, enzymatic processing investments, and packaging substrate choices fragment competitive positioning across price tiers and channel access. Manufacturers must align formulation specifications with jurisdiction-specific labeling rules while managing divergent margin structures between ambient and chilled distribution.
Product Type:
Volume concentration clusters in standard formulations, while premium capture concentrates in certified organic and sensory-enhanced variants with higher input costs and extended production cycles.
- Flavored:Vanilla, chocolate, and coffee infusions mask residual beany notes through natural flavor masking systems. German retailers are expanding shelf allocation for flavored SKUs as EFSA protein-content benchmarks elevate nutritional parity signaling among mainstream consumers.
- Unflavored:Plain formulations emphasize protein density and clean-label positioning for cooking applications and smoothie bases. Demand concentrates in North American foodservice channels where operators value neutral flavor profiles for recipe integration.
- Organic:Certified organic variants command input premiums tied to non-GMO soybean procurement and dual USDA-EU organic audits. Benelux processing hubs anchor supply networks for European distribution.
- Non-Dairy:This designation captures lactose-free positioning and broader plant-based dietary alignment without organic certification requirements. Price compression is most severe in this tier due to oat and pea protein substitution.
Mature deployment sits with Unflavored. Newer deployment is concentrated in Organic.
Distribution Channel:
Channel selection determines margin stack depth, with direct allocation models compressing traditional wholesale layers and subscription platforms capturing recurring revenue streams.
- Online Retail:E-commerce aggregators in Germany and the Netherlands now command direct processor allocation, bypassing conventional distributor relationships. Subscription lock-in rates for organic-flavored variants exceed conventional channel loyalty metrics significantly.
- Supermarkets:Chilled dairy-alternative aisles in France and Italy anchor volume throughput, with Tetra Pak ambient formats competing for shelf-stable positioning. High-pressure processing is extending chilled distribution radii beyond traditional constraints.
- Convenience Stores:Single-serve bottles dominate this channel, prioritizing grab-and-go consumption occasions over nutritional signaling. Ambient-stable packaging is essential given refrigeration limitations.
- Health Food Stores:Specialized retailers concentrate premium and organic SKUs with educated staff driving conversion through protein-content and sourcing narratives. REACH-compliant packaging migrations are most visible in this channel.
Margin concentration sits with Health Food Stores. Volume scaling is concentrated in Supermarkets.
End User:
User motivation splits between performance-oriented protein seekers and avoidance-driven dietary restriction management, with distinct formulation and messaging requirements.
- Fitness Enthusiasts:Post-workout recovery positioning emphasizes protein concentration above 3.5% and leucine content for muscle protein synthesis. Sports nutrition channels in the United States favor these specifications.
- Lactose Intolerant Consumers:Digestive comfort positioning targets the estimated majority of adults with reduced lactase persistence. This segment shows lowest brand loyalty and highest price sensitivity among major user groups.
- Vegans:Ethical and environmental alignment drives preference for deforestation-free supply chains and transparent sourcing disclosures. EU Green Deal sustainability mandates are creating first-mover advantage for verified processors.
- Health-Conscious Individuals:General wellness positioning emphasizes clean labels, reduced sugar, and fortification with calcium and vitamin D. FDA nutrition labeling compliance is table stakes for this segment.
Retention difficulty sits with Lactose Intolerant Consumers. Value capture is concentrated in Vegans.
Packaging Type:
Packaging substrate selection shapes shelf stability, distribution economics, and regulatory compliance burdens across ambient and chilled supply chains.
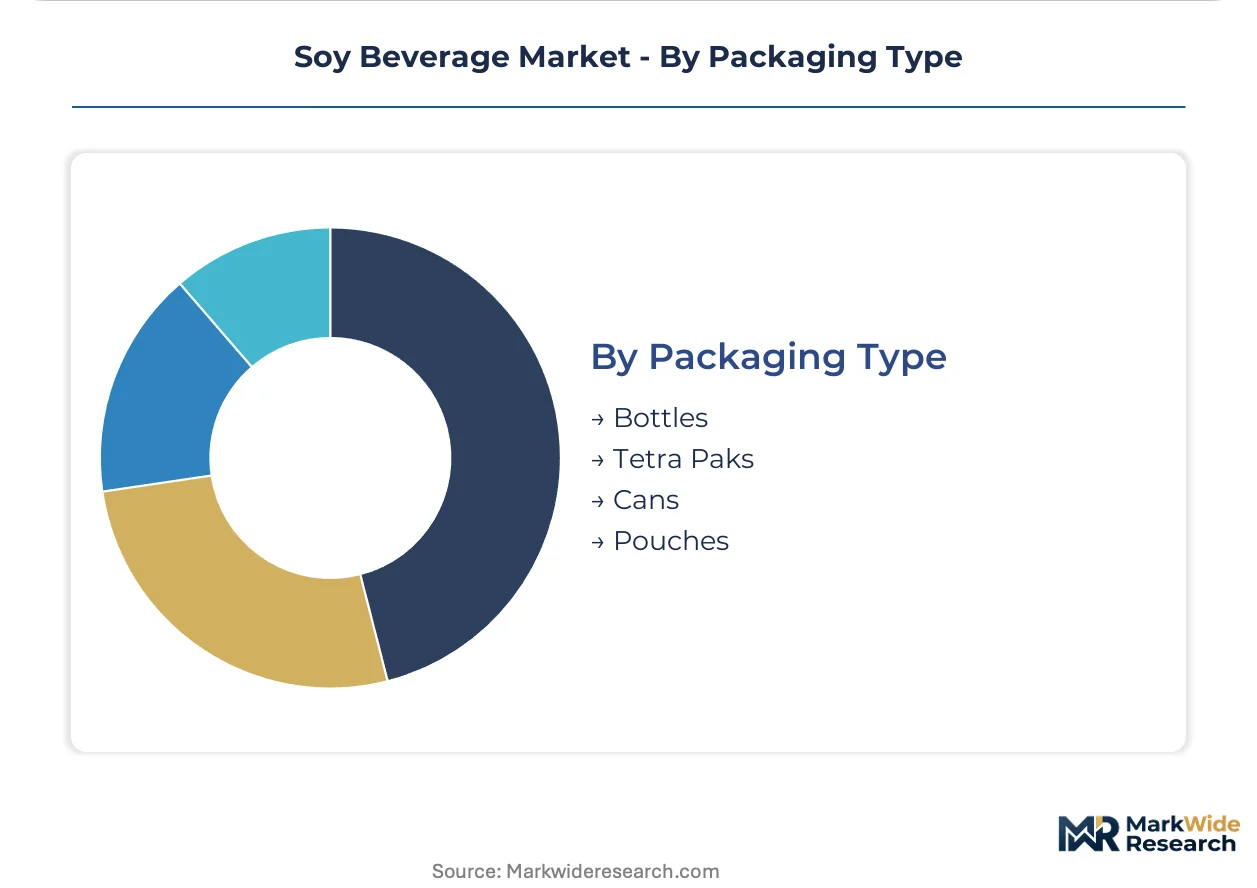
- Bottles:PET and HDPE formats anchor chilled segments in supermarket dairy-alternative aisles, enabling transparent product visibility and resealability. Higher viscosity fortified formulations require line retrofitting for reliable filling.
- Tetra Paks:Aseptic carton systems dominate ambient distribution with Swedish and Finnish forest-product corridors concentrating substrate supply. REACH chemical safety protocols are forcing liner migration from epoxy to polyester alternatives.
- Cans:Aluminum formats serve single-serve convenience and foodservice fountain applications with superior light and oxygen barrier properties. Recyclability messaging aligns with EU circular economy objectives.
- Pouches:Flexible formats reduce shipping cube and material weight for e-commerce fulfillment, though aseptic filling capabilities are less established than carton systems. German and Dutch subscription platforms are piloting these formats.
Supply vulnerability sits with Tetra Paks. Format innovation is concentrated in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers in Germany and the United States are expanding soy beverage consumption as protein-content benchmarks reshape retail positioning. Regulatory divergence between FDA, EFSA, and SAMR standards is forcing simultaneous reformulation cycles across export-oriented suppliers.
United States
FDA nutrition labeling rules and USDA organic certification govern interstate commerce for soy beverage claims. The agency's updated plant-based guidelines are rebalancing formulation requirements for dairy-alternative labeling. California's Bay Area processing clusters anchor innovation in enzymatic debittering protocols.
Germany
EFSA protein-content standards shape product development for export-oriented suppliers targeting mainstream retail. The EU Green Deal's sustainability disclosure mandates are creating first-mover advantage for verified deforestation-free supply chains. Hamburg and Berlin distribution hubs concentrate organic-flavored SKU allocation for pan-European distribution.
China
SAMR national food safety standards and GB labeling codes impose compliance layers for domestic retail channel access. The country's dual carbon goals are accelerating sustainability audits for soybean procurement corridors. Yangtze River Delta processing centers dominate aseptic packaging integration for ambient-stable formats.
Japan
METI industrial policy supports functional food positioning for soy protein isolates in aging-population nutrition strategies. JIS standards govern packaging material specifications for extended shelf-life products. Kanto region beverage conglomerates anchor vertical control over domestic soybean crushing capacity.
India
FSSAI regulatory clarity on plant-based protein fortification is opening formulation pathways previously blocked by ambiguous standards. The country's PLI scheme for food processing is attracting aseptic line investments from multinational suppliers. Maharashtra and Gujarat procurement networks are piloting organic soybean contract farming for export-grade output.
Soy Beverage Market Vendor Landscape
European producers anchor the premium organic tier; Asian specialists hold positions in vertically integrated commodity supply. The vendor base splits between consolidated multinational parents with dairy-alternative portfolios and mid-scale regional processors with certified sourcing networks. Three archetypes dominate: Danone-backed brand platforms with Benelux infrastructure, Asian soybean-origin processors with captive crushing assets, and North American private-label specialists with aseptic packaging capabilities. Competitive moves concentrate on M&A for organic certification bandwidth and strategic partnerships for deforestation-free supply verification.
Within the Asian-origin processor tier, Vitasoy International Holdings Ltd. exemplifies vertical control over procurement corridors, while Kikkoman Corporation occupies a position bridging fermented soy expertise with beverage applications. Among North American private-label fabricators, SunOpta Inc. represents specialized aseptic capabilities for ambient-stable formats.
| Leading Market Players |
|---|
| Vitasoy International Holdings Ltd. |
| Alpro (Danone S.A.) |
| Earth's Own Food Company Inc. |
| SunOpta Inc. |
| Pacific Foods of Oregon LLC |
| Kikkoman Corporation |
| Eden Foods Inc. |
| Morinaga Milk Industry Co., Ltd. |
| Pulmuone Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive sourcing of non-GMO soybean corridors anchors both supply security and premium-tier pricing power for organic-certified processors, while fragmented aseptic packaging substrate production concentrates cost leverage among Swedish and Finnish forest-product suppliers. This integration choice separates margin-stable players with verified deforestation-free networks from price-pressured mid-tier competitors exposed to Brazilian harvest volatility.
Pricing Analysis
Volume scaling concentrates in standard unflavored formulations, while margin capture clusters in organic and enzymatically-enhanced premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic SKUs with dual USDA-EU audits from private-label ambient formats facing oat and pea protein substitution. Cost compression in the non-dairy tier is intensifying because Brazilian non-GMO soybean premiums fluctuate with harvest cycles. Lactose-intolerant consumers show highest price sensitivity, while vegan-aligned buyers accept sourcing transparency premiums.
Supply Chain Analysis
Reverse-logistics flows for aseptic carton substrates remain underdeveloped, constraining circular packaging recovery rates in European ambient distribution. Soybean procurement draws from Brazil, the United States, and Benelux organic contract farming networks. Processing inputs rest on lipoxygenase enzymes for debittering, calcium and vitamin D fortification premixes, and polyester-based can linings compliant with REACH protocols. Single-source vulnerability clusters in Swedish and Finnish forest-product corridors for aseptic substrate supply. Distribution runs through German and Dutch e-commerce aggregators disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soy beverage market operates as a cost-of-compliance story where EU Green Deal sustainability disclosure mandates and EFSA protein-content thresholds erect barrier-to-entry moats favoring processors with pre-built certification bandwidth and verified supply chain documentation.
For Market Incumbents: Acquire organic certification audit capacity to compress the 14-18 month USDA-EU dual-certification timeline threatening product launch velocity. Secure deforestation-free supply verification partnerships ahead of EU Green Deal enforcement windows. Oat and pea protein substitution in German and UK retail represents the immediate share erosion threat; backward integration into Benelux organic soybean procurement corridors provides margin defense. For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's FSSAI-clarified plant-based protein fortification segment offers white-space entry with reduced incumbent saturation. Target direct-to-subscription health platform channels in France and Italy where subscription lock-in rates exceed conventional retail loyalty metrics. Pilot high-pressure processing capabilities for chilled distribution radius extension beyond traditional 200-kilometer constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational dairy-alternative portfolios seeking organic certification bandwidth and Asian procurement corridor access. Long-term viability hinges on processors with demonstrated compliance navigation across FDA, EFSA, and SAMR protein-content divergence. Watch enzymology talent scarcity as the inflection signal: food biochemists capable of protease optimization for texture modification command premium compensation that constrains R&D scaling at mid-tier targets.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Audit Investment | Compresses 14-18 month USDA-EU organic synchronization timelines blocking product launches. |
| Deforestation-Free Supply Verification | Creates first-mover positioning under EU Green Deal sustainability disclosure mandates. |
| High-Pressure Processing Adoption | Extends chilled distribution radii beyond 200-kilometer constraints in France and Italy. |
| Direct-to-Subscription Channel Launch | Bypasses supermarket dairy-alternative aisle congestion through German and Dutch health platforms. |
| Enzymology Talent Acquisition | Secures food biochemists capable of lipoxygenase inhibition for beany off-flavor elimination. |
Methodological Framework
Trade data from customs authorities, SEC filings from publicly traded processors, and EFSA health claim assessment databases formed the secondary backbone, cross-referenced against primary interviews with plant-based beverage R&D directors, organic certification auditors, and German supermarket category buyers. Bottom-up volume modeling triangulated against top-down value estimates derived from Nielsen retail audit data and Benelux processing hub capacity disclosures.
Historical trendline analysis of protein-content standardization trajectories across FDA, EFSA, and SAMR jurisdictions informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, distribution channel format, end-user motivation cluster, and packaging substrate regulatory compliance class. CAGRs were derived from slope analysis of normalized growth trajectories, incorporating enzymatic processing adoption curves and sustainability disclosure mandate implementation timelines as industry-specific forecast inputs.
Inputs from certification body disclosure records and aseptic packaging substrate production databases were available through the study window; gaps in real-time Brazilian non-GMO soybean premium pricing introduce uncertainty bands around input cost assumptions. Forecasts reflect documented assumptions regarding regulatory synchronization timelines and substitution elasticity between soy and alternative plant proteins. Material deviation in EFSA protein-content enforcement intensity or FSSAI fortification clarity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market