
 West Africa Plant Based Product Market | 2026-2036
West Africa Plant Based Product Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Plant Based Product Market Analytics
Buyer concentration across West African urban food retail is shifting from traditional open-air markets toward organized supermarket chains and quick-service restaurant networks. Nestle S.A. leverages its existing dairy distribution infrastructure to push plant-based creamers into Nigerian and Ghanaian retail shelves. Danone S.A. anchors its regional position through fermented almond and soy beverage production adapted to local taste profiles. Unilever PLC competes via spreadable plant-based fats targeting West African baking and cooking traditions.
West Africa plant based products encompass protein isolates, cold-pressed oils, dairy analogues, and shelf-stable snacks derived from indigenous crops such as cowpea, bambara nut, and shea, typically processed through dry fractionation or aqueous extraction to achieve functional food-grade specifications. Plant-based proteins and dairy alternatives command the dominant revenue share due to established consumer familiarity and lower price elasticity relative to novel snack formats. Distribution through supermarkets and online retail channels is expanding fastest, though convenience stores still occupy the deepest rural penetration and margin compression from fragmented wholesale layers.
NAFDAC in Nigeria and Ghana's Food and Drugs Authority enforce compositional standards and allergen disclosure rules that shape product formulation decisions for entrants without existing regulatory affairs capacity. The Economic Community of West African States (ECOWAS) convergence framework on food safety is forcing manufacturers to harmonize label claims across borders or face market exclusion. Stakeholders must monitor how upcoming regional tariff harmonization affects imported ingredient costs versus local sourcing economics.
Market Dynamics
NAFDAC's tightened labeling requirements for dairy alternatives are compressing formulation timelines and forcing manufacturers to rebuild compliance infrastructure from the ground up. This regulatory pressure intersects with rapid urban foodservice expansion in Lagos and Accra to create a bifurcated market structure.
Growth Catalysts
- ECOWAS Convergence Framework:The regional food safety harmonization mandate is creating cross-border product standardization that reduces duplicate certification costs for multi-country operators.
- Urban Foodservice Expansion:Quick-service restaurant networks in Nigerian and Ghanaian metropolitan corridors are adding dedicated plant-based menu sections to capture health-conscious professional consumers.
- Indigenous Crop Processing:Dry fractionation of cowpea and bambara nut is yielding functional protein isolates that match imported soy concentrate performance at lower input costs.
Market Restraints
- Shea Butter Price Volatility:Cold-pressed shea oil supply concentrates in Burkina Faso and Mali, exposing formulators to harvest-season price swings and export quota uncertainty.
- Import Dependency for Equipment:Aqueous extraction and spray-drying machinery originates primarily from European and Chinese suppliers, creating capex bottlenecks and maintenance skill gaps.
- NAFDAC Compliance Friction:The regulator's allergen disclosure rules require reformulation of legacy products, delaying commercialization timelines for entrants without established regulatory affairs teams.
Strategic Opportunities
- Benin and Togo Underpenetration:These coastal corridors lack organized supermarket density but show rising disposable income trajectories that favor first-mover plant-based positioning.
- Institutional Catering Contracts:University and hospital foodservice procurement in Nigeria's southwestern corridor is opening to shelf-stable dairy analogues as budget constraints tighten.
- Fermentation Technology Convergence:Combining traditional West African fermentation practices with controlled bioprocessing is creating novel umami profiles that differentiate regional products from imported alternatives.
Industry Challenges
- Food Technologist Scarcity:Formulation expertise in plant protein functionality and emulsion stability remains concentrated in South African and European talent pools, inflating recruitment costs for regional production facilities.
- Halal Certification Complexity:Multi-country operators must navigate separate accreditation pathways through Nigeria's NAFDAC and Ghana's Food and Drugs Authority, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Plant Based Product Market |
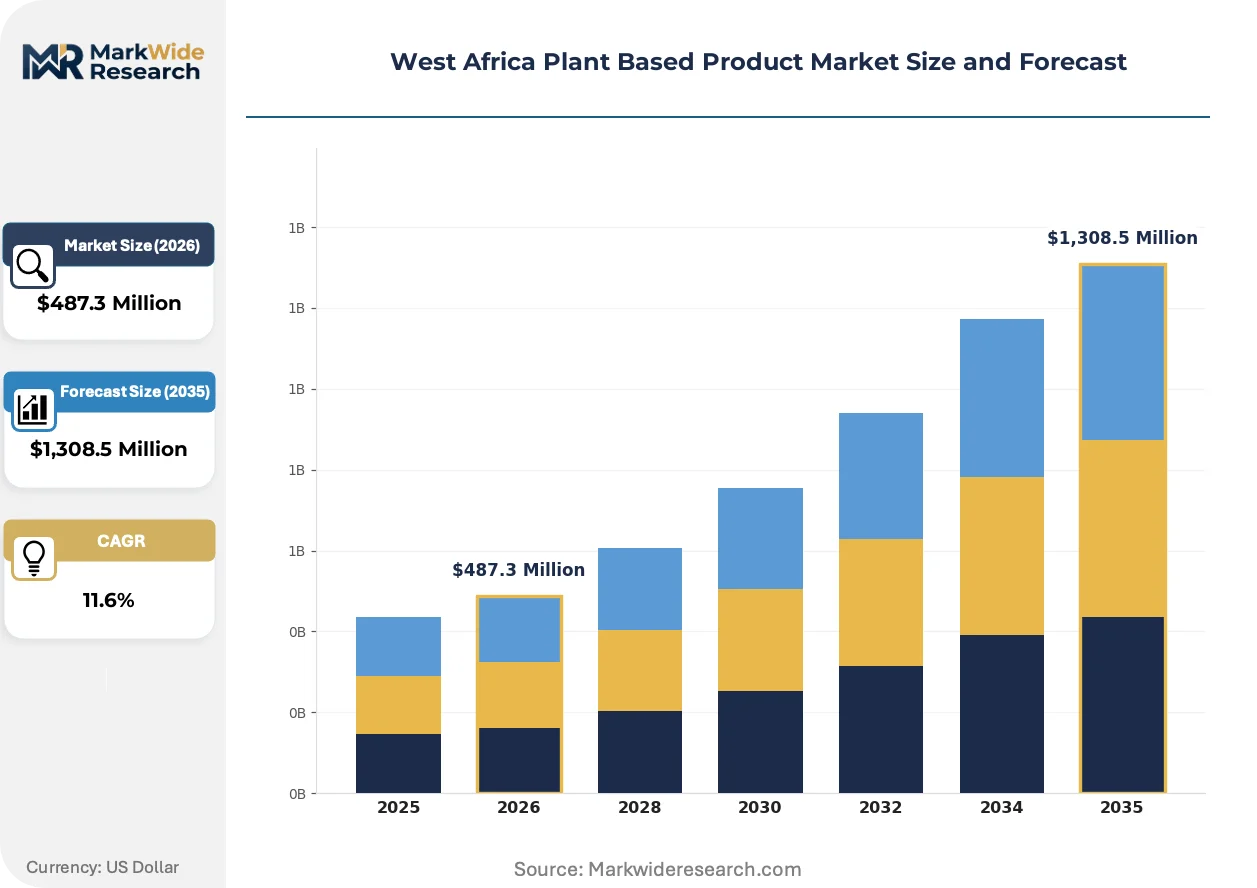
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Proteins, Oils, Dairy Alternatives, Snacks Application: Food Industry, Beverage Industry, Nutritional Supplements, Personal Care Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores End User: Vegetarians, Vegans, Health-Conscious Consumers, Eco-Conscious Consumers |
| Companies Covered | Nestle S.A., Danone S.A., Unilever PLC, Coca-Cola Company, Philafrica Foods, Cargill Incorporated, Archer Daniels Midland, Blue Diamond Growers, Cashewmeetly, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Plant Based Product Market Evolving Landscape
West African plant-based manufacturing is absorbing processing technologies from adjacent sectors while regulatory frameworks force faster product iteration cycles. Three distinct vectors are restructuring competitive positioning.
Extrusion technology adapted from animal feed processing is absorbing into plant-based meat analogue production. Nigerian contract manufacturers are retrofitting existing extruders with cooling dies and texturizing attachments. This equipment reuse is compressing capital requirements for mid-scale entrants and enabling faster production scale-up than greenfield facility construction.
NAFDAC's sequential tightening of label claim standards is forcing manufacturers to substantiate protein content and allergen warnings through third-party laboratory certification. This policy trajectory is elevating compliance costs for informal processors while creating barrier-to-entry advantages for organized players with captive testing relationships. The dairy alternatives segment bears the heaviest documentation burden as it competes directly with conventional dairy for shelf space.
Quick-service restaurant procurement in Lagos and Accra is consolidating toward centralized distribution agreements with approved suppliers. Independent operators are losing access to premium retail locations as chain networks enforce exclusive supply relationships. This channel compression is most visible in Nigeria's southwestern corridor, where supermarket penetration and foodservice density overlap most completely.
West Africa Plant Based Product Market Segmentation
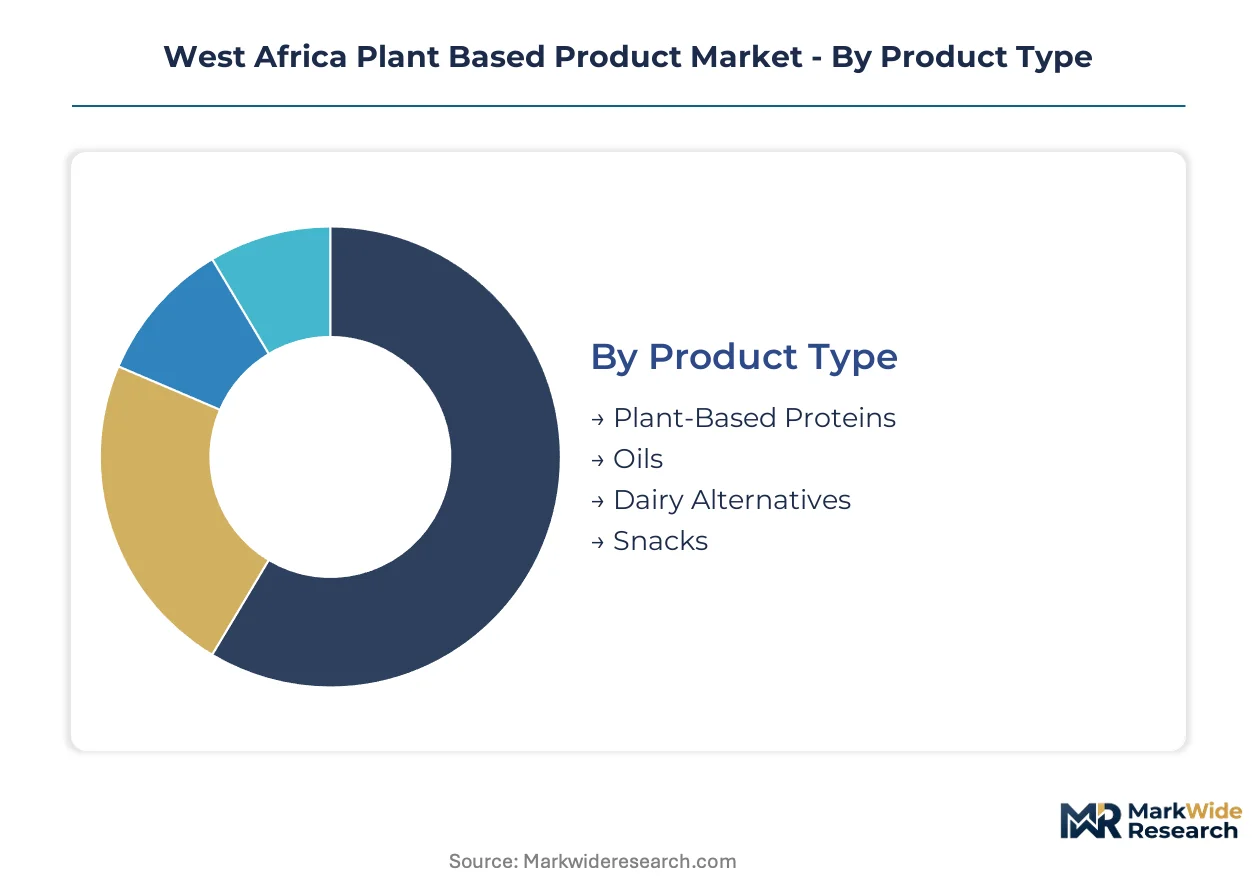
Segmentation in West Africa's plant-based market reveals how capital deployment, regulatory exposure, and channel economics fragment opportunity across distinct product and customer configurations. Understanding these fault lines enables manufacturers to match production scale with demand concentration.
Product Type:
Capital intensity varies sharply across processing technologies, with spray-drying and extrusion equipment representing the steepest upfront barriers.
- Plant-Based Proteins:Dry fractionation of cowpea and bambara nut yields functional isolates with emulsion stability comparable to imported soy concentrates. Nigerian foodservice operators in Lagos are absorbing volumes for meat analogue applications as quick-service restaurant procurement consolidates.
- Dairy Alternatives:Fermented almond and soy beverages require controlled bioprocessing infrastructure and carry the heaviest NAFDAC documentation burden for allergen disclosure and protein content verification. Ghanaian retail chains are expanding shelf space for these products in Accra's supermarket corridors.
- Oils:Cold-pressed shea and coconut oils demand lower capex than protein isolation but face harvest-season price volatility concentrated in Burkina Faso and Mali supply zones.
- Snacks:Shelf-stable extruded products leverage existing equipment from adjacent sectors, compressing entry costs for mid-scale Nigerian contract manufacturers.
Most installed capacity flows through Dairy Alternatives. Expansion is steepest in Plant-Based Proteins.
Application:
Margin profiles diverge based on formulation complexity and buyer procurement sophistication, with institutional channels offering volume stability at lower per-unit returns.
- Food Industry:Quick-service restaurant networks in Nigeria's southwestern corridor are adding dedicated plant-based menu sections, creating concentrated demand for texturized proteins and spreadable fats adapted to local cooking traditions.
- Beverage Industry:Fermented beverages with umami profiles developed through traditional West African fermentation practices are differentiating regional products from imported alternatives in Ghanaian and Nigerian urban markets.
- Nutritional Supplements:Protein isolates targeting health-conscious professional consumers concentrate in Lagos and Accra pharmacy retail channels.
- Personal Care:Shea butter derivatives for cosmetics applications compete with food-grade demand during harvest compression periods.
Volume concentrates in Food Industry. Value per kilogram peaks in Nutritional Supplements.
Distribution Channel:
Channel selection determines margin retention and regulatory touchpoint density, with organized retail imposing stricter compliance requirements than informal trade.
- Supermarkets:Nigerian and Ghanaian chains in Lagos and Accra are expanding dedicated plant-based sections, though shelf placement fees and exclusive supply agreements favor established manufacturers with captive distribution infrastructure.
- Online Retail:E-commerce penetration is climbing fastest among health-conscious professional consumers in metropolitan corridors, bypassing fragmented wholesale layers that compress rural margins.
- Convenience Stores:Deep rural penetration persists here, but limited cold chain infrastructure restricts dairy alternative assortment to shelf-stable formats.
- Health Food Stores:Premium positioning in Accra and Lagos targets eco-conscious consumers willing to absorb higher price points for certified organic or indigenous crop provenance.
Revenue concentration sits with Supermarkets. Customer acquisition costs are lowest in Convenience Stores.
End User:
User segmentation maps to price elasticity and information sensitivity, with ethical positioning commanding premiums only in specific urban clusters.
- Health-Conscious Consumers:Nigerian professionals in Lagos's southwestern corridor drive demand for protein-fortified products and allergen-labeled alternatives, responding to tightened NAFDAC disclosure requirements.
- Eco-Conscious Consumers:Ghanaian urbanites in Accra prioritize indigenous crop sourcing and reduced packaging, though this segment remains thinner than health-motivated buyers.
- Vegetarians:Religious and cultural vegetarianism in southern Nigeria creates baseline demand for dairy alternatives and protein isolates.
- Vegans:Strict veganism represents the smallest addressable pool, concentrated among expatriate communities and younger urban professionals.
Health-Conscious Consumers anchor volume. Eco-Conscious Consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria commands the dominant revenue share while Ghana offers faster regulatory harmonization progress. The southwestern Nigerian corridor anchors volume concentration. Ghana's Food and Drugs Authority provides clearer compliance pathways for dairy alternative entrants.
Nigeria
Quick-service restaurant procurement in Lagos and Ibadan drives concentrated demand for texturized proteins and spreadable fats. NAFDAC's tightened allergen disclosure rules compress formulation timelines for dairy alternative manufacturers. The southwestern corridor's overlapping supermarket penetration and health-conscious professional clusters create the densest addressable market in West Africa.
Ghana
Accra's urban foodservice operators are expanding dedicated plant-based menu sections to capture health-motivated consumers. The Food and Drugs Authority enforces compositional standards that shape product formulation decisions for entrants without established regulatory affairs capacity. Supermarket chains in metropolitan Accra are expanding shelf space for fermented almond and soy beverages.
Côte d'Ivoire
Abidjan's institutional catering procurement is opening to shelf-stable dairy analogues as budget constraints tighten across university and hospital foodservice. The country's national food safety regulator maintains alignment with ECOWAS convergence frameworks on cross-border product standardization. Cocoa-processing infrastructure in the southern corridor offers potential equipment reuse pathways for extrusion-based snack manufacturing.
Senegal
Dakar's coastal position enables import-efficient distribution of European processing equipment for aqueous extraction and spray-drying operations. The national pharmaceutical and food regulator enforces labeling standards that mirror ECOWAS harmonization mandates. The Cap-Vert peninsula's concentrated urban population supports health food store expansion targeting eco-conscious consumers.
Benin and Togo
These coastal corridors lack organized supermarket density but show rising disposable income trajectories favoring first-mover plant-based positioning. National food safety authorities in both countries are adopting ECOWAS-aligned standards that reduce duplicate certification costs for multi-country operators. Cotonou and Lomé's port infrastructure positions them as potential import hubs for regional ingredient supply.
West Africa Plant Based Product Market Competitive Landscape
Nigerian producers anchor one tier; European and North American specialists hold premium positioning through existing dairy distribution infrastructure. The market structure fragments across three operational scales: multinational FMCG conglomerates with captive regulatory affairs teams, regional African food processors leveraging indigenous crop sourcing, and emerging contract manufacturers retrofitting extrusion equipment from adjacent sectors. Two dominant competitive moves are reshaping positioning: strategic partnerships between global ingredient suppliers and local processors to secure cowpea and bambara nut offtake agreements, and portfolio diversification into fermented beverage formats that bypass cold chain limitations.
Within the multinational FMCG tier, Nestle S.A., Danone S.A., and Unilever PLC exemplify divergent entry strategies. Nestle leverages existing dairy distribution infrastructure to push plant-based creamers into Nigerian and Ghanaian retail shelves. Danone anchors its regional position through controlled bioprocessing infrastructure adapted to local taste profiles. Unilever competes via spreadable plant-based fats targeting West African baking and cooking traditions. These three occupy positions that represent distinct archetypes: infrastructure reuse, localized production investment, and culinary tradition alignment.
| Leading Market Players |
|---|
| Nestle S.A. |
| Danone S.A. |
| Unilever PLC |
| Coca-Cola Company |
| Philafrica Foods |
| Cargill Incorporated |
| Archer Daniels Midland |
| Blue Diamond Growers |
| Cashewmeetly |
| Others |
Value Network & Pricing Analysis
ECOWAS convergence on food safety harmonization gates both qualified supply and premium-tier pricing access, as manufacturers must absorb certification costs to serve multi-country procurement or retreat to informal channels with compressed margins. Nigerian and Ghanaian buyers with centralized distribution agreements command price discounts unavailable to fragmented rural operators.
Pricing Analysis
Capacity additions in Nigeria's southwestern corridor are reshaping price floors for plant-based proteins as dry fractionation of cowpea and bambara nut scales. Contract-based long-term offtake dominates, with price differentiation driven by NAFDAC certification tier and volume scale. Cost compression in standard-tier dairy alternatives is intensifying because quick-service restaurant procurement consolidation squeezes per-unit margins. Institutional buyers in Lagos and Accra show lowest price sensitivity; convenience store channels in rural Benin and Togo absorb the highest.
Supply Chain Analysis
Freight costs from Burkina Faso and Mali shea harvest zones to Nigerian processing hubs fluctuate with seasonal road conditions and fuel price movements. Raw material supply concentrates in Nigeria, Ghana, and Côte d'Ivoire, drawing from cowpea, bambara nut, and shea nut inputs. Single-source vulnerability in cold-pressed shea oil exposes formulators to harvest-season price swings. Distribution runs through supermarket chains in Lagos and Accra, with emerging e-commerce penetration bypassing fragmented wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NAFDAC compliance costs in Nigeria exceed Ghana's Food and Drugs Authority pathways, creating margin capture opportunities for multi-country operators with regulatory affairs scale.
For Market Incumbents: Hedge against shea butter price volatility through backward integration into Malian and Burkinabe sourcing cooperatives. Defensive consolidation around captive testing relationships with third-party laboratories accelerates NAFDAC documentation timelines as allergen disclosure rules tighten. Channel control through exclusive supply agreements with quick-service restaurant networks in Lagos and Accra locks out mid-scale challengers. For New Entrants and Emerging Players: Quick-service restaurant procurement managers represent the most accessible entry point for texturized protein volumes as chain networks expand plant-based menu sections. White-space concentration sits in Benin and Togo's underpenetrated supermarket corridors, where rising disposable income trajectories favor first-mover positioning. Go-to-market execution through institutional catering contracts at Nigerian universities and hospitals bypasses retail shelf placement fees. For Investors and Strategic Acquirers: Roll-up economics work for regional African food processors with indigenous crop sourcing relationships because ECOWAS harmonization reduces duplicate certification costs across borders. Long-term viability centers on 5-10 year positioning around fermentation technology convergence that differentiates regional products from imported alternatives. Acquisition target archetype: mid-scale Nigerian contract manufacturers with retrofitted extrusion equipment. The signal to watch is NAFDAC's sequential tightening of label claim standards elevating compliance costs for informal processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shea Sourcing | Captive supply from Burkina Faso and Mali insulates formulators against harvest-season price volatility. |
| Fermentation Technology Investment | Controlled bioprocessing infrastructure in Ghana creates umami profiles that differentiate regional beverages. |
| Regulatory Affairs Capacity Buildout | NAFDAC documentation expertise accelerates commercialization timelines for dairy alternative entrants. |
| Quick-Service Restaurant Supply Agreements | Exclusive relationships with Lagos and Accra chains lock in volume for texturized protein outputs. |
| E-Commerce Channel Expansion | Direct distribution to health-conscious professionals bypasses fragmented wholesale margin compression. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Nigerian foodservice procurement directors, Ghanaian supermarket category buyers, NAFDAC regulatory affairs leads, and West African contract manufacturing plant managers with secondary validation. Customs records, ECOWAS trade statistics, NAFDAC registration filings, and retail audit data from Lagos and Accra supermarket corridors anchored supply-side estimates. Bottom-up capacity assessments and top-down demand triangulation cross-verified segment outputs.
Comparable-period anchoring linked historical cowpea and bambara nut processing volumes to forward projections across the analysis window. The analytical framework modeled product type, application, distribution channel, and end-user dimensions alongside indigenous crop sourcing intensity as an industry-specific variable. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated NAFDAC regulatory trajectory assumptions and quick-service restaurant network expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to shea butter price volatility and ECOWAS tariff harmonization implementation. Model outputs reflect documented assumptions about urban foodservice penetration rates and regulatory enforcement consistency. A model refresh is warranted upon material change in NAFDAC label claim standards or ECOWAS convergence framework adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Rice Protein Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Alternatives Market