
 Chickpea-Based Products Market | 2026-2036
Chickpea-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea-Based Products Market Insights
EU Green Deal protein diversification targets are consolidating compliance costs for new entrants across the chickpea value chain. Banza leverages its vertically integrated supply chain to control ingredient quality from farm to package. Barilla competes through its established pasta manufacturing infrastructure and retail distribution depth. Saffron Road differentiates via its ethnic cuisine positioning and halal certification standards.
Chickpea-based products encompass food and beverage items formulated with chickpea flour, whole chickpeas, or chickpea protein isolate as primary ingredients, typically containing 20-30% protein content and functional binding properties derived from the legume's starch and fiber matrix. These products serve industrial food formulation and direct consumer consumption channels where allergen-friendly and gluten-free credentials command premium positioning. Flour dominates current volume as the foundational input for bakery and snack applications, while pasta represents the fastest-growing product type as consumers substitute traditional wheat formulations. The application split shows vegan cuisine capturing disproportionate margin pools due to certification premiums, whereas ready-to-eat meals sustain the broadest household penetration through convenience positioning.
FDA gluten-free labeling rules and USDA organic certification requirements shape product claims and substantiation protocols in the United States, while EFSA novel food assessments govern new chickpea protein ingredient introductions across European markets. India's FSSAI plant protein standards and China's SAMR food safety GB standards add compliance layers for exporters targeting Asia-Pacific demand centers. Stakeholders must monitor evolving allergen threshold definitions and carbon footprint disclosure mandates as these regulatory dimensions increasingly determine market access and shelf placement authority.
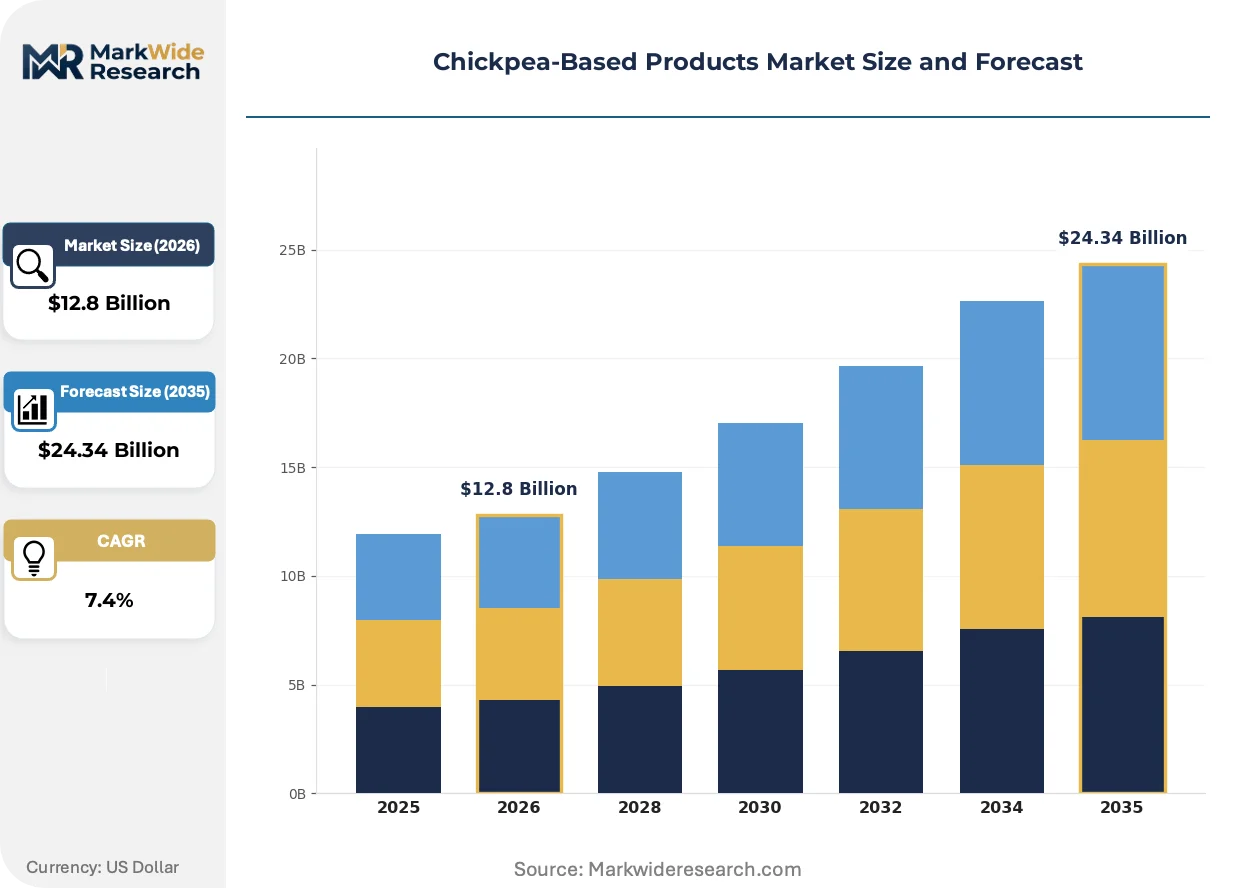
Market Dynamics
The EU Green Deal's protein diversification mandates are consolidating compliance costs across the chickpea value chain, forcing ingredient substitution timelines to compress while farm-to-package traceability becomes a non-negotiable procurement criterion.
Growth Catalysts
- EU Green Deal protein targets:Binding sustainable protein quotas accelerate chickpea flour adoption in bakery and snack formulations as manufacturers race to meet 2030 benchmarks.
- Clean-label mandates:Consumer packaged goods companies in Germany and France now require allergen-friendly credentials, driving chickpea-based alternatives into mainstream retail shelf resets.
- Pasta substitution wave:Wheat-to-legume formulation pivots in Italian and Spanish manufacturing plants create sustained demand for chickpea semolina with functional binding properties.
Market Restraints
- Input cost volatility:Chickpea harvest yields in India and Australia fluctuate with monsoon patterns, squeezing margin predictability for flour processors.
- Supply concentration risk:Premium-grade kabuli chickpea production clusters in Turkey and Ethiopia, exposing buyers to geopolitical disruption and quality inconsistency.
- EFSA novel food assessments:Extended safety evaluation timelines for new chickpea protein isolates delay European product launches by 18-24 months versus conventional ingredients.
Strategic Opportunities
- Underpenetrated Japanese market:METI's promotion of alternative proteins creates entry pathways for halal-certified chickpea snacks targeting inbound tourism and export channels.
- Precision fermentation convergence:Blending chickpea protein isolates with microbial biomass enables texture-matched dairy alternatives for vegan cheese applications.
- Direct-to-institutional channels:Hospital and school nutrition contracts in France and Italy now specify legume-forward menus, bypassing retail gatekeepers.
Industry Challenges
- Specialized milling expertise gap:Chickpea flour requires modified particle size distribution for extruded pasta, yet European equipment operators lack training on legume-specific processing parameters.
- Dual certification complexity:Simultaneous USDA organic and EU organic compliance demands parallel documentation systems that strain mid-tier processors.
- Legacy ERP integration friction:Farm-level traceability data from Turkish cooperatives fails to sync with major food manufacturers' blockchain verification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea-Based Products Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.34 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Snack, Hummus, Pasta Application: Food Industry, Bakery, Vegan Cuisine, Ready-to-Eat Meals End User: Households, Foodservice, Retail, Food Manufacturers Distribution Channel: Online, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | Banza, Chickapea Pasta, Explore Cuisine, Barilla, Saffron Road, THREE FARMERS, Olo Organic, Pasta Lensi, Marlow Foods Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea-Based Products Market Trends and Innovations
Active reshaping of the chickpea-based products market centers on three vectors: protein extraction technology maturation, regulatory disclosure mandates tightening, and procurement criteria hardening around carbon accountability.
High-pressure processing technology is expanding into chickpea protein isolate manufacturing, enabling functional ingredient production without chemical denaturation. European dairy alternative formulators now specify HPP-treated isolates for yogurt and cheese analogues. This capability compression is forcing commodity flour processors to upgrade equipment or exit premium ingredient supply contracts.
CSRD carbon footprint disclosure rules now require Scope 3 agricultural emissions reporting from EU-based food manufacturers. Chickpea suppliers must provide farm-level methane and nitrous oxide data to retain preferred vendor status. Pasta and bakery segments face the steepest compliance ramps, with German retailers already delisting products lacking verified lifecycle assessments.
Buyers now mandate regenerative agriculture verification as a procurement gate, displacing conventional price-per-ton negotiations. French and Dutch supermarket chains award multi-year supply contracts exclusively to chickpea growers with Soil Association or equivalent certification. This behavioral pivot concentrates sourcing power with vertically integrated farm-to-flour operators in Spain and Portugal.
Chickpea-Based Products Market Segmentation
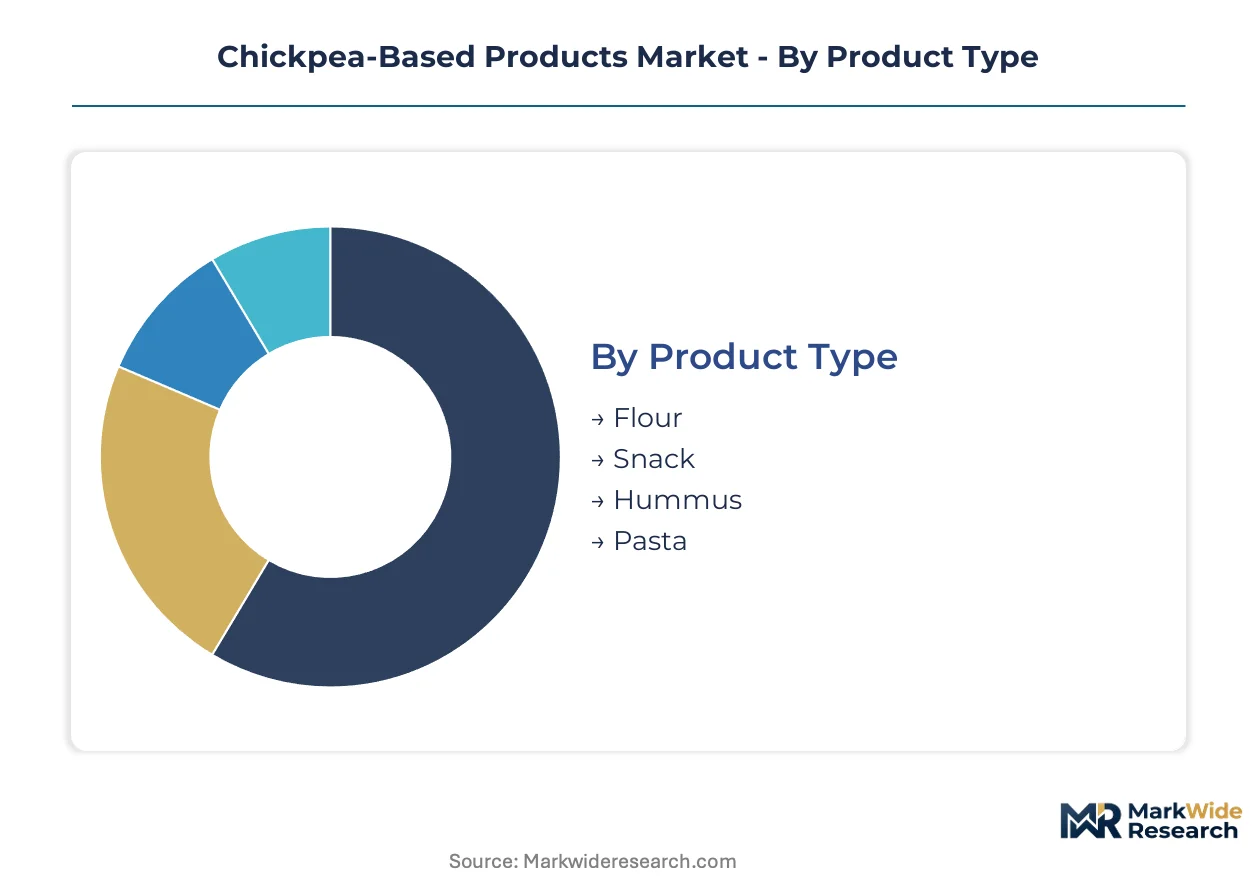
Chickpea-based product segmentation reveals how supply chain configuration dictates commercial outcomes across formulation types and channel access. Understanding these divides enables targeted investment in capacity and certification.
Product Type:
Supply concentration in milling infrastructure shapes competitive positioning across formulation categories, with particle size distribution capabilities determining margin capture.
- Flour:Finely milled chickpea flour with 20-30% protein content and functional starch-fiber binding properties serves as the foundational input for bakery extrusion and snack coating applications. German and Italian food manufacturers now specify regenerative-sourced flour to meet retailer sustainability mandates, compressing procurement timelines for conventional suppliers.
- Pasta:Extruded chickpea semolina formulations deliver al dente texture profiles that match wheat-based benchmarks while maintaining gluten-free credentials. Italian manufacturing plants in Emilia-Romagna and Puglia are retooling production lines to absorb this demand surge, though modified extrusion parameters require specialized operator training.
- Snack:Roasted and puffed chickpea formats target convenience positioning with clean-label allergen profiles.
- Hummus:Refrigerated and shelf-stable spreads leverage tahini-chickpea emulsion stability for Mediterranean cuisine applications.
Flour absorbs the bulk of installed capacity; pasta is expanding most quickly.
Application:
Cost tier differentiation separates premium-certified formulations from commodity substitutes, with compliance burden determining viable market entry.
- Vegan Cuisine:Plant-based entrees and dairy alternatives formulated with chickpea protein isolates command certification premiums through V-Label and organic dual credentials. French and Dutch retail buyers now require third-party carbon verification for shelf placement, elevating procurement standards beyond conventional ingredient sourcing.
- Ready-to-Eat Meals:Pre-packaged legume bowls and grain-chickpea combinations sustain broad household penetration through convenience positioning and extended shelf-life packaging. Hospital and school nutrition contracts in France specify legume-forward menus, creating institutional demand bypassing retail gatekeepers.
- Food Industry:Industrial ingredient supply for processed food formulation emphasizes functional binding and emulsification properties.
- Bakery:Gluten-free bread and pastry applications utilize chickpea flour for structure and moisture retention.
Ready-to-Eat Meals absorb the bulk of installed capacity; Vegan Cuisine is climbing the fastest.
End User:
Volume concentration in retail channels is displacing foodservice procurement patterns as shelf resets prioritize allergen-friendly alternatives.
- Retail:Branded packaged goods placement in German and French supermarket chains drives formulation standardization and packaging format consolidation. CSRD disclosure requirements now force private-label suppliers to provide farm-level emissions data, reshaping vendor qualification protocols.
- Food Manufacturers:Industrial buyers of chickpea flour and protein isolates specify functional performance metrics for extrusion and baking applications. Barilla and Banza compete through captive supply relationships and vertical infrastructure control.
- Households:Direct consumer purchases emphasize convenience and health-positioned packaging.
- Foodservice:Restaurant and institutional procurement favors bulk formats with consistent quality specifications.
Retail absorbs the bulk of installed capacity; Food Manufacturers is gaining share fastest.
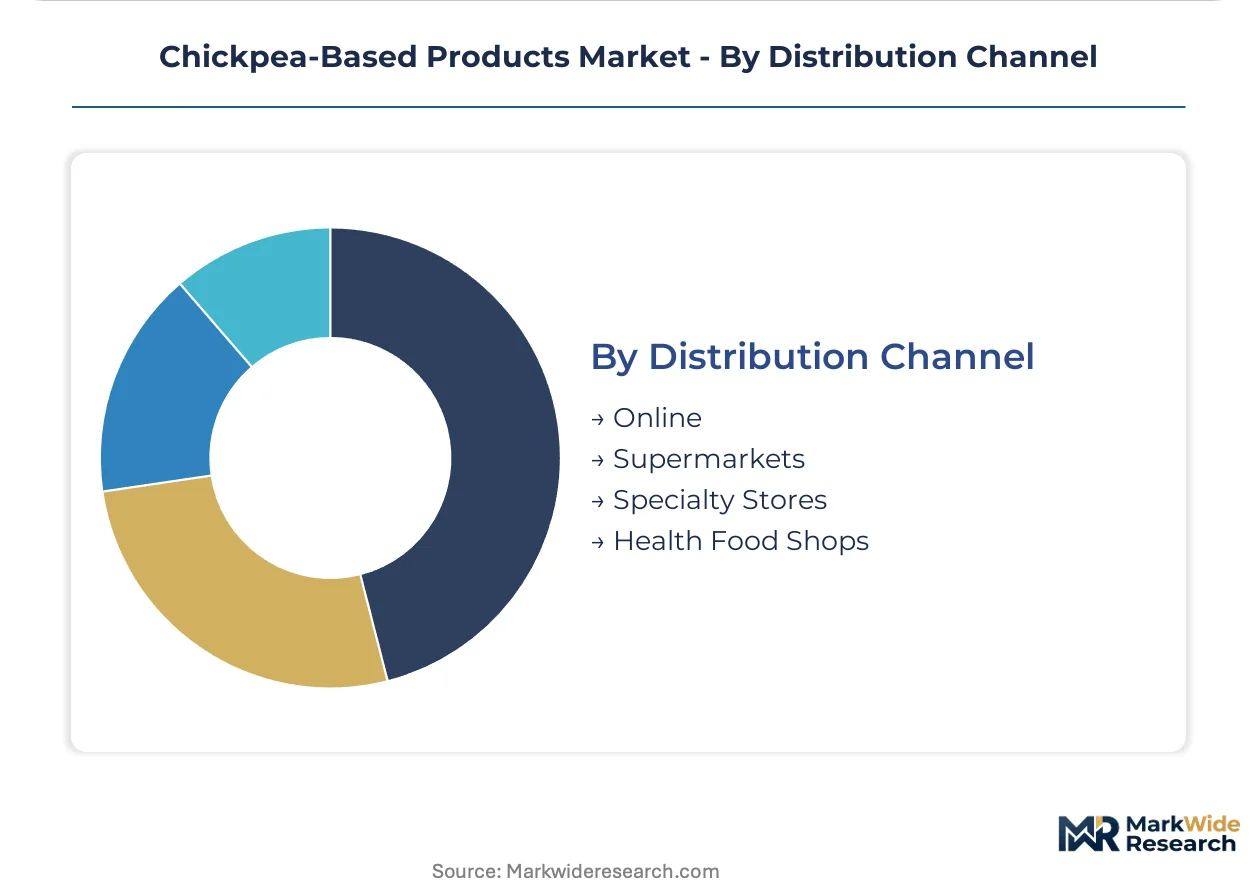
Distribution Channel:
Margin stratification across channel types reflects certification burden and customer acquisition cost differentials.
- Supermarkets:Mainstream retail shelf placement in Germany, France, and Italy requires dual organic certification and carbon footprint disclosure compliance. Rewe, Carrefour, and Coop Italia now delist products lacking verified lifecycle assessments, concentrating supplier power with integrated farm-to-shelf operators.
- Specialty Stores:Health-focused independent retailers emphasize niche positioning through ethnic cuisine and halal certification differentiation. Saffron Road leverages this channel for premium positioning outside conventional grocery competitive sets.
- Online:Direct-to-consumer and marketplace platforms enable subscription models and bulk purchasing.
- Health Food Shops:Natural products retailers prioritize regenerative agriculture and local sourcing credentials.
Supermarkets absorb the bulk of installed capacity; Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Almería agri-tech corridor concentrates chickpea processing infrastructure under EU Green Deal tax incentives, drawing ingredient suppliers toward Andalusian milling clusters.
Germany
Rewe and Edeka supermarket chains mandate regenerative-sourced chickpea flour for private-label placement, compressing supplier qualification timelines. The EU Green Deal's protein diversification targets bind manufacturers to 2030 benchmarks. Stuttgart-based milling cooperatives now retrofit facilities for organic certification to retain preferred vendor status.
United States
FDA gluten-free labeling rules and USDA organic certification requirements shape product claims substantiation for chickpea pasta and snack entrants. Clean-label mandates from Target and Whole Foods Market accelerate shelf resets for allergen-friendly alternatives. California's Central Valley hosts expanding chickpea acreage under contract for vertically integrated food manufacturers.
Italy
Barilla and regional pasta manufacturers drive wheat-to-legume formulation pivots in Emilia-Romagna production facilities. EFSA novel food assessments govern new chickpea protein ingredient introductions, delaying some launches by 18-24 months. Puglia's extrusion specialists retool lines for chickpea semolina as export demand for gluten-free credentials intensifies.
India
FSSAI plant protein standards and export-oriented processing incentives concentrate value-added chickpea product manufacturing in Gujarat and Maharashtra. Monsoon-dependent harvest yields in Madhya Pradesh create input cost volatility for flour processors. Mumbai-based traders now integrate farm-level traceability systems to meet European buyer procurement criteria.
Japan
METI's promotion of alternative proteins creates entry pathways for halal-certified chickpea snacks targeting inbound tourism channels. Specialty retailers in Tokyo and Osaka expand shelf space for Mediterranean-positioned hummus and roasted formats. Kobe's food technology incubators pilot precision fermentation blends with chickpea protein isolates for dairy alternative applications.
Chickpea-Based Products Market Competitive Landscape
North American producers anchor the venture-backed innovation tier; European specialists hold established manufacturing infrastructure and retail distribution depth. The vendor base stratifies across three archetypes: vertically integrated farm-to-package operators, legacy pasta manufacturers with captive ingredient supply, and ethnic cuisine specialists leveraging certification differentiation. Capacity expansion and regenerative agriculture verification represent the dominant competitive moves as procurement criteria harden.
Within the vertically integrated tier, Banza exemplifies supply chain control from farm sourcing through retail placement. Barilla occupies a position among legacy European manufacturers with established extrusion infrastructure and supermarket channel authority. Saffron Road sits within the specialty positioning vector, leveraging halal certification and ethnic cuisine differentiation to access premium shelf placement outside conventional grocery competitive sets.
| Leading Market Players |
|---|
| Banza |
| Chickapea Pasta |
| Explore Cuisine |
| Barilla |
| Saffron Road |
| THREE FARMERS |
| Olo Organic |
| Pasta Lensi |
| Marlow Foods Ltd |
| Others |
Pricing and Supply Chain Analysis
Family-owned milling cooperatives in Turkey and Ethiopia anchor premium kabuli chickpea supply, translating concentrated ownership into asymmetric pricing power that squeezes mid-tier flour processors during monsoon-driven harvest shortfalls in India and Australia.
Pricing Analysis
Short lead-time premiums now separate regenerative-certified flour from spot-market inventory as German retailers compress procurement windows to meet EU Green Deal disclosure deadlines. Three-tier pricing structure across regenerative-certified, organic-standard, and conventional grades reflects certification burden and carbon verification depth. Pricing pressure stems from CSRD-mandated Scope 3 reporting costs that processors cannot pass through to institutional buyers. Food manufacturers exhibit lowest price sensitivity due to captive supply relationships, while independent specialty retailers face margin compression from dual-certification documentation requirements.
Supply Chain Analysis
Regional distribution centers in Almería, Rotterdam, and Hamburg orchestrate hub-and-spoke patterns that consolidate flour and semolina flows toward extrusion facilities in Emilia-Romagna and Puglia. Geographic supply concentration centers on Turkey, Ethiopia, and India for raw chickpea sourcing, with Australian production providing counter-seasonal buffer stocks. Raw material dependencies include monsoon-dependent harvest yields, specialized milling equipment for particle size distribution, and regenerative agriculture verification systems. Single-source vulnerability runs through Turkish kabuli exports exposed to geopolitical disruption. Distribution runs through vertically integrated farm-to-package operators that bypass commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chickpea-based products market reads as a cost-of-compliance story where EU Green Deal protein diversification targets erect regulatory moats that favor incumbent players with pre-existing regenerative certification infrastructure.
For Market Incumbents: Deploy regenerative agriculture verification as a procurement gate to exclude non-compliant entrants from Rewe and Carrefour shelf resets. Deepen backward integration into Spanish and Portuguese farm cooperatives to secure Soil Association-certified supply before competitors consolidate preferred vendor status. This defensive posture neutralizes emerging precision-fermentation dairy alternatives that blend chickpea isolates with microbial biomass.
For New Entrants and Emerging Players: Begin with halal-certified snack formats targeting Japan's METI alternative protein promotion and inbound tourism channels, where certification differentiation commands premium placement outside conventional grocery competitive sets. White-space concentration sits in direct-to-institutional contracts for French hospital and school nutrition menus that specify legume-forward formulations. A precision-fermentation partnership with Kobe food technology incubators provides credible go-to-market positioning.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated farm-to-flour operators in Spain and Portugal with existing Soil Association certification and blockchain-enabled traceability systems. Long-term viability hinges on carbon-accounting infrastructure that survives tightening CSRD disclosure phases. Watch EFSA novel food assessment timelines as the signal for European protein isolate market entry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Soil Association verification unlocks multi-year supply contracts with French and Dutch supermarket chains. |
| Backward Integration into Farm Cooperatives | Captive sourcing from Spanish Almería clusters secures preferred vendor status under EU Green Deal incentives. |
| Precision Fermentation Partnership | Blending chickpea isolates with microbial biomass enables texture-matched dairy alternatives for vegan cheese. |
| Direct-to-Institutional Channel Development | Hospital and school nutrition contracts in France bypass retail gatekeepers and shelf-reset volatility. |
| Blockchain Traceability Implementation | Farm-level emissions data syncs with manufacturer verification platforms to meet CSRD Scope 3 mandates. |
Research Methodology
Multi-period observation of EU Green Deal protein target compliance timelines, regenerative certification adoption curves, and chickpea acreage shifts anchored the trend analysis, supplemented by interviews with milling cooperative managers, extrusion equipment operators, supermarket category buyers, and food manufacturer procurement leads. Secondary validation drew from EFSA novel food assessment databases, Soil Association certification registries, customs trade data for chickpea flour and semolina flows, and SEC filings of publicly traded packaged goods companies. Bottom-up volume modeling triangulated against top-down protein substitution benchmarks across bakery, pasta, and snack applications.
Input-output matrices mapped chickpea harvest yields through milling capacity utilization to end-product pricing tiers across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user channel, and distribution format, with carbon verification depth added as a cross-cutting qualifier. CAGRs emerged from regression analysis against protein diversification policy trajectories and clean-label shelf-reset velocity. Industry-specific forecast inputs incorporated monsoon pattern variability for Indian production and EFSA assessment pipeline congestion for novel isolate approvals.
Underlying measurement precision varies by segment; regenerative-certified and organic-standard tiers carry tighter precision than conventional commodity grades due to certification audit trail density. Forecasts reflect documented assumptions around EU Green Deal enforcement timelines, EFSA staffing capacity for novel food reviews, and Turkish geopolitical stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Rice Protein Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
North America Tofu Market