
 Plant Chocolate Protein Powder Market | 2026-2036
Plant Chocolate Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Chocolate Protein Powder Market Insights
Fitness enthusiasts and busy professionals are collapsing the historical dominance of core bodybuilder buyers in plant chocolate protein powder consumption. Orgain leverages its organic supply chain and retail shelf presence to anchor the premium natural channel. Vega competes through sustainability credentials and diversified plant protein sourcing across Canadian and US markets. NOW Health Group sustains its position via manufacturing scale and value-oriented pricing across mass-market distribution.
Plant chocolate protein powder combines isolated or concentrated plant proteins—typically pea, rice, or hemp at concentrations ranging from 70% to 90% protein by weight—with cocoa-derived flavoring systems and functional sweeteners to create a shelf-stable nutritional supplement for muscle recovery, satiety, or micronutrient fortification. Pea protein dominates formulation volumes due to its neutral flavor profile and emulsification stability, while hemp protein occupies a smaller but defensible niche among consumers seeking omega fatty acid co-benefits. The sports nutrition application leads absolute dollar contribution, though meal replacement formats targeting busy professionals represent the fastest-expanding margin pool as convenience positioning commands price premiums.
USDA organic certification, FDA Good Manufacturing Practice requirements, and EU Novel Food regulations collectively shape ingredient approval timelines, label claim permissibility, and cross-border market access for plant protein suppliers. The FDA maintains strict oversight of protein content claims and allergen labeling, while EU EFSA evaluations govern health claim substantiation for products entering European markets. Stakeholders must monitor evolving protein digestibility scoring methodologies and emerging carbon labeling mandates that threaten to reorder competitive positioning across supplier tiers.
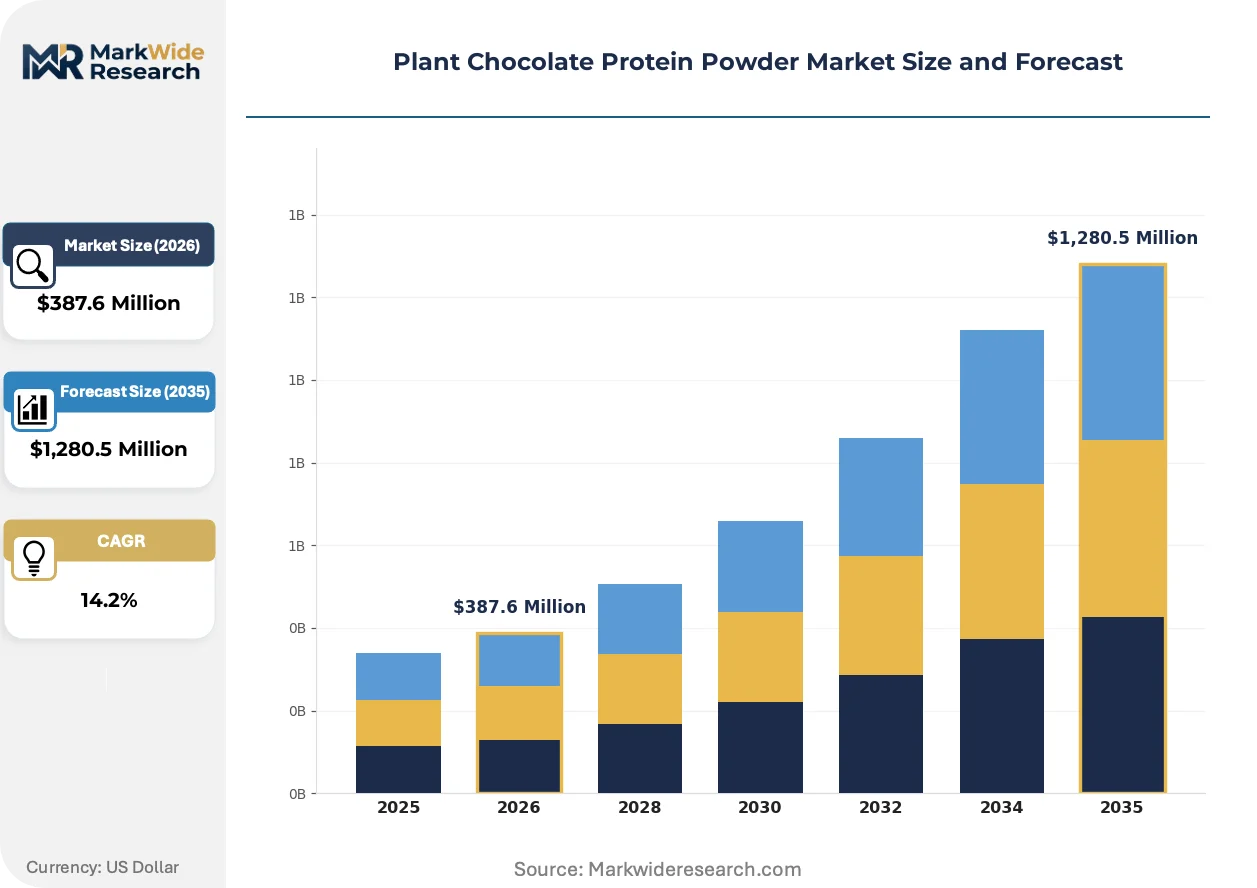
Market Dynamics
Clean-label formulation mandates and plant-based certification protocols are compressing product development timelines while fragmenting supplier qualification requirements across North America and Europe.
Growth Catalysts
- Fitness Enthusiast Demand:Muscle recovery applications in sports nutrition drive volume expansion as protein supplementation becomes routine among recreational athletes seeking dairy-free alternatives.
- USDA Organic Certification:Premium positioning through organic supply chains commands shelf-space allocation in specialty retail channels and direct-to-consumer platforms.
- Pea Protein Processing:Neutral flavor profiles and superior emulsification stability versus hemp or rice concentrates simplify formulation complexity for manufacturers.
Market Restraints
- Input Cost Volatility:Organic pea and hemp protein concentrate prices fluctuate with agricultural yield cycles and contract farming availability.
- EU Novel Food Approval:EFSA evaluation timelines for novel protein sources delay market entry by 18-36 months for innovative ingredient suppliers.
- Whey Protein Substitution:Dairy-based alternatives retain cost advantages in mass-market distribution and consumer familiarity in taste panels.
Strategic Opportunities
- Meal Replacement Formats:Busy professionals seeking convenience positioning create margin expansion through single-serve packaging and subscription models.
- Carbon Labeling Mandates:Early compliance with emerging environmental disclosure requirements differentiates suppliers in German and Australian procurement.
- Functional Sweetener Convergence:Stevia-monk fruit blends with cocoa masking properties enable sugar reduction without bitter aftertaste compromises.
Industry Challenges
- Protein Digestibility Scoring:PDCAAS and DIAAS methodology updates require reformulation investments and label claim substantiation.
- Cross-Contamination Controls:Allergen segregation protocols in contract manufacturing facilities demand capital expenditure for dedicated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Chocolate Protein Powder Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Hemp Protein, Pumpkin Seed Protein, Sacha Inchi Protein Formulation: Instant Mix, Concentrate, Isolate, Blend, Flavored Powder Application: Sports Nutrition, Weight Management, Meal Replacement, Dietary Supplement, Functional Foods End User Segment: Athletes, Fitness Enthusiasts, Vegan Consumers, Senior Citizens, Busy Professionals |
| Companies Covered | Glanbia, Nestlé Health Science, NOW Health Group, The Simply Good Foods Company, Orgain, Vega, Garden of Life, OWYN, PlantFusion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Chocolate Protein Powder Market Trends and Innovations
Precision fermentation and enzymatic processing are rewriting protein isolation economics while regulatory carbon accounting forces transparency through supply chains.
Fermentation-derived protein concentrates are displacing conventional extraction methods in pilot-scale production. Biotech ingredient suppliers are securing offtake agreements with sports nutrition brands seeking differentiated sustainability credentials. This technology is displacing solvent-based processing in premium tier positioning and compressing cost curves for novel protein sources.
EU EFSA health claim substantiation requirements are tightening permissible protein content declarations on cross-border shipments. Manufacturers must maintain clinical trial documentation for muscle maintenance claims targeting European fitness consumers. German and French regulators are enforcing stricter documentation than southern European counterparts, creating compliance fragmentation.
Direct-to-consumer subscription models are capturing repeat purchase loyalty previously held by brick-and-mortar specialty retailers. Digital-native brands bypass wholesale margin stacking through owned-channel fulfillment infrastructure. United States and Australian consumers demonstrate highest conversion rates for auto-replenishment programs targeting monthly consumption cycles.
Plant Chocolate Protein Powder Market Segmentation
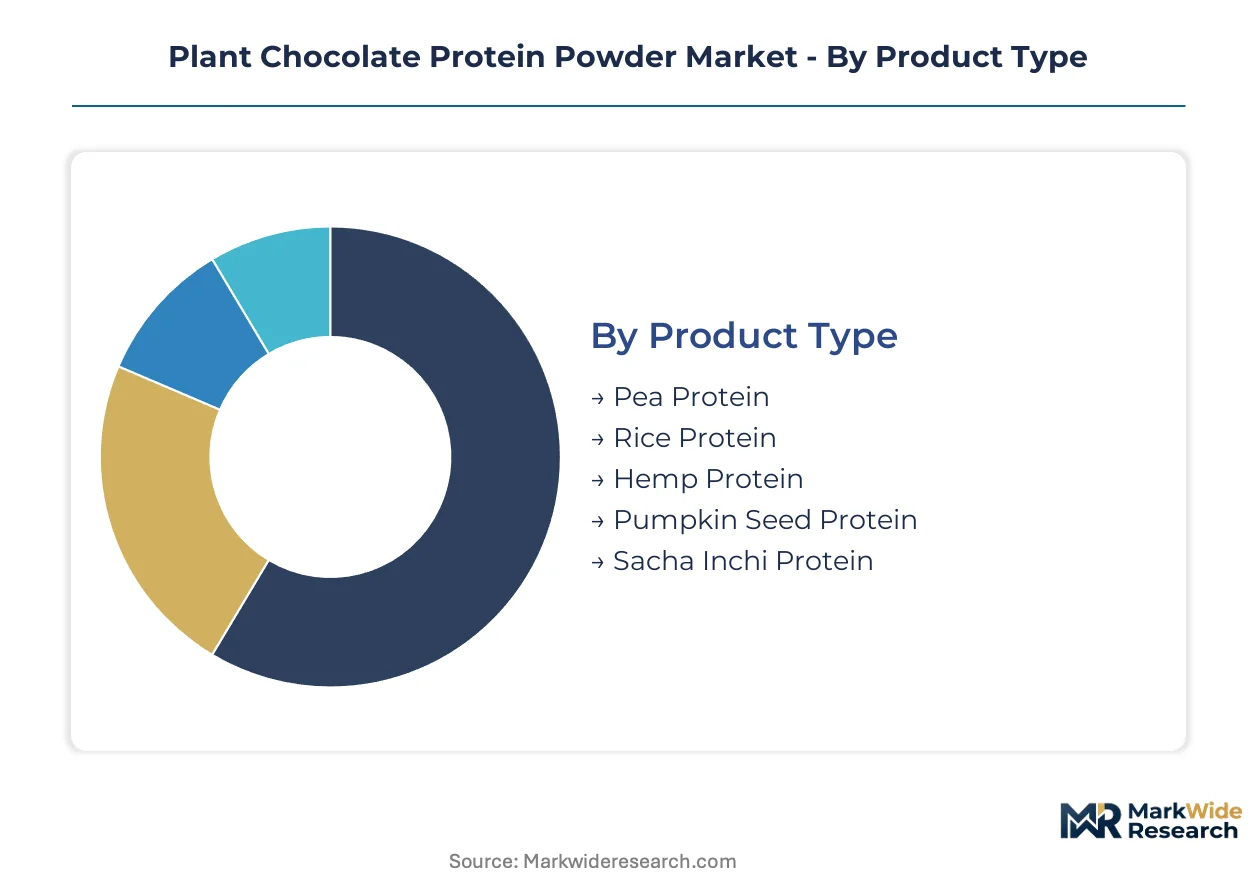
Plant chocolate protein powder segmentation reveals how protein source selection, formulation complexity, and end-user lifestyle patterns create distinct margin architectures across the value chain. Manufacturers configure supply chains and R&D investments around these category boundaries to capture premium positioning.
Product Type:
Pea protein commands the deepest margin pools due to its formulation versatility and neutral sensory profile, while hemp protein extracts sustainability premiums despite smaller volumes.
- Pea Protein:Isolated yellow pea protein concentrates at 80-85% protein by weight deliver superior emulsification stability and minimal off-flavors. Demand concentrates in United States sports nutrition applications where Orgain and Vega anchor retail shelf presence through organic certification.
- Rice Protein:Brown rice protein isolates offer hypoallergenic positioning for consumers with multiple dietary restrictions. German and Australian procurement channels prioritize rice protein for its clean-label compatibility with EU organic protocols.
- Hemp Protein:Cold-pressed hemp seed protein retains omega-3 and omega-6 fatty acid co-benefits alongside 50-70% protein content.
- Pumpkin Seed Protein:Emerging extraction technologies are scaling pumpkin seed protein from specialty ingredient to commercial viability.
- Sacha Inchi Protein:Peruvian-origin sacha inchi protein carries novel food status in EU markets, limiting near-term volume.
Pea protein holds installed capacity. Hemp protein is rotating up the share rankings.
Formulation:
Convenience-driven formats extract price premiums through packaging innovation and subscription economics, while raw concentrates serve contract manufacturing and bulk ingredient channels.
- Instant Mix:Pre-sweetened, pre-flavored single-serve sachets dissolve without blending equipment. United States direct-to-consumer brands capture repeat purchase loyalty through auto-replenishment models targeting monthly consumption cycles.
- Concentrate:70-80% protein powders require consumer-added liquid and flavor masking. Australian specialty retailers stock concentrates for price-sensitive vegan consumers seeking value-oriented bulk purchasing.
- Isolate:90%+ protein purity achieved through additional filtration steps reduces carbohydrate and fat content.
- Blend:Multi-source protein combinations optimize amino acid profiles through complementary plant inputs.
- Flavored Powder:Cocoa-forward flavor systems with stevia-monk fruit sweetening mask plant protein bitterness.
Instant mix formats command shelf space expansion. Blends are climbing the fastest as manufacturers diversify supply risk.
Application:
Sports nutrition anchors absolute dollar contribution, though meal replacement applications expand margins through convenience positioning and professional lifestyle targeting.
- Sports Nutrition:Post-workout recovery formulations emphasize leucine content and rapid absorption kinetics. German fitness consumers drive volume through pharmacy and specialty retail channels with strict EFSA health claim documentation requirements.
- Meal Replacement:Complete macronutrient profiles with added vitamins and minerals target time-constrained professionals. United States subscription models capture this segment through personalized nutrition algorithms and flexible delivery scheduling.
- Weight Management:Satiety-focused formulations leverage protein's thermic effect and appetite suppression.
- Dietary Supplement:Micronutrient-fortified powders address specific deficiency concerns in vegan populations.
- Functional Foods:Protein enrichment of bakery, beverage, and snack applications extends beyond traditional supplement formats.
Sports nutrition maintains production scale. Meal replacement is expanding most quickly through digital-native brand penetration.
End User Segment:
Fitness enthusiasts and vegan consumers represent the highest lifetime value cohorts, while busy professionals demonstrate steepest adoption velocity through convenience-seeking behavior.
- Fitness Enthusiasts:Recreational athletes seeking dairy-free alternatives drive routine supplementation habits. Australian gym chains and specialty retailers capture this segment through bundled protein and equipment promotions.
- Vegan Consumers:Ethical and environmental motivation sustains price inelasticity and brand loyalty. German consumers prioritize organic certification and carbon footprint transparency in procurement decisions.
- Athletes:Competitive and professional sports participants require batch-tested, contaminant-free formulations.
- Senior Citizens:Sarcopenia prevention and muscle maintenance claims target aging populations with tailored flavor profiles.
- Busy Professionals:Time-constrained urban workers prioritize portability and minimal preparation requirements.
Fitness enthusiasts dominate current purchasing frequency. Busy professionals are gaining share fastest through subscription model conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian pea protein processors supply formulation-ready concentrates to United States sports nutrition brands, while Australian hemp protein exporters serve German organic retailers through Rotterdam port distribution.
United States
Fitness enthusiasts and busy professionals drive subscription model adoption through direct-to-consumer platforms. FDA Good Manufacturing Practice requirements enforce protein content claim substantiation and allergen labeling protocols. Los Angeles and Austin host the densest clusters of digital-native brands deploying personalized nutrition algorithms.
Germany
Vegan consumers prioritize carbon footprint transparency and organic certification in procurement decisions. EFSA health claim evaluations govern muscle maintenance declarations on cross-border shipments. Berlin and Hamburg anchor specialty retail networks enforcing stricter documentation than southern European counterparts.
Australia
Gym chains bundle protein promotions with equipment sales to capture fitness enthusiast loyalty. TGA oversees therapeutic claim restrictions on sports nutrition imports. Sydney and Melbourne concentrate direct-to-consumer fulfillment infrastructure serving monthly auto-replenishment cycles.
Canada
Organic supply chain integration supports premium positioning in United States natural channel distribution. Health Canada and PMRA regulate novel protein ingredient approvals and pesticide residue thresholds. Prairie provinces concentrate pea protein processing capacity serving North American formulation demand.
Plant Chocolate Protein Powder Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies into three tiers: multinational nutrition conglomerates with retail shelf dominance, mid-cap organic specialists with supply chain control, and digital-native direct-to-consumer brands with subscription economics. Strategic moves concentrate on M&A for manufacturing scale and backward integration into organic pea protein cultivation.
Within the organic specialist tier, Orgain and Vega exemplify supply chain-anchored positioning, while NOW Health Group occupies the value-oriented mass-market vector. Glanbia and Nestlé Health Science represent multinational scale advantages in ingredient sourcing and regulatory compliance infrastructure. Garden of Life and OWYN sit within the clean-label certification cluster targeting premium natural channel placement.
| Leading Market Players |
|---|
| Glanbia |
| Nestlé Health Science |
| NOW Health Group |
| The Simply Good Foods Company |
| Orgain |
| Vega |
| Garden of Life |
| OWYN |
| PlantFusion |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Canadian pea protein processors and United States sports nutrition brands lock in supply access and price visibility across 18-36 month horizons. These arrangements buffer formulation-ready concentrate costs against organic agricultural yield volatility while securing shelf-space allocation in specialty retail channels.
Pricing Analysis
Current-generation enzymatic processing commands 15-25% premiums over solvent-based extraction methods, while precision fermentation-derived proteins remain pre-commercial with aspirational cost curves. Three-tier pricing structure across premium organic certified, standard conventional, and economy bulk concentrate levels stratifies by USDA certification status and volume scale. Cost compression in conventional concentrates is intensifying because Prairie province capacity expansions outpace near-term demand absorption. Vegan consumers demonstrate lowest price sensitivity, while contract manufacturing channels serving mass-market distribution exhibit highest elasticity.
Supply Chain Analysis
Canada and the United States anchor North American pea protein processing, while Australia and Germany concentrate hemp protein extraction and formulation-ready distribution. Raw material inputs draw from organic yellow pea cultivation in Prairie provinces, cocoa butter and powder sourcing from West African cooperatives, and stevia-monk fruit sweetener blends from Chinese extraction facilities. Single-source vulnerability concentrates in Canadian organic pea protein isolate supply, where three processors control 70% of installed capacity. Distribution runs through Rotterdam port hubs for EU-bound shipments and direct-to-consumer fulfillment centers in Los Angeles, Austin, Sydney, and Melbourne for subscription model delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant chocolate protein powder sits in early-cycle expansion as precision fermentation and enzymatic processing technologies compress production economics while carbon labeling mandates create first-mover positioning advantages. Fitness enthusiast routine adoption and busy professional convenience-seeking sustain penetration velocity across sports nutrition and meal replacement applications.
For Market Incumbents: Shield organic certification premiums by accelerating backward integration into Prairie province contract farming and securing dedicated allergen-segregated production lines before cross-contamination protocols tighten. Capacity reservation agreements with fermentation-derived protein suppliers hedge against novel ingredient substitution threats from biotech entrants. Channel control through direct-to-consumer subscription infrastructure defends margin position against digital-native brand encroachment. For New Entrants and Emerging Players: Anchor in Australian gym chain bundled promotions and German pharmacy channel specialty retail, where incumbent shelf presence remains underdeveloped relative to United States saturation. Meal replacement formats targeting time-constrained urban professionals represent the most penetrable white-space segment. Carbon-negative supply chain storytelling enables premium positioning without competing head-to-head on organic certification investment thresholds. For Investors and Strategic Acquirers: Fermentation technology platforms with offtake agreements and pilot-scale production capacity represent the highest-conviction acquisition target archetype for 5-10 year window viability. Mid-cap organic specialists with captive supply chain control command scarcity premiums in consolidation scenarios. The signal to watch is EFSA novel food approval timeline compression for precision fermentation proteins, which would reorder competitive tiers and validate technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive supply of yellow peas from Prairie province contract farming secures USDA certification premiums. |
| Precision Fermentation Scale-Up | Biotech-derived protein concentrates bypass solvent extraction costs and EFSA novel food bottlenecks. |
| Direct-to-Consumer Subscription Launch | Owned-channel fulfillment in Los Angeles and Sydney captures auto-replenishment loyalty from fitness enthusiasts. |
| Carbon Labeling Compliance Program | Early adoption of environmental disclosure protocols differentiates suppliers in German and Australian procurement. |
| Allergen-Segregated Production Investment | Dedicated lines for organic certification and cross-contamination control meet tightening FDA and EU manufacturing standards. |
Research Methodology
Desk research of customs and trade databases, organic certification registries, and EFSA novel food submission filings preceded structured interviews with sports nutrition brand procurement directors, contract manufacturing facility managers, organic supply chain certification auditors, and retail category buyers. Primary fieldwork with formulation scientists and fermentation technology developers combined with secondary validation against USDA organic handler databases and FDA facility registration records. Bottom-up volume modeling across protein source, formulation format, and application segments triangulated against top-down category spend estimates from retail audit data.
Variance decomposition across protein source tiers, formulation complexity levels, end-user lifestyle segments, and regional regulatory clusters shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level adoption curves weighted by channel expansion rates and certification penetration thresholds. Forecast inputs incorporated organic agricultural yield cycles, EFSA evaluation timeline distributions, and direct-to-consumer subscription conversion benchmarks from comparable nutrition categories.
Material uncertainties — EFSA novel food approval delays, organic input cost volatility, and precision fermentation technology cost curve trajectories — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway efficiency and consumer willingness-to-pay for sustainability credentials. Recalibration cycles align with material shifts in carbon labeling mandate implementation and protein digestibility scoring methodology updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Oat Protein Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Tempeh Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Soy Protein Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Europe Pea Protein Market