
 Plant Based Tuna Market | 2026-2036
Plant Based Tuna Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Tuna Market Outlook
Multi-source protein procurement is realigning how manufacturers secure inputs for plant-based seafood formulations. Good Catch leverages pea-protein supply partnerships across North American growing regions to anchor its production scale. Nestlé competes through its established cold-chain infrastructure, while OmniFoods differentiates via Asian-market recipe localization.
Plant-based tuna comprises textured protein isolates—typically pea or soy derived—blended with algae oils and binders to replicate the flake structure and umami profile of cooked skipjack or albacore, serving retail and foodservice channels seeking marine-free alternatives. Chilled formats occupy premium shelf space in European supermarkets, whereas pouched varieties target convenience-oriented flexitarian segments with lower per-unit pricing and extended ambient stability. Frozen products sustain the broadest ingredient diversity, incorporating seaweed and lentil blends that appeal to allergen-avoidant consumers.
The FDA governs allergen labeling and GRAS status for novel plant proteins in the United States, while EFSA evaluates health claims and novel-food authorizations across European member states; both frameworks elevate compliance costs but also validate product safety for mainstream retailers. BIS certification requirements in India and evolving GB standards in China add complexity for exporters targeting Asian growth corridors. Stakeholders must monitor regulatory divergence on protein-source nomenclature, as labeling restrictions on terms like "tuna" directly constrain market access and consumer communication strategies.
Market Dynamics
Protein sourcing concentration is restructuring the plant-based tuna market as manufacturers compete for limited pea and soy isolate capacity while algae oil suppliers struggle to scale fermentation output to match formulation demand.
Growth Catalysts
- EU Green Deal protein diversification mandates:The Farm to Fork Strategy sets binding sustainability targets for foodservice procurement across member states, creating institutional demand for marine-free alternatives in public catering contracts.
- Flexitarian household penetration:German and British supermarkets are expanding chilled plant-based seafood sets, with dedicated fixture space driving trial among reduction-focused consumers.
- Precision fermentation of heme and binding proteins:This technology is reducing off-flavors in legume-based formulations, improving sensory parity with cooked skipjack.
Market Restraints
- Pea protein supply concentration:North American growing regions dominate isolate production, exposing European manufacturers to currency and tariff volatility on imported inputs.
- EFSA novel-food authorization timelines:The 18-24 month evaluation window for new algae-derived ingredients delays product pipeline expansion.
- Price premium over conventional tuna:Ambient pouched varieties remain 40-60% above commodity skipjack, constraining mass-market penetration.
Strategic Opportunities
- Foodservice direct distribution:Contract manufacturers are bypassing retail slotting fees by supplying prepared salad and sandwich chains with bulk chilled formats.
- India BIS certification pathway:Early entrants securing domestic standards approval gain preferential placement in quick-service restaurant supply agreements.
- Seaweed-lentil hybrid formulations:These ingredient combinations address allergen labeling constraints while differentiating texture profiles in frozen retail segments.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, flavor masking, and extrusion processing commands premium compensation in competitive labor markets.
- Co-manufacturer capacity allocation:Shared production lines require complex changeover protocols between allergen-containing and allergen-free runs, constraining batch flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Tuna Market |
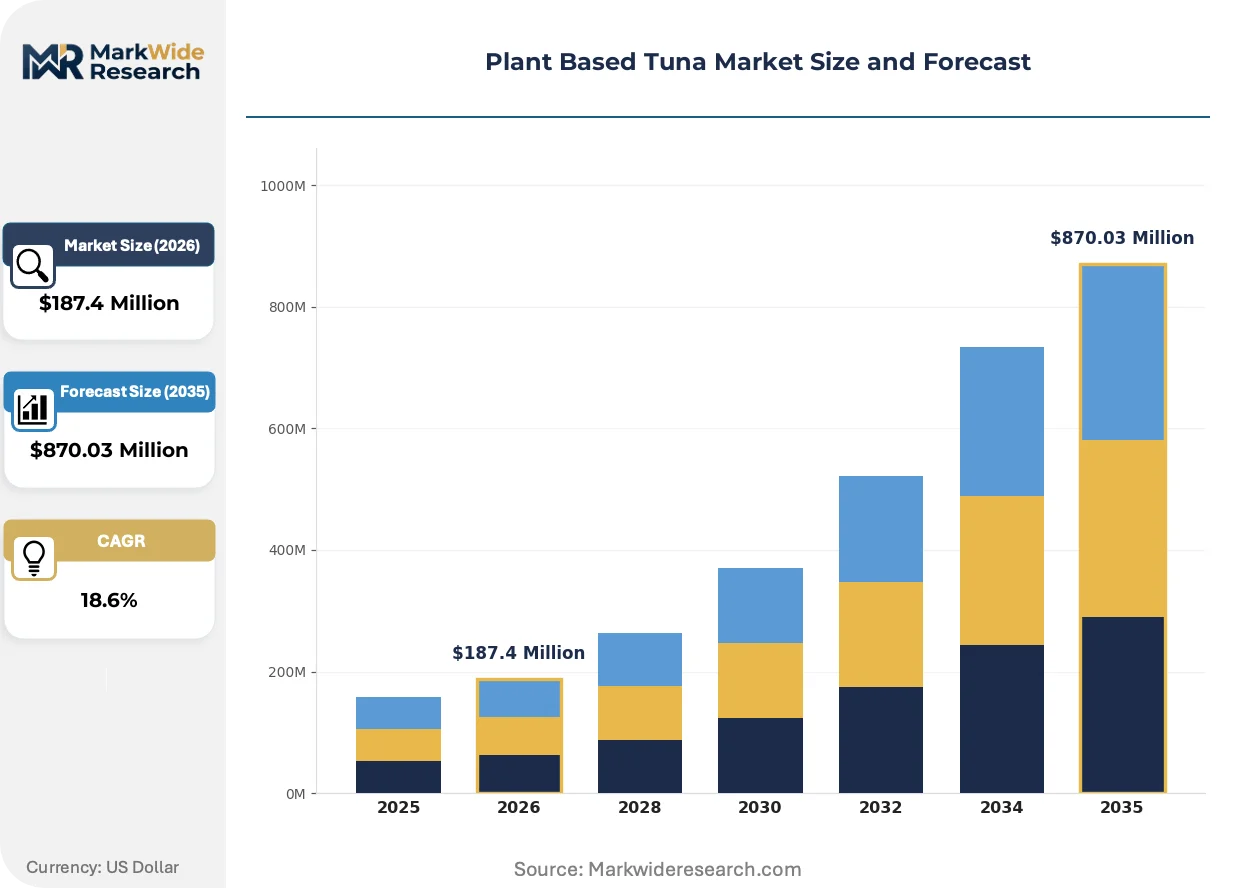
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled, Frozen, Canned, Pouched Ingredients: Pea Protein, Soy Protein, Seaweed, Lentils Distribution Channel: Supermarkets, Online Retailers, Natural Food Stores, Restaurants End User: Vegans, Vegetarians, Flexitarians, Seafood Enthusiasts |
| Companies Covered | Thai Union Group PCL, Good Catch, Ocean Hugger Foods, Atlantic Natural Foods, Sophie’s Kitchen, Nestlé, VGarden, Endori, OmniFoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Tuna Market Strategic Shifts
High-moisture extrusion technology is redefining texture replication capabilities while regulatory nomenclature battles reshape how products communicate with consumers. These forces are compressing development cycles and forcing faster go-to-market decisions.
High-moisture extrusion is consolidating its position as the dominant texturization platform for plant-based seafood. European and North American manufacturers are retrofitting existing protein processing lines with twin-screw configurations capable of continuous fiber alignment. This capital investment is consolidating supplier power among equipment vendors with proven scale-up experience.
REACH chemical safety registrations are expanding scrutiny of algae-derived lipid ingredients used for omega-3 fortification. ECHA evaluation of novel extraction solvents is extending compliance timelines for European market entry. Frozen product developers are responding by reformulating with domestically sourced seaweed oils to preempt authorization delays.
Direct-to-foodservice procurement is displacing traditional broker-mediated distribution in the United States. Restaurant chains are establishing captive supply agreements with dedicated co-manufacturers, securing volume commitments in exchange for recipe exclusivity. This channel compression is most visible in the fast-casual salad segment, where private-label plant-based tuna now commands dedicated menu positioning.
Plant Based Tuna Market Segmentation
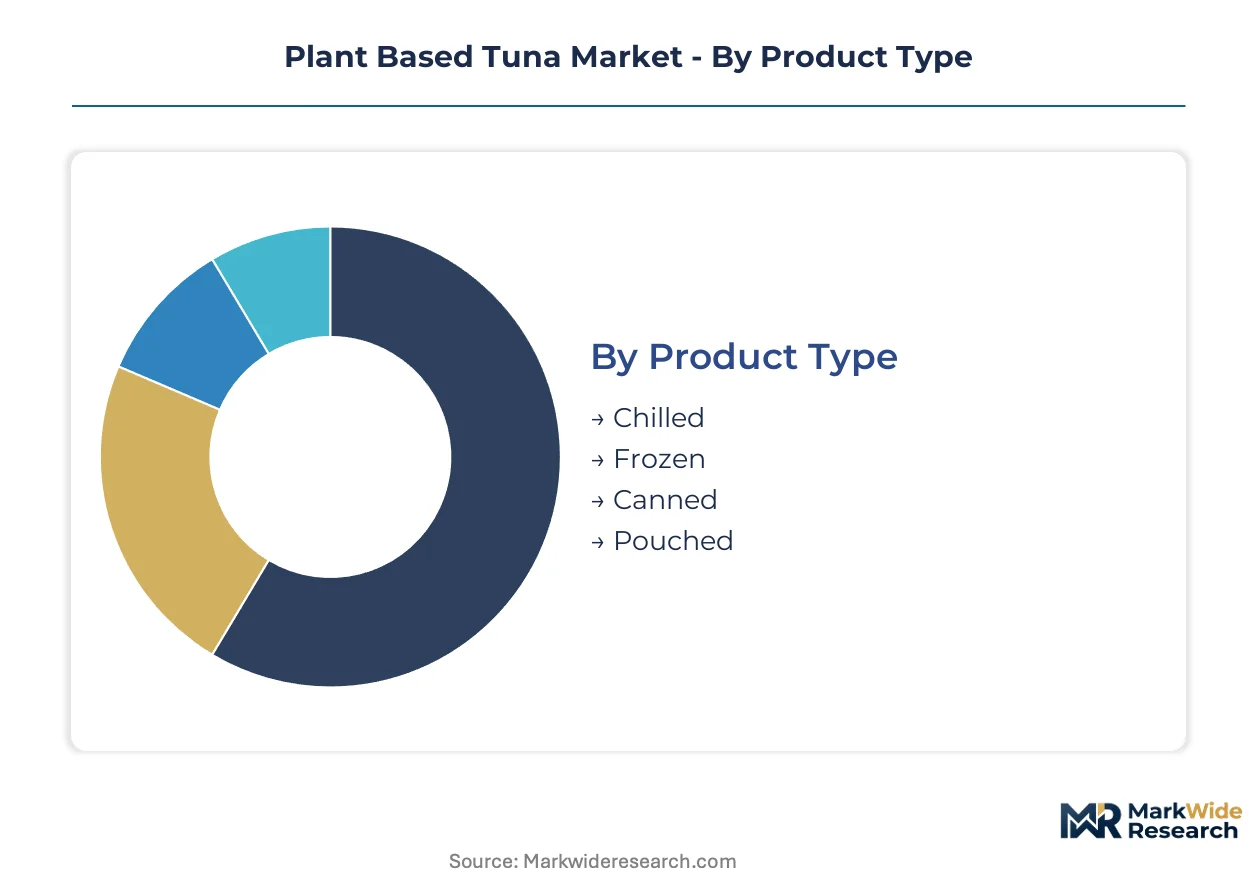
Segmentation in plant-based tuna reveals how formulation choices, temperature requirements, and channel strategies create distinct competitive arenas. Manufacturers must align protein sourcing decisions with format-specific shelf-life demands and end-user dietary motivations.
Product Type:
Integration depth varies sharply across temperature-controlled formats, with chilled products demanding dedicated cold-chain infrastructure while ambient-stable formats embed into broader pantry portfolios.
- Chilled:High-moisture extruded proteins in refrigerated formats replicate the flake structure of cooked skipjack most precisely. German and British supermarkets allocate dedicated fixture space to these premium offerings, driving trial among reduction-focused flexitarian households despite perishability constraints.
- Frozen:Blast-frozen blocks and individually quick-frozen portions incorporate the broadest ingredient diversity, including seaweed-lentil blends that appeal to allergen-avoidant consumers. Foodservice operators in the United States favor frozen formats for prepared salad and sandwich applications where portion control and extended holding tolerance matter.
- Canned:Retort-processed ambient formats leverage established seafood canning infrastructure with modified protein binders to survive thermal processing.
- Pouched:Flexible retort pouches target convenience-oriented flexitarian segments with lower per-unit pricing and shelf-stable portability for on-premise consumption.
Volume placements concentrate in frozen formats across foodservice procurement; the faster expansion belongs to chilled retail segments gaining dedicated supermarket space.
Ingredients:
Cost tier differentiation separates commodity legume isolates from novel fermentation-derived inputs, with premium positioning attaching to algae oil fortification and allergen-free blends.
- Pea Protein:North American isolate suppliers anchor formulation costs for major manufacturers, though European processors face currency and tariff exposure on imported inputs. EFSA novel-food timelines for alternative protein sources reinforce pea protein's incumbent position in EU formulations.
- Soy Protein:Established extrusion infrastructure and GRAS status in the United States sustain soy's cost advantage, though allergen labeling requirements constrain placement in school and institutional catering contracts.
- Seaweed:Domestic European sourcing of lipid extracts preempts REACH registration delays affecting algae oil competitors.
- Lentils:Pulse protein concentrates address clean-label preferences in natural food store channels with shorter ingredient declarations.
Procurement volumes cluster around pea protein isolates; lentil and seaweed hybrids are climbing the fastest as allergen-avoidant positioning gains shelf space.
Distribution Channel:
Customer type stratification separates mass-market supermarket penetration from specialized natural food store curation, with restaurant direct-distribution compressing traditional broker margins.
- Supermarkets:Chilled set expansion in Germany and the United Kingdom drives household penetration among flexitarian consumers seeking marine-free alternatives adjacent to conventional seafood fixtures.
- Online Retailers:Subscription and direct-to-consumer platforms capture trial-oriented buyers with educational content addressing protein completeness and omega-3 bioavailability claims.
- Natural Food Stores:Curated assortments emphasize certified organic and non-GMO verified formulations with premium price positioning.
- Restaurants:Fast-casual salad chains in the United States are establishing captive supply agreements with dedicated co-manufacturers, bypassing retail slotting fees through direct procurement.
Revenue concentration sits with supermarket chilled sets; restaurant direct-distribution channels are expanding most quickly as fast-casual chains add dedicated menu positioning.
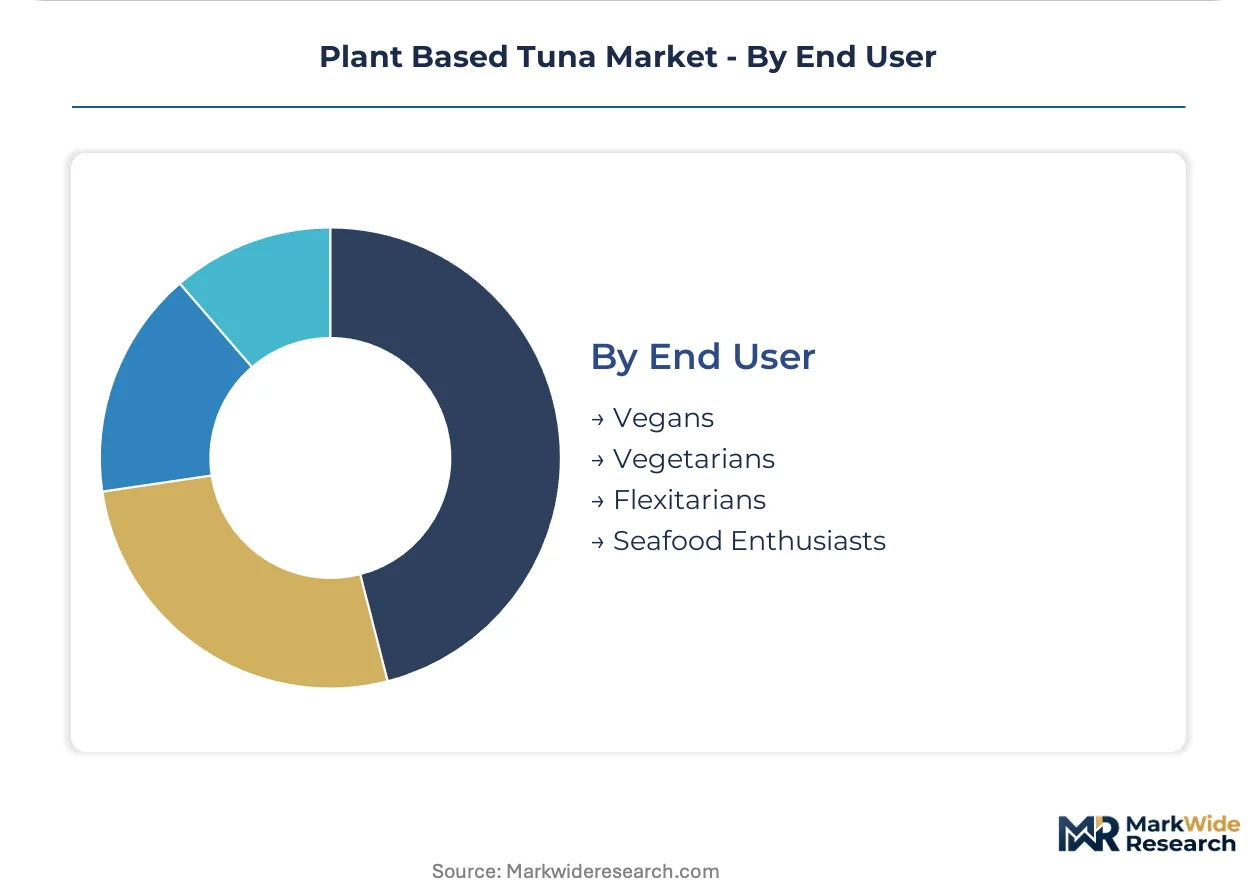
End User:
Maturity differentiation separates established vegan adopters from emerging flexitarian experimentation, with seafood enthusiasts representing the highest-value conversion target for sensory parity investments.
- Vegans:This core constituency accepts texture and flavor trade-offs that broader audiences reject, sustaining demand for earlier-generation formulations with simpler ingredient lists.
- Vegetarians:Lacto-ovo dietary patterns create crossover potential with egg-based binders in some European formulations, though this limits vegan market overlap.
- Flexitarians:Reduction-focused households in the United States and United Kingdom drive volume expansion, with precision fermentation of heme and binding proteins improving sensory parity to capture this segment's taste-driven purchase criteria.
- Seafood Enthusiasts:The most demanding segment on flake structure and umami intensity, requiring advanced extrusion technology and algae-derived flavor precursors to achieve acceptable substitution thresholds.
Absolute volume leadership belongs to flexitarian households; seafood enthusiasts represent the steepest expansion trajectory as formulation fidelity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plant-based tuna concentrates in Germany, the United Kingdom, and the United States as retail distribution widens and restaurant chains expand menu placements. Regulatory frameworks diverge sharply across these markets, shaping formulation choices and market entry timelines. Industrial clusters in each geography anchor distinct competitive advantages.
United States
Fast-casual salad chains drive foodservice volume through captive supply agreements with dedicated co-manufacturers. The FDA governs allergen labeling and GRAS status for novel plant proteins, elevating compliance costs for new entrants. California's Bay Area hosts precision fermentation startups improving sensory parity in legume-based formulations.
Germany
Flexitarian household penetration sustains chilled retail expansion with dedicated supermarket fixture space driving trial. The EU Green Deal's Farm to Fork Strategy sets binding sustainability targets for public catering procurement. Berlin-Brandenburg anchors alternative protein R&D clusters developing high-moisture extrusion capabilities.
United Kingdom
Supermarket chilled sets expand alongside marine-free alternatives adjacent to conventional seafood fixtures. EFSA evaluates health claims and novel-food authorizations with 18-24 month evaluation windows delaying pipeline expansion. London's food technology corridor attracts fermentation-derived ingredient startups.
India
Quick-service restaurant supply agreements offer preferential placement for early entrants securing BIS certification. FSSAI standards and evolving domestic regulations add complexity for exporters targeting Asian growth corridors. Maharashtra's food processing clusters develop lentil-protein concentrate capabilities for allergen-avoidant formulations.
China
GB standards evolution and dual carbon goals reshape protein sourcing requirements for foodservice operators. SAMR oversight of novel food ingredients extends authorization timelines for algae-derived formulations. Yangtze River Delta manufacturing hubs retrofit existing protein processing lines with twin-screw extrusion configurations.
Plant Based Tuna Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers secure limited pea and soy isolate capacity while algae oil suppliers scale fermentation output. The vendor base spans multinational food conglomerates, specialized alternative protein startups, and contract manufacturers with shared production lines. Three archetypes define positioning: established CPG players leveraging cold-chain infrastructure, venture-backed innovators driving recipe localization, and co-manufacturers offering batch flexibility. Competitive moves concentrate on direct-to-foodservice procurement bypassing retail slotting fees, and backward integration into North American pea-protein growing regions.
Within the venture-backed innovator tier, Good Catch and OmniFoods exemplify distinct geographic specialization strategies, with the former anchoring North American supply partnerships and the latter driving Asian-market recipe adaptation. Nestlé occupies a position representing established CPG infrastructure deployment, leveraging scale advantages in chilled distribution networks. These three entities collectively illustrate how capital structure and geographic focus differentiate competitive positioning.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Good Catch |
| Ocean Hugger Foods |
| Atlantic Natural Foods |
| Sophie's Kitchen |
| Nestlé |
| VGarden |
| Endori |
| OmniFoods |
| Others |
Value Chain & Pricing Dynamics
Pea protein isolate spot prices in North American growing regions cascade through formulation costs, compressing margins for European manufacturers while amplifying pricing power among chilled retail incumbents with captive supply agreements.
Pricing Analysis
Volume leadership sits with frozen foodservice formats, while margin concentration attaches to chilled premium retail. Three-tier pricing structure across premium, standard, and economy levels separates algae oil-fortified offerings from commodity legume isolates and private-label alternatives. Pricing pressure stems from currency volatility on imported pea protein isolates, eroding European manufacturer competitiveness. Flexitarian households in Germany and the United Kingdom exhibit highest price sensitivity, whereas seafood enthusiasts accept substantial premiums for sensory parity.
Supply Chain Analysis
Reverse-logistics flows remain minimal given perishable chilled formats and single-use retort pouches, though frozen block returns from foodservice operators create limited refurbishment channels for off-spec extruded protein. Supply concentrates in the United States, Canada, and Germany for pea protein isolate processing, with algae oil fermentation anchoring in California and the Netherlands. Raw material dependencies include North American yellow pea isolates, fermentation-derived algae lipids, and Asian-sourced seaweed extracts. Single-source vulnerability on twin-screw extrusion equipment from German and Italian vendors constrains capacity expansion timelines. Distribution runs through dedicated cold-chain partnerships for chilled retail, broker-mediated networks for ambient formats, and direct procurement agreements for restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into North American pea-protein growing regions has become the decisive vertical-integration race, with formulation fidelity and input cost control separating viable scale players from contract-manufacturing dependents.
For Market Incumbents: Deepen captive supply agreements with Alberta and Manitoba pea processing cooperatives to lock in isolate volume commitments ahead of European competitor expansion. Accelerate high-moisture extrusion R&D partnerships with Berlin-Brandenburg equipment clusters to preempt precision-fermentation disruptors achieving sensory parity. EFSA novel-food authorization delays for alternative protein sources create a temporary defensive moat worth reinforcing through accelerated pipeline submissions. For New Entrants and Emerging Players: Precision-fermentation heme platforms offer a technology-first wedge into the seafood-enthusiast segment where incumbent legume formulations underperform on umami intensity. Target India's quick-service restaurant supply agreements where BIS certification barriers filter out established Western competitors. A co-manufacturing partnership with Maharashtra lentil-protein concentrate developers enables clean-label positioning without capital-intensive isolate production infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European chilled-format specialists with established supermarket fixture space but strained working capital from pea protein import exposure. Long-term viability hinges on fermentation-derived ingredient pipelines achieving cost parity with commodity isolates. Monitor EFSA authorization timelines for novel algae-derived binding proteins as the inflection signal separating platform-scale players from formulation-limited niche operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Supply | Captive sourcing from Alberta and Manitoba growing regions locks in formulation cost stability against currency volatility. |
| High-Moisture Extrusion Capacity Expansion | Twin-screw retrofit partnerships with German equipment vendors accelerate texture replication capabilities for seafood-enthusiast conversion. |
| Direct-to-Foodservice Distribution Bypass | Restaurant chain procurement agreements eliminate retail slotting fees while securing volume commitments through recipe exclusivity. |
| Precision Fermentation Ingredient Pipeline | Heme and binding protein platforms from California Bay Area startups reduce off-flavors in legume-based formulations. |
| EFSA Novel-Food Pre-Submission Investment | Early regulatory engagement on algae-derived ingredients preempts authorization delays affecting competitor pipeline expansion. |
Study Parameters
Document review covered EU Farm to Fork Strategy implementation guidance, FDA GRAS notification filings for novel plant proteins, and EFSA novel-food authorization registers, complemented by interviews with food technology R&D directors, plant-based protein procurement leads at fast-casual restaurant chains, co-manufacturing operations managers, and chilled retail category buyers at German and British supermarkets. Secondary validation drew from customs trade data on pea protein isolate flows, SEC filings of diversified CPG conglomerates, and equipment vendor order backlogs for twin-screw extrusion systems. Bottom-up volume estimates from individual manufacturer capacity announcements were triangulated against top-down protein substitution demand models.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation modeling incorporated temperature-controlled format, protein source type, distribution channel structure, and end-user dietary motivation. CAGRs were derived from slope-intercept fitting of validated data points rather than extrapolation of single-year anomalies. Industry-specific forecast inputs included EFSA authorization pipeline status, precision-fermentation scale-up timelines, and supermarket chilled fixture expansion plans.
Several conditions sit outside the modeled scope, including potential EU labeling restrictions on marine-derived terminology, trade policy shifts affecting North American pea protein export tariffs, and breakthroughs in whole-cut extrusion technology that could displace flake-format dominance. Forecasts reflect documented assumptions on protein isolate supply elasticity and consumer willingness-to-pay thresholds. Practitioners should monitor EFSA novel-food evaluation acceleration, precision-fermentation cost curves, and quick-service restaurant procurement policy shifts for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Soy Food Products Market
Plant Based Food
China Plant Protein Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Vegan Food Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Europe Tofu Market
Plant Based Food
India Plant Protein Market