
 South Africa Beverages Market | 2026-2036
South Africa Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Beverages Market Analytics
South Africa is reconfiguring beverage production capacity through expanded bottling infrastructure in the Western Cape and KwaZulu-Natal corridors. The Coca-Cola Company leverages its entrenched fountain and retail distribution network to sustain volume leadership in soft drinks. Heineken N.V. anchors premium beer positioning through licensed brewing operations and route-to-market density in metropolitan areas. Tiger Brands Ltd competes aggressively in affordable juice and ready-to-drink segments through price-accessible packaging formats.
South Africa beverages encompass potable liquids manufactured through fermentation, extraction, carbonation, or blending processes, with formulations governed by microbial safety thresholds, sugar content specifications, and alcohol-by-volume gradations for commercial distribution. These products serve hydration, refreshment, social occasion, and nutritional supplementation purposes across consumer and institutional channels. Alcoholic beverages and soft drinks command the dominant revenue pools, while bottled water and juice segments attract margin-focused investment as health-conscious retail consumers shift purchase patterns. Distribution through supermarkets and convenience stores retains structural importance, though online retailers capture incremental growth in bulk and subscription formats.
South Africa's national sugar tax framework, administered by the Department of Health and National Treasury, compels manufacturers to reformulate recipes or absorb excise cost pass-through, directly altering competitive economics across carbonated and juice portfolios. The country's Bureau of Standards (SABS) certification requirements and National Regulator for Compulsory Specifications (NRCS) labeling mandates govern product safety, alcohol content declaration, and allergen disclosure, shaping market access conditions for domestic and imported brands alike. Stakeholders must monitor regulatory amendment timelines and reformulation cost trajectories to calibrate portfolio mix and pricing architecture.
Market Dynamics
The Department of Health sugar tax framework is compressing margins across carbonated and juice portfolios, forcing manufacturers to reformulate recipes or absorb excise pass-through costs while competing for shelf space in Gauteng's concentrated retail corridors.
Growth Catalysts
- Urban retail consumption density:Johannesburg and Pretoria distribution clusters anchor national supply throughput, concentrating volume growth in metropolitan catchment areas with higher per-capita beverage expenditure.
- Health and Wellness Levy:The National Treasury's sugar tax regulations are accelerating portfolio diversification toward low-sugar and zero-calorie formulations, creating new product development pipelines.
- Bottling infrastructure expansion:Western Cape and KwaZulu-Natal production corridors are adding fermentation and carbonation capacity to serve coastal demand growth and export positioning.
Market Restraints
- Input cost volatility:Cane sugar and maize pricing fluctuations squeeze formulation economics, particularly for mid-tier juice and carbonated brands with limited pricing power.
- Supply concentration risk:Gauteng province dominates national distribution infrastructure, creating single-point vulnerability for brands dependent on Johannesburg logistics hubs.
- Technical limitation:Alternative sweetener formulations face taste-profile acceptance barriers among traditional consumers, constraining rapid sugar reduction targets.
Strategic Opportunities
- Underpenetrated rural channels:Eastern Cape and Limpopo informal retail networks offer volume expansion potential for affordable packaging formats and sachet-based distribution.
- E-commerce subscription models:Online retailers are capturing incremental bulk purchase growth, enabling direct-to-consumer relationships outside supermarket margin structures.
- Regulatory tailwind:National Regulator for Compulsory Specifications labeling mandates favor transparent ingredient disclosure, rewarding early reformulation investments with shelf positioning advantages.
Industry Challenges
- Reformulation timeline compression:South African Bureau of Standards certification requirements for new low-sugar variants extend product launch cycles, delaying competitive response to tax pressures.
- Route-to-market reconfiguration:Legacy distributor relationships in township economies resist integration with modern trade analytics systems, fragmenting demand visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Beverages Market |
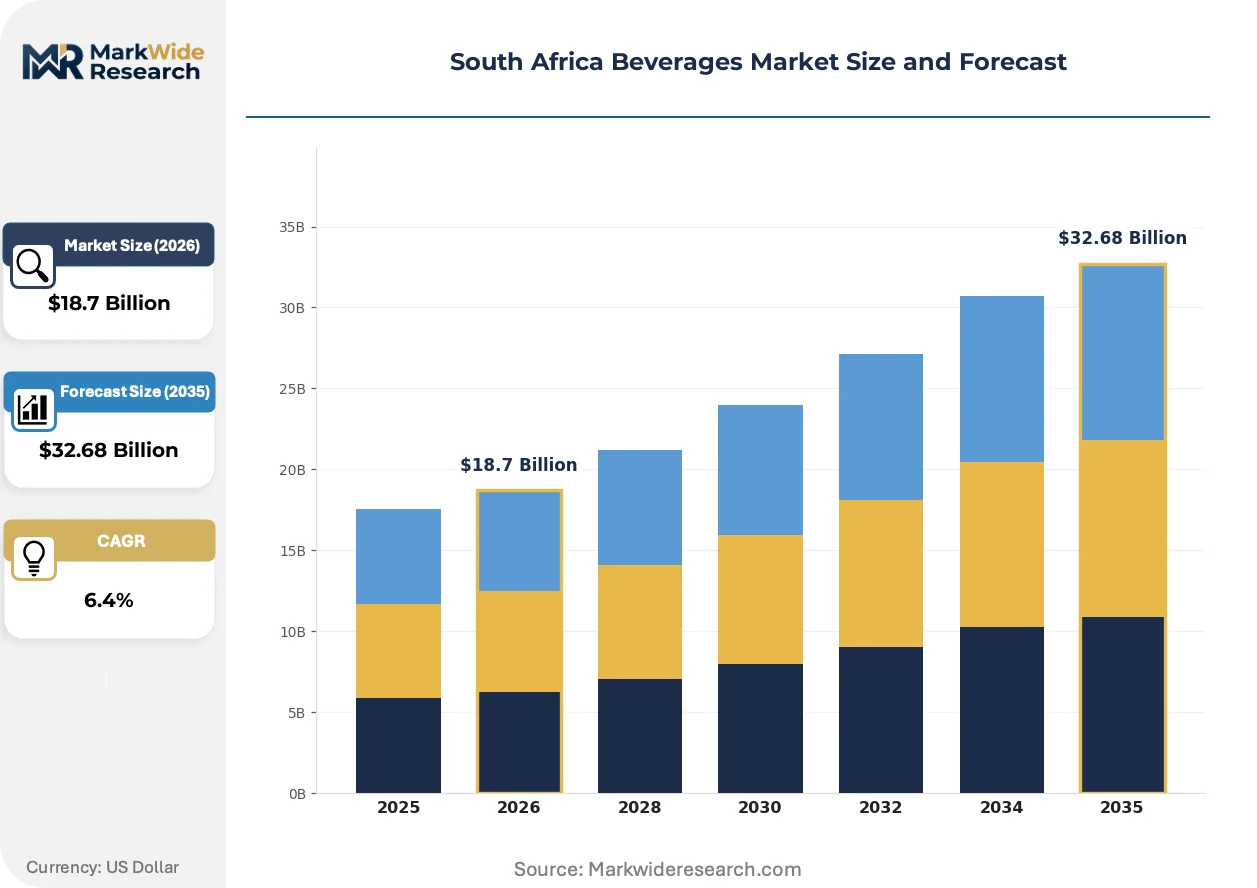
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Alcoholic Beverages, Bottled Water, Juice Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Bars Customer Type: Retail Consumers, Restaurants, Hotels, Catering Services Size: Small, Medium, Large, Extra Large |
| Companies Covered | Heineken N.V., Red Bull GmbH, Anheuser-Busch InBev NV, Carlsberg Group, Monster Beverage Corporation, The Coca-Cola Company, Diageo PLC, Tiger Brands Ltd, PepsiCo Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Beverages Market Evolving Landscape
Reformulation science and digital route-to-market tools are restructuring competitive advantage in South African beverages, shifting value capture from brand equity alone toward operational precision in配方 chemistry and last-mile distribution.
Stevia and monk fruit extract blends are replacing sucrose in carbonated formulations without triggering the aftertaste rejection that plagued early aspartame alternatives. Metropolitan retailers are accelerating adoption of these reformulated SKUs in response to sugar tax tiering. The technology is rendering obsolete the historical trade-off between sweetness intensity and clean-label positioning that constrained premium juice development.
The Department of Health's Health Promotion Levy implements tiered excise structures based on sugar content per 100ml, creating direct financial incentives for recipe engineering. Manufacturers face compressed margins on legacy formulations while gaining competitive room on reduced-sugar alternatives. Carbonated soft drinks and ready-to-drink juices bear the heaviest burden, with portfolio mix shifting toward artificially sweetened and naturally low-sugar variants.
Consumer purchasing is fragmenting across channel types as subscription bulk delivery captures health-conscious household segments. Supermarkets retain impulse and occasion-based transactions, while online platforms secure planned replenishment cycles with lower per-unit logistics costs. This bifurcation is most pronounced in Gauteng and Western Cape urban corridors where delivery infrastructure density supports same-day fulfillment promises.
South Africa Beverages Market Segmentation
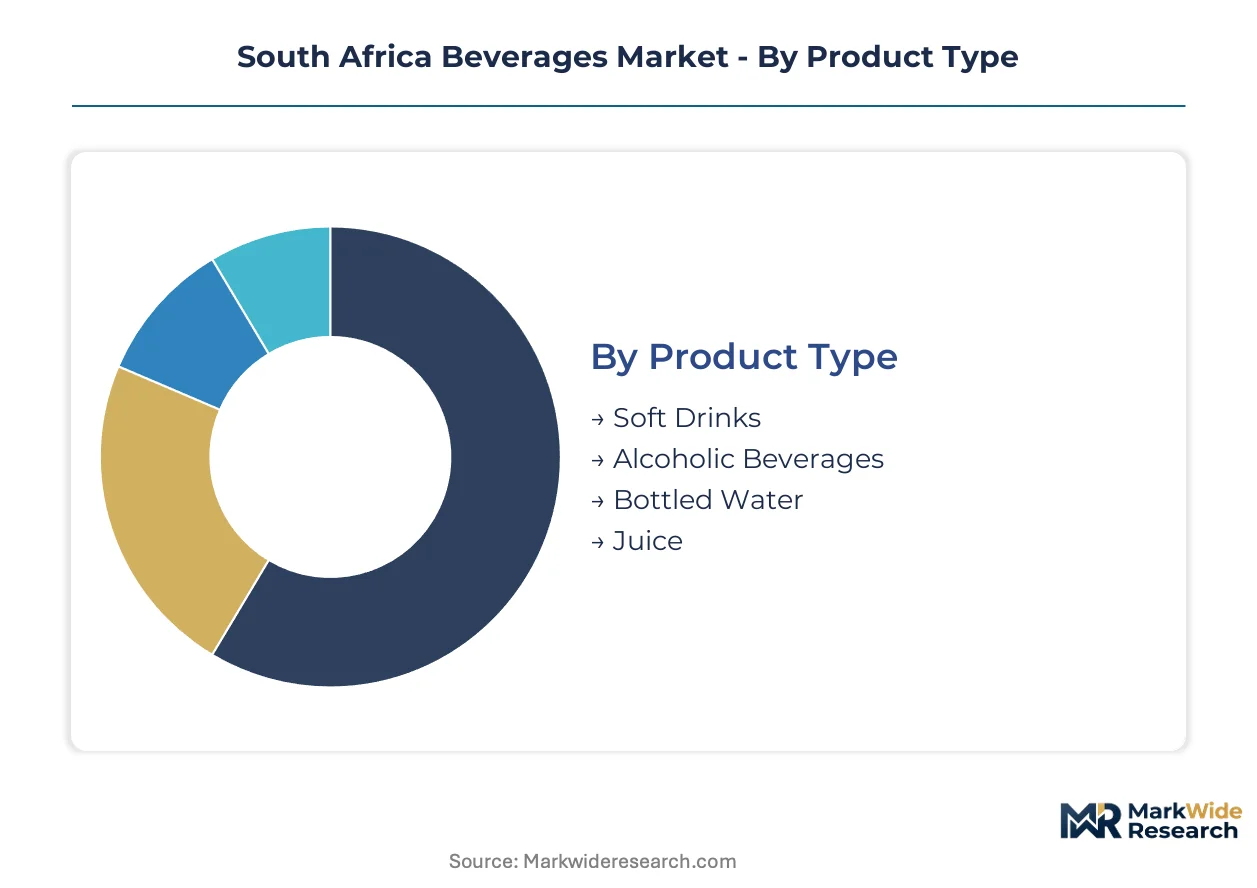
South Africa's beverage segmentation reflects the tension between sugar tax compliance and route-to-market economics. Manufacturers must align product portfolios across four distinct category systems to capture volume in Gauteng's retail corridors while managing excise tier exposure.
Product Type:
Cost tier differentiation governs margin structures as reformulation investments concentrate in premium-positioned categories while economy segments absorb price sensitivity.
- Soft Drinks:Carbonated formulations face the steepest Health Promotion Levy exposure, driving sucrose replacement with stevia-monk fruit blends in Johannesburg and Pretoria metropolitan catchments where sugar-reduced SKUs gain shelf priority.
- Alcoholic Beverages:Licensed brewing operations anchor revenue pools through beer and ready-to-drink spirits, with distribution density in urban corridors supporting premium positioning against excise escalation.
- Bottled Water:Still and sparkling variants bypass sugar tax entirely, attracting margin-focused investment as health-conscious households shift procurement toward hydration categories.
- Juice:Concentrated and not-from-concentrate formulations confront tiered excise structures, forcing portfolio rotation toward reduced-sugar variants with National Regulator for Compulsory Specifications-compliant labeling.
Soft Drinks holds installed capacity. Bottled Water is rotating up the share rankings.
Distribution Channel:
Application-based channel selection determines margin capture as modern trade analytics displace legacy distributor relationships in township economies.
- Supermarkets:Hypermarket and supermarket chains retain structural importance for impulse and occasion-based transactions, with shelf positioning fees increasingly favoring reformulated low-sugar portfolios.
- Convenience Stores:Spaza shops and fuel station retail anchor last-mile access in urban peripheries, though inventory visibility remains fragmented outside integrated route-to-market systems.
- Online Retailers:Subscription bulk delivery captures planned replenishment cycles with lower per-unit logistics costs, concentrated in Western Cape and Gauteng corridors where same-day fulfillment infrastructure exists.
- Bars:On-premise consumption channels support premium alcohol velocity through fountain and draught systems, with volume tied to metropolitan social occasion density.
Supermarkets dominate transaction volume. Online Retailers is climbing the fastest.
Customer Type:
Customer-type segmentation separates institutional procurement scale from household replenishment patterns across diverging price elasticity profiles.
- Retail Consumers:Individual households drive health and wellness purchasing shifts, with sugar-conscious buyers migrating toward zero-calorie alternatives and bottled water in bulk formats.
- Restaurants:Foodservice operators negotiate fountain equipment placements and syrup supply contracts, with menu engineering increasingly excluding high-sugar beverage pairings under consumer pressure.
- Hotels:Hospitality procurement favors premium-branded mini-bar and banquet portfolios, with property-level beverage managers balancing guest expectation against sugar tax cost pass-through.
- Catering Services:Event and contract catering demands volume-scaled packaging with price-accessible unit economics, concentrating purchases in juice and soft drink categories for large-format service.
Retail Consumers anchor volume throughput. Restaurants is gaining share fastest.
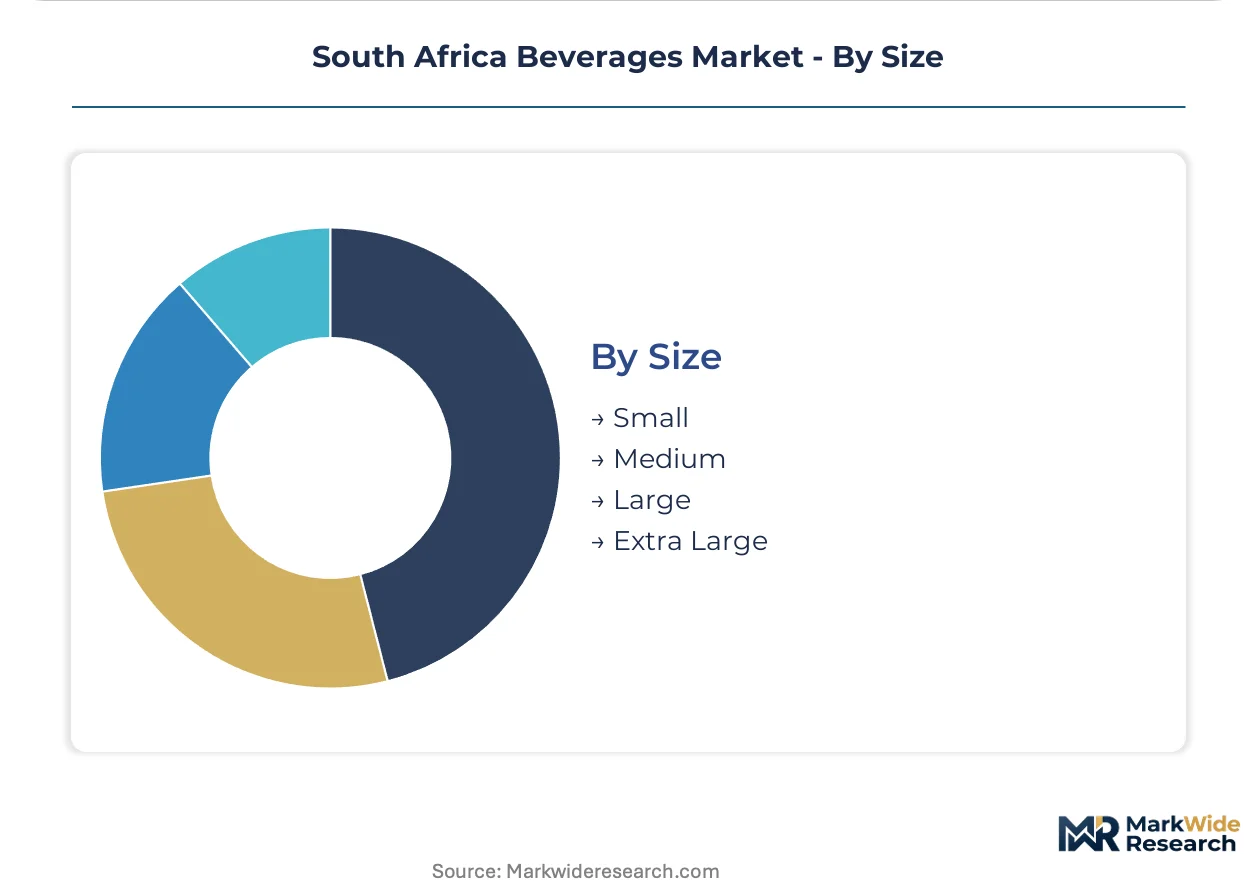
Size:
Packaging volume tiers align with channel economics and consumption occasion, from single-serve impulse to household bulk replenishment.
- Small:Single-serve cans and bottles dominate convenience store and on-premise channels, with unit pricing absorbing sugar tax pass-through more visibly than larger formats.
- Medium:Multi-serve bottles balance portability with per-liter value, capturing family consumption in supermarket weekly shopping baskets across metropolitan areas.
- Large:Two-liter and equivalent formats concentrate in spaza shop and township retail, where price-per-volume sensitivity drives brand switching toward private label alternatives.
- Extra Large:Bulk and dispenser-refill formats serve institutional customers and subscription e-commerce, with logistics optimization favoring consolidated delivery routes in dense urban corridors.
Medium formats hold installed capacity. Extra Large is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bottling capacity clusters in Gauteng province anchor national distribution throughput, with Johannesburg and Pretoria logistics corridors processing the majority of finished goods volume. Western Cape and KwaZulu-Natal production zones are expanding fermentation and carbonation infrastructure to capture coastal demand growth and export positioning. Provincial regulatory enforcement varies across the nine regions, with metropolitan municipalities applying stricter sugar tax compliance monitoring than rural districts.
Gauteng
Johannesburg and Pretoria metropolitan areas concentrate retail consumption density and per-capita beverage expenditure. The Department of Health's Health Promotion Levy enforcement is strictest in Tshwane and Johannesburg metros, accelerating manufacturer reformulation timelines. The East Rand industrial corridor hosts expanded bottling facilities serving national distribution networks.
Western Cape
Cape Town's port infrastructure supports import-dependent ingredient supply chains and export-oriented production. The National Treasury coordinates sugar tax administration with provincial revenue services, creating compliance cost differentials. The Paarl-Stellenbosch wine and beverage manufacturing cluster is diversifying into low-sugar ready-to-drink formulations.
KwaZulu-Natal
Durban's logistics hub anchors coastal distribution for sugar-sweetened beverage categories facing excise pressure. The South African Bureau of Standards maintains regional certification laboratories in eThekwini, streamlining product approval for local manufacturers. The Richards Bay industrial zone is adding carbonation capacity to serve Eastern Cape and Mpumalanga catchments.
Eastern Cape
Port Elizabeth and East London retail networks remain underpenetrated relative to national averages, offering volume expansion potential. Provincial health departments apply variable sugar tax compliance monitoring, creating enforcement gaps in informal township retail. The Coega industrial development zone is attracting beverage packaging investment for regional supply.
Limpopo
Polokwane and rural retail corridors exhibit high price sensitivity and sachet-format preference in beverage purchasing. The National Regulator for Compulsory Specifications labeling mandates face slower adoption in spaza shop channels. The Musina-Beitbridge logistics corridor is developing cross-border distribution infrastructure for regional beverage trade.
South Africa Beverages Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and packaging supply. The South Africa beverages market structures around three distinct competitive tiers: multinational brewers and soft drink manufacturers with integrated route-to-market systems; regional bottlers and licensed producers leveraging foreign brand equity; and domestic specialists in affordable juice and water categories. Consolidation pressure is accelerating through portfolio diversification toward low-sugar variants and strategic partnerships for distribution access in informal retail channels.
Among multinational platform operators, The Coca-Cola Company, Heineken N.V., and PepsiCo Inc. occupy positions defined by entrenched fountain equipment placements and metropolitan retail density. These Amsterdam-based, Atlanta-headquartered, and Purchase-based corporations exemplify the scale-driven archetype through licensed brewing and bottling arrangements that transfer capital-intensive production risk to local partners. Tiger Brands Ltd represents the domestic specialist tier, competing through price-accessible packaging formats in categories where multinational cost structures face margin compression from sugar tax exposure.
| Leading Market Players |
|---|
| Heineken N.V. |
| Red Bull GmbH |
| Anheuser-Busch InBev NV |
| Carlsberg Group |
| Monster Beverage Corporation |
| The Coca-Cola Company |
| Diageo PLC |
| Tiger Brands Ltd |
| PepsiCo Inc. |
| Others |
Value Network & Pricing Analysis
The N3 freight corridor connecting Johannesburg to Durban anchors beverage logistics economics, with fuel surcharge volatility cascading through Gauteng distribution clusters and forcing tiered price differentiation between metropolitan and coastal catchments.
Pricing Analysis
The Department of Health's Health Promotion Levy dictates the pricing tier structure across carbonated and juice portfolios, compressing margins on legacy formulations while creating competitive room for reduced-sugar alternatives. Three-tier pricing structure across premium, standard, and economy levels separates reformulated stevia-blend SKUs from mid-tier cane-sugar variants and entry-level private-label alternatives. Cost compression in economy juice segments is intensifying because maize and cane sugar input volatility squeezes brands with limited pricing power. Township spaza shop operators exhibit highest price sensitivity, while hospitality procurement managers in Johannesburg and Cape Town hotels demonstrate lowest elasticity due to guest expectation lock-in.
Supply Chain Analysis
Single-source vulnerability in Johannesburg logistics hubs dominates supply chain risk assessment, with Gauteng province processing the majority of national beverage volume through concentrated bottling and distribution infrastructure. Manufacturing capacity draws from Western Cape fermentation corridors, KwaZulu-Natal carbonation facilities, and Eastern Cape packaging investments. Raw material dependencies center on cane sugar from KwaZulu-Natal agricultural zones, imported stevia extract from China, and PET resin from Saudi petrochemical suppliers. Distribution runs through supermarket central depots, spaza shop wholesale networks, and direct-to-consumer subscription platforms in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation chemistry expertise and last-mile route-to-market integration represent the scarcest capabilities in South African beverages, with manufacturers competing for talent pools that bridge food science and digital distribution analytics.
For Market Incumbents: Pre-empt margin erosion in carbonated portfolios by accelerating backward integration into stevia and monk fruit extract supply chains through strategic agricultural partnerships in Limpopo and Mpumalanga. Secure shelf positioning advantages by achieving National Regulator for Compulsory Specifications compliance ahead of enforcement timeline compression, while defending against Tiger Brands' price-accessible packaging incursions in township retail channels through volume-based spaza shop loyalty programs. For New Entrants and Emerging Players: Establish a beachhead in Eastern Cape and Limpopo informal retail networks where multinational route-to-market density remains underdeveloped and sachet-format distribution economics favor agile local operators. Target catering services and institutional procurement channels with bulk-format water and reduced-sugar juice offerings, leveraging direct e-commerce subscription models to bypass supermarket margin structures and capture health-conscious household replenishment cycles. For Investors and Strategic Acquirers: Regional bottlers with licensed multinational agreements and established distributor relationships in underserved provinces represent the most attractive acquisition archetype for portfolio diversification. Monitor National Treasury sugar tax amendment timelines and South African Bureau of Standards certification backlog durations as inflection indicators for reformulation investment urgency and competitive response lag. Long-term viability hinges on exposure to low-sugar variant pipelines and coastal production capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | Stevia-monk fruit blend development enables Health Promotion Levy tier migration and shelf priority in Gauteng retailers. |
| Route-to-Market Digitization | Spaza shop inventory visibility systems displace legacy distributor relationships and fragment demand data capture. |
| Coastal Capacity Expansion | Western Cape and KwaZulu-Natal bottling investments reduce Gauteng logistics concentration risk and support export positioning. |
| E-Commerce Subscription Launch | Direct-to-consumer bulk delivery captures planned replenishment outside supermarket margin structures in urban corridors. |
| Regulatory Pre-Compliance | Early National Regulator for Compulsory Specifications labeling investment secures competitive shelf positioning advantages. |
Research Methodology
A standing panel of beverage brand managers, category buyers at supermarket chains, spaza shop wholesale distributors, and Department of Health regulatory affairs officers provided ongoing calibration across primary interview cycles. Secondary validation drew from National Treasury excise revenue disclosures, South African Bureau of Standards certification databases, Nielsen retail audit data, and customs import records for alternative sweetener shipments. Bottom-up volume modeling across distribution channels triangulated against top-down category expenditure estimates from National Accounts data.
Scenario-bracketing around sugar tax enforcement intensity and reformulation cost trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and packaging size tier, with provincial regulatory enforcement variation treated as a cross-cutting modifier. CAGRs derived from elasticity-adjusted volume projections and price pass-through assumptions, incorporating input cost volatility indices for cane sugar and maize.
Sensitivities concentrate around Health Promotion Levy tier adjustments, alternative sweetener taste-profile acceptance rates, and informal retail channel penetration speed in Eastern Cape and Limpopo. Forecasts reflect documented assumptions regarding regulatory timeline adherence and manufacturer reformulation investment capacity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
White Wine Market