
 Hydroelectricity Market | 2026-2036
Hydroelectricity Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroelectricity Market Analysis
Brazil is rewriting the competitive map for large-scale hydroelectric development, with state-level auctions in Pará and Amazonas driving turbine procurement cycles. Siemens Energy AG leverages its Francis turbine manufacturing depth to anchor contracts across South American utilities. ANDRITZ AG competes through pumped storage integration capabilities that sustain project margins in alpine European markets. Voith GmbH & Co. KGaA dominates the Kaplan turbine segment, where variable-blade designs position the firm for run-of-river expansion in Southeast Asian river basins.
Hydroelectricity denotes electricity generated from gravitational force of falling or flowing water, typically through penstock-fed turbines operating at head pressures from 5 meters to over 1,000 meters and rotational speeds calibrated to generator synchronization requirements. The technology serves baseload power generation, grid stabilization, and seasonal energy storage for integrated electricity networks. Pumped storage installations command the largest capital allocation pools due to their dual-mode generation and load-balancing function for renewable-heavy grids. Run-of-river capacity leads in annual commissioning volume across emerging markets where environmental licensing constraints limit reservoir development. Micro hydropower occupies a niche but defensible margin tier in distributed rural electrification programs where transmission extension proves uneconomical.
China's MIIT enforces GB turbine efficiency standards that dictate minimum performance thresholds for domestic and imported equipment, while Brazil's national electric energy regulator structures auction timelines that directly shape developer procurement calendars. The EPA and FERC in the United States coordinate on environmental review timelines that constrain licensing duration for new reservoir projects. Stakeholders must monitor how evolving carbon accounting rules under the EU Green Deal reshape the eligibility of existing hydroelectric assets for green financing classifications.
Market Dynamics
Grid operators in renewable-heavy electricity systems are prioritizing pumped storage capacity to manage intermittency from wind and solar assets. This structural pull toward storage-integrated hydroelectric infrastructure is reshaping equipment procurement specifications and project financing structures.
Growth Catalysts
- MIIT dual carbon targets:China's GB turbine efficiency standards mandate performance upgrades across domestic and imported equipment, forcing modernization of aging infrastructure.
- Brazilian state auctions:Pará and Amazonas procurement cycles for reservoir capacity are accelerating capital deployment into large-scale turbine installations.
- Run-of-river expansion:Southeast Asian utilities are scaling grid-connected installations in river basins where environmental licensing constrains dam construction.
Market Restraints
- Steel and copper input volatility:Turbine manufacturing faces margin compression from commodity price swings in critical alloys and conductive materials.
- Environmental licensing friction:EPA and FERC coordination in the United States extends review timelines for new reservoir projects beyond developer risk thresholds.
- Grid-scale battery substitution:Lithium-ion storage systems compete for frequency regulation contracts that historically favored pumped hydro.
Strategic Opportunities
- Alpine pumped storage retrofit:European utilities are upgrading existing reservoirs with reversible turbine technology to capture arbitrage from renewable intermittency.
- Micro-hydropower rural electrification:Distributed sub-100kW installations serve unelectrified communities where transmission extension proves uneconomical.
- EU Green Deal carbon accounting:Evolving eligibility rules for green financing classifications create refinancing windows for certified low-impact hydroelectric assets.
Industry Challenges
- Specialized welding and machining talent:Francis and Kaplan turbine blade fabrication requires skilled labor pools concentrated in aging European and Japanese industrial regions.
- Legacy grid synchronization:Variable-speed generator integration with existing 50Hz/60Hz infrastructure demands custom control system engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroelectricity Market |
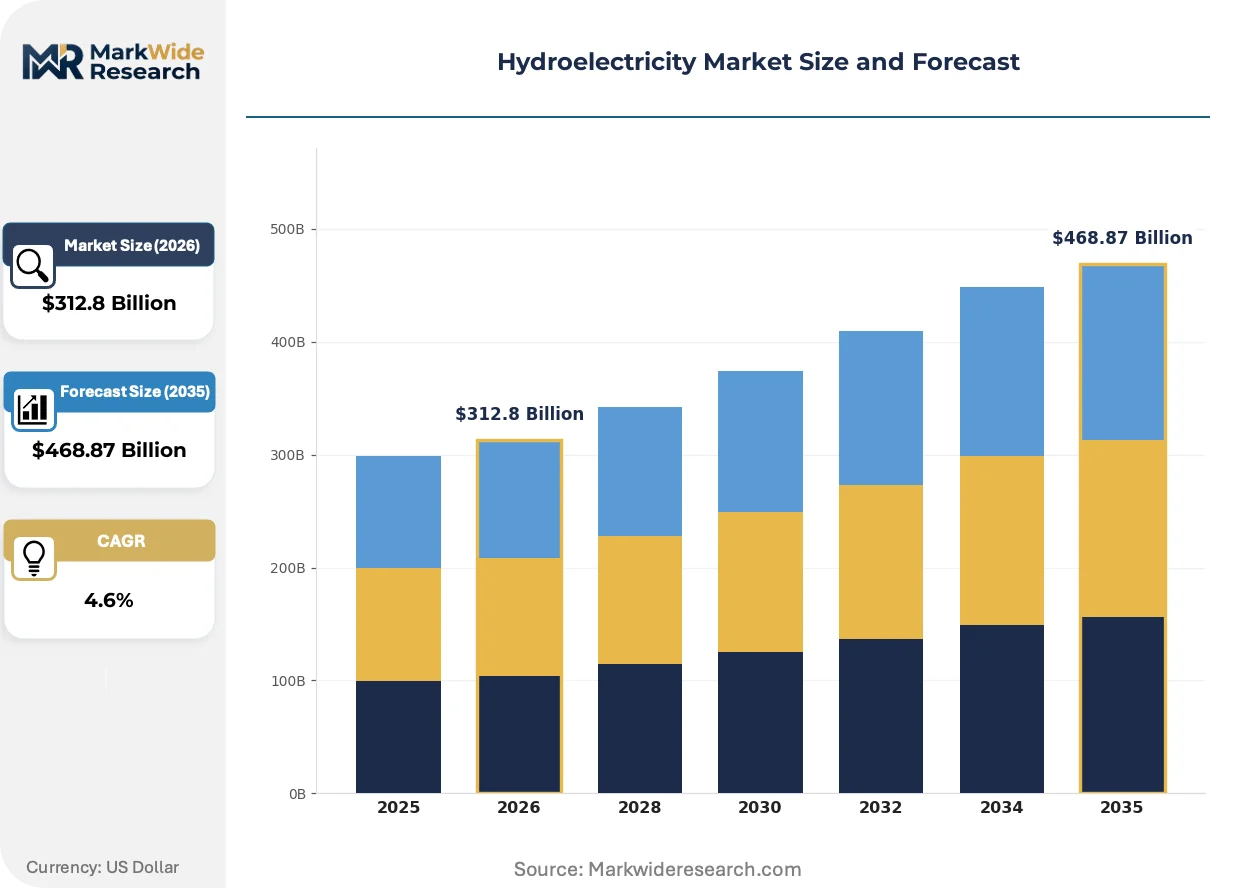
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $468.87 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Plant Type: Run-of-River, Pumped Storage, Reservoir, Micro Hydropower End User: Utilities, Industrial, Commercial, Residential Installation Type: Onshore, Offshore, Hybrid, Distributed Technology: Synchronous Generators, Kaplan Turbines, Francis Turbines, Pelton Wheels |
| Companies Covered | Siemens Energy AG, ANDRITZ AG, Voith GmbH & Co. KGaA, China Three Gorges Corporation, General Electric, Statkraft Sweden, ABB Ltd., Tata Power, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroelectricity Market Emerging Trajectories
Digital twin technology is penetrating hydroelectric asset management, compressing maintenance cycles and enabling predictive intervention before mechanical failure. This virtualization of physical infrastructure is redrawing competitive boundaries between equipment OEMs and software platforms.
Sensor-integrated turbine monitoring is virtualizing traditional inspection regimes. Brazilian and Chinese utilities are deploying vibration analysis and cavitation detection systems across aging Francis turbine fleets. Equipment suppliers now bundle predictive maintenance software with hardware contracts, capturing recurring revenue streams that previously flowed to third-party service providers.
The EU Green Deal's carbon accounting rules are tightening disclosure requirements for hydroelectric operators. Project developers must now document reservoir methane emissions and sediment disruption impacts to qualify for green bond classifications. European investment funds are screening existing hydroelectric portfolios against these standards, diverting capital toward run-of-river and pumped storage assets with lower environmental intensity.
Power purchase agreement structures are fragmenting across Southeast Asian markets. State-owned utilities in Vietnam and Indonesia are unbundling long-term offtake contracts into shorter tenors with indexed pricing, transferring volume risk to developers. Independent power producers are responding by securing equipment supply agreements with flexible delivery schedules that align with uncertain commissioning timelines.
Hydroelectricity Market Segmentation
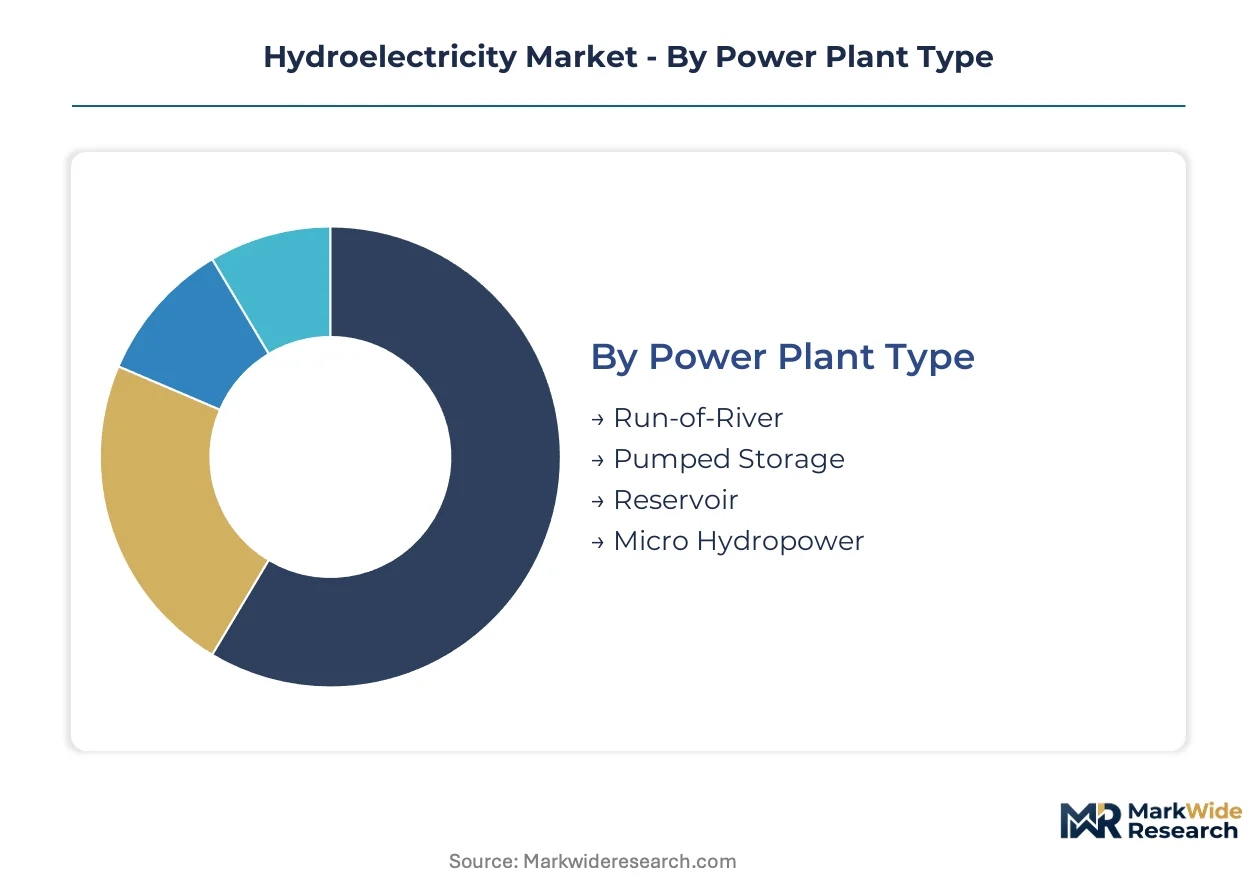
Hydroelectricity market segmentation reflects divergent capital intensity profiles and operational flexibility requirements across infrastructure classes. Equipment specifications, financing structures, and regulatory exposure vary sharply between mature reservoir technologies and emerging distributed configurations.
Power Plant Type:
Mature baseload technologies dominate installed capacity, while emerging configurations address grid modernization and environmental constraints.
- Run-of-River:Generation infrastructure channels natural river flow through diversion weirs without significant impoundment, limiting reservoir methane emissions. Southeast Asian utilities in Vietnam and Indonesia are scaling grid-connected installations where environmental licensing restricts dam construction.
- Pumped Storage:Dual-mode facilities pump water to upper reservoirs during low-demand periods and release it through reversible turbines during peak load. European utilities in Switzerland and Austria are retrofitting alpine installations to capture arbitrage from renewable intermittency.
- Reservoir:Large-scale impoundment systems with multi-gigawatt capacity serve seasonal storage and flood control functions. Brazilian state auctions in Pará and Amazonas are accelerating procurement cycles for turbine installations.
- Micro Hydropower:Sub-100kW distributed units serve rural electrification programs where transmission extension proves uneconomical. India's Ministry of New and Renewable Energy targets village-level deployment across Himalayan foothill states.
Reservoir capacity retains volume leadership; micro hydropower holds the steepest expansion curve.
End User:
Customer concentration follows grid access patterns and power purchase agreement structures across deregulated and regulated electricity markets.
- Utilities:Vertically integrated state-owned and private grid operators procure multi-megawatt installations under long-term offtake contracts. China's State Grid Corporation anchors equipment demand through MIIT-mandated efficiency upgrades.
- Industrial:Energy-intensive manufacturing facilities deploy captive hydroelectric capacity to secure price-stable baseload power. Aluminum smelters in Iceland and Norway leverage glacial runoff-fed turbines for process electrification.
- Commercial:Corporate power purchase agreements drive smaller-scale run-of-river development. Technology firms in Oregon and Washington contract directly with independent hydroelectric producers.
- Residential:Individual property owners install micro-turbine systems for off-grid or net-metered generation. Rural property holders in British Columbia and New Zealand exploit stream access rights for distributed supply.
Utilities command installed capacity; industrial offtake is expanding most quickly.
Installation Type:
Physical siting configurations reflect topography constraints, transmission proximity, and hybrid technology integration opportunities.
- Onshore:Conventional land-based turbine halls and penstock infrastructure account for the overwhelming majority of operating capacity. China's Three Gorges Dam anchors the global onshore installed base.
- Offshore:Tidal barrage and marine current turbine installations exploit coastal hydrology with minimal land use conflicts. South Korea's Sihwa Lake Tidal Power Station demonstrates commercial-scale deployment.
- Hybrid:Co-located hydroelectric and solar photovoltaic systems share transmission infrastructure and optimize capacity factor. Portugal's Alqueva reservoir hosts floating solar arrays above pumped storage operations.
- Distributed:Modular turbine packages enable rapid deployment across multiple small-scale sites without centralized control. Nepal's rural electrification programs aggregate village-level micro-hydro clusters.
Onshore retains volume leadership; hybrid configurations gain share fastest.
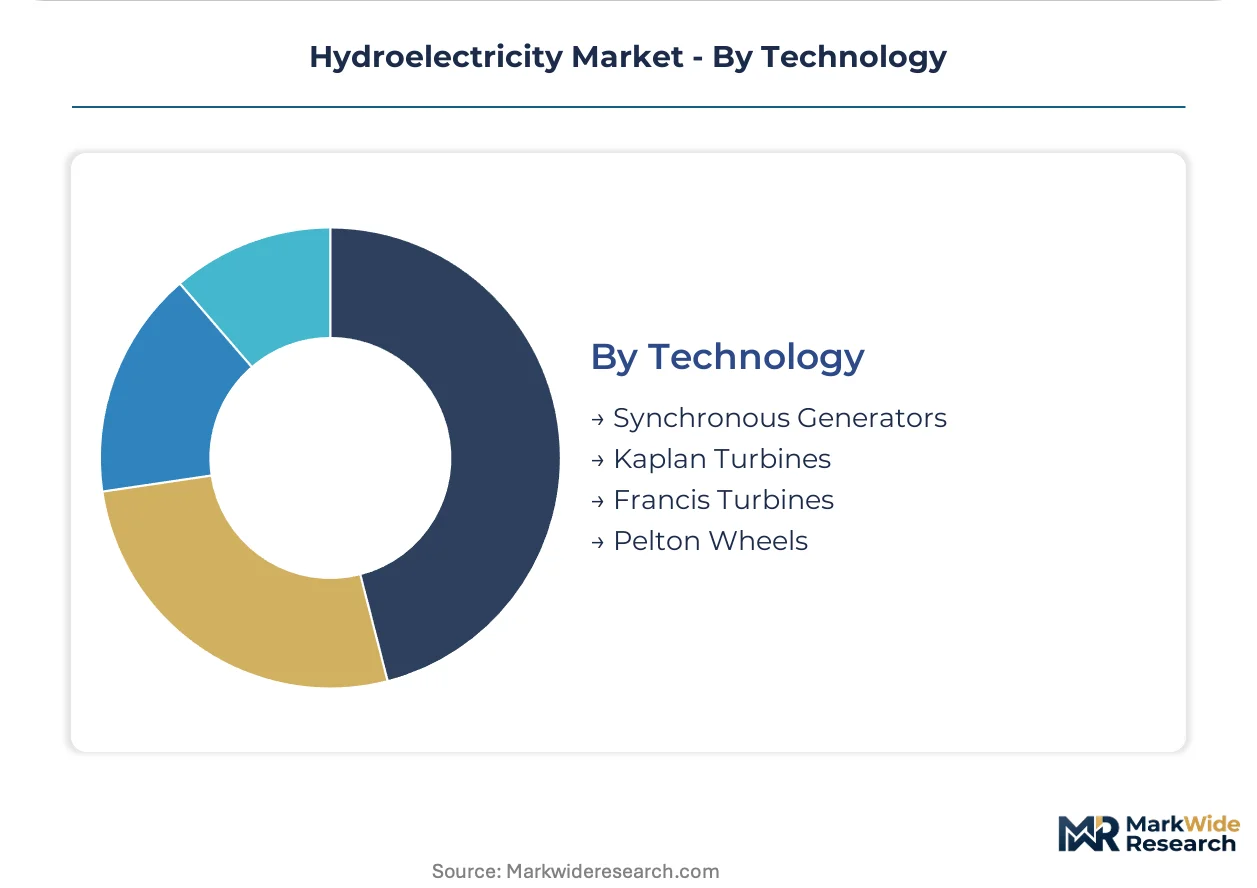
Technology:
Prime mover selection depends on head pressure, flow variability, and grid synchronization requirements across hydrological conditions.
- Synchronous Generators:Conventional wound-rotor machines maintain grid frequency through direct mechanical coupling, requiring precise turbine speed control. Aging European fleets face GB standards-equivalent modernization mandates.
- Kaplan Turbines:Variable-blade propeller designs optimize efficiency across wide flow ranges in low-head river installations. Voith GmbH manufacturing depth anchors contracts for Southeast Asian run-of-river expansion.
- Francis Turbines:Reaction-type runners operate efficiently across medium-head applications from 20 to 700 meters. Brazilian northern hydrology corridor procurement concentrates demand for high-capacity units.
- Pelton Wheels:Impulse turbines extract energy from high-velocity jets in high-head, low-flow alpine environments. Swiss and Austrian pumped storage retrofits specify Pelton configurations for reversible operation.
Francis turbines retain volume leadership; synchronous generator replacements show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon targets in China are tightening GB turbine efficiency standards, forcing equipment upgrades across the world's largest hydroelectric installed base. State-level procurement cycles in Brazil and environmental licensing constraints in Southeast Asia are redrawing regional investment patterns.
China
State Grid Corporation anchors equipment demand through MIIT-mandated modernization of aging Francis turbine fleets. The GB standards for turbine efficiency dictate minimum performance thresholds for both domestic and imported equipment. Yangtze River Delta manufacturers are scaling production of reversible turbine technology for pumped storage retrofits.
Brazil
Pará and Amazonas state auctions for reservoir capacity are accelerating capital deployment into large-scale turbine installations. ANEEL structures procurement timelines that directly shape developer equipment calendars. The northern hydrology corridor concentrates demand for high-capacity Francis units from international OEMs.
United States
FERC coordinates with EPA on environmental review timelines that constrain licensing duration for new reservoir projects beyond developer risk thresholds. Pacific Northwest utilities are retrofitting existing installations with digital twin monitoring systems. Alaska and Mountain West micro-hydropower programs target rural electrification gaps.
Switzerland
Alpine utilities are capturing arbitrage from renewable intermittency through pumped storage retrofits with reversible Pelton turbine configurations. The EU Green Deal carbon accounting rules tighten disclosure requirements for reservoir methane emissions. Swiss manufacturing clusters supply precision-machined turbine components to European retrofit programs.
Vietnam
EVN is scaling grid-connected run-of-river installations in Mekong Delta river basins where environmental licensing restricts dam construction. Shorter-tenor power purchase agreements with indexed pricing transfer volume risk to independent power producers. Central Highlands provinces concentrate village-level micro-hydropower deployment.
Hydroelectricity Market Vendor Landscape
Integrated turbine manufacturers and specialized component fabricators split the market along capital intensity and customization vectors. The structure consolidates around three tiers: full-service OEMs with manufacturing depth, regional equipment assemblers, and precision component specialists. Strategic moves concentrate on technology licensing partnerships and backward integration into critical alloy supply chains.
Within the full-service OEM tier, Siemens Energy AG, ANDRITZ AG, and Voith GmbH & Co. KGaA exemplify divergent specialization patterns. Siemens Energy AG represents the integrated European archetype with manufacturing depth across reaction turbine categories. ANDRITZ AG occupies a position emphasizing pumped storage integration capabilities. Voith GmbH & Co. KGaA anchors the variable-blade propeller segment for low-head river applications. Chinese state-owned entities including China Three Gorges Corporation sit within the scale-driven end, leveraging domestic project pipelines to capture equipment procurement cycles.
| Leading Market Players |
|---|
| Siemens Energy AG |
| ANDRITZ AG |
| Voith GmbH & Co. KGaA |
| China Three Gorges Corporation |
| General Electric |
| Statkraft Sweden |
| ABB Ltd. |
| Tata Power |
| Alfa Laval |
| Others |
Supply Flow & Price Mechanics
Yangtze River freight corridors carry precision-machined turbine components from Chinese manufacturing clusters to Southeast Asian project sites, where logistics costs compound with steel and copper alloy volatility to widen spreads between European OEM-delivered equipment and regional assembler pricing. This transport-cost wedge feeds downstream price differentiation between premium Francis turbine packages and standard Kaplan configurations.
Pricing Analysis
Geographic price spreads between European-manufactured Francis turbines and Chinese-assembled Kaplan units reach multiples of landed cost once Yangtze-to-Mekong logistics and import duties layer onto base equipment pricing. Project-based long-term offtake contracts dominate utility procurement, with price differentiation driven by GB standards certification tier and after-sales service bundling. Cost compression in the standard-equipment tier intensifies because Brazilian state auctions compress developer margins and force equipment suppliers to absorb steel input volatility. Industrial aluminum smelters in Iceland and Norway show least price sensitivity due to captive hydroelectric integration, while Southeast Asian independent power producers operate at highest bid sensitivity.
Supply Chain Analysis
Export-control regimes under EU dual-use technology restrictions limit flows of precision turbine blade machining equipment to non-OEM assemblers, concentrating advanced manufacturing capability in Germany, Austria, and Switzerland. Supply draws from Chinese steel forging clusters, Japanese specialty alloy producers, and Swiss precision-machining centers. Raw material dependencies include high-grade stainless steel forgings, copper windings, and rare-earth magnetic components. Single-source vulnerability concentrates in European precision-machining talent pools for Francis runner fabrication. Distribution runs through EPC contractor-led procurement with utility direct-negotiation bypass for mega-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
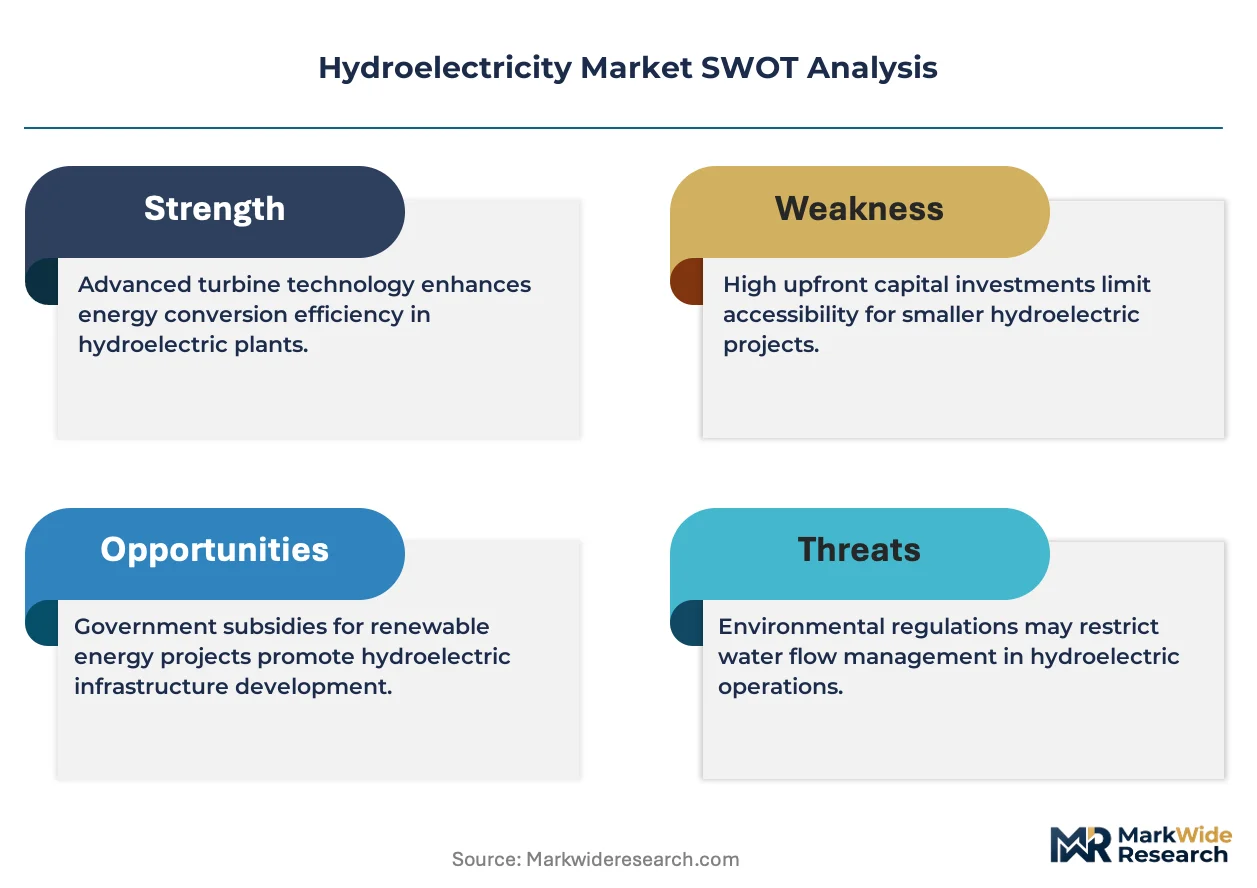
Hydroelectric infrastructure operates as a defensive-moat market where regulatory entrenchment through environmental licensing and grid interconnection agreements creates durable incumbent positions against battery storage substitution threats.
For Market Incumbents: Entrench market position through backward integration into specialty steel forging capacity in Yangtze River Delta manufacturing zones, insulating margins from alloy price volatility that compresses project returns. Deepen digital twin software bundling with hardware contracts to capture recurring maintenance revenue streams threatened by third-party predictive analytics platforms. Prioritize certification investment under evolving EU Green Deal carbon accounting rules to defend green financing eligibility against run-of-river competitors. For New Entrants and Emerging Players: Establish a beachhead in micro-hydropower rural electrification programs across Himalayan foothill states and Central Highlands Vietnam, where transmission extension economics favor distributed sub-100kW installations over grid-connected mega-projects. Target village-level deployment clusters in Nepal and Indonesia where state-owned utility procurement fragmentation opens direct contracting channels. Pursue technology licensing partnerships with European precision-machining specialists to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded hydroelectric equipment divisions lacking digital service capabilities. Long-term viability centers on pumped storage retrofit demand from renewable-heavy grids requiring frequency regulation assets. Watch for inflection in FERC environmental review timeline compression that would unlock reservoir project licensing velocity in the United States Pacific Northwest.| Strategic Initiative | Industry Significance |
|---|---|
| Pumped Storage Retrofit | European alpine utilities capture arbitrage from renewable intermittency through reversible turbine upgrades. |
| Digital Twin Integration | Equipment OEMs bundle predictive maintenance software to displace third-party service provider revenue. |
| GB Standards Certification | MIIT-mandated efficiency upgrades force modernization of aging Francis turbine fleets across China. |
| Micro-Hydropower Deployment | Village-level installations serve unelectrified communities where transmission extension proves uneconomical. |
| Backward Integration | Turbine manufacturers secure captive supply of specialty steel forgings to insulate margins from commodity volatility. |
Methodological Framework
The analysis maps run-of-river, pumped storage, reservoir, and micro-hydropower sub-sectors, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up equipment procurement tracking triangulates against top-down national capacity forecasts.
Assumptions held fixed include MIIT dual carbon target enforcement timelines, Brazilian ANEEL auction structures, and EU Green Deal carbon accounting rule implementation; variables stress-tested across steel and copper price bands, environmental licensing duration, and grid-scale battery cost curves. Segmentation dimensions modeled span power plant type, end user archetype, installation configuration, and prime mover technology across the projection horizon. CAGRs derive from equipment procurement cycle analysis and project commissioning velocity.
Stress conditions across commodity input costs, regulatory review timelines, and renewable substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology cost trajectories and policy continuity. Material shifts in FERC environmental coordination protocols or MIIT GB standards enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
United States Hydropower Market