
 Indonesia ICT Market | 2026-2036
Indonesia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia ICT Market Foresight
Modular service bundling is recalibrating how Indonesian enterprises consume ICT infrastructure. PT Telekomunikasi Indonesia Tbk (Telkomsigma) leverages its nationwide fiber backbone to dominate enterprise connectivity contracts. Alibaba Cloud anchors its position through localized data center investments in Jakarta and Batam. Microsoft differentiates by embedding productivity suites into government digitalization programs.
Information and communications technology encompasses computing hardware, software applications, network infrastructure, and cloud-based service delivery systems operating through packet-switched data protocols with latency thresholds below 50 milliseconds for enterprise-grade connectivity. Its primary purpose centers on enabling data transmission, storage, processing, and analytics across organizational boundaries. Cloud Services currently absorbs the largest share of new capital allocation as enterprises migrate from on-premise servers. Cybersecurity commands premium pricing due to Indonesia's escalating threat surface and BSI certification requirements. Hardware maintains steady replacement cycles in education and healthcare verticals where legacy device depreciation schedules govern refresh timing.
Indonesia's Ministry of Communication and Informatics, the National Cyber and Crypto Agency, and BSI standards collectively enforce data localization mandates and security certification protocols that filter market access for foreign platform providers. These frameworks elevate compliance costs for unlicensed operators while creating protected demand channels for certified domestic resellers. Stakeholders must monitor evolving BSI cloud security certification tiers and their implications for cross-border service architectures.
Market Dynamics
Enterprise migration from on-premise servers to cloud infrastructure is compressing procurement cycles and forcing legacy hardware distributors to reinvent service delivery models around subscription-based consumption.
Growth Catalysts
- Kominfo Digital Transformation Mandates:Government directives require state-owned enterprises to modernize IT infrastructure, creating protected demand channels for certified domestic providers.
- SME Cloud Adoption:Small and medium enterprises across Java are abandoning capital-intensive server ownership for operational expenditure models that preserve working capital.
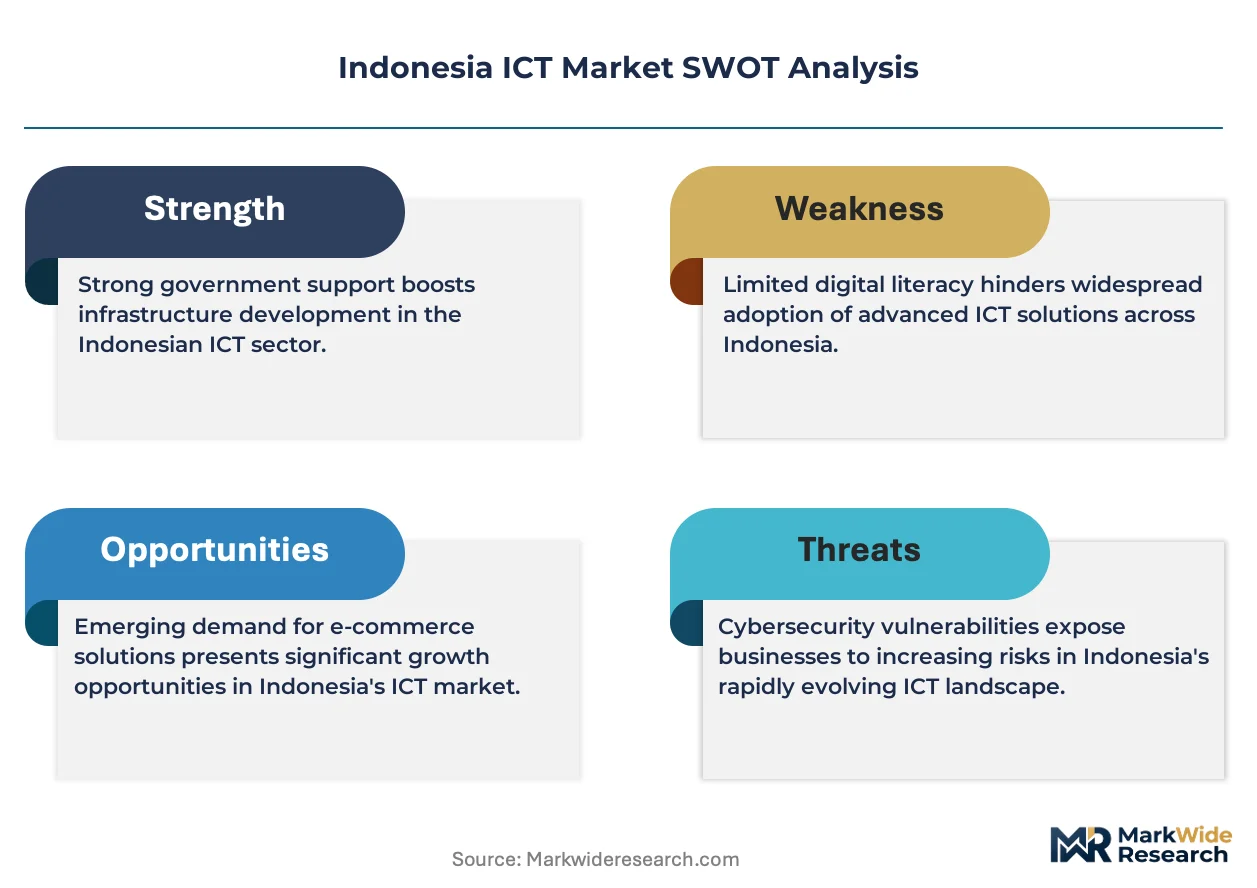
- BSI Certification Requirements:Mandatory security standards for critical infrastructure operators are elevating compliance spending and filtering market access toward qualified vendors.
Market Restraints
- Data Localization Compliance Costs:Foreign platform providers face elevated capital requirements to establish certified in-country data centers meeting Kominfo sovereignty rules.
- Java-Centric Supply Concentration:Fiber backbone and data center capacity concentrates in the Greater Jakarta corridor, leaving outer islands with higher latency and limited redundancy.
- Skilled Cybersecurity Talent Scarcity:Shortage of BSI-certified security architects constrains enterprise ability to implement and maintain compliant architectures.
Strategic Opportunities
- Outer Island Infrastructure Gap:Sumatra, Sulawesi, and Papua present underpenetrated markets where localized edge computing investments could capture first-mover positioning.
- Converged AI-Cloud Services:Integration of machine learning inference with existing cloud workloads opens new revenue streams for providers offering bundled analytics platforms.
- Healthcare Digitalization Wave:Ministry of Health electronic medical record mandates are driving replacement cycles in hospital IT systems previously governed by decade-long depreciation schedules.
Industry Challenges
- Multi-Cloud Integration Complexity:Enterprises adopting services from multiple hyperscalers face operational friction harmonizing identity management and data governance across disparate environments.
- Certification Timeline Compression:BSI security certification processes lag behind product release cycles, delaying market entry for innovative solutions.
- Legacy System Interoperability:Banking and government verticals maintain decades-old core systems that resist API-based connectivity with modern cloud architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia ICT Market |
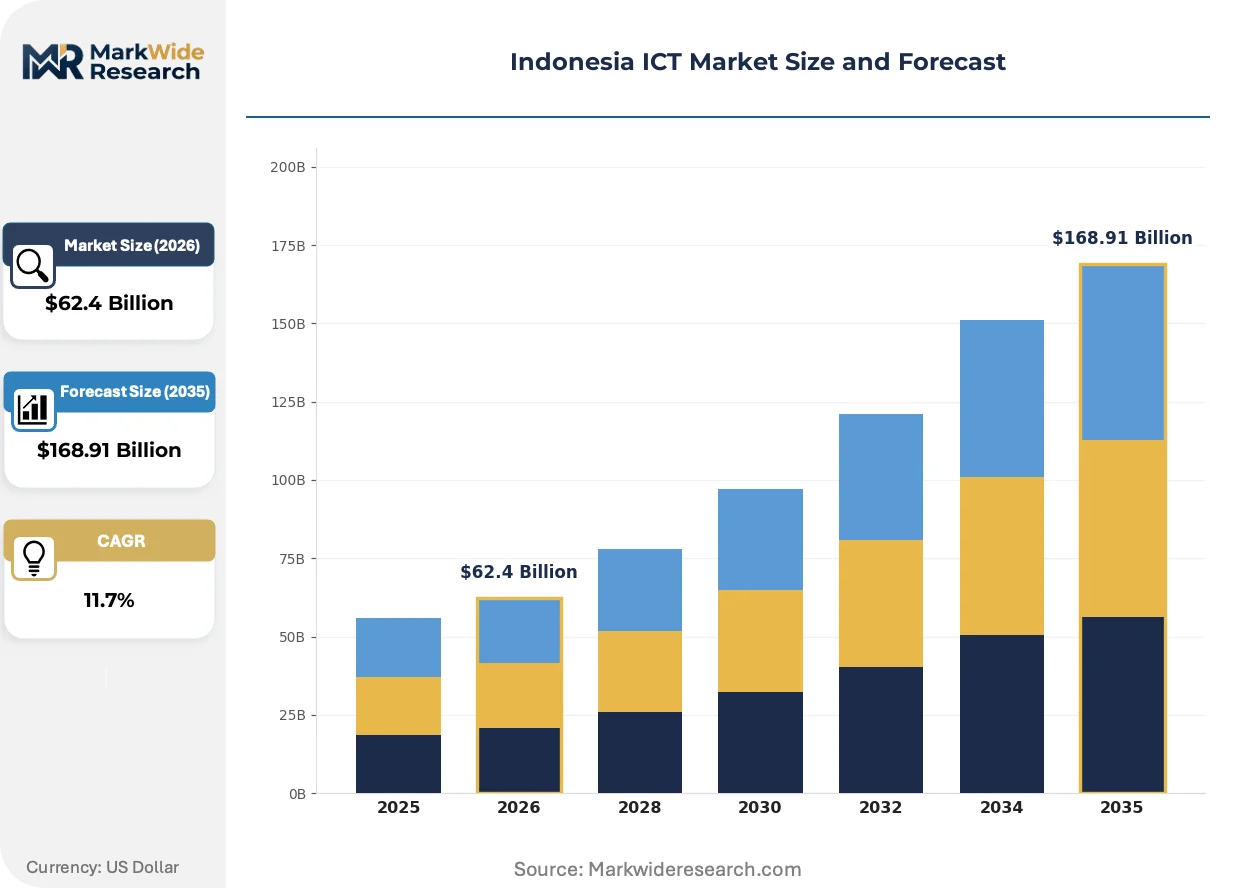
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $168.91 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
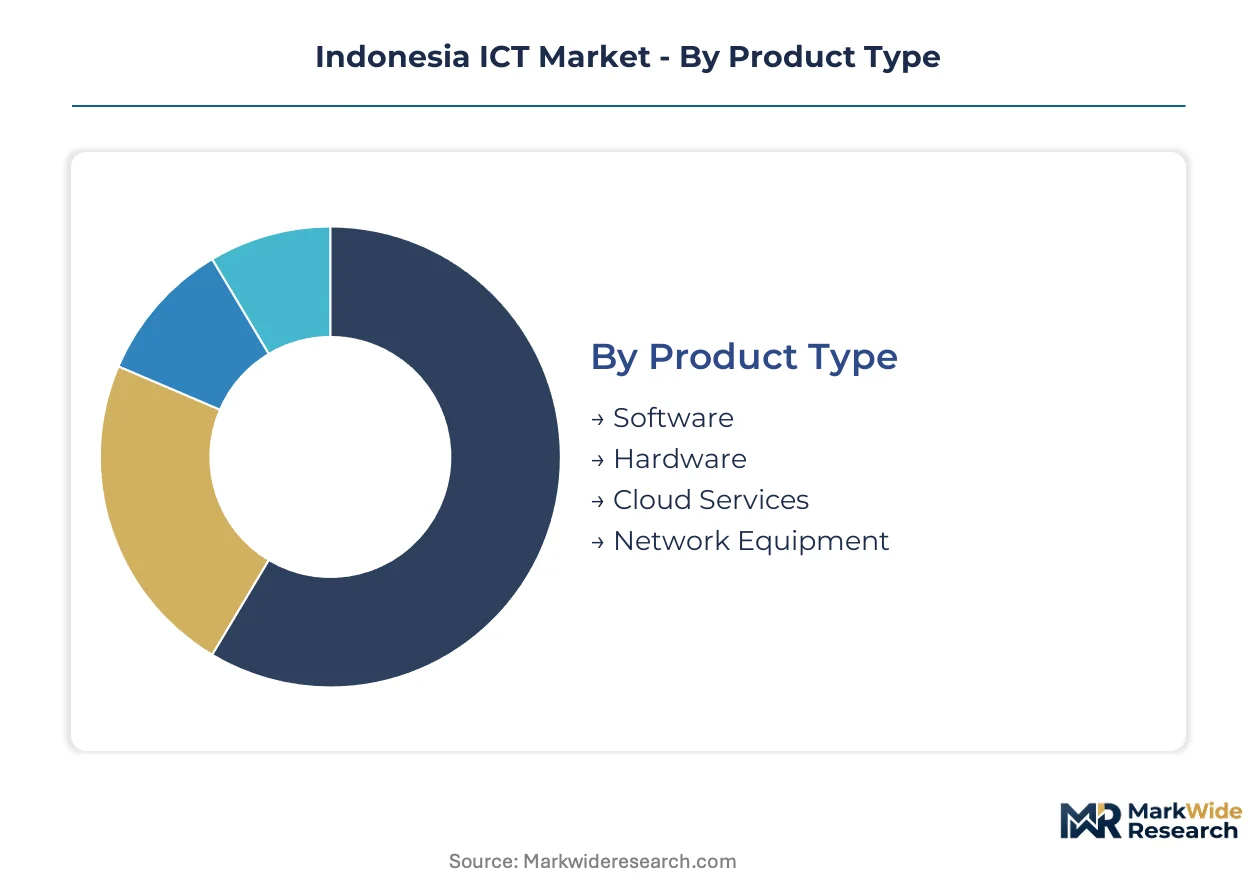
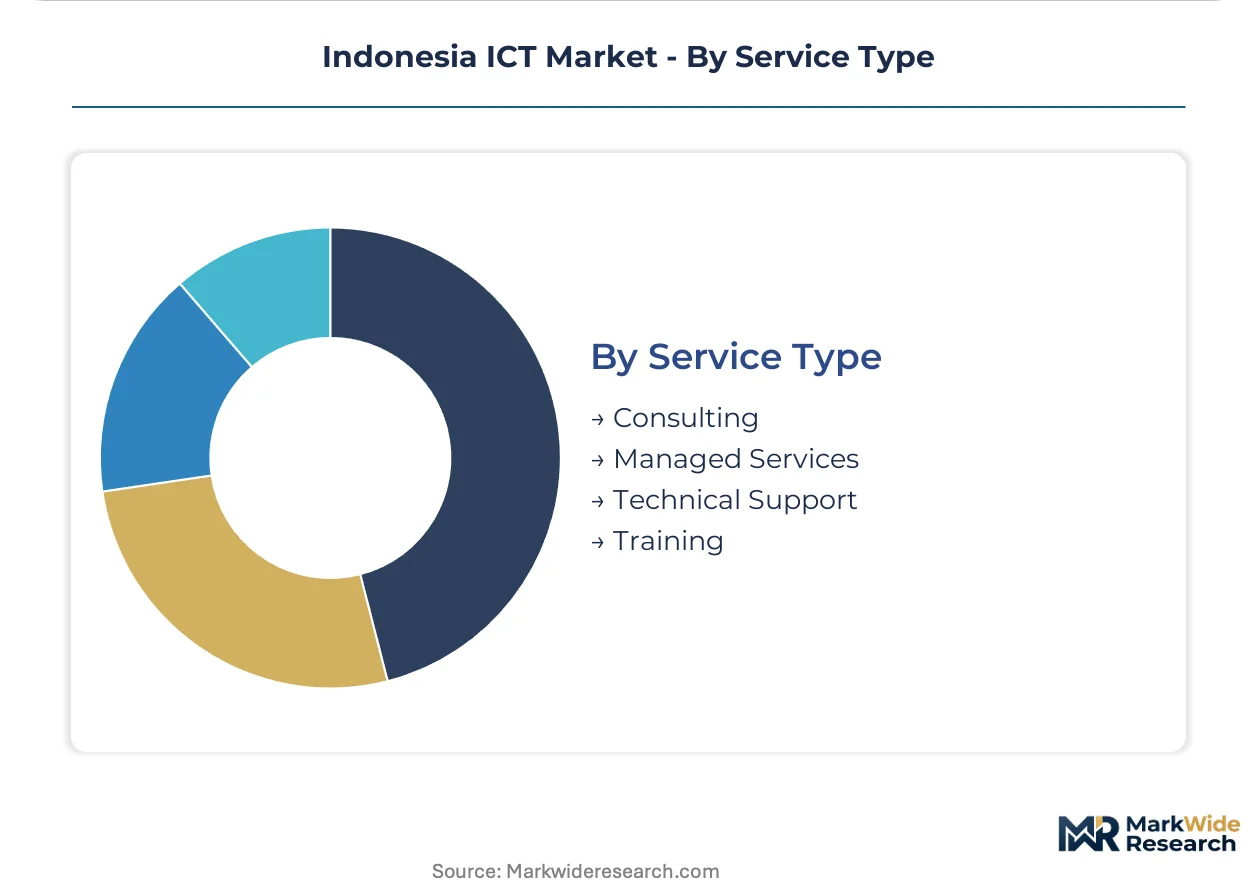
| Segmentation | Product Type: Software, Hardware, Cloud Services, Network Equipment Application: Enterprise Solutions, Cybersecurity, Data Analytics, Content Management End User: SMEs, Government, Healthcare, Education Service Type: Consulting, Managed Services, Technical Support, Training |
| Companies Covered | PT Metrodata Electronics Tbk, Alibaba Cloud, PT Telekomunikasi Indonesia Tbk (Telkomsigma), PT Majapahit Teknologi Nusantara, Microsoft, PT Multipolar Technology Tbk, PT Phintraco Technology, Closeloop Technologies, PT Mitra Integrasi Informatika, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia ICT Market Shifts & Advancements
Artificial intelligence integration is rewriting service delivery expectations across Indonesian enterprise software, while regulatory frameworks accelerate the formalization of previously informal IT procurement practices.
Generative AI copilots embedded within enterprise productivity suites are automating routine documentation, code generation, and customer interaction workflows. Mid-sized professional services firms in Jakarta and Surabaya are deploying these tools at scale, compressing project delivery timelines and reducing headcount growth in administrative functions. The technology is automating tasks previously requiring dedicated junior staff, reshaping hiring patterns across legal, accounting, and consulting verticals.
Kominfo's implementing regulations on Private Scope Electronic System Operators are mandating incident reporting, data breach notifications, and mandatory security audits for critical infrastructure providers. These rules impose operational burdens on foreign cloud operators while creating compliance service opportunities for domestic cybersecurity consultancies. Financial services and telecommunications verticals face the steepest compliance ramps, with Q3 2024 marking the first enforcement window for tier-one operators.
Consumption-based licensing models are displacing perpetual software ownership across Indonesian enterprise procurement. State-owned enterprises and regional government agencies, previously locked into multi-year capital budgets, now favor monthly operational expenditure arrangements that align costs with actual utilization. This behavioral shift is most pronounced in the education vertical, where ministry funding volatility makes subscription predictability preferable to large upfront outlays.
Indonesia ICT Market Segmentation
Indonesia's ICT procurement patterns fragment sharply across organizational maturity, regulatory exposure, and infrastructure legacy. Understanding these fault lines clarifies where subscription models displace capital expenditure and which verticals drive compliance-premium capture.
Product Type:
Supply concentration in fiber backbone and data center capacity shapes how product categories reach end users across the archipelago.
- Cloud Services:Distributed computing resources delivered through hyperscaler platforms with localized Jakarta and Batam data centers. Banking and telecommunications operators in Greater Jakarta dominate consumption as BSI certification mandates filter procurement toward certified domestic resellers with established sovereign infrastructure.
- Software:Enterprise applications spanning ERP, productivity suites, and vertical-specific platforms operating on subscription licensing models. State-owned enterprises favor monthly operational expenditure arrangements that align costs with utilization rather than multi-year capital commitments.
- Hardware:Physical computing equipment including servers, storage arrays, and endpoint devices subject to depreciation schedules. Education and healthcare verticals govern replacement timing through decade-long depreciation cycles that resist cloud migration pressure.
- Network Equipment:Routing, switching, and wireless infrastructure enabling packet-switched connectivity with latency thresholds below 50 milliseconds. Deployment concentrates in Java where fiber density supports enterprise-grade service level agreements.
Cloud Services absorbs the bulk of installed capacity; Network Equipment is expanding most quickly as outer island connectivity gaps close.
Application:
Cost tier differentiation separates compliance-heavy deployments from discretionary productivity investments.
- Cybersecurity:Threat detection, identity management, and incident response systems mandated by Kominfo for critical infrastructure operators. Financial services and telecommunications verticals face the steepest compliance ramps with mandatory security audits and breach notification protocols.
- Enterprise Solutions:Integrated platforms spanning collaboration, resource planning, and workflow automation. Mid-sized professional services firms in Jakarta and Surabaya deploy generative AI copilots at scale to compress project delivery timelines.
- Data Analytics:Business intelligence and machine learning inference tools processing operational and customer data. Integration with existing cloud workloads opens revenue streams for providers offering bundled analytics platforms.
- Content Management:Document repositories, digital asset platforms, and web content systems for regulated industries. Government agencies prioritize solutions with localized data residency to satisfy sovereignty requirements.
Cybersecurity commands premium pricing; Data Analytics is gaining share fastest as AI-cloud convergence accelerates.
End User:
Customer type determines procurement flexibility and compliance burden intensity.
- Government:Central and regional agencies subject to Kominfo digital transformation mandates requiring modernization of legacy IT infrastructure. Procurement favors certified domestic providers with established relationships and sovereign data center presence.
- SMEs:Small and medium enterprises across Java abandoning capital-intensive server ownership for operational expenditure models. Subscription predictability preserves working capital amid funding volatility.
- Healthcare:Hospitals and clinics driven by Ministry of Health electronic medical record mandates into replacement cycles. Previously decade-long depreciation schedules now compress as regulatory deadlines force system upgrades.
- Education:Schools and universities with ministry funding volatility making subscription arrangements preferable to large upfront outlays. Perpetual software ownership is displacing fastest in this vertical.
Government absorbs the bulk of compliance-driven spending; Healthcare is climbing the fastest as EMR mandates override legacy depreciation schedules.
Service Type:
Margin structure varies with technical complexity and regulatory proximity.
- Managed Services:Ongoing infrastructure operation and maintenance outsourced to third-party providers. Shortage of BSI-certified security architects constrains enterprise ability to implement compliant architectures internally.
- Consulting:Advisory engagements spanning digital transformation strategy, cloud migration planning, and compliance readiness. Domestic cybersecurity consultancies capture opportunity as foreign operators face elevated operational burdens.
- Technical Support:Break-fix and maintenance services for hardware and software deployments. Response time requirements tighten for critical infrastructure operators under incident reporting mandates.
- Training:Skills development programs addressing certified security architect scarcity and cloud platform proficiency. BSI certification timeline compression creates persistent demand for accelerated credentialing pathways.
Managed Services captures the bulk of recurring revenue; Consulting is expanding most quickly as compliance complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's ICT production concentrates in Java while consumption spreads unevenly across the archipelago, creating infrastructure gaps that shape competitive entry strategies.
Java
Greater Jakarta anchors national data center capacity with hyperscaler investments from Alibaba Cloud and Microsoft. Kominfo's digital transformation mandates drive state-owned enterprise procurement toward certified domestic providers. Surabaya and Bandung form secondary clusters where SME cloud adoption accelerates fastest.
Sumatra
Medan and Palembang generate demand from plantation conglomerates and logistics operators seeking enterprise connectivity. Telkomsigma extends fiber backbone reach through submarine cable investments linking Batam to Singapore. Local data center scarcity forces latency-sensitive workloads toward Java-based facilities.
Sulawesi
Makassar serves as the eastern hub for nickel processing and fisheries export operations requiring industrial IoT infrastructure. Ministry of Communication and Informatics universal service obligations subsidize backbone extension to outer island corridors. Edge computing investments remain minimal due to demand fragmentation.
Kalimantan
Balikpapan and Samarinda support coal and palm oil headquarters with legacy on-premise systems resisting cloud migration. New capital city Nusantara construction creates greenfield opportunities for sovereign cloud architecture. BSI certification requirements filter vendor selection toward established domestic resellers.
Papua
Jayapura and Timika host mining operations with satellite-dependent connectivity and limited fiber redundancy. Resource extraction companies self-provision private networks due to commercial infrastructure absence. Kominfo's Palapa Ring program extends submarine fiber to Merauke, compressing latency for critical infrastructure operators.
Indonesia ICT Market Competitive Landscape
The competitive structure tilts toward state-affiliated infrastructure providers with fiber backbone control. Telkomsigma leverages nationwide connectivity assets to dominate enterprise contracts, while foreign hyperscalers compete through localized data center investments. Three archetypes define positioning: sovereign infrastructure incumbents, global cloud platforms with certified local presence, and domestic system integrators bridging compliance gaps. Consolidation pressure intensifies as certification requirements raise capital barriers, while partnerships between global technology vendors and domestic resellers accelerate market access.
Among domestic system integrators, PT Metrodata Electronics Tbk, PT Multipolar Technology Tbk, and PT Mitra Integrasi Informatika occupy positions linking foreign platforms to regulated enterprise buyers. These Jakarta-based entities exemplify the reseller archetype that captures value from BSI certification requirements and Kominfo procurement rules. Their positioning depends on maintaining credentialing velocity as security standards tighten.
| Leading Market Players |
|---|
| PT Metrodata Electronics Tbk |
| Alibaba Cloud |
| PT Telekomunikasi Indonesia Tbk (Telkomsigma) |
| PT Majapahit Teknologi Nusantara |
| Microsoft |
| PT Multipolar Technology Tbk |
| PT Phintraco Technology |
| Closeloop Technologies |
| PT Mitra Integrasi Informatika |
| Others |
Supply & Pricing Matrix
Sovereign-backed infrastructure providers with nationwide fiber backbone control anchor supply-side concentration, translating into pricing discipline that favors certified domestic resellers over foreign platform operators facing elevated compliance costs.
Pricing Analysis
Margin tightening in BSI-certified cloud services reflects the scarcity of qualified domestic resellers capable of meeting Kominfo data localization mandates. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-managed solutions from domestic partner-resold offerings from uncertified gray-market alternatives. Price differentiation hinges on certification grade and after-sales compliance support, with banking and telecommunications verticals showing lowest price sensitivity due to regulatory enforcement timelines. State-owned enterprises and regional government agencies exhibit highest price sensitivity as budget volatility forces operational expenditure preferences over capital commitments.
Supply Chain Analysis
Certified security architect shortages across Jakarta and Surabaya constrain implementation capacity for compliant enterprise architectures. Hardware supply draws from China, Taiwan, and South Korea for server components, networking equipment, and semiconductor inputs. Software licensing rests on Singapore and US-based hyperscaler platforms with localized Jakarta and Batam data center presence. Single-source vulnerability concentrates in submarine cable landing stations linking outer islands to Java backbone capacity. Distribution runs through Telkomsigma's enterprise connectivity contracts and domestic system integrator partnerships with government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure is displacing on-premise server ownership across Indonesian enterprise procurement, compressing legacy hardware replacement cycles and elevating subscription-based consumption models.
For Market Incumbents: Cement fiber backbone dominance through edge computing investments in Sumatra and Sulawesi before foreign hyperscalers achieve localized certification. Deepen BSI credentialing velocity to maintain reseller partnership exclusivity as security standards tighten. Expand sovereign data center capacity in Batam to capture cross-border latency-sensitive workloads from Singapore-linked enterprises.
For New Entrants and Emerging Players: Direct-to-enterprise SaaS channels bypassing domestic system integrators offer entry points in healthcare and education verticals where ministry mandates override legacy procurement relationships. Target hospital IT replacement cycles driven by Ministry of Health electronic medical record deadlines. Pursue outer island SME segments in Makassar and Medan where fiber backbone extension creates first-mover positioning before infrastructure maturity attracts incumbent saturation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor BSI-certified domestic cybersecurity consultancies in Greater Jakarta facing talent scarcity but protected regulatory demand. Long-term viability centers on credentialing moats deepening through Kominfo implementing regulation enforcement windows. Monitor BSI cloud security certification tier expansions as inflection indicators for cross-border service architecture viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Data Center Expansion | Alibaba Cloud and Microsoft anchor positions through Jakarta and Batam sovereign infrastructure investments. |
| BSI Certification Investment | Domestic resellers capture protected demand channels as security standards filter market access. |
| Edge Computing Deployment | Outer island infrastructure gaps in Sumatra and Sulawesi present first-mover positioning opportunities. |
| AI-Cloud Convergence | Machine learning inference integration opens revenue streams for bundled analytics platform providers. |
| Healthcare System Integration | Ministry of Health EMR mandates compress decade-long depreciation schedules into immediate replacement cycles. |
Research Methodology
Kominfo regulatory filings, BSI certification databases, and hyperscaler capex disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with CTOs at state-owned enterprises, IT procurement officers in banking and telecommunications verticals, platform engineers at domestic system integrators, and channel partners serving government agencies validated demand patterns and pricing dynamics. Bottom-up triangulation across enterprise cloud migration timelines and top-down reconciliation against national ICT expenditure aggregates anchored value estimates.
Historical trendline analysis of cloud services adoption rates, hardware replacement cycles, and cybersecurity compliance spending established baseline growth trajectories across the projection horizon. The analytical framework modeled deployment model, organization size, vertical regulatory exposure, and regional infrastructure maturity as segmentation dimensions. CAGRs were derived from regression-adjusted adoption curves incorporating SME cloud migration acceleration and government digital transformation mandate enforcement phases. Forecast inputs included fiber backbone extension timelines and BSI certification process compression effects.
The model holds under sustained Kominfo enforcement of data localization mandates and stable BSI certification timelines; deviation in regulatory relaxation or accelerated tier expansion would shift competitive positioning toward foreign direct operators. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Algeria Telecom Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Iceland Telecom Market
Telecommunications
Kenya Telecom Market
Telecommunications
Singapore MVNO Market
Telecommunications
Austria ICT Market
Telecommunications
Poland Telecom Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Indonesia Volte Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Russia ICT Market
Telecommunications
Tetra Terminals Market