
 5G Connections Market | 2026-2036
5G Connections Market Size, Share, and Industry Trends Forecast 2026-2036
5G Connections Market Intelligence
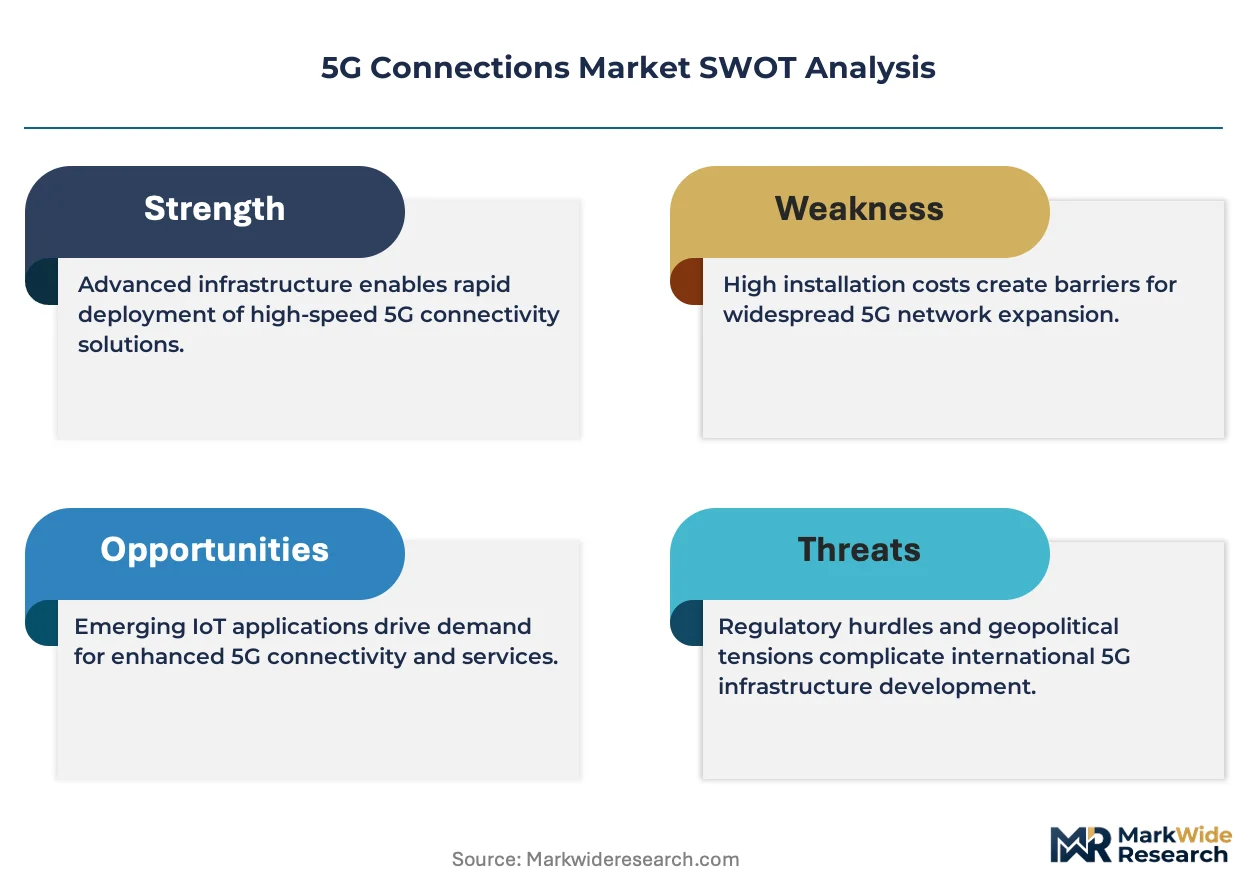
Standalone (SA) 5G architecture is redrawing the competitive landscape for telecommunications operators. Verizon Communications Inc. leverages its early investment in millimeter-wave spectrum to offer high-speed fixed wireless access in dense urban areas. In Europe, Deutsche Telekom AG positions itself as a leader in industrial IoT solutions through network slicing capabilities. Reliance Jio Infocomm Ltd. competes on scale and affordability to capture market share in India's rapidly expanding smartphone user base.
5G connections refer to the access links between user equipment and the 5G radio access network. These connections operate across low-band, mid-band, and high-band (mmWave) spectrum, delivering data rates exceeding 10 Gbps with latency under 1 millisecond. Enhanced Mobile Broadband for smartphones currently constitutes the largest volume of connections. However, Massive Machine Type Communications for IoT sensors and industrial equipment represent the fastest-growing category, driven by industrial automation.
Spectrum allocation policies from bodies like the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) directly influence network deployment timelines. In parallel, EU regulations on data privacy, such as GDPR, shape the architecture of services delivered over 5G networks, particularly for edge computing applications. Operator success will depend on securing strategic spectrum holdings and developing viable monetization models for network slicing and low-latency services.
Market Dynamics
The transition from Non-Standalone (NSA) to Standalone (SA) 5G architectures is the central force defining network evolution. This shift unlocks ultra-reliable low-latency communication (URLLC) capabilities, moving the market beyond consumer broadband into industrial-grade applications.
Growth Catalysts
- Industrial IoT Expansion:Demand for Massive Machine Type Communications (mMTC) in smart factories and logistics is a primary catalyst, enabling large-scale sensor deployments and process automation without reliance on wired connections.
- Government Modernization Programs:National industrial policies, such as those from China's Ministry of Industry and Information Technology (MIIT), are directly funding and incentivizing the adoption of 5G-enabled equipment to upgrade manufacturing infrastructure.
- Spectrum Availability:The progressive release of new mid-band spectrum by regulators like the US Federal Communications Commission (FCC) provides the necessary capacity and coverage balance for widespread service deployment.
Market Restraints
- High-Band Propagation Limits:Millimeter-wave (mmWave) spectrum, while offering immense speed, suffers from short range and poor object penetration, creating significant coverage gaps and requiring dense, costly infrastructure deployments in urban canyons.
- Capital Expenditure Intensity:The immense cost of deploying nationwide Standalone 5G networks, including new core infrastructure and radio access network upgrades, strains the financial resources of telecommunications operators.
- Spectrum Scarcity and Cost:Competition for limited mid-band spectrum assets in government auctions drives up acquisition costs for operators, potentially delaying or limiting the scope of network buildouts in certain territories.
Strategic Opportunities
- Private 5G Networks:Enterprises in manufacturing, logistics, and mining are creating a new market for dedicated, on-premise private 5G networks, offering an opportunity beyond public consumer services for operators and system integrators.
- Edge Computing Integration:The convergence of 5G connectivity with edge computing creates a powerful platform for new services, such as real-time analytics for autonomous systems and low-latency interactive cloud gaming.
- Fixed Wireless Access (FWA):In regions with limited fiber-to-the-home penetration, such as parts of India and Southeast Asia, 5G-based FWA presents a significant opportunity to provide competitive high-speed home and business internet services.
Industry Challenges
- Legacy System Integration:Operators face considerable technical complexity and operational cost in integrating new 5G Standalone core networks with existing 4G LTE infrastructure while maintaining seamless service continuity for customers.
- Monetization of Advanced Services:Developing viable and scalable pricing models for new capabilities like network slicing and guaranteed low-latency services remains a critical challenge, as enterprise value propositions are still being proven.
- Cybersecurity Vulnerabilities:The massive increase in connected devices, particularly in IoT, exponentially expands the potential attack surface, requiring new security architectures to protect networks and user data from sophisticated threats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Connections Market |
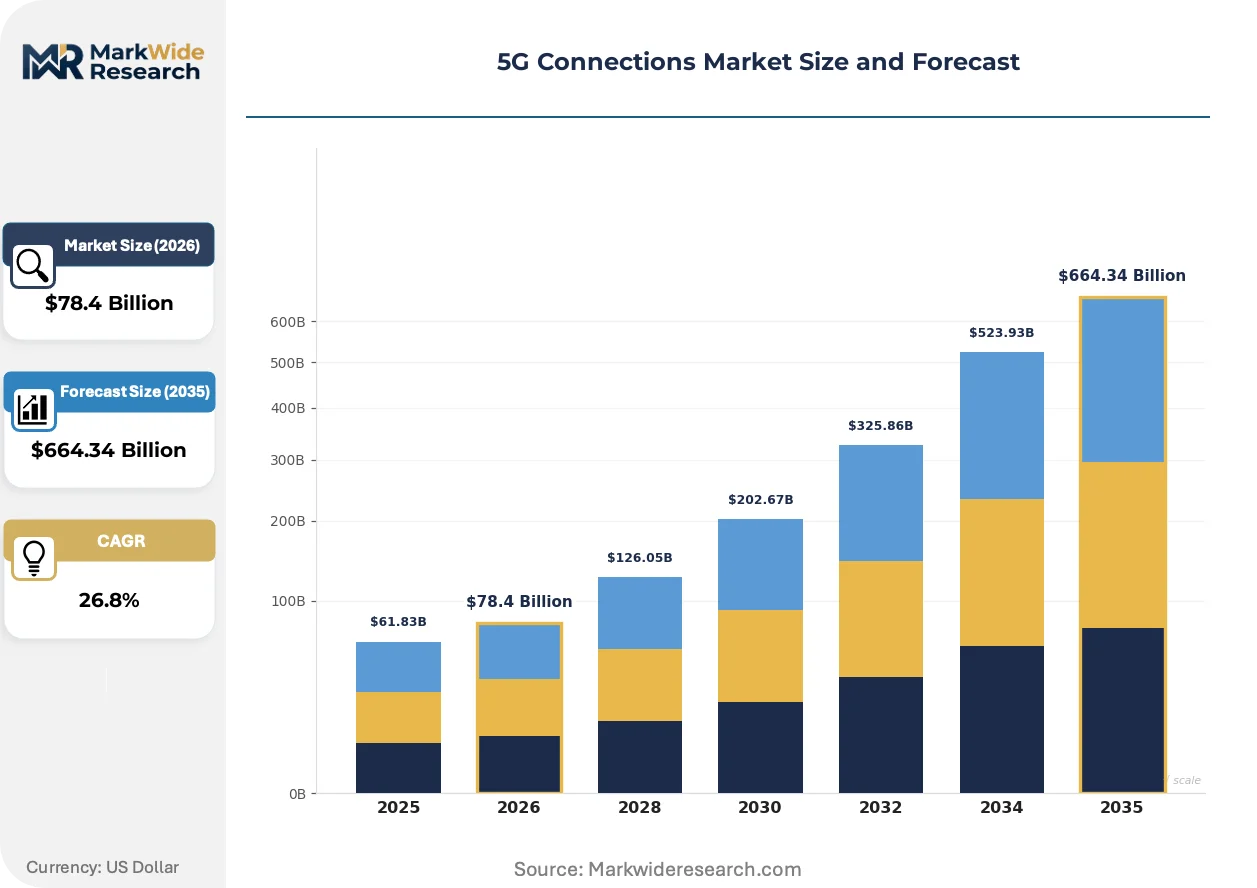
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $664.34 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connection Type: Enhanced Mobile Broadband, Massive Machine Type Communications, Ultra-Reliable Low Latency Communications, Fixed Wireless Access Device Category: Smartphones, Tablets, IoT Sensors, Industrial Equipment, Wearables Deployment Model: Non-Standalone, Standalone, Network Slicing, Edge Computing End User Segment: Telecommunications Operators, Smart Factories, Connected Vehicles, Media & Entertainment, Public Safety |
| Companies Covered | AT&T Inc., Verizon Communications Inc., Vodafone Group Plc, T-Mobile US Inc., China Mobile Ltd., China Telecommunications Corp., Deutsche Telekom AG, Reliance Jio Infocomm Ltd., SK Telecom Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Connections Market Strategic Shifts & Innovations
Enterprise requirements for dedicated performance and security are shifting the market's focus from consumer mobile broadband toward industrial-grade private networks and edge services. This evolution is driven by innovations in silicon, new regulatory frameworks, and changing procurement models.
Advanced System-on-Chip (SoC) designs integrate 5G modems with application processors and RF components. Smartphone and IoT device manufacturers are rapidly adopting these integrated circuits to reduce costs and design complexity. This integration is miniaturizing the component footprint and power requirements, enabling 5G connectivity in smaller form factors like industrial sensors and augmented reality glasses.
European Union regulations, especially the General Data Protection Regulation (GDPR), directly influence 5G service architecture. The regulation's strict rules on data residency and processing force operators to deploy edge computing resources geographically to keep user data within national or regional borders. The financial services and healthcare sectors are most affected, demanding network designs that ensure compliance by default.
A transition toward acquiring network capabilities as a managed service is altering enterprise purchasing behavior. Instead of relying on public carrier networks, corporations in sectors like manufacturing and logistics are procuring private 5G solutions from system integrators and cloud providers. This trend is most prominent in Germany and Japan, where industrial automation projects demand dedicated, secure, and low-latency on-site connectivity.
5G Connections Market Segmentation
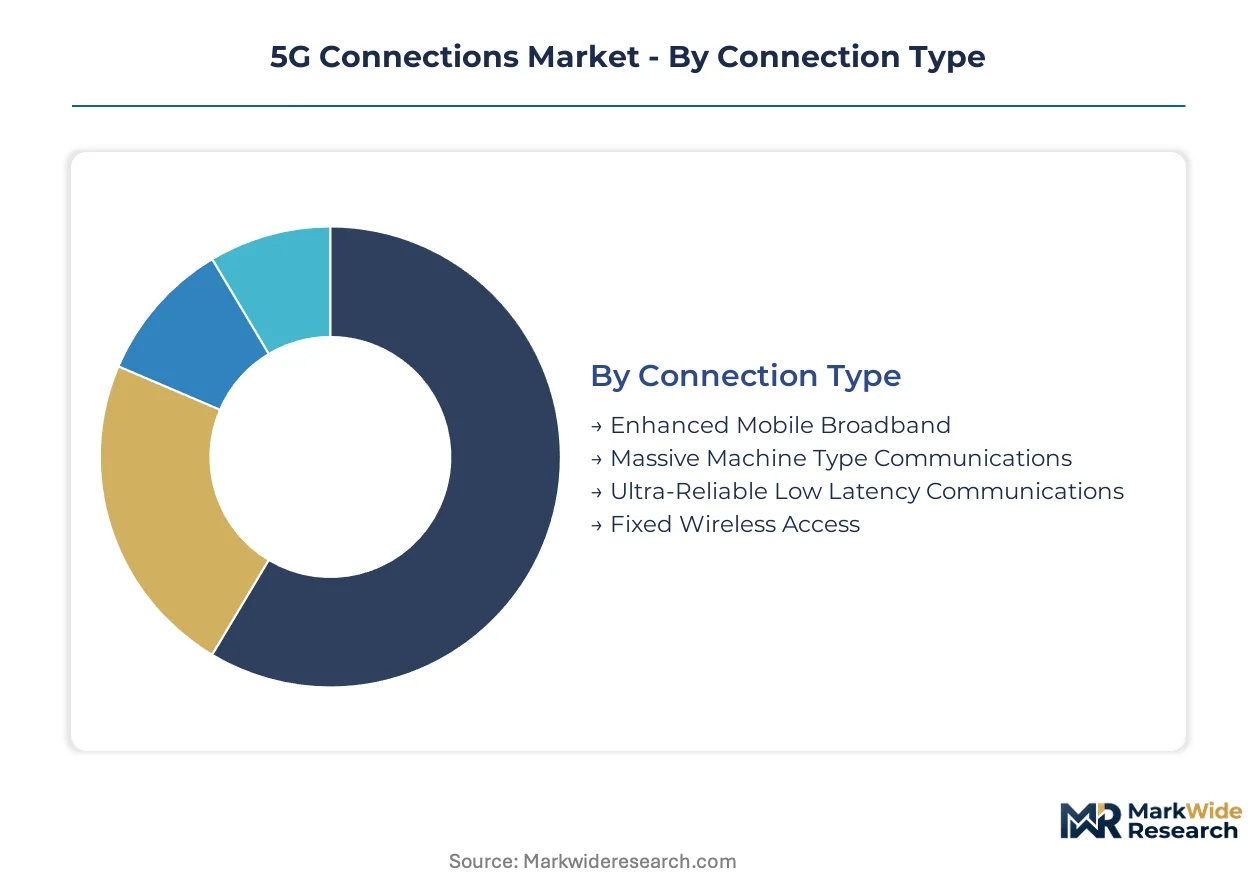
Understanding the segmentation of the 5G Connections Market is crucial for identifying distinct revenue streams and strategic investment areas. This analysis delineates the varying types of connections, devices, deployment architectures, and end-user applications that collectively shape the market landscape. Each segment presents unique technological requirements and commercial opportunities for network operators and solution providers.
Connection Type:
The distribution of 5G connections reflects varied access pathways, from consumer mobile broadband to industrial automation links.
- Enhanced Mobile Broadband:This service provides high-speed data access for consumer devices, enabling applications like streaming video and cloud gaming. Demand concentrates in dense urban areas, particularly for Verizon Communications Inc.'s millimeter-wave offerings, driven by consumer appetite for faster mobile internet.
- Massive Machine Type Communications:mMTC facilitates large-scale deployments of low-power, low-cost IoT devices, optimized for long battery life and infrequent data transmission. Demand is particularly strong in smart factories and logistics operations in China, propelled by government-led industrial modernization initiatives.
- Ultra-Reliable Low Latency Communications:URLLC offers guaranteed low latency and high reliability, critical for real-time control systems and autonomous applications.
- Fixed Wireless Access:FWA delivers high-speed internet to homes and businesses using 5G radio links, serving as an alternative to fiber in underserved regions like India.
By volume, Enhanced Mobile Broadband commands the largest share. By growth pace, Massive Machine Type Communications is expanding most quickly.
Device Category:
Device categories delineate the diverse hardware leveraging 5G connectivity, catering to both consumer and industrial applications.
- Smartphones:These handheld devices integrate advanced System-on-Chip (SoC) designs for 5G connectivity, supporting a wide range of mobile applications. Demand remains highest in markets like India, where Reliance Jio Infocomm Ltd. targets a rapidly expanding smartphone user base with affordable plans.
- IoT Sensors:IoT sensors are compact, low-power devices embedded in machinery or environments to collect data, communicating via mMTC. Their adoption is surging in European industrial settings, where Deutsche Telekom AG offers specialized solutions for process automation.
- Industrial Equipment:This category includes robots, automated guided vehicles, and production line machinery, increasingly leveraging 5G for real-time control and data exchange.
- Tablets:Tablets utilize 5G for enhanced portability and connectivity, supporting mobile productivity and multimedia consumption.
- Wearables:Wearable devices like smartwatches and AR glasses incorporate 5G for continuous connectivity and low-latency data processing, enabling new user experiences.
The proliferation of these devices directly influences the density and specialization of 5G network infrastructure deployments.
Deployment Model:
Deployment models highlight the architectural evolution of 5G networks, from initial overlay strategies to advanced, dedicated infrastructure.
- Standalone:Standalone 5G networks feature a new, cloud-native core independent of 4G infrastructure, enabling advanced capabilities like network slicing and URLLC. The transition to SA is a primary focus for telecommunications operators globally, driven by the need to support industrial-grade applications.
- Edge Computing:Edge computing integrates processing power closer to the data source, reducing latency and enabling real-time analytics for 5G-connected devices. Its adoption is accelerating in Europe, influenced by GDPR regulations requiring local data processing for financial services and healthcare.
- Non-Standalone:NSA 5G relies on the existing 4G LTE core network, providing faster speeds but limited advanced 5G capabilities.
- Network Slicing:Network slicing creates multiple virtual networks on a shared physical infrastructure, each tailored with specific performance characteristics for different services.
Strategic investment in Standalone and Edge Computing models is critical for operators aiming to capture high-value enterprise segments.
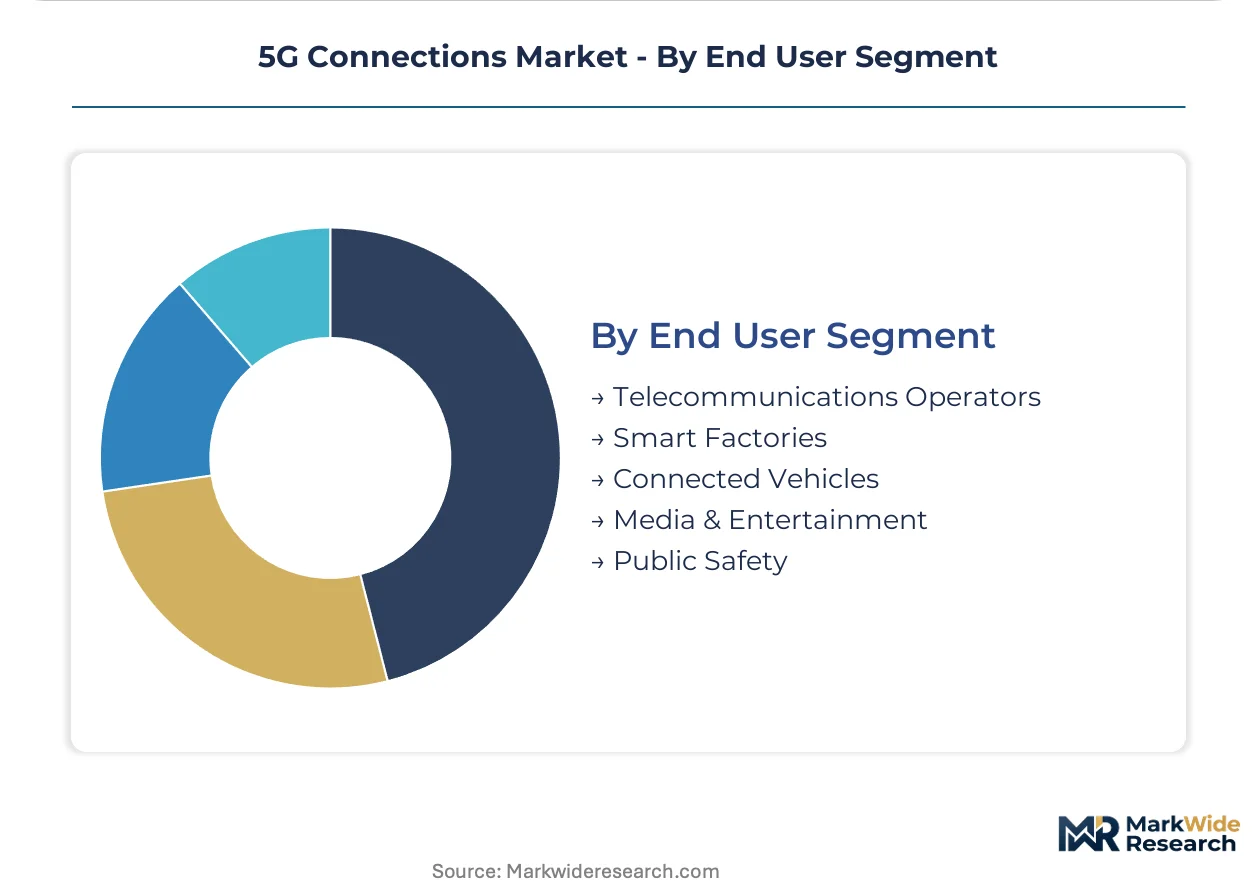
End User Segment:
End user segments define the distinct market demands and specific value propositions enabled by 5G connectivity across various industries.
- Smart Factories:Smart factories deploy 5G for industrial automation, real-time monitoring, and predictive maintenance, integrating IoT sensors and robotic systems. Demand is particularly high in Germany and Japan, where industrial automation projects require dedicated, secure, and low-latency on-site connectivity.
- Telecommunications Operators:Telecom operators invest in 5G infrastructure to offer connectivity services, developing new monetization models for enterprise solutions and consumer broadband. Verizon Communications Inc. and Deutsche Telekom AG are actively shaping this segment through strategic spectrum holdings and specialized service offerings.
- Connected Vehicles:Connected vehicles utilize 5G for V2X communication, infotainment, and autonomous driving features, enhancing safety and efficiency.
- Media & Entertainment:This segment leverages 5G for high-bandwidth content delivery, immersive experiences, and remote production workflows.
- Public Safety:Public safety agencies adopt 5G for reliable, secure communication, supporting emergency services and critical infrastructure protection.
Monetization strategies for 5G services will increasingly rely on tailoring solutions to the unique operational requirements of these diverse end user groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for advanced 5G connectivity flows significantly from industrial powerhouses to emerging markets. China's industrial modernization initiatives drive substantial equipment adoption globally. European enterprises also increasingly procure specialized 5G solutions for factory automation.
China
Demand for Massive Machine Type Communications (mMTC) in smart factories is a primary driver. The Ministry of Industry and Information Technology (MIIT) actively funds modernization programs. The Yangtze River Delta region focuses on manufacturing upgrades through 5G-enabled automation.
United States
Enhanced Mobile Broadband (eMBB) in dense urban areas and Fixed Wireless Access (FWA) drive connection growth. The US Federal Communications Commission (FCC) regulates spectrum allocation for widespread deployment. Silicon Valley and other technology hubs integrate edge computing for low-latency applications.
Germany
Enterprises increasingly adopt private 5G networks and industrial IoT solutions. EU regulations like GDPR influence edge computing architecture for data residency. Bavaria and North Rhine-Westphalia are hubs for advanced manufacturing utilizing 5G automation.
India
Affordable smartphone connectivity and Fixed Wireless Access (FWA) are key demand drivers. India's telecom regulator shapes spectrum policies to expand network reach. Bangalore and Mumbai represent significant markets for expanding smartphone user bases.
Japan
Industrial automation and dedicated private 5G solutions require low-latency capabilities. The Ministry of Economy, Trade and Industry (METI) promotes industrial digitalization. The Kanto region and major industrial zones implement dedicated on-site 5G connectivity.
5G Connections Market Key Industry Players
Listed leaders compete with private specialists across the 5G connections market. The market structure blends established telecommunications operators with emerging solution integrators. Key strategic archetypes include core network providers, access network developers, and enterprise service enablers. Dominant competitive moves involve strategic spectrum acquisition and the development of network slicing capabilities.
Among global telecommunications operators, Verizon Communications Inc. and Deutsche Telekom AG represent distinct strategic approaches. Verizon Communications Inc., a US-based entity, leverages millimeter-wave spectrum for high-speed fixed wireless access. Deutsche Telekom AG, a European corporation, exemplifies leadership in industrial IoT solutions through network slicing capabilities. Reliance Jio Infocomm Ltd., an Indian company, occupies a position focused on scale and affordability to capture market share among smartphone users.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications Inc. |
| Vodafone Group Plc |
| T-Mobile US Inc. |
| China Mobile Ltd. |
| China Telecommunications Corp. |
| Deutsche Telekom AG |
| Reliance Jio Infocomm Ltd. |
| SK Telecom Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The immense capital expenditure required for nationwide 5G Standalone network deployments creates significant scale economies, which in turn concentrate supply among large telecommunications operators and establish high price floors for advanced enterprise services.
Pricing Analysis
The 5G pricing model currently exhibits a gap between consumer-focused Enhanced Mobile Broadband and emerging industrial-grade services. Operators primarily offer subscription-tiered plans for consumer 5G, while enterprise solutions like network slicing are moving towards value-based, contract pricing. Price differentiation stems from guaranteed service level agreements and data security features. Pricing pressure stems from intense competition in consumer mobile broadband, particularly in markets like India. Industrial end-users, especially smart factories, demonstrate lower price sensitivity for mission-critical URLLC applications.
Supply Chain Analysis
Long lead times for specialized 5G core network equipment and radio access network components are a critical consideration for deployment schedules. Geographic supply concentration for these advanced components is centered in countries like China, South Korea, and Finland. The supply chain relies heavily on sophisticated System-on-Chip designs from Taiwan for 5G modems. Single-source vulnerability for specific high-performance components represents a structural risk. Distribution runs through a mix of direct sales to operators and system integrators for private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G Connections Market presents a significant fragmentation opportunity, driven by enterprise demand for dedicated, on-premise private networks. This shift creates distinct niches beyond traditional public mobile broadband services.
For Market Incumbents: Secure strategic spectrum holdings in mid-band frequencies to offer a balanced portfolio of consumer and enterprise services. Consolidate core network infrastructure to reduce operational costs and mitigate the threat from new specialized private network providers. Invest in network slicing capabilities to differentiate offerings and address the specific needs of industrial IoT applications, counteracting margin pressure in consumer segments. Leverage existing customer relationships to cross-sell private 5G solutions.
For New Entrants and Emerging Players: Lead with specialized private 5G solutions tailored for specific industrial verticals, such as smart factories or logistics hubs. Target the manufacturing sector in Germany and Japan, where industrial automation demands dedicated, secure, and low-latency on-site connectivity. Offer comprehensive managed service models, bundling hardware, software, and integration services, as a key go-to-market angle. Focus on delivering outcome-based solutions rather than just connectivity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers offering managed private 5G networks and edge computing services to enterprises. The long-term viability favors companies that can consistently deliver guaranteed service level agreements and integrate seamlessly with existing industrial IT infrastructure over a 5-10 year window. Target acquisition archetypes include specialized system integrators with deep vertical expertise in industrial automation. The signal to watch is the acceleration of large-scale enterprise private network deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Standalone Core Network | This enables advanced network slicing capabilities for high-value industrial applications, attracting new enterprise clients. |
| Acquire Mid-Band Spectrum Licenses | Securing balanced spectrum assets allows operators to offer competitive 5G services across urban and rural areas. |
| Develop Edge Computing Partnerships | Integrating processing power closer to data sources supports real-time analytics for autonomous systems and IoT devices. |
| Offer Private 5G as Managed Service | Enterprises in manufacturing and logistics gain dedicated, secure connectivity without internal operational burdens. |
| Expand Fixed Wireless Access Footprint | This provides high-speed internet alternatives to homes and businesses in underserved regions like India. |
Research Approach
A standing panel of telecommunications operators, network equipment vendors, IoT device manufacturers, and enterprise IT decision-makers provided ongoing calibration for market sizing and forecasting. This approach combined primary interviews with industry stakeholders with extensive secondary validation. Secondary data sources included spectrum auction results, operator financial reports, government industrial policy documents, and industry association reports. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Market outputs were consistently checked against external benchmarks and validated through a robust analytical framework across the analysis window. Segmentation dimensions modeled included connection type, device category, deployment model, end-user segment, and regional spectrum availability. Compound Annual Growth Rates were derived from historical trends and projected future adoption rates. Key forecast inputs included 5G network buildout timelines and enterprise digital transformation budgets.
The analysis sits within stated boundaries; outcomes outside unforeseen spectrum policy changes or slower-than-expected enterprise adoption would require recalibration. Forecasts reflect assumptions concerning technological advancements and global economic stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
DECT System Market
Telecommunications
5G in Defense Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Esim Subscription Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Smart SIM Market
Telecommunications
Voip Phone Market
Telecommunications
Colombia Telecom Market
Telecommunications
MVNO Market
Telecommunications
5G MVNO Market
Telecommunications
France Telecom Market
Telecommunications
Telecom API Platform Market