
 Nigeria Telecom Tower Market | 2026-2036
Nigeria Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Telecom Tower Market Insights
Co-location tenancy revenue is rewriting the margin architecture of Nigerian tower economics. IHS Towers leverages its portfolio scale to sustain tenancy ratios above industry averages across multiple states. American Tower Corporation anchors its position through long-term lease agreements with major mobile network operators. Helios Towers competes by specializing in rural coverage extensions where single-tenant configurations remain economically viable.
Nigeria telecom towers are steel or concrete structures engineered to heights between 30 and 120 meters, designed to mount multiple antenna arrays and support power systems for continuous radio transmission across cellular networks. Lattice towers dominate the installed base due to their load-bearing capacity for multi-tenant configurations, while monopole designs are displacing older guyed structures in urban deployments where land constraints limit guy-wire footprints. Microwave backhaul equipment represents a mature segment with stable replacement cycles, whereas 5G-ready tower upgrades constitute the fastest-growing technology category as operators prepare for spectrum auctions.
The Nigerian Communications Commission enforces infrastructure sharing mandates that reduce duplicate tower construction, while the National Environmental Standards and Regulations Enforcement Agency imposes electromagnetic field exposure limits that shape site selection and equipment specifications. The country's national broadband plan sets coverage obligations that directly determine tower deployment priorities in underserved local government areas. Stakeholders must monitor spectrum allocation timelines and tenancy rate negotiations as the decisive variables for capital deployment returns.
Market Dynamics
Co-location tenancy economics are restructuring Nigeria's tower sector as infrastructure sharing mandates compress capital intensity per site. Mobile network operators now prioritize tenancy ratios over greenfield construction, forcing tower companies to optimize existing portfolios for multi-tenant revenue stacking.
Growth Catalysts
- National Broadband Plan coverage obligations:The federal mandate for universal connectivity drives tower deployment into 774 local government areas previously outside commercial viability thresholds.
- 5G spectrum preparation:Mobile operators are pre-positioning antenna capacity and power upgrades to accommodate massive MIMO configurations ahead of auction timelines.
- Lagos-South-South fiber convergence:Dense population clusters along submarine cable landing points concentrate backhaul-ready demand for co-located infrastructure.
Market Restraints
- Diesel price volatility:Tower power systems remain 78% dependent on fossil fuel generation, exposing opex to NNPC pricing adjustments and forex-driven import costs.
- Steel supply concentration:Lattice tower fabrication relies on imported hot-rolled coils, with lead times extending when Lagos port congestion peaks during Q4 import seasons.
- Electromagnetic field exposure limits:National Environmental Standards and Regulations Enforcement Agency proximity rules restrict site placement in urban centers where land scarcity already compresses zoning options.
Strategic Opportunities
- Northeast corridor underpenetration:Borno, Yobe and Adamawa states carry sub-40% mobile coverage, creating first-mover tenancy contracts for rural-optimized monopole configurations.
- Solar-hybrid power convergence:Integration of photovoltaic arrays with lithium-ion storage is collapsing diesel dependency and unlocking carbon credit revenue streams.
- Central Bank renewable energy credit lines:Tier-1 banks now offer concessional project finance for green tower retrofits, reducing WACC for portfolio upgrades.
Industry Challenges
- Site acquisition and community engagement:Land rights negotiations in Niger Delta communities require 14-18 month timelines, delaying rollout schedules against license conditions.
- Multi-tenant RF interference management:Technical teams must coordinate antenna positioning across competing operators to prevent signal degradation that triggers service level penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Telecom Tower Market |
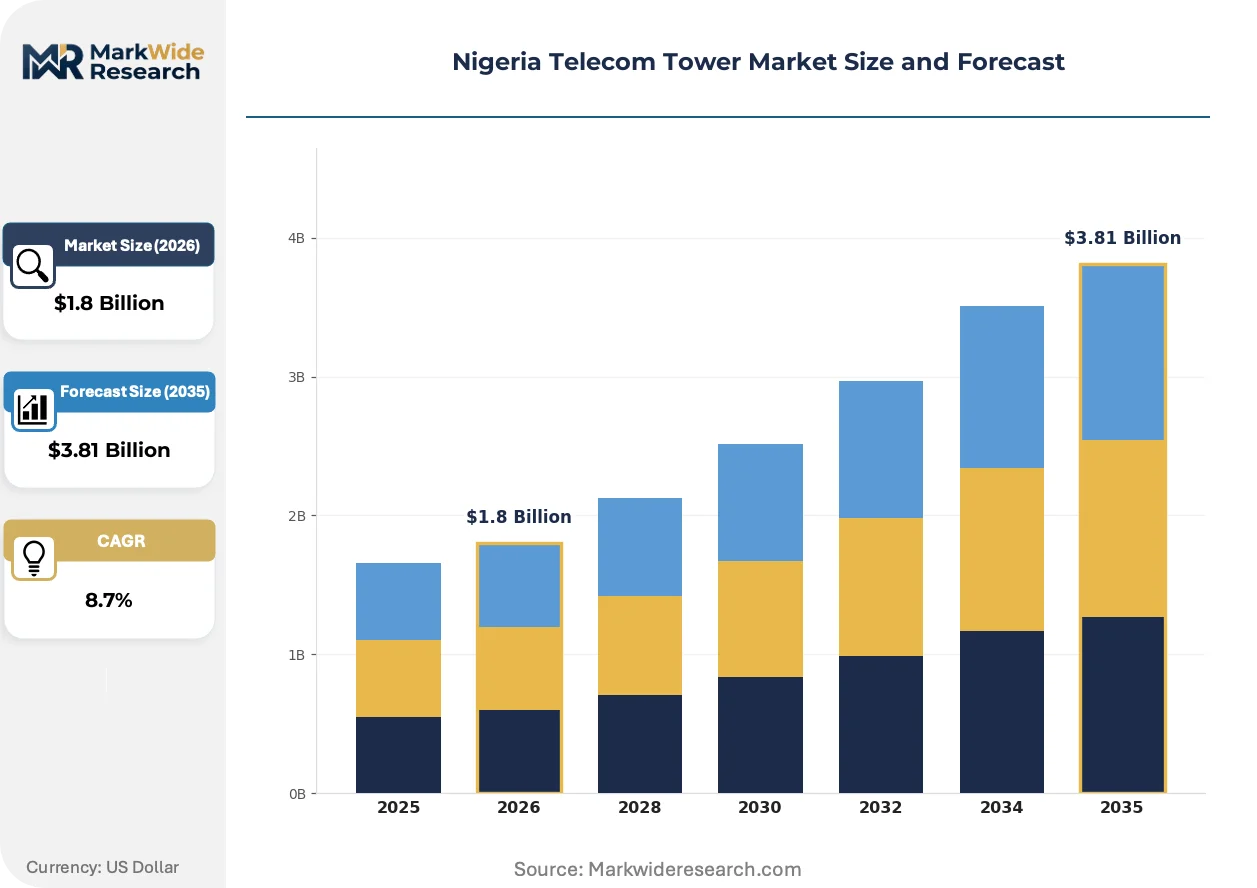
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Guyed, Rooftop Technology: 4G, 5G, LTE, Microwave Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: MNOs, ISPs, Enterprises, Government |
| Companies Covered | IHS Towers, American Tower Corporation, Pan African Towers Limited, Africa Mobile Networks, Helios Towers, Communication Towers Nigeria Limited, Eastcastle Infrastructure Limited, Hotspot Networks, ATC Nigeria, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Telecom Tower Market Trends and Innovations
Network function virtualization is collapsing the boundary between physical tower assets and software-defined radio access. This architectural shift permits dynamic spectrum allocation without hardware swaps, compressing upgrade cycles and reshaping how tower companies monetize structural capacity.
Virtualized radio access network technology is virtualizing baseband processing functions that previously required dedicated equipment at each tower site. Mobile operators in Lagos and Abuja are piloting centralized cloud-RAN hubs that pool processing across 40-60 cell sites simultaneously. This topology is virtualizing the traditional one-to-one relationship between tower steel and network capacity, enabling tenancy ratio expansion without structural augmentation.
The Nigerian Communications Commission infrastructure sharing framework now mandates joint use of passive assets and standardized interconnection protocols. Tower companies must publish transparent pricing for co-location space, power and backhaul to prevent discriminatory access. Rural coverage extensions face the steepest compliance adjustments, as single-tenant legacy sites require rapid retrofitting to accommodate secondary tenants under revised license terms.
Operator procurement patterns now emphasize tenancy rate guarantees over upfront lease payments, shifting tower company revenue recognition toward performance-linked structures. Major mobile network operators in the South-South corridor negotiate escalator clauses tied to subscriber growth rather than fixed annual uplifts. This model concentrates margin pressure on tower owners while transferring demand risk downstream, visible most acutely in Port Harcourt and Warri cluster negotiations where multiple operators simultaneously restructure legacy agreements.
Nigeria Telecom Tower Market Segmentation
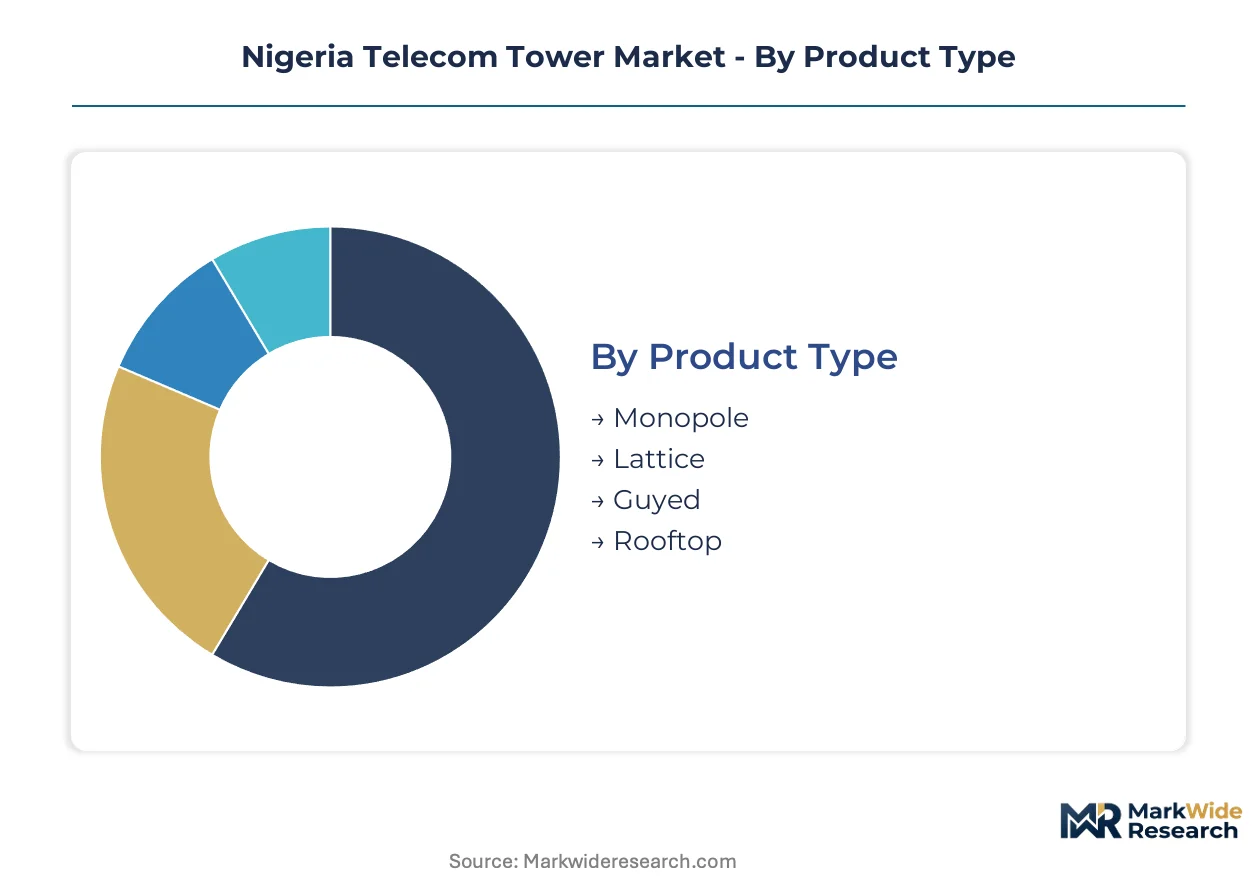
Nigeria's telecom tower segmentation reflects divergent infrastructure economics across urban density gradients and technology migration timelines. Tower companies optimize portfolio composition against tenancy ratios, backhaul readiness, and power reliability constraints that vary sharply between Lagos commercial zones and Northeast rural corridors.
Product Type:
Structural configurations span load-bearing requirements from single-tenant rural sites to multi-tenant urban hubs, with material specifications and foundation engineering driving total cost of ownership across Nigeria's varied soil conditions.
- Monopole:Tubular steel structures reaching 40-60 meters with minimal ground footprint, engineered for dense urban deployments where Lagos land scarcity restricts guy-wire clearances. Demand concentrates in Victoria Island and Ikeja commercial districts where zoning codes prioritize aesthetic integration over lattice visibility.
- Lattice:Triangular or square-section steel frameworks supporting 80-120 meter heights and 15-ton antenna loads, dominating multi-tenant configurations across Port Harcourt and Abuja industrial zones. Port Harcourt cluster operators specify lattice designs to accommodate three-plus tenant arrays without structural reinforcement.
- Guyed:Masted towers stabilized by tensioned cable arrays, occupying extensive ground footprints that limit deployment to peri-urban fringes and rural expanses where Borno and Yobe land costs permit 30-meter radius clearances.
- Rooftop:Building-integrated installations leveraging existing commercial and residential structures, proliferating in Lagos Island and Ikoyi where street-level site acquisition exceeds 24-month timelines.
Established volume favors lattice configurations; emerging adoption favors monopole deployments.
Technology:
Radio access generations segment capital deployment timing, with spectrum auction schedules and subscriber migration curves determining upgrade sequencing across operator portfolios.
- 4G:Mature LTE infrastructure constituting the installed revenue base across MTN and Airtel Nigeria portfolios, concentrated in South-South corridor urban centers where subscriber density justifies capacity expansion over greenfield 5G overlay.
- 5G:Massive MIMO-ready tower modifications requiring power system upgrades and antenna mounting capacity expansion, climbing the fastest in Lagos and Abuja pilot zones ahead of Nigerian Communications Commission spectrum allocation timelines.
- LTE:Legacy 4G equipment configurations optimized for voice-data convergence, persisting in Kano and Kaduna secondary markets where operator capex prioritizes coverage density over speed tier differentiation.
- Microwave:Point-to-point backhaul transmission equipment mounted at tower apex, stabilizing in replacement-cycle demand as fiber convergence in Lagos-South-South corridors displaces wireless backhaul for high-capacity routes.
Revenue concentration remains with LTE infrastructure; steepest expansion trajectory attaches to 5G-ready modifications.
Deployment Model:
Operational responsibility distribution shapes opex allocation and control retention between mobile network operators and tower company intermediaries.
- On-Premises:Operator-owned and operated tower assets with captive maintenance teams, persisting among tier-1 MNOs in core revenue markets where direct control outweighs outsourcing economics.
- Cloud-Based:Virtualized baseband processing centralized across multiple cell sites, piloting in Lagos metropolitan clusters where IHS Towers and American Tower Corporation test vRAN topology consolidation.
- Hybrid:Split architectures combining on-site radio units with centralized processing hubs, emerging in Abuja corridor deployments balancing latency sensitivity against power cost reduction.
- Managed Services:Full opex outsourcing to tower specialists encompassing power, security, and maintenance, dominating new tenancy agreements as operators divest operational complexity to focus on subscriber acquisition.
Legacy ownership favors on-premises retention; contract velocity favors managed services expansion.
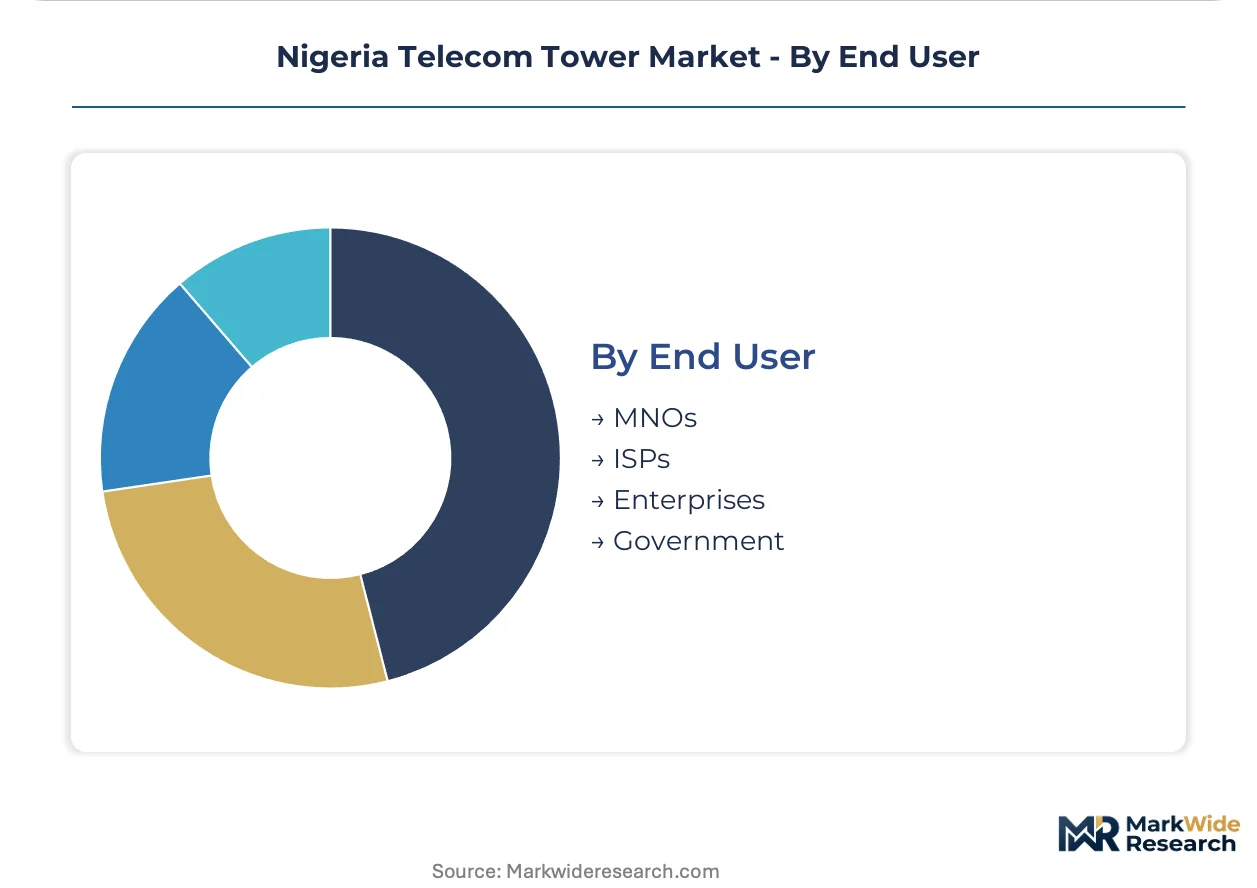
End User:
Demand source diversity segments tenancy risk profiles and contract duration patterns across Nigeria's connectivity ecosystem.
- MNOs:Mobile network operators MTN, Airtel, Globacom, and 9mobile constituting primary tenancy demand, driving co-location economics through multi-year lease commitments anchored to subscriber growth escalators.
- ISPs:Fixed wireless access providers and fiber operators leasing tower space for last-mile distribution, expanding in Lagos and South-South corridors where enterprise connectivity demand outpaces MNO fixed-line offerings.
- Enterprises:Mining, oil and gas, and logistics operators procuring dedicated coverage for remote operations, concentrated in Niger Delta extraction zones and solid mineral belts requiring private network configurations.
- Government:Federal and state agencies deploying emergency communications and rural connectivity infrastructure, channeling demand through Universal Service Provision Fund subsidies targeting 774 local government area coverage mandates.
Tenancy volume concentrates with MNOs; contract margin expansion favors enterprise and government segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Lagos and Abuja corridors exhibit low price elasticity for premium co-location sites with fiber backhaul, while operators in Borno and Yobe states face acute cost sensitivity that compresses tenancy rates and extends payback periods for rural deployments.
Lagos State
Lagos anchors Nigeria's tower demand through Victoria Island and Ikeja commercial districts where land scarcity elevates site acquisition premiums above national averages. The Nigerian Communications Commission enforces infrastructure sharing mandates that compel multi-tenant configurations in dense urban zones. IHS Towers and American Tower Corporation concentrate lattice and monopole portfolios along submarine cable landing corridors where fiber convergence supports 5G-ready upgrades.
South-South Corridor
Port Harcourt and Warri clusters generate concentrated demand from oil and gas enterprises requiring private network coverage alongside MNO tenancy. National Environmental Standards and Regulations Enforcement Agency electromagnetic field exposure limits restrict site placement in waterfront industrial zones. Tower companies optimize lattice designs for three-plus tenant arrays across Rivers and Delta states where fiber backhaul intersects with Niger Delta extraction operations.
Federal Capital Territory
Abuja's administrative concentration drives government-funded rural connectivity mandates through Universal Service Provision Fund subsidies. The National Broadband Plan coverage obligations direct tower deployment into satellite communities surrounding the capital. Managed services agreements dominate as operators outsource operational complexity to focus on subscriber acquisition in the metropolitan cluster.
Northeast States
Borno, Yobe and Adamawa states present underpenetrated terrain where sub-40% mobile coverage creates first-mover opportunities for rural-optimized monopole configurations. Security challenges and extended land rights negotiations compress commercial viability, requiring concessional Central Bank renewable energy credit lines to reduce WACC. Solar-hybrid power integration is collapsing diesel dependency in remote sites where grid connectivity remains absent.
Kano-Kaduna Axis
Northern commercial centers sustain legacy LTE infrastructure demand where subscriber density justifies capacity expansion over 5G overlay investments. The Nigerian Communications Commission spectrum allocation timelines lag behind southern corridors, delaying massive MIMO upgrade cycles. Tower companies prioritize tenancy ratio optimization on existing portfolios rather than greenfield construction in secondary markets.
Nigeria Telecom Tower Market Competitive Landscape
Capability concentration sits with tower specialists possessing rural deployment expertise and government relationship networks; scale advantage sits with international operators leveraging portfolio breadth across multiple African markets. The sector exhibits tiered consolidation with three distinct player categories dominating contract awards. Strategic archetypes include pan-African infrastructure platforms, Nigeria-focused specialists, and operator-captive ventures. Competitive dynamics center on tenancy rate guarantees and long-term lease escalator structures rather than asset acquisition velocity.
Within the international platform tier, IHS Towers and American Tower Corporation occupy positions defined by portfolio scale and multi-country operating frameworks. Helios Towers exemplifies the specialist archetype through rural coverage extension capabilities. These three entities anchor competitive positioning as the sector transitions from greenfield construction toward tenancy ratio optimization and existing site retrofitting for multi-tenant configurations.
| Leading Market Players |
|---|
| IHS Towers |
| American Tower Corporation |
| Pan African Towers Limited |
| Africa Mobile Networks |
| Helios Towers |
| Communication Towers Nigeria Limited |
| Eastcastle Infrastructure Limited |
| Hotspot Networks |
| ATC Nigeria |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Lagos lattice tower fabrication compresses supplier pricing power while elevating buyer leverage in tenancy rate negotiations. Nigerian tower companies respond by shifting procurement toward long-term steel supply contracts that lock in input costs against NNPC diesel pricing volatility.
Pricing Analysis
After-sales power service contracts now drive lifetime value for tower operators more than structural lease revenue alone. Three-tier pricing structure across premium, standard, and economy levels segments by fiber backhaul readiness and power reliability guarantees. Price differentiation hinges on solar-hybrid integration certification and tenancy ratio commitments. Pricing pressure stems from operator procurement teams demanding performance-linked escalators over fixed uplifts. Enterprise buyers in Niger Delta extraction zones exhibit lowest price sensitivity; rural MNO tenants in Borno and Yobe states face acute cost compression.
Supply Chain Analysis
Tariff exposure between China and Nigeria dominates input cost risk for hot-rolled coil imports used in lattice fabrication. Tower steel draws from Chinese mills, South Korean specialty producers, and domestic rolling stock at Ajaokuta. Lithium-ion battery cells, photovoltaic arrays, and diesel generators constitute critical power system inputs. Single-source vulnerability concentrates in Lagos port clearance bottlenecks during Q4 import seasons. Distribution runs through IHS Towers and American Tower Corporation captive logistics networks to site clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tower economics in Nigeria are restructuring around service-attach revenue as power-as-a-service contracts expand faster than steel tenancy leases. Managed services outsourcing now captures margin pools that hardware ownership cannot access.
For Market Incumbents: Insulate tenancy ratio leadership by accelerating solar-hybrid retrofits before Central Bank renewable credit lines expire. Lock in 10-year power service contracts with MNOs to substitute recurring revenue for volatile lease escalators. Vertical integration into lithium-ion storage assembly reduces exposure to forex-driven battery import costs. For New Entrants and Emerging Players: Northeast corridor monopole deployments in Adamawa and Taraba states represent the most penetrable entry point given sub-40% coverage and limited incumbent presence. Solar-native tower configurations bypass diesel logistics entirely. Partner with Universal Service Provision Fund administrators to secure subsidy-anchored tenancy guarantees before infrastructure sharing mandates tighten. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tower operators with above-industry tenancy ratios and captive power service divisions. Long-term viability over the next decade hinges on portfolio positioning along fiber convergence corridors. Monitor Nigerian Communications Commission spectrum auction timelines as the decisive inflection signal for 5G-ready upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Hybrid Retrofit Program | Collapses diesel opex and unlocks carbon credit revenue streams under NESREA compliance frameworks. |
| Multi-Tenant Configuration Upgrade | Maximizes tenancy ratios on existing lattice assets to meet National Broadband Plan coverage mandates. |
| Long-Term Power Service Contracting | Shifts revenue recognition from volatile lease escalators to predictable managed services annuities. |
| Fiber Backhaul Site Clustering | Concentrates capital along Lagos-South-South submarine cable corridors where demand density justifies premium pricing. |
| Rural Monopole Deployment | Captures first-mover tenancy in Northeast states where grid absence necessitates solar-native engineering. |
Research Methodology
The analysis maps lattice, monopole, guyed, and rooftop tower configurations, each validated through tower company procurement directors, MNO network planning executives, Nigerian Communications Commission regulatory officers, and solar EPC contractors. Primary interviews triangulate against Nigerian Customs Service import records, NNPC petroleum pricing bulletins, Central Bank renewable energy financing circulars, and Universal Service Provision Fund disbursement filings. Bottom-up site-level tenancy modeling converges with top-down infrastructure investment flow analysis.
Assumptions held fixed include National Broadband Plan coverage obligation timelines and NESREA electromagnetic field exposure limits; variables tested include diesel price trajectories and spectrum auction sequencing. Segmentation dimensions span structural type, radio access technology generation, deployment model responsibility split, and end-user category across the projection horizon. CAGRs derive from tenancy ratio expansion curves and power system upgrade cycles. Forecast inputs incorporate NNPC fossil fuel pricing corridors and lithium-ion battery cost decline trajectories.
Macroeconomic conditions sit as an overlay; deviation in naira exchange rates or Lagos port congestion severity would shift the trajectory. Forecasts reflect documented assumptions about infrastructure sharing enforcement intensity and solar-hybrid adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
5G Network Infrastructure Market