
 Competitive Local Exchange Carriers (CLEC) Market | 2026-2036
Competitive Local Exchange Carriers (CLEC) Market Size, Share, and Industry Trends Forecast 2026-2036
Competitive Local Exchange Carriers (CLEC) Market Intelligence
A shift from single-source network procurement to a multi-vendor strategy is decoupling enterprise telecommunications spending from traditional incumbent carriers. This creates opportunities for specialized providers. For instance, Windstream leverages its extensive fiber network to serve enterprise clients with specific connectivity needs. CenturyLink competes by offering a broad portfolio of managed network and cloud connectivity solutions, while Verizon Communications operates in this segment alongside its established incumbent services.
A Competitive Local Exchange Carrier is a telecommunications company that provides services in competition with incumbent local exchange carriers. These entities offer services over their own network facilities or by leasing unbundled network elements from incumbents, often delivering connectivity via technologies like VoIP and Ethernet over fiber. Data Services and Cloud Connectivity are the leading service types by revenue. Within the technology segment, SD-WAN solutions represent the fastest-growing category, displacing legacy MPLS in many enterprise deployments.
Regulatory frameworks are fundamental to market structure, with bodies like the US Federal Communications Commission (FCC) and India's TRAI mandating terms for network access. In Europe, national regulators such as Germany's BNetzA enforce pro-competition policies that enable CLEC operations. The central strategic decision for carriers remains balancing investment in proprietary fiber infrastructure against the operational costs of leasing network elements from incumbents.
Market Dynamics
The central dynamic is the decoupling of enterprise telecommunications procurement from single-source incumbent carriers. This shift, enabled by software-defined networking, creates distinct market openings for specialized CLECs that can compete on service agility, price, or niche capabilities.
Growth Catalysts
- SD-WAN Proliferation:This technology allows enterprises to manage network services more flexibly and cost-effectively, creating demand for CLECs that can provide the underlying connectivity and managed SD-WAN overlays.
- Medium Enterprise Demand:Businesses in this segment require integrated data, voice, and cloud connectivity solutions that are more sophisticated than small business offerings but more agile than traditional incumbent contracts.
- Digital Infrastructure Policy:National initiatives, such as those in India promoted by the TRAI, prioritize the development of digital infrastructure, creating a favorable environment for competitive carriers to expand their fiber and service footprint.
Market Restraints
- Infrastructure Investment:The high capital expenditure required to build, maintain, and expand proprietary fiber optic networks represents a significant barrier to entry and a constraint on rapid geographic expansion.
- Incumbent Dependency:CLECs often rely on leasing unbundled network elements from incumbents, making their cost structure and service availability subject to the terms and conditions mandated by regulators like the FCC.
- Wireless Substitution:The maturation of 5G Fixed Wireless Access (FWA) presents a viable alternative for last-mile business connectivity, potentially bypassing the need for CLEC-provided wireline services in some areas.
Strategic Opportunities
- Cloud Connectivity Specialization:CLECs can develop high-value services focused on providing secure, low-latency, and high-bandwidth connections directly to major cloud service provider platforms and data center ecosystems.
- SASE Integration:The convergence of networking and security offers an opportunity to bundle SD-WAN with Secure Access Service Edge (SASE) components, delivering an integrated solution to security-conscious enterprises.
- Targeting Underserved Corridors:Focusing network build-outs on specific business parks, industrial zones, or secondary metropolitan areas that lack dense fiber infrastructure from incumbent carriers presents a clear path to market entry.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity of integrating modern VoIP and Ethernet services with the diverse and often outdated legacy IT and MPLS network infrastructure of enterprise customers.
- Network Engineering Talent:There is a persistent shortage of skilled engineers who possess expertise across both traditional telecommunications protocols and modern software-defined networking and cybersecurity technologies.
- Bandwidth Scaling Pressure:The constant growth in enterprise data usage necessitates continuous, capital-intensive upgrades to network backbones and access infrastructure to maintain service quality and competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Competitive Local Exchange Carriers (CLEC) Market |
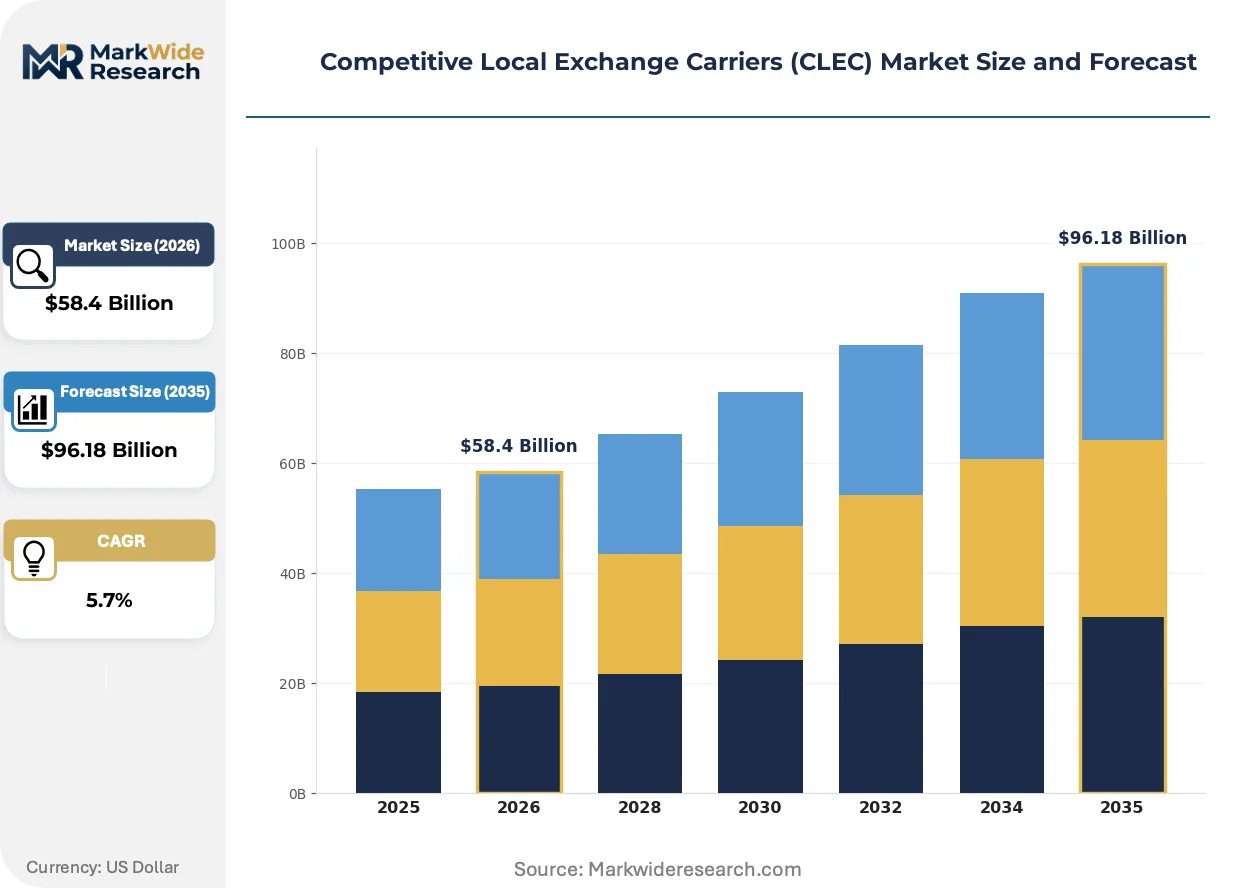
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $96.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Services, Data Services, Internet Access, Managed Network, Cloud Connectivity, Security Solutions Client Type: Small Businesses, Medium Enterprises, Large Corporations, Government Agencies, Educational Institutions, Nonprofit Organizations Technology: VoIP, MPLS, Ethernet, SD-WAN, Fiber Optic, Wireless Broadband Distribution Channel: Direct Sales, Channel Partners, Online Platforms, Retail Outlets, Value-Added Resellers, Consultants |
| Companies Covered | Windstream, XO Communications, AT&T, EarthLink, Electric Lightwave, Verizon Communications, RCN, Frontier Communications, CenturyLink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Competitive Local Exchange Carriers (CLEC) Market Strategic Shifts & Innovations
Service unbundling and specialization define the market's evolution. Software-defined technologies are enabling enterprises to assemble best-of-breed network and communication solutions from multiple vendors, breaking the monolithic hold of traditional, fully integrated carrier contracts and creating openings for agile competitors.
Software-Defined Wide Area Networking (SD-WAN) provides centralized, software-based control over network traffic routing. Multi-site enterprises are adopting the technology to improve application performance and reduce reliance on expensive legacy circuits. As a consequence, SD-WAN is expanding into the domain traditionally held by MPLS, offering a more agile and cost-effective alternative for enterprise connectivity.
Regulatory frameworks mandating pro-competitive network access are a foundational element of the CLEC market. Rules requiring incumbents to lease unbundled network elements (UNEs) at regulated rates lower the barrier to market entry. The operations of CLECs in jurisdictions governed by the US Federal Communications Commission (FCC), India's TRAI, and Germany's BNetzA are directly shaped by these critical access policies.
A clear behavioral change sees enterprises moving from single-carrier relationships toward a multi-vendor sourcing model. This disaggregation of the traditional telecom contract allows businesses to select specialized providers for distinct services like voice, data, and security. This pattern is most evident in the medium and large enterprise segments, which require customized solutions for their complex IT environments.
Competitive Local Exchange Carriers (CLEC) Market Segmentation
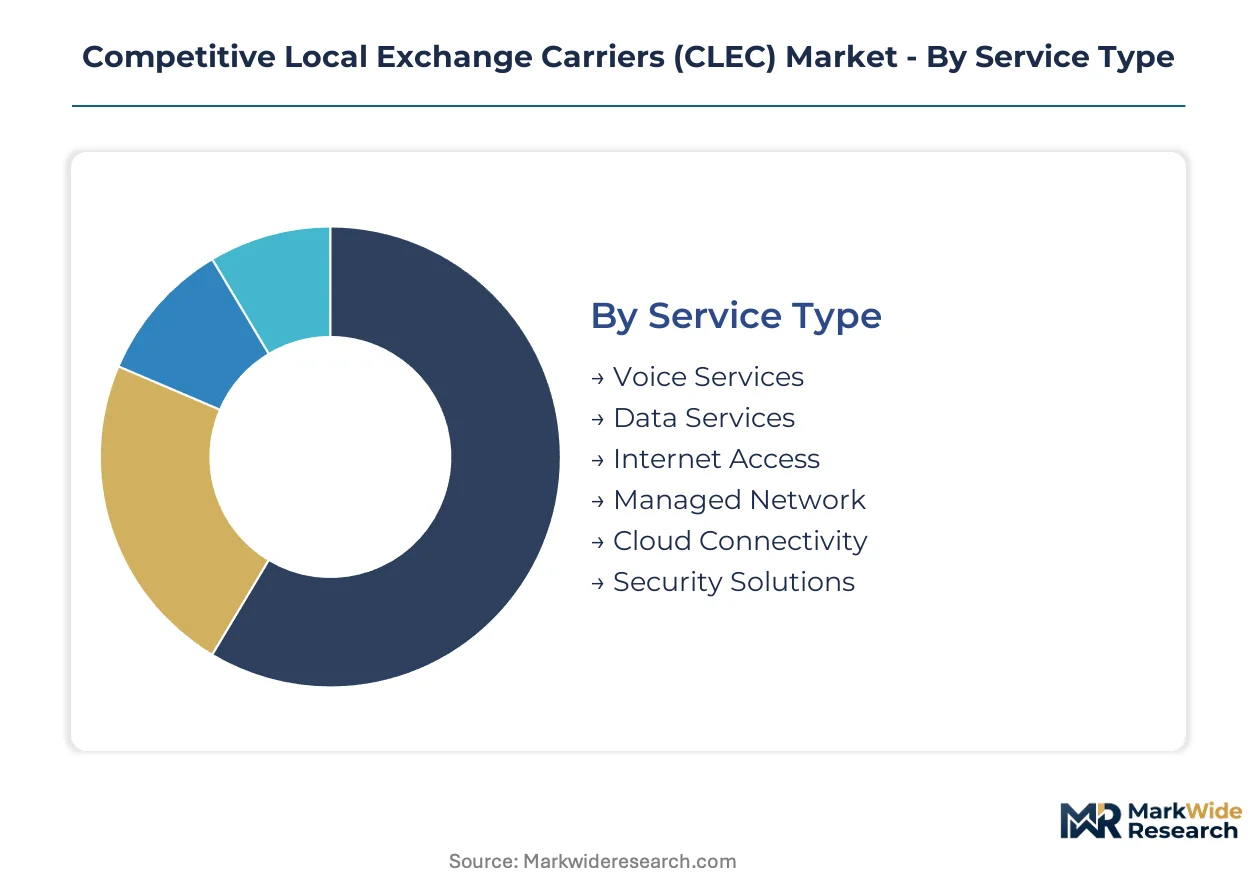
The Competitive Local Exchange Carriers (CLEC) market segmentation reveals how service providers tailor offerings to diverse customer needs and technological demands. Analyzing these distinct segments helps understand the varied competitive strategies and market opportunities available to CLECs.
Service Type:
The range of service types reflects the customization versus standardization spectrum in telecommunications offerings.
- Data Services:These encompass high-speed internet, dedicated internet access, and private line services, forming the backbone of enterprise connectivity. Demand for robust data services concentrates in metropolitan business districts and data centers, driven by cloud adoption.
- Cloud Connectivity:This segment provides direct, secure, and low-latency connections to major cloud service providers and data center ecosystems. Enterprises seek these connections for hybrid cloud deployments and mission-critical applications, particularly in financial services and tech sectors.
- Voice Services:Traditional and Voice over IP (VoIP) solutions provide communication capabilities for businesses.
- Internet Access:This includes broadband and dedicated internet services for general business use.
- Managed Network:CLECs offer outsourced management of customer network infrastructure, including routing and firewalls.
- Security Solutions:Services like DDoS mitigation, managed firewalls, and secure access service edge (SASE) protect enterprise data.
Most installed capacity flows through Data Services. Expansion is steepest in Cloud Connectivity.
Client Type:
Client types differentiate demand based on organizational scale, complexity, and specific telecommunication requirements.
- Medium Enterprises:Businesses in this segment require integrated data, voice, and cloud connectivity solutions that are more sophisticated than small business offerings. These enterprises often seek agile and cost-effective alternatives to incumbent contracts, driving CLEC expansion.
- Large Corporations:These entities demand highly customized, scalable, and secure network solutions, often across multiple locations. Large corporations prioritize reliability and advanced managed services for their complex IT environments.
- Small Businesses:These clients typically need basic internet access and voice services, often prioritizing cost-efficiency.
- Government Agencies:Public sector organizations require secure, compliant, and often redundant network infrastructure.
- Educational Institutions:Schools and universities need high-bandwidth connectivity for students and staff, supporting digital learning initiatives.
- Nonprofit Organizations:These groups seek reliable and affordable communication services to support their operational and outreach efforts.
The demand profile for Medium Enterprises is distinct from Small Businesses.
Technology:
The technology segment reflects the evolution of network infrastructure, from legacy systems to modern software-defined solutions.
- SD-WAN:Software-Defined Wide Area Networking provides centralized, software-based control over network traffic routing, improving application performance. Multi-site enterprises in India and other digital-first economies widely adopt SD-WAN to reduce reliance on expensive legacy circuits.
- Ethernet:This technology delivers high-speed, reliable local area network (LAN) and wide area network (WAN) connectivity, often over fiber optic infrastructure. Ethernet offers scalable bandwidth and is a preferred choice for data-intensive business operations.
- VoIP:Voice over Internet Protocol enables voice communication over internet networks, offering cost savings over traditional telephony.
- MPLS:Multi-Protocol Label Switching is a legacy network routing technology for high-performance telecommunications networks.
- Fiber Optic:This physical layer technology provides high-bandwidth, low-latency data transmission over optical fibers.
- Wireless Broadband:Technologies like 5G Fixed Wireless Access (FWA) offer alternative last-mile connectivity solutions for businesses.
Technological advancements continue to redefine offerings, with SD-WAN leading the shift.
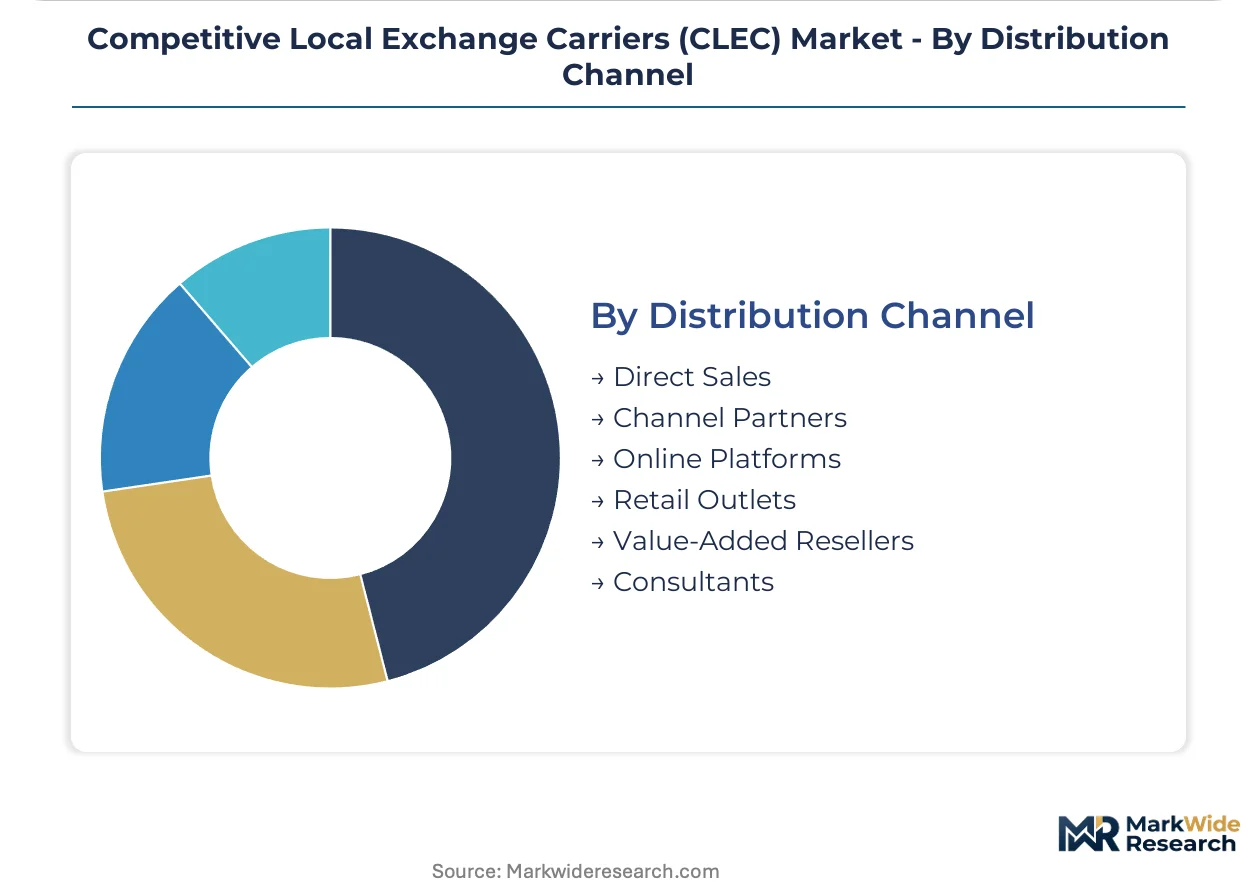
Distribution Channel:
Distribution channels illustrate how CLEC services reach end-users, highlighting the varying levels of direct engagement and partner leverage.
- Direct Sales:This channel involves CLECs selling services directly to end-user businesses through their own sales teams. Direct sales allow for deep customer relationships and customized solution development for large accounts.
- Channel Partners:CLECs collaborate with value-added resellers, system integrators, and master agents to extend their market reach. These partners often bundle CLEC connectivity with their own IT services, especially for medium enterprises.
- Online Platforms:Web-based portals and e-commerce sites allow businesses to research, configure, and purchase basic services.
- Retail Outlets:Physical locations offer a point of sale and customer service, primarily for small businesses or consumer-grade services.
- Value-Added Resellers:VARs integrate CLEC services with other technologies to provide comprehensive solutions.
- Consultants:Independent advisors recommend CLEC services as part of broader IT and network strategy engagements.
The effectiveness of Direct Sales often depends on the strategic alignment with Channel Partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan business districts globally drive demand for competitive local exchange carrier services, especially for high-bandwidth data and cloud connectivity. These regions benefit from regulatory frameworks that foster competition and enable specialized providers to offer agile, cost-effective network solutions to enterprises seeking alternatives to traditional incumbent carriers.
United States
Medium enterprises in the United States demand integrated data and voice services, alongside robust cloud connectivity solutions. The US Federal Communications Commission (FCC) mandates terms for network access, facilitating CLEC operations. Major technology hubs like Silicon Valley and New York City exhibit high concentrations of businesses requiring advanced telecommunications infrastructure.
Germany
German enterprises seek secure and managed network solutions, including SASE integration, to support their digital transformation initiatives. Germany's BNetzA enforces pro-competition policies, which enable CLECs to expand their service offerings. Industrial centers such as Munich and Frankfurt show strong demand for specialized network providers.
India
India's digital infrastructure development, a national priority, fuels demand for SD-WAN proliferation and fiber-based connectivity. The TRAI promotes a favorable environment for competitive carriers to expand their service footprint. Technology corridors in Bengaluru and Mumbai are experiencing rapid growth in enterprise connectivity needs.
United Kingdom
United Kingdom businesses prioritize flexible and cost-effective network solutions, particularly for data services and cloud access. National regulators in the UK enforce policies that support competitive network access for CLECs. Financial services firms in London and technology companies in Manchester require high-performance, resilient connectivity.
Japan
Japanese enterprises require high-bandwidth connections and reliable managed network services to support their advanced technological operations. National regulators in Japan oversee network access terms, contributing to a competitive telecommunications landscape. Business districts in Tokyo and Osaka show strong adoption of modern network solutions.
Competitive Local Exchange Carriers (CLEC) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces like cloud connectivity and SASE integration. The market structure exhibits a tiered consolidation, with large incumbents coexisting with specialized CLECs and agile, niche providers. Strategic archetypes include incumbent challengers, fiber infrastructure specialists, and managed services integrators. Competitive moves focus on fiber network expansion and portfolio diversification.
On the premium-tier vector, Verizon Communications operates in this segment alongside its established incumbent services, leveraging its broad portfolio. CenturyLink exemplifies a provider offering a broad portfolio of managed network and cloud connectivity solutions. Windstream represents a specialized CLEC, leveraging its extensive fiber network to serve enterprise clients with specific connectivity needs.
| Leading Market Players |
|---|
| Windstream |
| XO Communications |
| AT&T |
| EarthLink |
| Electric Lightwave |
| Verizon Communications |
| RCN |
| Frontier Communications |
| CenturyLink |
| Others |
Cost & Logistics Intelligence
Medium enterprises' demand for integrated data and voice services influences the pricing of customized CLEC solutions. Regulatory frameworks, such as those from the FCC and TRAI, also shape market pricing dynamics.
Pricing Analysis
The high capital expenditure for fiber infrastructure influences pricing, often passed through to enterprise customers. Contract-based long-term offtake agreements represent the dominant pricing model in this market. Price differentiation stems from the customization level required by large corporations and the volume scale for medium enterprises. Pricing softness reflects intense competition from incumbents and wireless substitution. Small businesses exhibit high price sensitivity, while large corporations prioritize reliability and advanced managed services.
Supply Chain Analysis
Direct sales channels handle complex enterprise client engagements, while channel partners support medium enterprise needs. Geographic supply concentration for core infrastructure components centers on countries like the US, India, and Germany. Raw material dependencies include fiber optic cables, specialized network hardware like routers and switches, and SD-WAN software licenses. A structural risk involves single-source vulnerability for unbundled network elements sourced from incumbent carriers. Distribution relies on a mix of direct sales and channel partnerships.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CLEC market is a late-cycle quality story, driven by enterprises demanding premium, secure, and low-latency cloud connectivity. This shift requires carriers to focus on high-performance infrastructure and specialized service offerings.
For Market Incumbents:
Anticipate continued decoupling of enterprise telecommunications spending from traditional contracts, driven by SD-WAN proliferation. Incumbents should leverage existing fiber assets to offer specialized cloud connectivity, countering the threat of agile CLECs. Strategic R&D in SASE integration can differentiate offerings against niche providers. Channel control through partnerships with system integrators can also reinforce market position.
For New Entrants and Emerging Players:
SD-WAN solutions provide a technology-first wedge for new entrants to target medium enterprises seeking cost-effective and flexible network management. Focus on underserved corridors and specific business parks lacking dense fiber infrastructure. A go-to-market angle emphasizing bundled SASE integration offers a compelling value proposition. Specialization in secure, low-latency cloud connectivity can penetrate high-value tech and financial sectors.
For Investors and Strategic Acquirers:
Hyperscale cloud providers are the most active acquirers in this space, seeking to deepen their network infrastructure control. Long-term viability hinges on CLECs with proprietary fiber assets in key metropolitan areas and strong cloud connectivity specializations. Acquisition targets include agile CLECs with established customer bases in high-growth segments. The signal to watch is the continued consolidation of regional fiber networks by larger telecom players.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Network Expansion | Expands proprietary infrastructure, reducing incumbent dependency and improving service agility. |
| SASE Integration | Bundles security with networking, meeting enterprise demand for integrated, secure solutions. |
| Cloud Interconnect Partnerships | Provides direct, low-latency access to major cloud platforms, enhancing service value. |
| Targeted Geographic Build-Outs | Focuses capital on underserved business areas, capturing niche market share. |
| Managed SD-WAN Overlay Services | Leverages software-defined networking to offer flexible, cost-effective enterprise solutions. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved combining in-depth interviews with telecom executives, IT procurement officers, network architects, and regulatory specialists. Secondary validation drew from FCC filings, TRAI reports, BNetzA publications, and enterprise technology adoption surveys. A robust bottom-up and top-down triangulation approach ensured data consistency.
Rate-of-change decomposition informed market projections across the analysis window. Segmentation dimensions modeled include service type, client type, technology, distribution channel, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) derived from historical trends and projected technological adoption rates. Key forecast inputs include enterprise digital transformation budgets and SD-WAN deployment forecasts.
The model holds under current regulatory stability and projected digital infrastructure investment; deviation in competitive intensity or significant policy changes would shift outcomes. Forecasts reflect assumptions regarding technology adoption and market competition. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Switzerland Telecom Market
Telecommunications
Global LTE Market
Telecommunications
Software Defined Radio Market
Telecommunications
South Korea Telecom Market
Telecommunications
Promotional Sms Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Thailand ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Germany ICT Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Australia Telecom Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Iceland Telecom Market
Telecommunications
Land Professional Mobile Radio Market