
 Microwave Backhaul System Market | 2026-2036
Microwave Backhaul System Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Backhaul System Market Foresight
The direct-to-operator channel is narrowing as vendor consolidation pressures independent distributors. Huawei Technologies leverages integrated radio and antenna platforms to sustain pricing power in emerging markets. Ericsson anchors European supply relationships through localized manufacturing partnerships. Ceragon Networks competes on spectral efficiency for dense urban deployments.
A microwave backhaul system transmits digital traffic between cell sites and core networks using directional antennas in licensed or unlicensed spectrum bands, typically operating from 6 GHz to 80 GHz with link distances from a few hundred meters to over 50 kilometers depending on frequency and environmental conditions. Its primary purpose is to provide cost-effective, rapidly deployable connectivity where fiber installation proves economically or physically impractical. Point-to-Point configurations dominate capital deployment for telecom operators due to deterministic capacity and latency performance, while Point-to-Multipoint architectures are gaining traction in enterprise private networks where hub-and-spoke economics reduce per-site infrastructure costs. All-Outdoor units lead in total volume for macro cell backhaul, though Indoor configurations retain margin pools in controlled-environment data center interconnections.
The Federal Communications Commission in the United States governs E-band and V-band licensing rules that directly determine available channel widths and transmit power limits for backhaul equipment deployment. The European Conference of Postal and Telecommunications Administrations harmonizes cross-border frequency coordination, shaping product certification requirements under CE marking protocols. India's Wireless Planning and Coordination Wing manages microwave spectrum allocation for telecom operators, influencing vendor market access conditions. Stakeholders must monitor pending spectrum reallocation proceedings across these jurisdictions to anticipate equipment refresh cycles and certification compliance timelines.
Market Dynamics
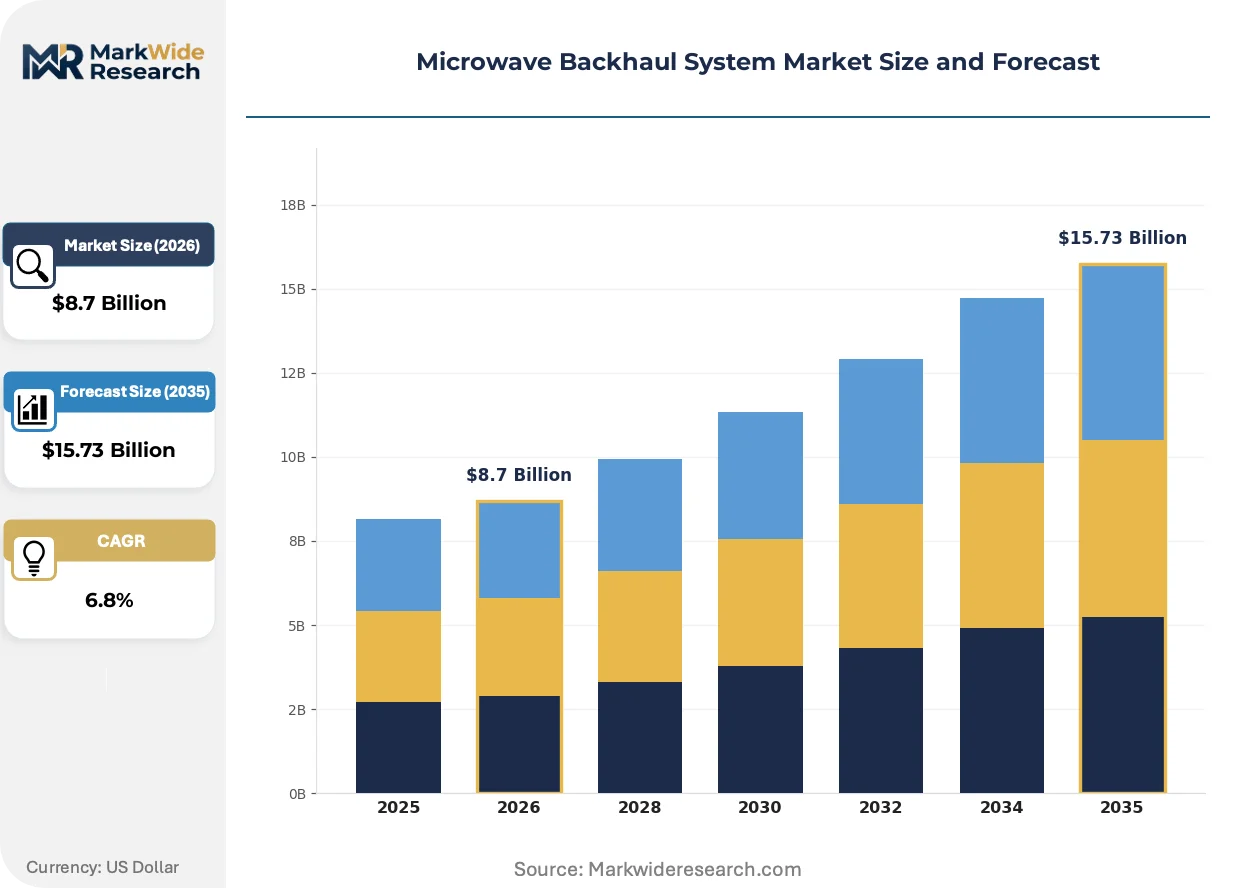
Spectrum liberalization across E-band and V-band frequencies is compressing equipment refresh cycles while forcing vendors to reconfigure radio architectures for wider channel widths and higher modulation schemes.
Growth Catalysts
- TRAI spectrum allocation rules:India's telecom regulator mandates specific backhaul capacity targets for 5G rollouts, compelling operators to upgrade microwave links in tier-2 and tier-3 cities.
- E-band frequency liberalization:Wider channel availability in the 71-76 GHz and 81-86 GHz ranges enables multi-gigabit backhaul without fiber trenching in dense urban corridors.
- Brazil infrastructure acceleration:ANVISA-aligned telecommunications investments under the national broadband plan are channeling capital toward microwave deployments in underserved municipalities.
Market Restraints
- Gallium nitride substrate costs:Power amplifier manufacturing depends on specialized semiconductor materials subject to supply bottlenecks from concentrated foundry capacity.
- Cross-border frequency coordination:CEPT harmonization delays create certification fragmentation, forcing vendors to maintain multiple product variants for adjacent European markets.
- Fiber substitution threat:Underground fiber deployments in metropolitan cores are capturing high-value backhaul contracts previously secured by microwave systems.
Strategic Opportunities
- Private 5G networks:Manufacturing campuses and mining operations in Brazil require non-public backhaul solutions where licensed spectrum microwave links bypass carrier infrastructure.
- CE marking streamlining:Proposed EU radio equipment directive amendments may collapse certification timelines, creating first-mover advantages for pre-compliant vendors.
- AI-driven link optimization:Machine learning algorithms converging with adaptive modulation hardware enable real-time bandwidth allocation in rain-fade conditions.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave link planning expertise concentrates among legacy telecom workforces nearing retirement.
- Multi-vendor interoperability testing:Operators demand seamless integration between antenna, radio, and transport layers, extending deployment validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Backhaul System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-to-Point, Point-to-Multipoint, All-Outdoor, Indoor Technology: Frequency Division Multiplexing, Time Division Multiplexing, Adaptive Modulation, MIMO Use Case: Telecommunications, Private Networks, Disaster Recovery, Urban Connectivity End User: Telecom Operators, Enterprises, Government Agencies, Service Providers |
| Companies Covered | Huawei Technologies, Ericsson, Nokia Corporation, Ceragon Networks, ZTE Corporation, NEC Corporation, Aviat Networks, Siklu Communication, SIAE Microelettronica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Backhaul System Market Shifts & Advancements
Carrier aggregation techniques and software-defined radio platforms are dissolving the boundary between traditional microwave hardware and virtualized network functions, enabling programmable capacity scaling.
Integrated radio-and-antenna platforms with embedded beamforming are rendering obsolete separate outdoor unit configurations that required coaxial cable runs and weatherproofing enclosures. Telecom operators in India and Brazil are standardizing on these all-in-one designs for rapid cell site activation. The consolidation compresses installation labor costs and reduces tower loading constraints.
CEPT harmonization decisions on 6 GHz band extensions are reshaping equipment certification roadmaps across European markets. Manufacturers must redesign filter banks and power amplifiers to accommodate prospective channel reallocations. The uncertainty is accelerating R&D spending on wideband-tunable architectures that can adapt without hardware swaps.
Network operators are consolidating vendor panels to reduce interoperability testing burdens, favoring suppliers with end-to-end microwave and fiber transport portfolios. This concentration is squeezing specialized radio-only vendors from large-scale RFP processes. The procurement compression is most pronounced in India, where Reliance Jio and Bharti Airtel have halved qualified supplier lists since 2022.
Microwave Backhaul System Market Segmentation
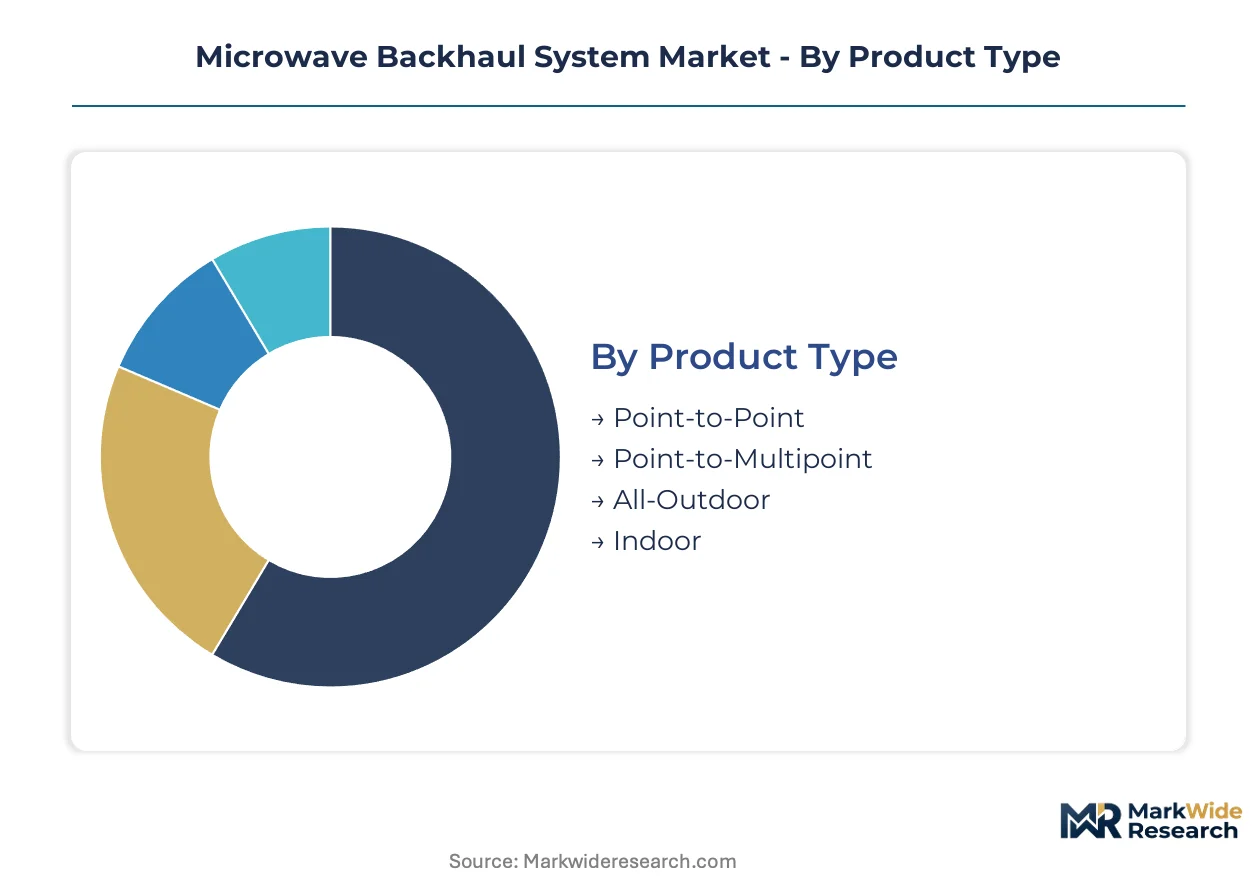
Microwave backhaul systems fragment across four distinct dimensions that govern procurement patterns and margin structures. Product architecture determines installation economics and tower loading requirements. Technology choices constrain spectral efficiency and link reliability under environmental stress. Use case segmentation separates carrier-grade deployments from private infrastructure investments. End user categories concentrate purchasing power among distinct buyer archetypes with divergent technical specifications and contract terms.
Product Type:
Architecture selection hinges on link distance requirements, environmental exposure tolerance, and site infrastructure constraints.
- Point-to-Point:Dedicated directional links between two fixed locations operate across licensed spectrum bands with deterministic latency guarantees. Telecom operators in India deploy these configurations for 4G and 5G macro cell backhaul under TRAI spectrum allocation rules, prioritizing capacity predictability over hub-and-spoke economics.
- Point-to-Multipoint:Hub stations communicate with multiple remote terminals using sectorized antennas, reducing per-site infrastructure costs through shared radio resources. Enterprise private networks in Brazil favor this architecture for manufacturing campus connectivity where fiber trenching faces ANVISA-aligned regulatory delays.
- All-Outdoor:Integrated radio and antenna units mount directly on towers or poles without shelter requirements, compressing installation timelines and eliminating climate-controlled enclosure costs.
- Indoor:Split-mount configurations separate radio units from baseband processing equipment housed in controlled environments, retaining margin pools for data center interconnections and central office deployments.
Point-to-Point holds installed capacity. All-Outdoor is rotating up the share rankings.
Technology:
Signal processing methods differentiate spectral efficiency, interference resilience, and hardware cost structures.
- Frequency Division Multiplexing:Allocates distinct carrier frequencies to separate data streams, enabling simultaneous transmission without temporal coordination overhead. Legacy telecom infrastructure in tier-2 Indian cities retains FDM dominance where equipment refresh cycles lag 5G deployment timelines.
- Adaptive Modulation:Dynamically adjusts constellation density and coding rates based on real-time link conditions, maximizing throughput during clear weather while preserving connectivity through rain fade events. Brazilian operators standardize on this technology for Amazon basin deployments where atmospheric attenuation varies seasonally.
- Time Division Multiplexing:Segments transmission into allocated time slots, optimizing spectrum utilization for symmetric traffic patterns.
- MIMO:Deploys multiple spatial streams through antenna diversity, multiplying link capacity without additional spectrum allocation.
Frequency Division Multiplexing dominates legacy deployments. Adaptive Modulation is climbing the fastest as operators prioritize link availability guarantees.
Use Case:
Application context determines performance thresholds, regulatory exposure, and procurement channel selection.
- Telecommunications:Carrier-grade backhaul connecting cell sites to core networks demands sub-millisecond latency and carrier-class reliability standards. Indian operators under TRAI-mandated 5G capacity targets drive volume concentration in this segment.
- Private Networks:Non-public infrastructure serving single enterprises or industrial campuses operates on licensed or lightly regulated spectrum. Mining operations in Brazil deploy microwave links to bypass carrier infrastructure where terrestrial connectivity remains underdeveloped.
- Disaster Recovery:Rapidly deployable temporary links restore connectivity when fiber cuts or natural disasters disrupt primary transport.
- Urban Connectivity:Dense metropolitan deployments prioritize compact form factors and visual integration with street furniture.
Telecommunications commands capital deployment. Private Networks is gaining share fastest as enterprise spectrum liberalization accelerates.
End User:
Buyer category shapes contract structures, technical specification authority, and vendor relationship dynamics.
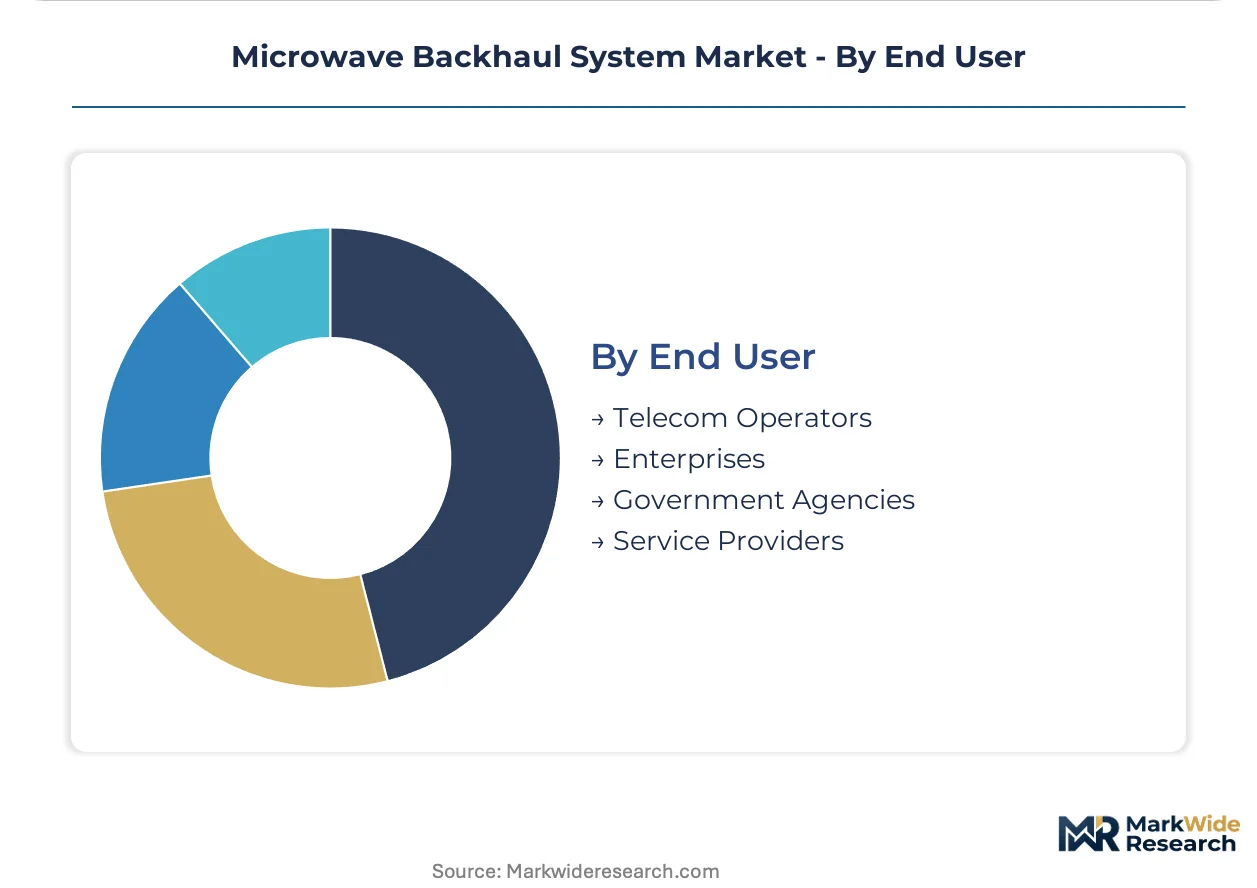
- Telecom Operators:Licensed carriers with spectrum holdings and tower infrastructure represent the volume anchor for equipment manufacturers. Reliance Jio and Bharti Airtel in India have consolidated vendor panels since 2022, halving qualified supplier lists and compressing procurement negotiation cycles.
- Enterprises:Manufacturing, logistics, and resource extraction companies procure private backhaul for campus and remote site connectivity. Brazilian industrial conglomerates under national broadband plan incentives channel capital toward microwave deployments in underserved municipalities.
- Government Agencies:Public sector procurement emphasizes interoperability standards and domestic content requirements.
- Service Providers:Neutral host operators and managed service vendors aggregate demand across multiple end users.
Telecom Operators anchor procurement volume. Enterprises is expanding most quickly as private 5G network investments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Indian procurement channels where consolidated operator panels compress vendor margins, while Brazilian infrastructure acceleration sustains premium equipment valuations through ANVISA-aligned project timelines.
United States
FCC E-band and V-band licensing rules govern channel widths and transmit power limits for backhaul deployment across metropolitan corridors. Equipment vendors redesign radio architectures to accommodate prospective 6 GHz band extensions under pending proceedings. Silicon Valley cluster firms drive adaptive modulation R&D for rain-fade resilience in coastal markets.
Germany
CEPT harmonization protocols shape cross-border frequency coordination requirements for microwave link certification. CE marking directives under EU radio equipment standards filter market access for non-compliant hardware. Bavaria-based industrial automation campuses deploy private 5G backhaul where fiber trenching faces regulatory delays.
India
TRAI spectrum allocation rules mandate specific backhaul capacity targets for 5G rollouts across tier-2 and tier-3 urban centers. Wireless Planning and Coordination Wing licensing procedures influence vendor market access conditions and equipment certification timelines. Maharashtra and Karnataka telecom clusters anchor macro cell deployment volumes for Reliance Jio and Bharti Airtel networks.
Brazil
ANVISA-aligned telecommunications infrastructure investments channel capital toward microwave deployments in underserved municipalities under national broadband plan frameworks. Mining operations in Amazon basin regions require licensed spectrum backhaul where terrestrial carrier infrastructure remains underdeveloped. São Paulo industrial corridors standardize on hub-and-spoke architectures for manufacturing campus connectivity.
Japan
METI spectrum coordination frameworks align microwave backhaul deployment with 5G base station densification targets in urban cores. JIS standards certification requirements filter equipment procurement for disaster recovery and emergency communications networks. Kanto region telecom operators consolidate vendor relationships around integrated radio-and-antenna platforms for rapid cell site activation.
Microwave Backhaul System Market Competitive Landscape
Integrated platform specialists and spectral efficiency innovators split the market between volume-driven emerging market deployments and performance-optimized dense urban configurations. The vendor base concentrates around three strategic archetypes: end-to-end transport portfolio providers, radio-only specialists competing on link optimization, and integrated hardware-software platform vendors. Consolidation pressures compress qualified supplier lists at major operators while M&A activity absorbs point-product vendors into broader networking portfolios.
Within the integrated platform tier, Huawei Technologies and Ericsson exemplify archetype positioning through geographic anchoring and supply relationship structures. Ceragon Networks occupies a position among spectral efficiency specialists competing for dense urban deployment contracts. ZTE Corporation and NEC Corporation represent scale-driven Asian-origin vendors with regional market penetration. Nokia Corporation and Aviat Networks sit within the transport portfolio category spanning microwave and fiber backhaul solutions.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia Corporation |
| Ceragon Networks |
| ZTE Corporation |
| NEC Corporation |
| Aviat Networks |
| Siklu Communication |
| SIAE Microelettronica |
| Others |
Supply & Pricing Matrix
Gallium nitride foundry concentration in Taiwan and the United States anchors power amplifier costs, compressing margin pools for radio-only vendors while integrated platform suppliers capture value through captive semiconductor sourcing.
Pricing Analysis
The customization-premium spread separates standard all-outdoor units from configured-to-order indoor split-mount systems with embedded beamforming. Project-based pricing dominates telecom operator procurement, with price differentiation hinging on spectral efficiency certification tiers and after-sales service bundling. Pricing pressure stems from vendor panel consolidation at Indian operators, where qualified supplier lists have halved since 2022. Enterprise private networks exhibit the highest price sensitivity due to hub-and-spoke architecture economics, while carrier-grade telecommunications deployments absorb premiums for deterministic latency guarantees.
Supply Chain Analysis
Supplier-financing facilities from integrated platform vendors have extended payment terms to 90-120 days for tier-2 distributors, locking in channel loyalty. Manufacturing concentrates in China, Finland, and Japan for radio assembly, with gallium nitride substrates and precision filter banks as critical component dependencies. Single-source vulnerability sits with concentrated foundry capacity for GaN-on-SiC wafers. Distribution runs through direct-to-operator channels that are narrowing as vendor consolidation pressures independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to 5G base station densification waves, with equipment refresh cycles compressing as E-band and V-band spectrum liberalization forces architectural redesigns.
For Market Incumbents: Build switching-cost moats through deep integration of radio and antenna platforms that eliminate multi-vendor interoperability testing burdens. Pursue backward integration into gallium nitride power amplifier production to defend against substrate supply bottlenecks. Extend certification pre-compliance investments across CE marking and FCC proceedings to accelerate product launch timelines when spectrum reallocations finalize. For New Entrants and Emerging Players: Tier-3 municipalities in Brazil under ANVISA-aligned national broadband frameworks represent the most penetrable entry point, with underserved fiber corridors creating demand for rapid-deploy microwave alternatives. Private 5G networks for mining and manufacturing campuses in Amazon basin regions offer white-space traction where carrier infrastructure remains underdeveloped. Lead with hub-and-spoke Point-to-Multipoint architectures that reduce per-site infrastructure costs against incumbent Point-to-Point dominance. For Investors and Strategic Acquirers: Capital is best deployed toward spectral efficiency specialists with adaptive modulation IP and dense urban deployment track records, as these capabilities command pricing power in capacity-constrained metropolitan corridors. Long-term viability over the next decade rests on software-defined radio platforms that bridge microwave hardware with virtualized network functions. Monitor CEPT harmonization proceedings on 6 GHz band extensions as the critical inflection signal for equipment refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Radio-Antenna Platform Development | Consolidates installation labor costs and reduces tower loading constraints for Indian operators. |
| Adaptive Modulation IP Acquisition | Secures spectral efficiency advantages for rain-fade resilience in Brazilian Amazon deployments. |
| CE Marking Pre-Compliance Investment | Creates first-mover positioning when EU radio equipment directive amendments collapse certification timelines. |
| Private 5G Network Partnership | Channels capital toward enterprise backhaul bypassing carrier infrastructure in underserved municipalities. |
| GaN Substrate Supply Agreement | Locks in power amplifier manufacturing capacity against concentrated foundry bottlenecks. |
Research Methodology
Operator-level perspectives from network planning engineers, procurement directors at tier-1 carriers, and RF engineering specialists anchored the qualitative base, cross-referenced with regulatory filings from TRAI, FCC, and CEPT proceedings. Secondary validation drew from equipment certification databases, spectrum allocation notices, and tower infrastructure deployment records. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against operator capex frameworks ensured consistency.
Scenario-bracketing around spectrum liberalization timelines and fiber substitution rates bounded the projection uncertainty across the analysis window. Segmentation dimensions modeled include product architecture, signal processing technology, use case context, and end-user procurement archetype. CAGRs were derived from installed base turnover rates and capacity upgrade cycles, with inputs from E-band channel width availability and 5G backhaul density targets.
Macroeconomic conditions sit as an overlay; deviation in carrier capital expenditure cycles or semiconductor foundry utilization would shift the trajectory. Forecasts reflect documented assumptions regarding spectrum harmonization progress and equipment refresh cadence. Regulatory reversal on frequency liberalization, supply disruption in gallium nitride substrates, or accelerated fiber trenching in metropolitan cores would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market