
 Wholesale Roaming Market | 2026-2036
Wholesale Roaming Market Size, Share, and Industry Trends Forecast 2026-2036
Wholesale Roaming Market Outlook
Specialized telecom engineering talent is redrawing competitive boundaries in wholesale roaming as 5G signaling complexity and IPX network management outpace traditional workforce training pipelines. Syniverse leverages its SS7-to-IPX migration expertise to anchor large operator consortiums in North America. BICS sustains extensive bilateral agreements across African and Middle Eastern corridors. Orange Wholesale competes through deep integration with the group's mobile subsidiaries spanning multiple continents.
Wholesale roaming denotes the commercial arrangement where one mobile operator permits subscribers from another operator to access its radio network and core infrastructure, typically governed by signaling protocols such as SS7, Diameter, or HTTP/2-based 5G interfaces and settled through cleared financial mechanisms. Its primary purpose is to ensure seamless subscriber connectivity across geographic boundaries while enabling host operators to monetize excess network capacity. Data services now dominate traffic volumes among service type segments, while bundled voice-SMS-data packages retain relevance for enterprise fleet clients. 5G roaming infrastructure represents the fastest-expanding technology segment, though 4G LTE still carries the majority of commercial traffic and associated margin pools.
GSMA wholesale roaming rate frameworks, EU roaming regulation remnants affecting inbound pricing psychology, and national telecom regulators in high-traffic corridors such as Brazil's ANATEL and India's TRAI collectively shape operator negotiation leverage and settlement transparency requirements. The EU F-Gas Regulation indirectly pressures cooling-dependent data center operators that host roaming exchange infrastructure to disclose environmental compliance to partner carriers. Stakeholders must monitor how 5G standalone network slicing standards redefine quality-of-service commitments in roaming service level agreements.
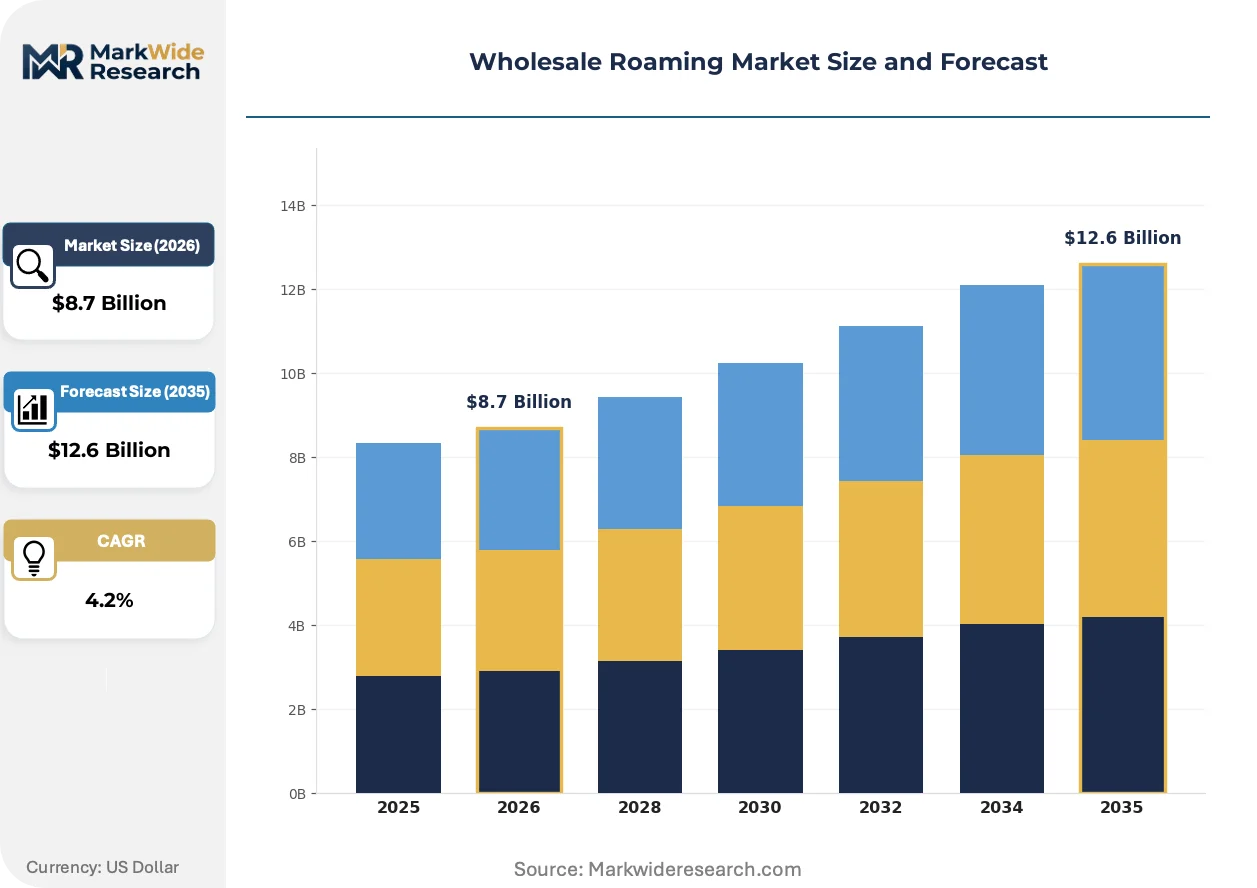
Market Dynamics
The wholesale roaming market pivots on 5G standalone network slicing standards that are redefining quality-of-service commitments and forcing operators to rebuild inter-carrier settlement frameworks from SS7-era protocols toward HTTP/2-based interfaces.
Growth Catalysts
- IoT Fleet Expansion:Connected vehicle and industrial sensor deployments are generating machine-to-machine roaming traffic that demands persistent IPX connectivity across Southeast Asian logistics corridors.
- EU F-Gas Regulation:Cooling-dependent data center operators hosting roaming exchange infrastructure must now disclose environmental compliance, accelerating partner carrier demand for certified green interconnection facilities.
- Tourism Recovery Patterns:Bilateral traffic volumes between Thailand, Vietnam, and Indonesia are climbing as cross-border labor mobility and leisure travel normalize post-pandemic mobility behaviors.
Market Restraints
- GSMA Rate Benchmark Compression:Standardized inter-operator settlement frameworks are eroding per-megabyte margins that previously subsidized legacy network maintenance costs.
- Signaling Protocol Fragmentation:Operators must simultaneously maintain SS7, Diameter, and HTTP/2 interfaces, multiplying engineering overhead without proportional revenue uplift.
- Regulatory Asymmetry:Brazil's ANATEL and India's TRAI impose divergent transparency requirements that complicate multi-party consortium negotiations for traffic exchange.
Strategic Opportunities
- 5G Standalone Roaming:Network slicing capabilities enable premium service tiering for enterprise clients requiring guaranteed latency for autonomous vehicle telemetry.
- African Corridor Development:Underpenetrated mobile money integration across East African Community member states creates whitespace for roaming-data bundling with financial services.
- EU CSRD Alignment:Sustainability reporting mandates are pushing operators to seek roaming partners with verified carbon disclosure, favoring early-compliant infrastructure providers.
Industry Challenges
- IPX Engineering Talent Scarcity:SS7-to-IPX migration expertise concentrates among a narrow cohort of specialists, constraining operator consortium formation timelines.
- Legacy Billing System Integration:Real-time charging platforms for 5G roaming require expensive retrofitting of pre-4G revenue assurance architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wholesale Roaming Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, SMS, Data, Bundled Services Client Type: Mobile Network Operators, MVNOs, Enterprises, Resellers Technology: 2G, 3G, 4G LTE, 5G Billing Model: Postpaid, Prepaid, Subscription-Based, Metered |
| Companies Covered | Cellusys, Vodafone Procure & Connect, Syniverse, Telna, Telefónica Global Solutions, BICS, Comfone, Mobileum, Orange Wholesale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wholesale Roaming Market Strategic Shifts
Wholesale roaming infrastructure is undergoing protocol-layer transformation as HTTP/2-based 5G signaling is displacing decades-old SS7 dominance, while regulatory pressure and buyer behavior shifts reshape commercial arrangements.
HTTP/2-based 5G interfaces are displacing SS7 and Diameter protocols as the default roaming signaling standard. Mobile Network Operators in North America and Western Europe are mandating HTTP/2 support in new bilateral agreements signed since 2023. This displacement is compressing the addressable market for legacy signaling hardware vendors while expanding demand for cloud-native IPX orchestration software.
REACH and EU F-Gas Regulation compliance requirements are cascading into roaming infrastructure procurement criteria. Data center operators hosting roaming exchange points must now document refrigerant management and embodied carbon in facility disclosures. German and French carriers are prioritizing interconnection partners with verified environmental product declarations for cooling systems.
Enterprise fleet managers are unbundling roaming services from traditional mobile network operator bundles. Logistics conglomerates in the Netherlands and Singapore are negotiating direct IPX access agreements for IoT device fleets, bypassing retail roaming markups. This disintermediation concentrates buying power among large fleet operators and pressures wholesale margin structures in high-volume corridors.
Wholesale Roaming Market Segmentation
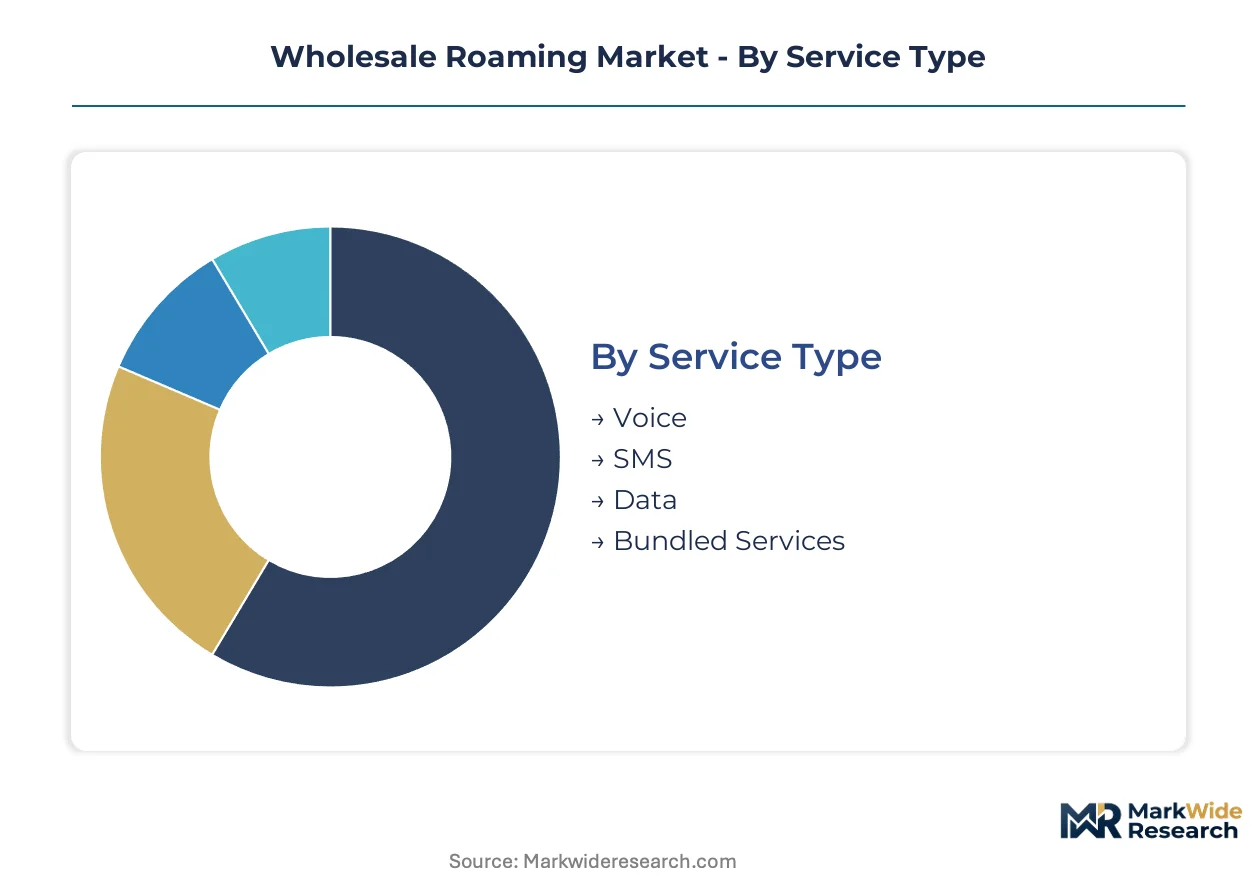
Wholesale roaming segmentation reveals how traffic monetization strategies diverge across service portfolios and customer archetypes. Each category reflects distinct technical requirements, settlement mechanisms, and margin structures that shape operator consortium formation and bilateral negotiation leverage.
Service Type:
Domestic traffic concentrates in voice and SMS for labor corridors within single countries, while data and bundled services drive cross-border export volumes across international roaming agreements.
- Voice:Circuit-switched and VoLTE roaming for person-to-person calling retains relevance in emerging markets with limited OTT penetration. Demand clusters in Southeast Asian labor corridors connecting Vietnam, Thailand, and Indonesia where cross-border worker remittance patterns sustain traditional calling behaviors.
- Data:IP-based packet roaming now dominates wholesale settlement volumes, driven by smartphone penetration and video consumption. Traffic concentrates in tourism corridors where inbound visitors from Germany, the United Kingdom, and South Korea generate disproportionate per-subscriber data consumption during short-stay periods.
- SMS:Declining person-to-person volumes persist for two-factor authentication and machine-to-machine signaling. Banking and logistics enterprises in Singapore and the Netherlands embed SMS roaming into fleet management protocols for reliable delivery confirmation.
- Bundled Services:Combined voice-SMS-data packages serve enterprise fleet clients seeking simplified procurement. German automotive and Dutch shipping conglomerates negotiate multi-service roaming agreements for connected vehicle and container tracking deployments.
Data holds the largest share; momentum sits with bundled services as enterprise procurement centralizes.
Client Type:
Cost tier differentiation separates premium-tier mobile network operators from price-sensitive resellers, with volume concentration and margin profiles diverging sharply across the four client archetypes.
- Mobile Network Operators:Tier-1 carriers with owned spectrum and radio access networks anchor wholesale roaming as both buyers and sellers. These operators in Germany, France, and South Korea drive HTTP/2 protocol adoption and 5G standalone roaming standards through bilateral consortium leadership.
- MVNOs:Mobile virtual network operators without infrastructure assets purchase wholesale roaming as a resale input. European and Japanese MVNOs concentrate buying power through hub-and-spoke arrangements with single host operators, compressing per-megabyte margins.
- Enterprises:Direct IPX access negotiations bypass traditional retail roaming markups for large device fleets. Logistics operators in the Netherlands and Singapore now source roaming connectivity independently of mobile network operator bundles.
- Resellers:Intermediary entities aggregate roaming capacity for niche geographic corridors or specialized use cases. African corridor specialists bundle roaming with mobile money services across East African Community member states.
Mobile network operators command the largest share; direct enterprise procurement is climbing the fastest as fleet disintermediation accelerates.
Technology:
Maturity curves separate legacy 2G/3G maintenance from 4G LTE volume dominance and 5G expansion trajectories, with infrastructure investment requirements scaling nonlinearly across generations.
- 2G:Legacy circuit-switched infrastructure persists in rural coverage extensions and machine-to-machine applications with decade-long device lifecycles. Maintenance demand concentrates in African and South Asian markets where 2G-enabled POS terminals and agricultural sensors remain economically viable.
- 3G:Transitional technology facing accelerated sunset schedules across European and East Asian markets. Remaining 3G roaming traffic funnels through maintained gateways primarily serving voice fallback and legacy IoT device populations.
- 4G LTE:Current volume and margin anchor for wholesale roaming, carrying the majority of commercial data traffic. LTE roaming agreements span the densest bilateral corridors including Germany-Switzerland, South Korea-Japan, and United Kingdom-Spain.
- 5G:HTTP/2-based standalone architecture enabling network slicing and quality-of-service tiering. Early adoption concentrates in North American and Western European operator consortiums mandating 5G roaming support in agreements signed since 2023.
4G LTE holds the largest share; 5G demonstrates the steepest expansion trajectory as standalone slicing standards mature.
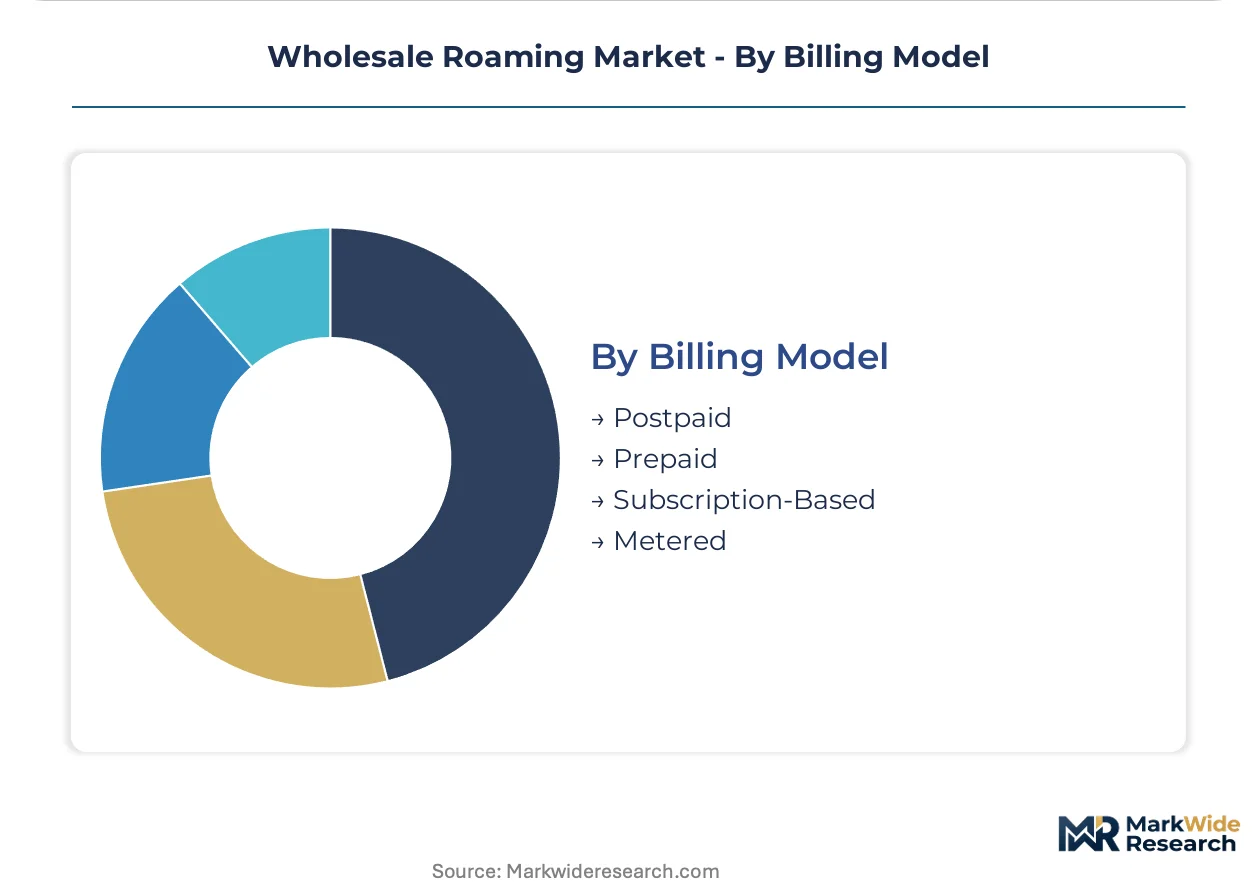
Billing Model:
Customer type and traffic predictability determine billing model selection, with postpaid arrangements dominating established operator relationships and prepaid structures serving volatile or credit-constrained segments.
- Postpaid:Traditional settlement mechanism with monthly invoicing based on cleared traffic volumes. Standard for tier-1 mobile network operator bilateral agreements in Germany, France, and South Korea with established credit relationships and predictable traffic patterns.
- Prepaid:Advance payment structures reducing counterparty credit risk in emerging market corridors. Common in African and Southeast Asian roaming agreements where currency volatility and regulatory transparency gaps complicate traditional settlement.
- Subscription-Based:Fixed-fee arrangements for enterprise fleets with predictable device counts and geographic footprints. Dutch logistics and German automotive operators favor subscription models for budget certainty across multi-year fleet deployments.
- Metered:Real-time charging platforms enabling granular usage-based settlement for variable traffic profiles. Required for 5G network slicing implementations where quality-of-service tiers demand instantaneous rating and balance management.
Postpaid holds the largest share; metered billing is gaining share fastest as real-time charging infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes wholesale roaming capacity differently than other markets, with enterprise fleet procurement driving direct IPX negotiations rather than traditional operator-mediated bundles. Brazil and India emphasize prepaid settlement structures due to currency volatility and regulatory transparency gaps. Southeast Asian corridors concentrate bilateral traffic growth from tourism recovery and cross-border labor mobility.
Germany
Automotive and logistics conglomerates negotiate multi-service roaming agreements for connected vehicle deployments. The country's national telecom regulator enforces transparency requirements that shape operator settlement frameworks. Berlin and Munich host dense clusters of tier-1 mobile network operators mandating HTTP/2 protocol adoption in bilateral consortiums.
United States
North American operator consortiums anchor 5G standalone roaming standards through HTTP/2 interface mandates in agreements signed since 2023. The FCC shapes inter-carrier negotiation leverage through disclosure requirements for network infrastructure. Dallas and Atlanta concentrate IPX exchange facilities where cloud-native orchestration software displaces legacy signaling hardware.
Brazil
ANATEL imposes transparency requirements that complicate multi-party consortium negotiations for traffic exchange. Prepaid settlement structures dominate due to currency volatility and regulatory asymmetry with partner markets. São Paulo anchors roaming exchange infrastructure serving South American logistics corridors with persistent machine-to-machine connectivity demands.
India
TRAI mandates divergent settlement transparency requirements that reshape operator negotiation leverage in high-traffic corridors. Prepaid billing models prevail as advance payment structures reduce counterparty credit risk. Mumbai and Bangalore concentrate mobile network operator headquarters driving bilateral agreement expansion across Southeast Asian tourism corridors.
Singapore
Logistics operators negotiate direct IPX access agreements for IoT device fleets, bypassing retail roaming markups. The country's national telecom regulator enforces environmental disclosure requirements that favor certified green interconnection facilities. The city-state hosts dense clusters of enterprise fleet managers centralizing procurement for container tracking deployments across regional shipping lanes.
Wholesale Roaming Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around signaling protocol expertise and geographic corridor coverage. Tier-1 integrated carriers leverage mobile subsidiary networks across multiple continents, while specialist hubs concentrate on SS7-to-IPX migration services and African corridor development. Strategic moves center on M&A activity targeting IPX engineering talent and partnerships with data center operators for certified green interconnection facilities.
Within the integrated carrier tier, Vodafone Procure & Connect and Orange Wholesale represent archetypes of deep mobile subsidiary network integration spanning multiple continents. Syniverse occupies a position exemplifying specialized SS7-to-IPX migration expertise that anchors large operator consortiums in North American markets. BICS sits within the corridor-specialist archetype, sustaining extensive bilateral agreements across African and Middle Eastern traffic routes where mobile money integration creates bundling opportunities.
| Leading Market Players |
|---|
| Cellusys |
| Vodafone Procure & Connect |
| Syniverse |
| Telna |
| Telefónica Global Solutions |
| BICS |
| Comfone |
| Mobileum |
| Orange Wholesale |
| Others |
Value Chain & Pricing Dynamics
Long-term bilateral roaming agreements with take-or-pay minimums anchor supply access for tier-1 mobile network operators while locking in rate visibility against GSMA benchmark compression. These contract structures concentrate procurement leverage among German automotive fleets and Dutch logistics operators seeking multi-year connectivity budgets.
Pricing Analysis
Subscription-based billing with volume-tiered discounts dominates enterprise fleet procurement, while postpaid settlement persists in operator-to-operator arrangements. Price differentiation rests on HTTP/2 protocol readiness and 5G standalone certification tier. Cost compression in data-per-megabyte rates is intensifying because GSMA wholesale benchmarks standardize inter-operator settlements. MVNOs exhibit highest price sensitivity due to hub-and-spoke buying concentration, whereas tier-1 mobile network operators with owned spectrum show lowest sensitivity.
Supply Chain Analysis
Inventory lead times for IPX orchestration software stretch across 12-18 month deployment cycles, constraining rapid consortium formation. Supply concentrates in the United States, Germany, and Singapore where cloud-native signaling infrastructure clusters. Engineering talent dependencies draw from SS7-to-HTTP/2 migration specialists and Diameter gateway maintainers. Single-source vulnerability sits with narrow cohorts of protocol engineers capable of 5G standalone integration. Distribution runs through bilateral operator negotiations rather than centralized exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wholesale roaming market tracks a cyclical recovery pattern as tourism corridors between Thailand, Vietnam, and Indonesia normalize post-pandemic mobility behaviors and restore bilateral traffic volumes.
For Market Incumbents: Consolidate SS7-to-IPX engineering talent through targeted acquisition of specialist teams in North American and Western European markets. Lock in long-term enterprise fleet contracts with German automotive and Dutch shipping conglomerates before direct IPX disintermediation accelerates. Prioritize 5G standalone certification investment to maintain premium tier positioning against price-sensitive MVNO entrants. For New Entrants and Emerging Players: Differentiate on mobile money integration capabilities across East African Community corridors where roaming-data bundling with financial services remains underpenetrated. Target African and Southeast Asian prepaid settlement corridors where currency volatility creates whitespace for alternative clearing mechanisms. Pursue direct IPX access negotiations with Singapore-based logistics operators seeking to bypass traditional retail roaming markups. For Investors and Strategic Acquirers: Capital is best deployed toward corridor-specialist hubs with proven African and Middle Eastern bilateral agreement networks and demonstrated mobile money bundling traction. Long-term viability hinges on HTTP/2 migration completion and 5G standalone slicing capability maturation. Watch for inflection signals in enterprise fleet direct procurement rates as a leading indicator of wholesale margin structure compression.| Strategic Initiative | Industry Significance |
|---|---|
| SS7-to-HTTP/2 Protocol Migration | Enables 5G standalone roaming and network slicing for enterprise latency guarantees. |
| Green Interconnection Certification | Aligns with EU F-Gas Regulation and REACH compliance for data center partner selection. |
| African Corridor Development | Captures mobile money bundling opportunities across East African Community member states. |
| Enterprise Direct IPX Access | Bypasses retail roaming markups for German automotive and Dutch logistics fleet procurement. |
| IPX Engineering Talent Acquisition | Addresses scarcity constraints constraining operator consortium formation timelines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with wholesale roaming executives, IPX network engineers, enterprise fleet procurement managers, and mobile money platform operators; and secondary validation through GSMA rate benchmark publications, national telecom regulatory filings from ANATEL and TRAI, and operator bilateral agreement disclosures. Bottom-up traffic volume modeling triangulated against top-down market sizing from infrastructure capacity disclosures.
Across the analysis window, forecasts integrated service type segmentation by voice, data, SMS, and bundled offerings; client type differentiation across mobile network operators, MVNOs, enterprises, and resellers; technology generation splits from 4G LTE through 5G standalone; and billing model variation between postpaid, prepaid, subscription, and metered structures. CAGRs derived from traffic volume elasticity against tourism recovery patterns and IoT fleet deployment trajectories.
Material uncertainties — regulatory asymmetry between Brazil's ANATEL and India's TRAI, GSMA rate benchmark compression timing, and 5G standalone slicing standard finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions about protocol migration completion and enterprise procurement centralization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
United States Contract Manufacturing Services Market
Information and Communication Technology
Global Address Verification Software Market
Information and Communication Technology
3D Printer Market
Information and Communication Technology
Test Management Software Market
Information and Communication Technology
Vietnam Data Center Server Market
Information and Communication Technology
Europe Intralogistics Automation Market
Information and Communication Technology
POS Restaurant Management System Market
Information and Communication Technology
Building Information Modeling (BIM) Extraction Software Market
Information and Communication Technology
Digital Dispenser Systems Market
Information and Communication Technology
Automotive Dealer Management Systems (DMS) Market
Information and Communication Technology
IoT IAM Market
Information and Communication Technology
India Sports Management Software Market
Information and Communication Technology
Global 4G LTE Market
Information and Communication Technology
Global Smart Leak Detection Solutions Market
Information and Communication Technology
Global Client Management Tools Market
Information and Communication Technology
Global Terminal Management System Market