
 Australia Mobile Virtual Network Operator (MVNO) Market | 2026-2036
Australia Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mobile Virtual Network Operator (MVNO) Market Insights
eSIM technology is consolidating subscriber onboarding economics across the Australia Mobile Virtual Network Operator (MVNO) landscape. Kogan Mobile leverages its retail ecosystem to bundle mobile plans with consumer electronics purchases. Amaysim Mobile Pty Ltd anchors its position through aggressive unlimited data pricing that undercuts tier-one carriers. Boost Mobile differentiates via exclusive access to Telstra's full retail network footprint rather than wholesale-only coverage.
A Mobile Virtual Network Operator leases wholesale network capacity from infrastructure-owning Mobile Network Operators and resells mobile services under its own brand, typically operating through cloud-native billing platforms and digital-first customer acquisition channels with minimal physical retail presence. The prepaid pricing strategy segment dominates subscriber acquisition volumes among budget-conscious consumers and temporary residents. Full MVNO service models capture the highest margin pools due to network switching and core infrastructure control, while 5G technology deployment is expanding addressable segments into fixed wireless home broadband substitution.
The Australian Competition and Consumer Commission enforces wholesale access obligations under the Telecommunications Act, compelling MNOs to supply regulated network capacity that underpins MVNO viability. The Australian Communications and Media Authority administers numbering rights, spectrum compliance, and consumer protection codes that shape product design and disclosure requirements. Stakeholders must monitor ACCC pricing determinations and 5G wholesale rate renegotiations as these directly compress or expand MVNO margin sustainability.
Market Dynamics
eSIM technology and 5G wholesale rate renegotiations are compressing subscriber acquisition costs while forcing MVNOs to rebuild pricing models around data-centric value propositions rather than voice-centric bundles.
Growth Catalysts
- ACCC Wholesale Access Rules:The Competition and Consumer Act mandates regulated network capacity supply from Telstra, Optus, and TPG Telecom, creating a legislated foundation for MVNO market entry and margin sustainability.
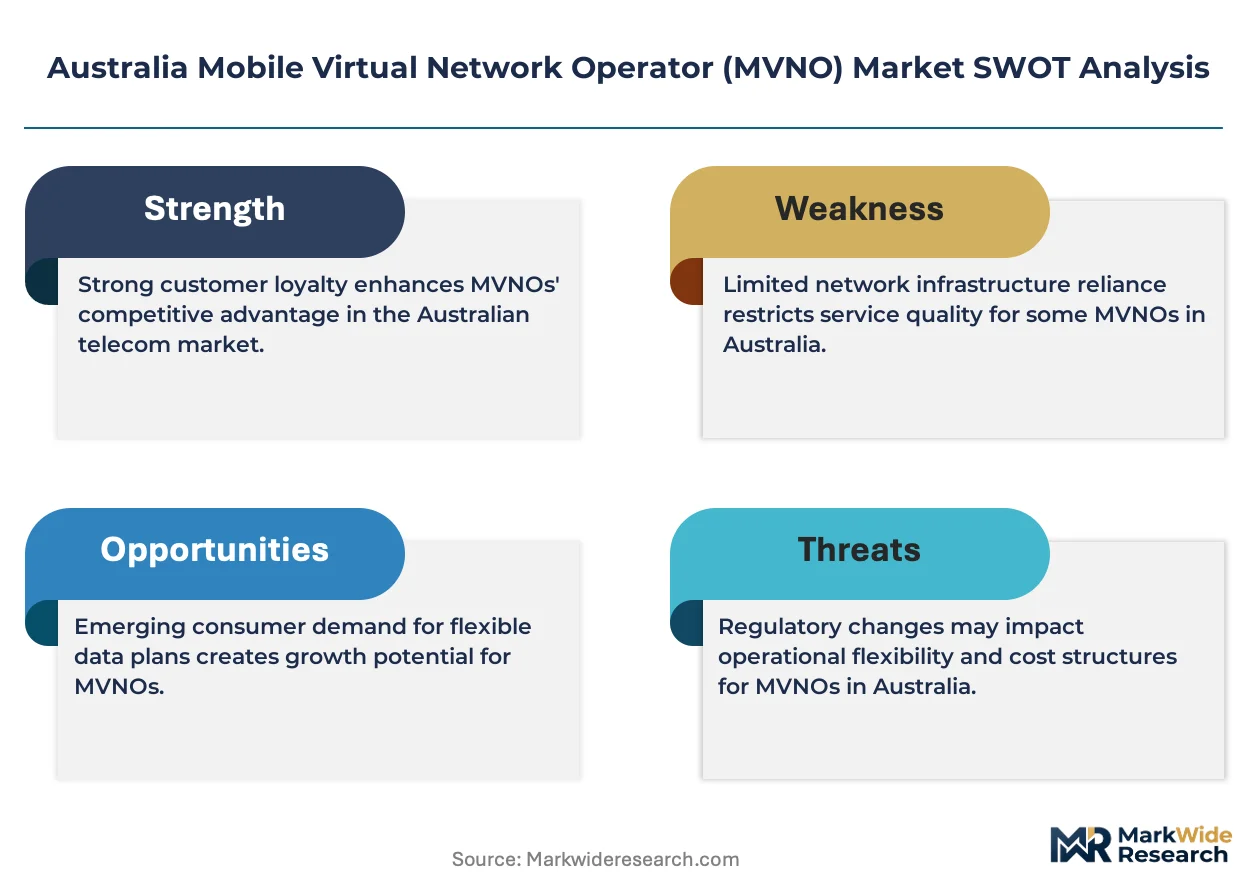
- Prepaid Plan Demand:Budget-conscious consumers and temporary residents in metropolitan Sydney and Melbourne corridors are driving volume concentration in no-contract, unlimited data offerings.
- Cloud-Native Billing Platforms:Digital-first customer acquisition channels and automated provisioning systems are eliminating physical retail overhead and enabling rapid plan customization.
Market Restraints
- Wholesale Rate Volatility:5G capacity pricing remains unsettled between MNOs and resellers, creating margin compression risk for full MVNO service models dependent on network switching control.
- Infrastructure Supplier Concentration:Three Mobile Network Operators control all macro network assets in Australia, limiting bargaining power for independent virtual operators during contract renewals.
- Coverage Gap Limitation:Wholesale-only network access excludes Telstra's full retail footprint, constraining regional and rural service differentiation for most MVNOs outside Boost Mobile's exclusive arrangement.
Strategic Opportunities
- Fixed Wireless Home Broadband Substitution:5G technology deployment is enabling MVNOs to address NBN displacement demand in Queensland and Western Australia outer suburbs with competitive data allowances.
- ACMA Consumer Protection Code Alignment:Enhanced disclosure requirements under Australian Communications and Media Authority administration are creating trust differentiation for compliant operators.
- Consumer Electronics Bundling Convergence:Retail ecosystem integration between mobile plans and hardware purchases is opening subscriber acquisition channels beyond traditional telecommunications marketing.
Industry Challenges
- Numbering Rights Compliance Timeline:ACMA spectrum compliance and numbering administration processes impose administrative burdens that delay product launches and plan modifications.
- Legacy Billing Integration Complexity:MVNOs acquiring subscribers from MNO porting processes face system interoperability friction with established carrier provisioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mobile Virtual Network Operator (MVNO) Market |
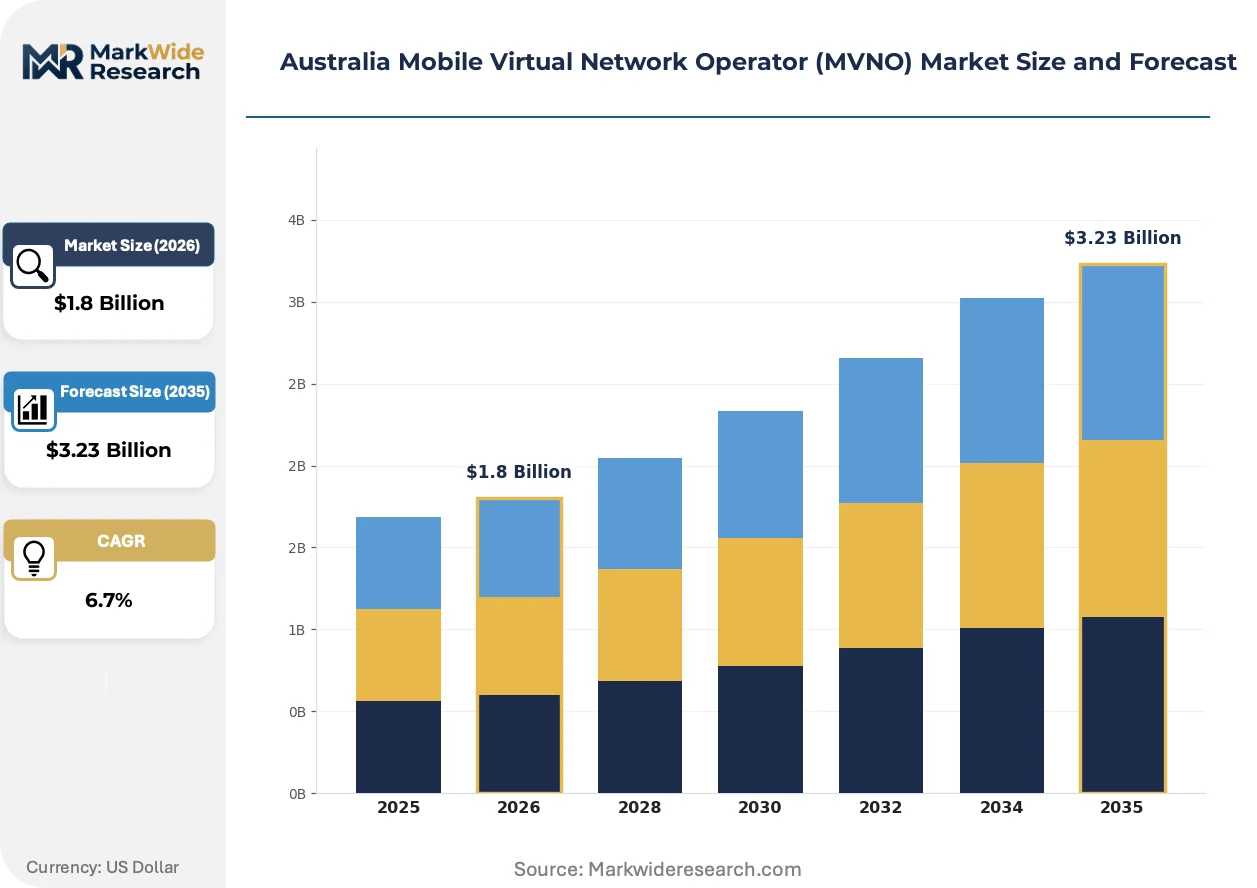
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Full MVNO, Light MVNO, Branded Reseller, Affiliate MVNO Customer Segment: Consumer, Business, Enterprise, Wholesale Technology: LTE, 5G, Wi-Fi Calling, VoLTE Pricing Strategy: Prepaid, Postpaid, Unlimited Plans, Tiered Plans |
| Companies Covered | Kogan Mobile, Lyca Mobile, Boost Mobile, Activ8me, Moose Mobile, Amaysim Mobile Pty Ltd, Lebara Mobile, Tangerine Telecom, ALDImobile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mobile Virtual Network Operator (MVNO) Market Trends and Innovations
Digital identity verification and automated provisioning pipelines are compressing subscriber onboarding from days to minutes, while regulatory pressure on wholesale transparency is forcing new commercial frameworks between network owners and resellers.
eSIM technology is consolidating subscriber onboarding economics across the Australia Mobile Virtual Network Operator landscape. Digital-first consumers in New South Wales and Victoria metropolitan corridors are adopting embedded SIM provisioning at accelerated rates. The technology is consolidating physical SIM logistics costs and enabling instant plan activation without retail intermediary involvement.
The ACCC's ongoing wholesale access determinations under the Telecommunications Act are reshaping network resale commercial terms. Regulated pricing benchmarks for 5G capacity are creating predictable input cost structures for virtual operators. Full MVNO service models with network switching infrastructure are capturing margin advantages from these transparency mandates.
Prepaid plan procurement through direct digital channels is displacing traditional retail brokerage for budget-conscious segments. Younger demographics and temporary residents are bypassing physical storefronts for app-based plan comparison and instant activation. This behavioral shift concentrates subscriber acquisition investment in search optimization and comparison platform presence rather than location-based retail networks.
Australia Mobile Virtual Network Operator (MVNO) Market Segmentation
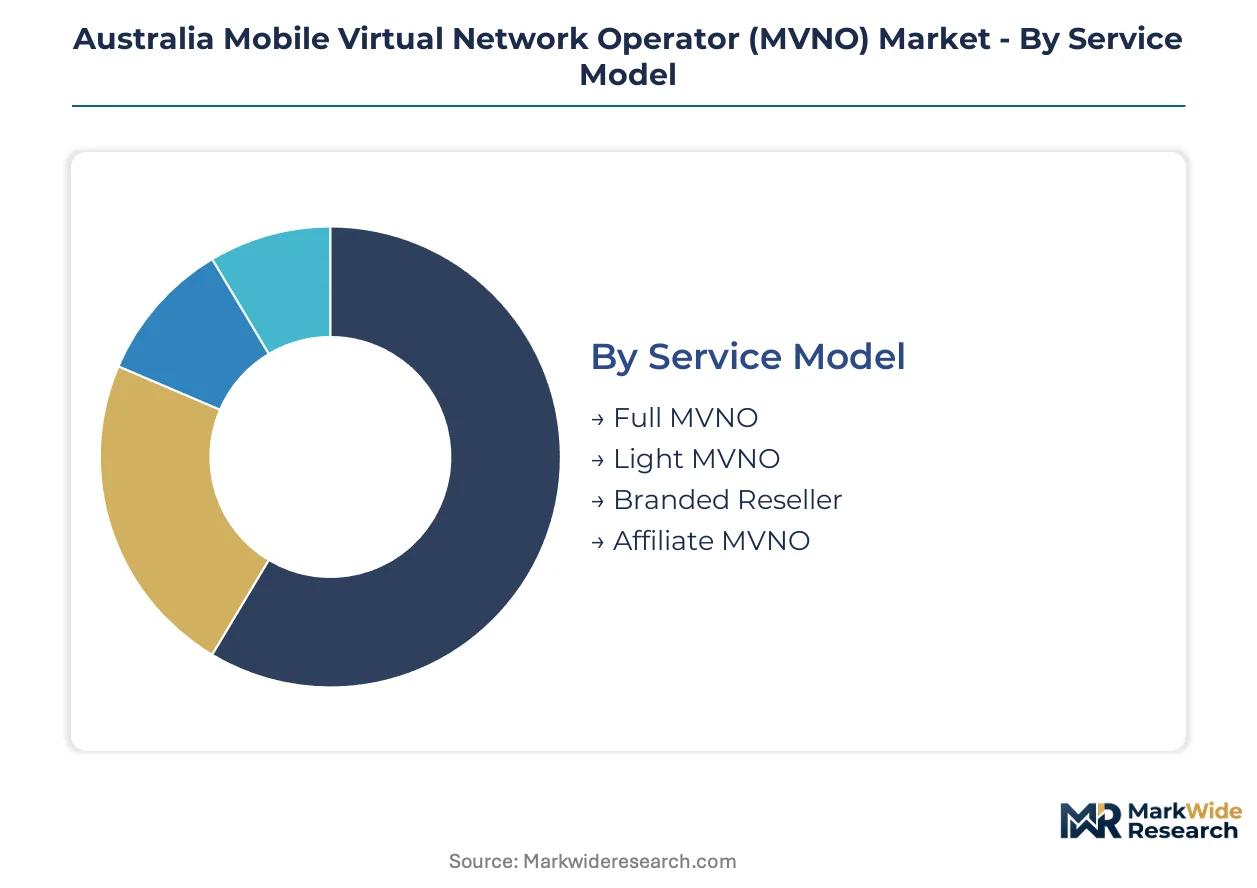
MVNO business models in Australia diverge sharply in infrastructure control, customer acquisition economics, and margin sustainability. Segmentation reveals which configurations capture wholesale rate advantages under ACCC-mandated access rules versus those locked into thin-reseller economics.
Service Model:
ACCC wholesale access determinations under the Telecommunications Act impose distinct compliance burdens across service model tiers, with core network control triggering numbering rights administration and spectrum compliance obligations through ACMA.
- Full MVNO:Operators maintain dedicated core network infrastructure with independent switching and routing capabilities. Sydney and Melbourne metropolitan corridors concentrate procurement from enterprises requiring guaranteed quality-of-service SLAs and custom APN configurations.
- Light MVNO:Resellers lease both radio access and core network elements from host MNOs, operating through cloud-native billing platforms without switching infrastructure. Queensland and Western Australia outer suburbs show expanding uptake for fixed wireless home broadband substitution where capital constraints prevent full MVNO investment.
- Branded Reseller:Thin-layer operators white-label existing MNO plans with minimal technical differentiation, relying entirely on parent network provisioning systems and customer service platforms.
- Affiliate MVNO:Retail ecosystem participants bundle mobile services with core product offerings, leveraging existing customer relationships and transaction data for cross-sell economics.
Leading the category by volume: Light MVNO. Growing fastest: Full MVNO.
Customer Segment:
Procurement patterns across customer segments track directly to contract duration preferences and data volume requirements, with enterprise accounts demanding multi-year agreements that contrast sharply with prepaid consumer flexibility.
- Consumer:Individual subscribers prioritize no-contract flexibility and unlimited data allowances. New South Wales and Victoria metropolitan corridors dominate volume, driven by temporary residents and budget-conscious demographics.
- Business:Small and medium enterprises seek pooled data arrangements and simplified fleet management. These accounts concentrate in professional services and construction verticals across Australian state capitals.
- Enterprise:Large organizations negotiate custom SLAs with dedicated account management and integration into unified communications platforms.
- Wholesale:Sub-reseller arrangements enable regional ISPs and niche service providers to extend mobile offerings without direct MNO negotiations.
Dominating revenue concentration: Enterprise. Expanding most quickly: Business.
Technology:
Network technology selection determines coverage footprint eligibility and wholesale rate structures, with 5G capacity pricing remaining unsettled between MNOs and resellers despite ACCC transparency mandates.
- LTE:Mature 4G infrastructure delivers predictable wholesale economics and universal device compatibility. Regional and rural deployments continue relying on LTE where 5G radio densification remains uneconomical.
- 5G:Next-generation capacity enables fixed wireless home broadband substitution with competitive data allowances. Telstra's full retail network footprint, accessible exclusively through Boost Mobile, creates coverage differentiation unavailable to wholesale-only operators.
- Wi-Fi Calling:Native handset integration extends service continuity into buildings and underground spaces with poor macro coverage.
- VoLTE:Voice-over-LTE provisioning eliminates circuit-switched fallback requirements, simplifying device certification and improving spectral efficiency.
Highest volume deployment: LTE. Steepest expansion trajectory: 5G.
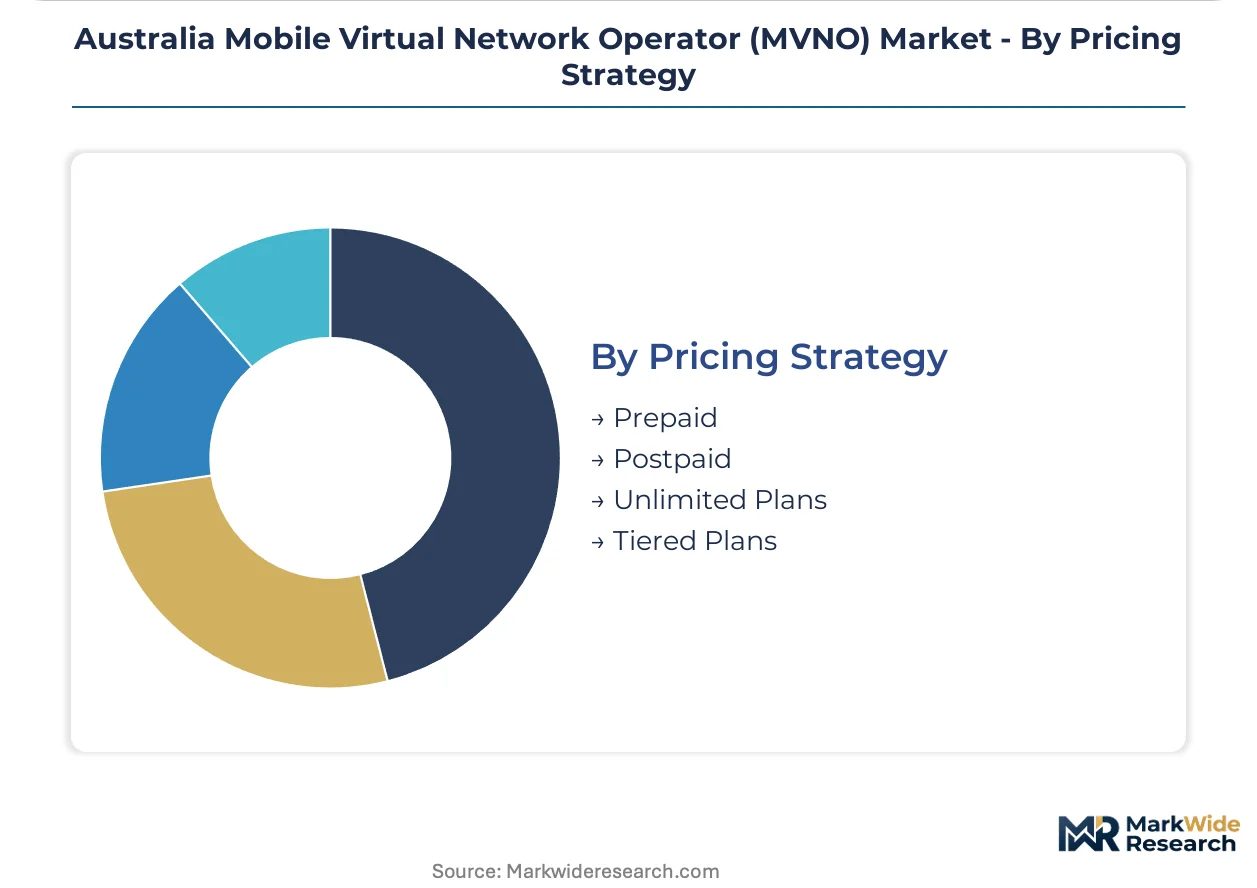
Pricing Strategy:
Margin structures across pricing strategies reflect customer lifetime value trade-offs against acquisition cost recovery, with prepaid economics favoring digital-first distribution and postpaid arrangements supporting handset subsidy models.
- Prepaid:No-contract arrangements with upfront payment eliminate credit risk and churn penalties. Budget-conscious consumers and temporary residents in metropolitan Sydney and Melbourne drive volume concentration.
- Postpaid:Monthly billing with device financing integration captures higher ARPU through handset ecosystem lock-in and automatic renewal mechanics.
- Unlimited Plans:Flat-rate data allowances with deprioritization thresholds simplify value propositions and reduce customer service interactions around overage disputes.
- Tiered Plans:Usage-based pricing with data buckets targets light users and IoT deployments where connectivity requirements remain predictable and capped.
Capturing greatest subscriber volume: Prepaid. Gaining share fastest: Unlimited Plans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan corridors in New South Wales and Victoria concentrate MVNO subscriber acquisition, driven by prepaid plan demand from temporary residents and budget-conscious consumers. Digital-first distribution channels and cloud-native billing platforms eliminate physical retail overhead in these dense urban markets. The ACCC's wholesale access rules under the Competition and Consumer Act create uniform regulatory conditions across Australian states.
New South Wales
Sydney's metropolitan corridor anchors the highest MVNO subscriber density, fueled by international student populations and gig economy workers seeking no-contract flexibility. The Australian Competition and Consumer Commission enforces wholesale access obligations that compel Telstra, Optus, and TPG Telecom to supply regulated network capacity to virtual operators. Parramatta and Western Sydney sub-regions show expanding uptake of fixed wireless home broadband substitution as 5G radio densification progresses.
Victoria
Melbourne's inner suburbs and university precincts drive prepaid plan volumes among temporary residents and young professionals prioritizing unlimited data allowances. ACMA numbering rights administration and spectrum compliance requirements shape product launch timelines for MVNOs entering this market. The Docklands and Southbank commercial clusters concentrate small and medium enterprise accounts seeking pooled data arrangements with simplified fleet management.
Queensland
Brisbane's outer suburbs and Gold Coast corridor generate demand for fixed wireless home broadband substitution as NBN displacement accelerates. The ACCC's ongoing wholesale access determinations create predictable input cost structures for virtual operators targeting this geography. Southeast Queensland's regional centers face coverage gap limitations where wholesale-only network access excludes Telstra's full retail footprint.
Western Australia
Perth's metropolitan area and outer suburban expansion zones show growing MVNO adoption for 5G-enabled home broadband alternatives. ACMA consumer protection codes mandate enhanced disclosure requirements that shape product design for operators entering this market. The Pilbara and regional mining corridors remain underserved due to infrastructure supplier concentration among three Mobile Network Operators controlling all macro network assets.
Australia Mobile Virtual Network Operator (MVNO) Market Competitive Landscape
Service model diversification dominates the current landscape as operators rebuild economics around data-centric value propositions. The market structures around three infrastructure-dependent tiers: full MVNOs with network switching control, light MVNOs leasing core and radio access, and thin-layer branded resellers. Strategic archetypes include retail ecosystem bundlers, aggressive unlimited data pricers, and exclusive network access arrangers. Competitive intensity concentrates on wholesale rate renegotiations and eSIM-enabled subscriber onboarding compression.
Within the retail ecosystem bundler archetype, Kogan Mobile leverages its consumer electronics platform for cross-sell economics. Amaysim Mobile Pty Ltd occupies a position exemplifying aggressive unlimited data pricing that undercuts tier-one carriers. Boost Mobile anchors the exclusive network access tier through its arrangement for Telstra's full retail footprint rather than wholesale-only coverage. These three operators represent distinct margin sustainability models under ACCC-mandated wholesale access rules.
| Leading Market Players |
|---|
| Kogan Mobile |
| Lyca Mobile |
| Boost Mobile |
| Activ8me |
| Moose Mobile |
| Amaysim Mobile Pty Ltd |
| Lebara Mobile |
| Tangerine Telecom |
| ALDImobile |
| Others |
Pricing and Supply Chain Analysis
Captive wholesale network access through the ACCC's mandated infrastructure sharing anchors both supply position and pricing power for Australian MVNOs, with exclusive Telstra retail footprint arrangements commanding premium positioning unavailable to wholesale-only resellers.
Pricing Analysis
Volume concentration in prepaid unlimited data plans runs against margin capture in full MVNO service models with network switching control. Price differentiation rests on coverage footprint exclusivity and core infrastructure ownership rather than brand premium alone. Cost compression in light MVNO tiers is intensifying because 5G wholesale rate renegotiations remain unsettled between MNOs and resellers. Budget-conscious consumers and temporary residents in Sydney and Melbourne corridors exhibit highest price sensitivity, while enterprise accounts with custom SLA requirements show lowest.
Supply Chain Analysis
Logistics and provisioning cost structures center on cloud-native billing platforms and digital identity verification pipelines that displace physical SIM distribution. Network capacity sourcing draws from Telstra, Optus, and TPG Telecom infrastructure concentrated in New South Wales and Victoria metropolitan corridors. Single-source vulnerability manifests in numbering rights administration delays through ACMA that extend product launch timelines. Distribution runs through app-based direct channels and retail ecosystem bundling partnerships rather than location-based storefront networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian MVNO landscape reads as a consolidation play where wholesale rate volatility and 5G capacity pricing uncertainty will force thinner-margin branded resellers toward acquisition or exit.
For Market Incumbents: Lock in exclusive network access arrangements and core switching infrastructure before 5G wholesale rate renegotiations conclude. Prioritize fixed wireless home broadband substitution capabilities in Queensland and Western Australia outer suburbs where NBN displacement demand is accelerating. Defensive consolidation of cloud-native billing platforms will counter emerging retail ecosystem bundlers with captive customer acquisition channels. For New Entrants and Emerging Players: Begin with underserved regional mining corridors in Western Australia's Pilbara where infrastructure supplier concentration among three MNOs has left coverage gaps. Target small and medium enterprise pooled data arrangements in professional services verticals where fleet management simplification commands premium positioning. Go-to-market execution should leverage eSIM-enabled instant provisioning to bypass legacy billing integration complexity with established carrier systems. For Investors and Strategic Acquirers: Exit pathways concentrate in full MVNO acquisitions with network switching infrastructure and independent core network control. Long-term viability across the analysis window favors operators with guaranteed quality-of-service SLA capabilities and custom APN configuration offerings for enterprise accounts. The signal to watch is ACCC pricing determinations on 5G wholesale rates, which will compress or expand margin sustainability for infrastructure-dependent tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed Wireless Home Broadband Expansion | Addresses NBN displacement demand in Queensland and Western Australia outer suburbs with competitive data allowances. |
| eSIM Technology Integration | Compresses subscriber onboarding from days to minutes while eliminating physical SIM logistics costs entirely. |
| Retail Ecosystem Bundling | Opens subscriber acquisition channels beyond traditional telecommunications marketing through consumer electronics integration. |
| Full MVNO Infrastructure Investment | Captures margin advantages from ACCC transparency mandates through network switching and core control. |
| Enterprise SLA Customization | Secures multi-year agreements with dedicated account management in Docklands and Southbank commercial clusters. |
Research Methodology
Document review covered ACCC wholesale access determinations, ACMA numbering rights administration records, and Telecommunications Act compliance frameworks, complemented by interviews with MVNO operations executives, MNO wholesale partnership managers, and cloud-native billing platform engineers. Secondary validation drew from carrier financial disclosures, spectrum auction records, and consumer protection code filings. Bottom-up subscriber volume estimates triangulated against top-down market value reconstructions.
Segmentation outputs across service model, customer segment, technology, and pricing strategy dimensions were modeled with CAGRs derived from historical growth rate analysis and forward-looking infrastructure deployment schedules. Inputs included 5G radio densification timelines, eSIM adoption curves in New South Wales and Victoria metropolitan corridors, and enterprise fixed wireless substitution elasticities relative to NBN pricing.
Underlying measurement precision varies by segment; prepaid consumer volumes carry tighter precision than enterprise custom SLA negotiations due to disclosure standardization. Forecasts reflect assumptions on wholesale rate stability and regulatory enforcement continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
France Telecom Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Italy Telecom Market
Telecommunications
Mftpaas Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Brazil Telecom Market
Telecommunications
Germany ICT Market
Telecommunications
Global Esim Market
Telecommunications
IP PBX Market
Telecommunications
Telecommunication Service Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Thailand ICT Market