
 Africa Prefabricated Housing Market | 2026-2036
Africa Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Prefabricated Housing Market Outlook
Offsite digital fabrication coupled with BIM-to-field workflows is reconfiguring how prefabricated housing reaches African construction sites. Moladi leverages its reusable plastic formwork system to deliver low-cost molded structures across Southern Africa. Lafarge Africa anchors cement-based panel production through integrated material supply chains that reach multiple national markets. Karmod Prefabricated Technologies competes via steel-frame modular units engineered for rapid deployment in remote locations.
Prefabricated housing encompasses factory-built structural components transported to site for assembly into permanent or semi-permanent dwellings, typically employing steel frames, precast concrete panels, or timber modules with specified thermal and seismic ratings. The primary purpose is compressing construction timelines while maintaining structural integrity across varied climatic and soil conditions. Panelized homes and pre-cast concrete dominate current output volumes, with hybrid structures capturing margin pools where developers blend permanent foundations with modular superstructures. Steel frame technology leads installation speed metrics, though eco-friendly materials are gaining specification share in donor-funded projects.
Kenya's National Construction Authority, South Africa's National Home Builders Registration Council, and Nigeria's Federal Ministry of Works and Housing each enforce distinct structural standards and quality certification pathways that filter market access. Compliance with these national frameworks determines eligibility for public procurement and development finance, directly shaping manufacturer geographic priorities. Stakeholders must track evolving local content requirements and building code harmonization initiatives as these regulatory trajectories will determine which fabrication technologies achieve scalable deployment.
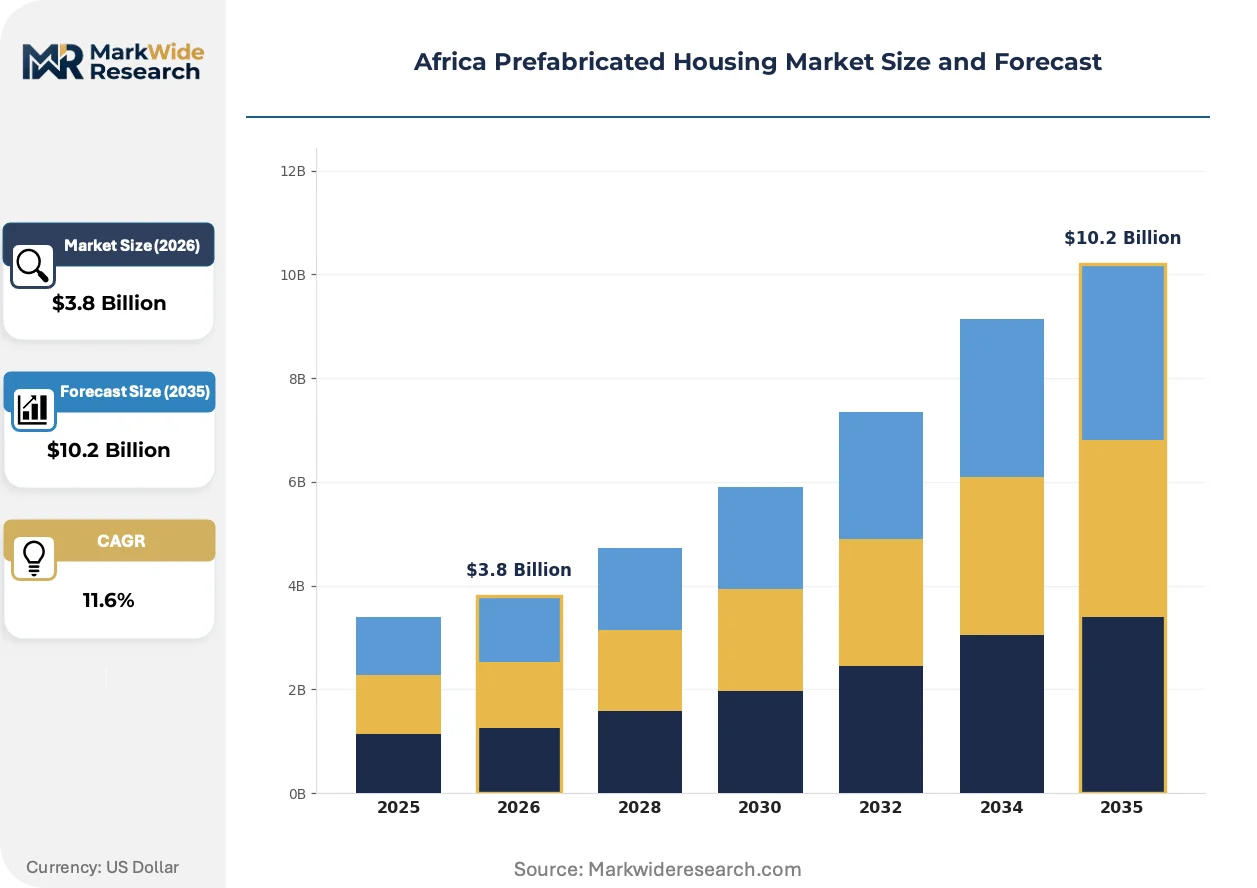
Market Dynamics
Offsite digital fabrication is compressing construction timelines across African peri-urban corridors, with BIM-to-field workflows enabling same-day assembly of steel-frame modules that previously required weeks of on-site masonry labor. This structural shift is redrawing competitive boundaries between traditional contractors and factory-based producers.
Growth Catalysts
- Kenya's Affordable Housing Program:Government-backed financing schemes for low-income residential developments are mandating modular construction methods to meet delivery targets in Nairobi's satellite towns.
- Lightweight steel framing:Cold-formed steel sections with corrosion-resistant coatings are replacing timber in coastal zones where termite damage and humidity degrade traditional materials.
- Development agency procurement:Rapid-deployment housing specifications from UN-Habitat and African Development Bank are channeling capital toward panelized systems in East African corridor projects.
Market Restraints
- Cement price volatility:Nigeria's Dangote Cement and regional competitors face input cost pressure from fuel subsidies and clinker import dependencies that destabilize precast concrete panel economics.
- Skills concentration in South Africa:Certified modular construction technicians cluster in Gauteng and Western Cape, creating labor bottlenecks for projects in secondary cities like Polokwane or Gqeberha.
- Foundation incompatibility:Expansive clay soils across Ethiopia's highlands and Sudan's Gezira Plain require engineered ground preparation that erodes the speed advantage of lightweight superstructures.
Strategic Opportunities
- Angola's post-conflict reconstruction:Luanda's peri-urban densification plans lack sufficient brick production capacity, creating entry points for containerized modular units in informal settlement upgrading.
- Green building certification:IFC's EDGE program and South Africa's Green Building Council ratings are creating specification premiums for insulated panel systems with verified thermal performance data.
- Mobile factory deployment:Skid-mounted production lines are enabling manufacturers to relocate fabrication capacity to project clusters in Tanzania's Dodoma new capital zone and Zambia's Copperbelt mining towns.
Industry Challenges
- Building code harmonization delays:Divergent seismic and wind-loading standards between Kenya's National Construction Authority and Tanzania's Engineers Registration Board complicate cross-border project execution.
- Quality assurance fragmentation:Inconsistent third-party inspection protocols for welded steel connections and panel joint sealing create warranty disputes that slow developer adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Prefabricated Housing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cast Concrete, Hybrid Structures End User: Residential Developers, Government Projects, NGOs, Commercial Builders Technology: Steel Frame, Wood Frame, 3D Printing, Eco-Friendly Materials Installation: Onsite Assembly, Offsite Construction, Quick Installation, Custom Fabrication |
| Companies Covered | Moladi, Lafarge Africa, Karmod Prefabricated Technologies, Kwikspace, Holcim, Algeco (Modulaire Group), Red Sea Housing Services, Robust Structures, Portakabin, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Prefabricated Housing Market Strategic Shifts
Digital fabrication workflows are collapsing the boundary between design optimization and field assembly, with parametric modeling tools now generating cutting files that feed directly into CNC roll-forming equipment at factory sites.
Lightweight insulated panel systems are collapsing the traditional trade-sequence of African residential construction. Factory-bonded polyurethane or mineral wool cores eliminate separate insulation subcontractor coordination. Kenyan developers in Kiambu and Kajiado counties are specifying these panels for two-story walk-up apartments that achieve thermal compliance without masonry cavity walls. The compression of envelope installation from weeks to hours is enabling developers to accelerate rental income realization.
South Africa's National Home Builders Registration Council is tightening warranty insurance requirements for structural systems, compelling modular manufacturers to submit third-party engineering certifications for wind and seismic performance. This regulatory pressure is filtering out informal panel assemblers who lack accredited testing relationships. Gauteng-based producers with SANAS-certified laboratories are capturing specification share in bonded warehouse and workforce housing developments where institutional lenders mandate compliant collateral.
Buying committees at mining corporations and agricultural estates are consolidating housing procurement under framework agreements that bundle design, fabrication, transport, and installation under single-source contracts. This behavioral shift is marginalizing traditional general contractors who subcontract discrete trades. Copperbelt operations in Zambia and platinum belt expansions in South Africa's Limpopo province are driving this consolidation, with procurement officers prioritizing speed-certain delivery over lowest capital cost.
Africa Prefabricated Housing Market Segmentation
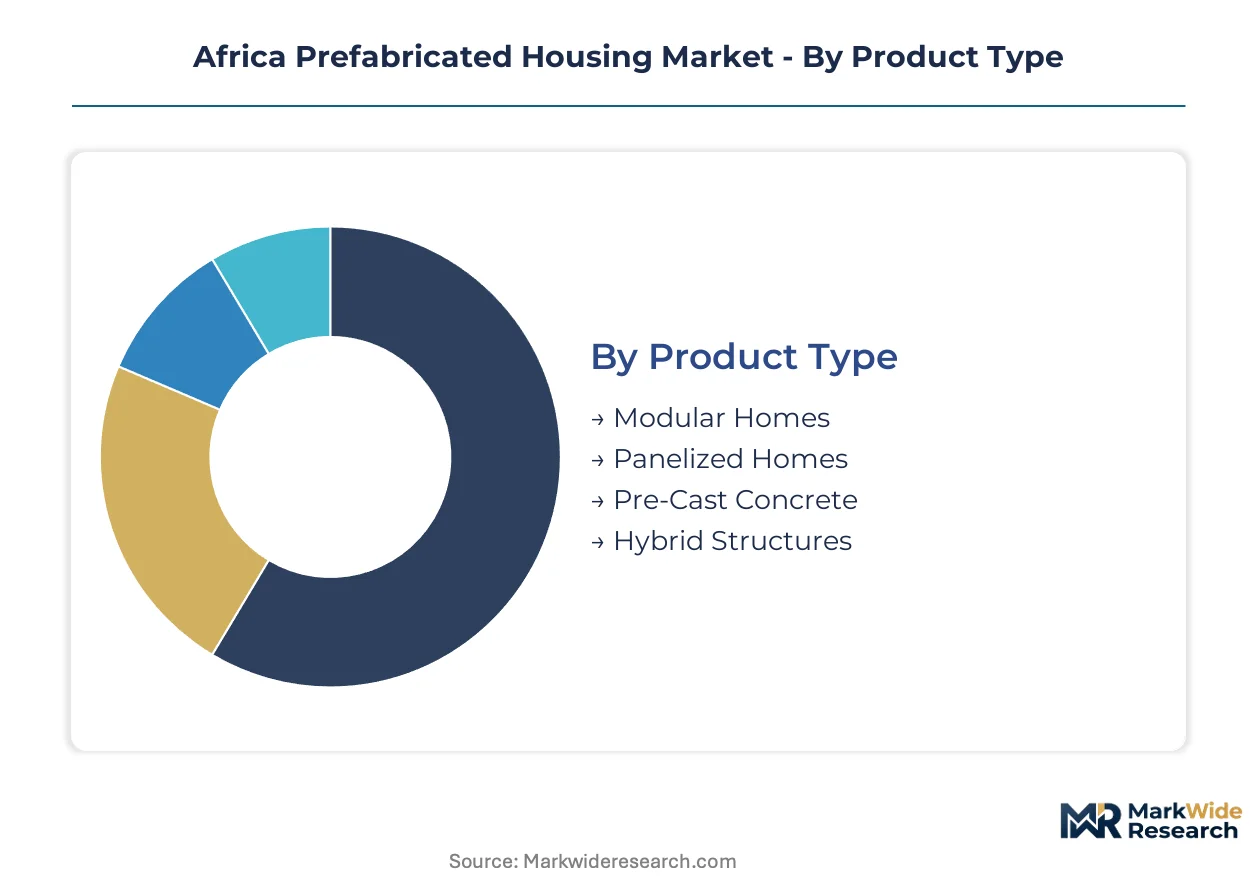
Segmentation in Africa's prefabricated housing market reveals how fabrication technology, procurement channels, and installation methods intersect with local construction norms. Distinct product categories serve divergent buyer priorities across peri-urban residential zones, government housing corridors, and remote commercial sites.
Product Type:
Mature panelized systems dominate current output volumes while emerging fabrication methods reshape competitive boundaries between factory-based and site-built approaches.
- Modular Homes:Complete volumetric units fabricated in factory conditions with MEP systems pre-installed, transported to site for crane-assisted placement. Demand concentrates in Angola's post-conflict reconstruction zones where Luanda's peri-urban densification plans lack sufficient brick production capacity, creating entry points for containerized modular units in informal settlement upgrading.
- Panelized Homes:Factory-produced wall, floor, and roof panels assembled on permanent foundations at destination sites. Kenyan developers in Kiambu and Kajiado counties are specifying insulated panels for two-story walk-up apartments that achieve thermal compliance without masonry cavity walls, compressing envelope installation from weeks to hours.
- Pre-Cast Concrete:Cement-based structural elements cured under controlled conditions before transport, favored for seismic resilience and thermal mass in highland climates.
- Hybrid Structures:Permanent foundation systems paired with modular superstructures, capturing margin pools where developers blend speed advantages with collateral requirements from institutional lenders.
Panelized homes handle the majority of throughput; modular homes are the fastest mover on share.
End User:
Procurement concentration varies sharply between state-backed housing programs and private commercial demand, with development finance institutions channeling capital toward specific buyer categories.
- Residential Developers:Private sector builders targeting middle-income rental and ownership markets in Nairobi's satellite towns and South Africa's Gauteng corridor. Buying committees are consolidating procurement under framework agreements that bundle design, fabrication, transport, and installation under single-source contracts, marginalizing traditional general contractors who subcontract discrete trades.
- Government Projects:State housing programs across Kenya, Nigeria, and South Africa mandating modular construction methods to meet delivery targets. Kenya's Affordable Housing Program anchors demand through government-backed financing schemes for low-income residential developments.
- NGOs:Humanitarian and development agency specifications from UN-Habitat and African Development Bank channeling capital toward rapid-deployment panelized systems in East African corridor projects.
- Commercial Builders:Mining corporations and agricultural estates in Zambia's Copperbelt and South Africa's Limpopo platinum belt prioritizing speed-certain delivery over lowest capital cost for workforce housing.
Government projects anchor volume commitment; commercial builders are expanding most quickly as procurement officers consolidate vendor relationships.
Technology:
Material selection tracks corrosion resistance requirements, termite exposure, and donor-funded sustainability specifications across coastal and inland deployment zones.
- Steel Frame:Cold-formed steel sections with corrosion-resistant coatings replacing timber in coastal zones where humidity and termite damage degrade traditional materials. Leads installation speed metrics with same-day assembly capabilities that previously required weeks of on-site masonry labor.
- Wood Frame:Timber-based structural systems constrained to termite-protected inland highlands and donor projects specifying renewable material content.
- 3D Printing:Emerging robotic deposition methods for concrete and polymer composites, piloted in demonstration projects but lacking scalable supply chains.
- Eco-Friendly Materials:Bamboo composites, compressed earth blocks, and recycled aggregate systems gaining specification share in IFC's EDGE program and South Africa's Green Building Council ratings.
Steel frame technology commands the widest deployment; eco-friendly materials are climbing the fastest as green certification creates specification premiums.
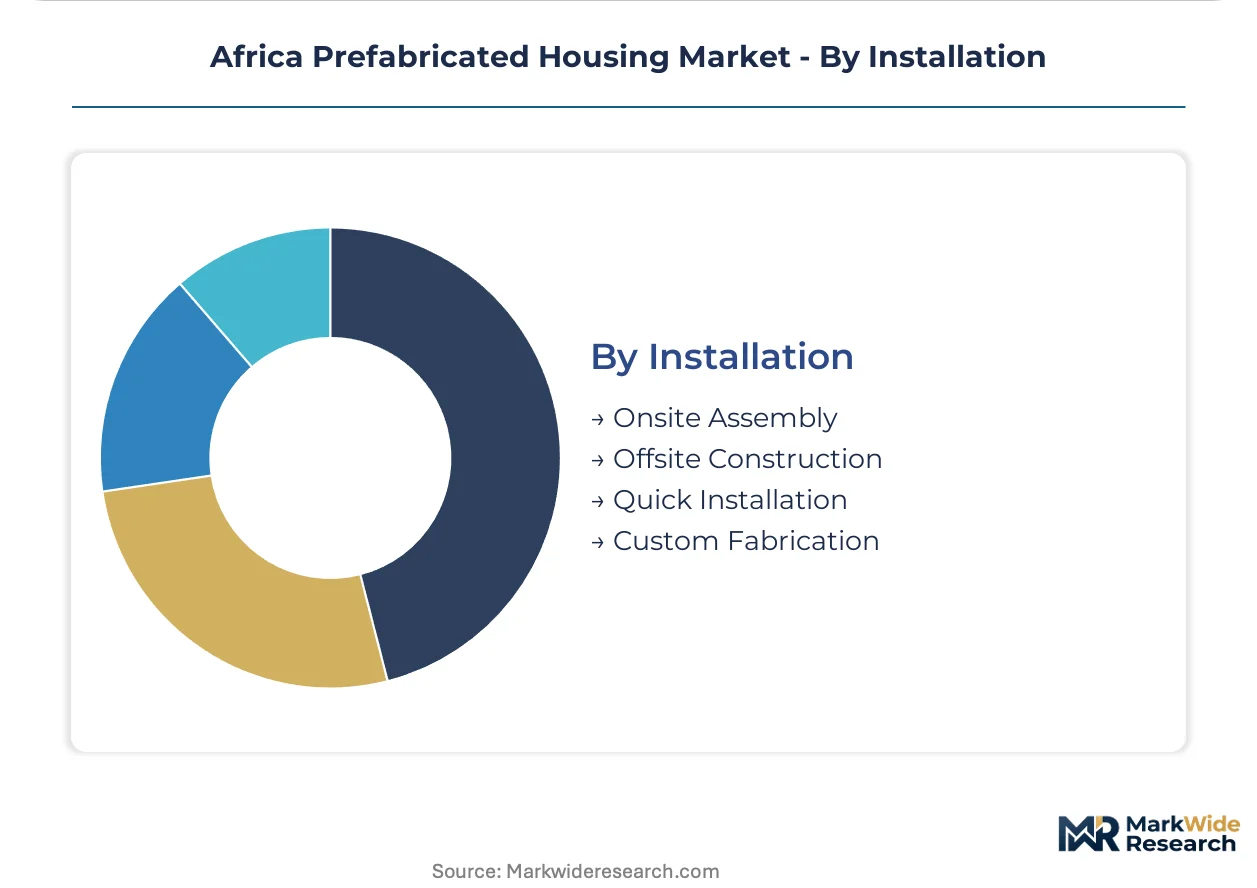
Installation:
Site preparation requirements and foundation compatibility determine which installation methods achieve viable economics across expansive clay soils and seismic zones.
- Onsite Assembly:Component delivery to prepared foundations with local labor completing final connections. Required in Ethiopia's highlands and Sudan's Gezira Plain where expansive clay soils demand engineered ground preparation that erodes the speed advantage of lightweight superstructures.
- Offsite Construction:Complete factory fabrication with minimal site work limited to foundation and utility tie-ins. Mobile factory deployment via skid-mounted production lines enables manufacturers to relocate fabrication capacity to project clusters in Tanzania's Dodoma new capital zone and Zambia's Copperbelt mining towns.
- Quick Installation:Accelerated assembly protocols for emergency and rapid-deployment housing, specified by UN-Habitat and development agencies in crisis response contexts.
- Custom Fabrication:Design-to-order systems for non-standard footprints and architectural specifications, serving institutional clients with unique spatial requirements.
Offsite construction generates the highest throughput volumes; quick installation is gaining share fastest as development agencies expand rapid-deployment financing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government housing programs and mining sector procurement anchor demand across the continent. State-backed financing schemes in East Africa and workforce housing contracts in Southern Africa's mineral belts concentrate buying power. Development agencies channel capital toward rapid-deployment specifications in corridor projects.
Kenya
Nairobi's satellite towns drive absorption through the Affordable Housing Program. The National Construction Authority enforces structural standards that filter market access for modular suppliers. Kiambu and Kajiado counties host clusters where developers specify insulated panels for two-story walk-up apartments.
South Africa
Gauteng and Western Cape concentrate certified modular construction technicians. The National Home Builders Registration Council tightens warranty insurance requirements for structural systems. Polokwane and Gqeberha face labor bottlenecks as procurement officers consolidate housing contracts under single-source frameworks.
Nigeria
Lagos and Abuja peri-urban zones absorb panelized systems for low-income residential developments. The Federal Ministry of Works and Housing maintains distinct quality certification pathways. Cement price volatility from Dangote Cement and regional competitors destabilizes precast concrete panel economics.
Angola
Luanda's post-conflict reconstruction creates entry points for containerized modular units. Peri-urban densification plans lack sufficient brick production capacity. Informal settlement upgrading programs channel demand toward rapid-deployment specifications.
Zambia
Copperbelt mining towns prioritize speed-certain delivery for workforce housing. Procurement officers consolidate vendor relationships under framework agreements. Mobile factory deployment via skid-mounted production lines relocates fabrication capacity to project clusters.
Africa Prefabricated Housing Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct procurement pathways. The vendor base spans integrated material suppliers, dedicated modular fabricators, and mobile production operators. Two strategic archetypes dominate: cement-based panel producers leveraging supply chain integration, and steel-frame specialists optimizing for rapid deployment. Competitive moves center on geographic expansion through mobile factory deployment and strategic partnerships with development finance institutions.
Among Africa-based fabricators, Moladi and Robust Structures exemplify the site-adaptable formwork archetype. Karmod Prefabricated Technologies occupies a position within the steel-frame modular tier. Lafarge Africa and Holcim represent the integrated material-supply archetype. Algeco (Modulaire Group) and Portakabin sit within the international modular leasing tier. Kwikspace and Red Sea Housing Services anchor the rapid-deployment workforce housing segment.
| Leading Market Players |
|---|
| Moladi |
| Lafarge Africa |
| Karmod Prefabricated Technologies |
| Kwikspace |
| Holcim |
| Algeco (Modulaire Group) |
| Red Sea Housing Services |
| Robust Structures |
| Portakabin |
| Others |
Value Chain & Pricing Dynamics
The Mombasa-Nairobi-Dar es Salaam freight corridor's fuel-indexed haulage costs concentrate supply power among Gauteng-based steel fabricators and Nigerian cement producers, while downstream price differentiation splits between donor-funded projects with fixed-budget specifications and commercial developers negotiating volume discounts.
Pricing Analysis
Cost-plus contracts with steel price indexation dominate procurement for mining and government housing programs, creating three-tier pricing structure across premium certified systems, standard panelized units, and economy-grade containerized modules. Price differentiation hinges on SANAS engineering certification status and after-sales warranty bundling. Pricing pressure stems from Dangote Cement's input cost volatility transmitting into precast panel margins. Commercial builders in Zambia's Copperbelt exhibit lowest price sensitivity due to speed premiums, while peri-urban residential developers in Kenya face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on cold-formed steel roll-forming equipment from European and East Asian suppliers limit technology transfer to African fabrication facilities, constraining quality-tier expansion. Manufacturing concentrates in South Africa's Gauteng corridor, China's Hebei province, and Turkey's Kocaeli industrial zone. Supply chains draw from galvanized steel coil, polyurethane insulation foam, and Portland cement clinker. Single-source vulnerability runs through South Africa's concentrated certified technician pool. Distribution runs through development finance institution procurement frameworks and mining sector framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital fabrication workflows and BIM-to-field assembly protocols constitute a structural inflection reconfiguring competitive boundaries between factory-based and site-built construction across African housing markets.
For Market Incumbents: Entrench specification control by securing SANAS-certified laboratory partnerships for wind and seismic performance testing, filtering out informal panel assemblers from institutional lender-mandated collateral pools. Deepen backward integration into clinker supply through offtake agreements with Dangote Cement and regional competitors to buffer margin erosion from fuel subsidy volatility. Mobile factory deployment to Tanzania's Dodoma zone and Zambia's Copperbelt defends geographic share against emerging steel-frame specialists.
For New Entrants and Emerging Players: Angola's post-conflict reconstruction corridors present underpenetrated entry points where Luanda's brick production deficit exceeds containerized modular supply capacity. Target rapid-deployment workforce housing specifications for UN-Habitat and African Development Bank procurement channels with skid-mounted production lines that relocate to project clusters. Partner with mining procurement officers consolidating vendor relationships under single-source framework agreements to bypass traditional general contractor gatekeepers.
For Investors and Strategic Acquirers: Kenya's National Construction Authority building code harmonization with Tanzania's Engineers Registration Board reshapes the acquisition landscape by rewarding cross-border execution capabilities. Long-term viability centers on fabricators with mobile factory assets and accredited testing relationships rather than fixed-plant operators. Target acquisition archetype: Gauteng-based producers with SANAS-certified laboratories and existing mining sector framework contracts. Monitor cement price stabilization mechanisms as inflection indicator for precast concrete panel economics recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Factory Deployment | Skid-mounted production lines capture project-cluster demand in Dodoma and Copperbelt mining towns. |
| SANAS Certification Investment | Accredited laboratory relationships unlock institutional lender-mandated collateral specifications in Gauteng. |
| Development Finance Partnership | UN-Habitat and African Development Bank procurement channels anchor rapid-deployment volume commitments. |
| Clinker Supply Integration | Backward integration into Dangote Cement offtake agreements buffers precast panel margin volatility. |
| Cross-Border Code Harmonization | Kenya-Tanzania building code alignment enables scalable deployment across East African corridor projects. |
Study Parameters
Cross-validation between primary interviews with modular construction technicians, procurement officers at mining corporations, and development agency program managers anchors the qualitative findings against secondary validation from National Construction Authority filings, Engineers Registration Board certifications, and UN-Habitat rapid-deployment specifications. Bottom-up triangulation of fabrication capacity at Gauteng, Kocaeli, and Hebei production facilities converges with top-down analysis of government housing program delivery targets across Kenya, Nigeria, and South Africa.
Calibration against historical delivery data from Kenya's Affordable Housing Program and Zambia's Copperbelt workforce housing deployments informs the projection framework across the analysis window. Segmentation dimensions span product type, end-user procurement channel, material technology, and installation method, with regional regulatory clusters modeled as distinct adoption corridors. CAGRs derive from volume-weighted averaging of segment trajectories, incorporating cement price volatility indices and steel framing penetration rates as industry-specific forecast inputs.
Practitioners should monitor building code harmonization progress and development agency procurement specification shifts for early signals of technology preference inflection. Forecasts reflect assumptions regarding fuel subsidy stability and clinker import dependency trajectories. Material shifts in National Construction Authority structural standards or African Development Bank rapid-deployment financing thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Poland Construction Market
Building Construction
India Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Guatemala Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Honduras Construction Market
Building Construction
Prefabricated Construction Market
Building Construction
Thailand Construction Market