
 Indonesia Commercial Construction Market | 2026-2036
Indonesia Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Commercial Construction Market Insights
A widening capital-intensity divergence between state-owned giants and mid-tier private contractors is redrawing competitive boundaries in Indonesia's commercial construction sector. PT Wijaya Karya Tbk leverages its vertically integrated engineering and procurement capabilities to dominate large-scale infrastructure-adjacent commercial projects. PT PP (Persero) Tbk anchors its position through sustained access to government-backed financing channels and public-private partnership mandates. Shimizu Bangun Cipta Kontraktor differentiates by deploying Japanese precision-engineering protocols on premium office and hospitality developments.
Indonesia commercial construction encompasses the planning, design, and erection of non-residential structures using reinforced concrete frameworks, structural steel systems, and modular precast components engineered to withstand seismic loads up to magnitude 8.0. These facilities serve retail, corporate, hospitality, and institutional functions across the archipelago's urban centers. Office buildings and hotels command the largest share of current project value, while modular construction methods represent the fastest-expanding segment as developers seek to compress delivery schedules on remote island sites. Traditional block construction still occupies substantial volume in secondary cities where labor costs offset speed premiums.
BIS-equivalent national standards, the Green Building Council Indonesia certification framework, and regional seismic building codes collectively shape material selection, structural design parameters, and project approval timelines across Indonesian provinces. Compliance with these requirements determines market access for contractors and influences lifecycle cost calculations for institutional investors. Stakeholders must monitor how evolving provincial zoning reforms and accelerating green certification thresholds will reshape project feasibility and contractor qualification requirements.
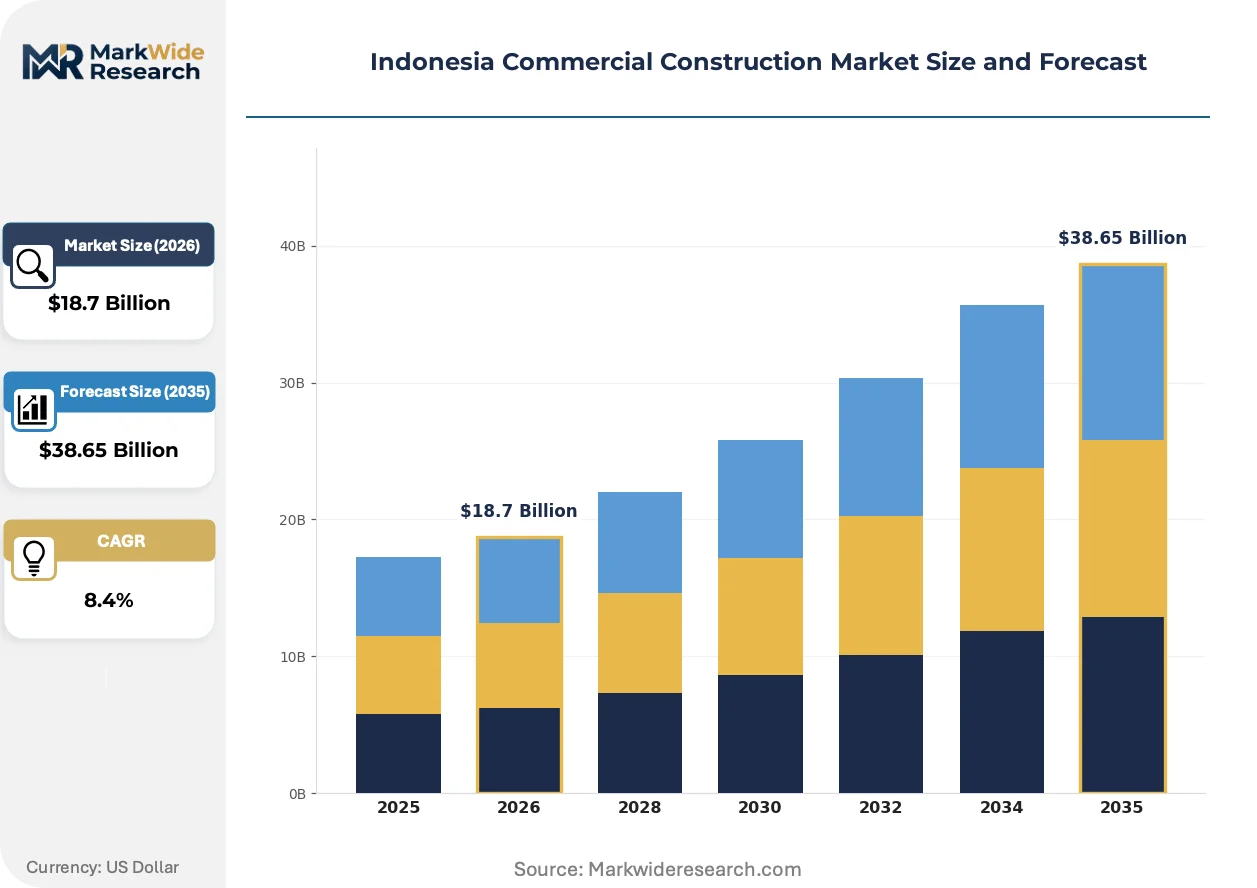
Market Dynamics
Green Building Council Indonesia certification mandates are compressing project timelines and forcing material specification changes across commercial developments, while seismic engineering requirements above magnitude 8.0 reshape structural design priorities.
Growth Catalysts
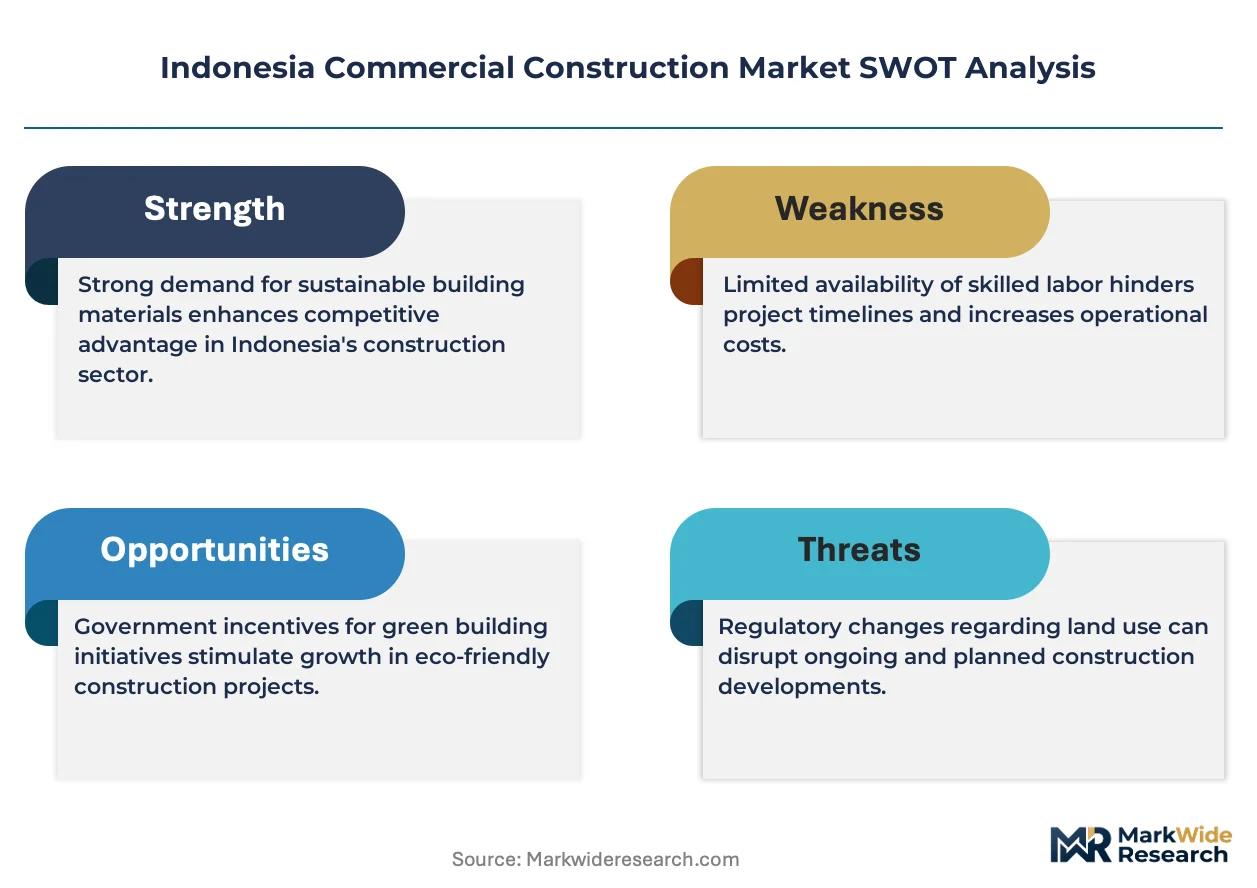
- GBCI Green Certification Mandate:Mandatory green building ratings for commercial structures above 10,000 square meters are accelerating specification of low-carbon concrete and photovoltaic-integrated facades.
- Hospitality Pipeline Concentration:International hotel chains expanding in Bali and Jakarta are driving demand for mixed-use developments with integrated conference and retail components.
- Modular Prefabrication:Remote island logistics challenges are pushing developers toward factory-built structural components that reduce on-site labor dependency.
Market Restraints
- Structural Steel Import Dependency:Heavy reliance on imported H-beam and plate steel exposes contractors to currency volatility and shipping delays through the Sunda Strait corridor.
- Specialized Seismic Engineering Shortage:Limited domestic capacity for performance-based seismic design extends consultant procurement timelines for high-rise commercial towers.
- Cement Price Volatility:Regional supply imbalances and energy cost fluctuations in clinker production compress margins for fixed-price contracts.
Strategic Opportunities
- Eastern Indonesia Expansion:Underserved secondary cities in Sulawesi and Papua present first-mover advantages for contractors with modular construction capabilities.
- Logistics Facility Surge:E-commerce fulfillment center demand is creating specialized warehouse construction segments requiring high-clearance spans and automated loading systems.
- Carbon Credit Integration:Emerging voluntary carbon markets offer revenue stacking for developments achieving GBCI Platinum ratings with measurable embodied carbon reductions.
Industry Challenges
- Certification Timeline Compression:GBCI review backlogs and provincial permitting variations create schedule uncertainty for speculative commercial developments.
- Digital Twin Implementation Gap:Limited BIM-to-field execution capability among mid-tier contractors fragments coordination on complex mixed-use projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Commercial Construction Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Office Buildings, Shopping Malls, Hotels, Educational Institutions Construction Method: Precast Concrete, Steel Frame, Modular Construction, Traditional Block Market Player Type: General Contractors, Subcontractors, Engineers, Material Suppliers Financing Source: Public Funding, Private Investment, Joint Ventures, Foreign Investment |
| Companies Covered | PT Wijaya Karya Tbk, PT PP (Persero) Tbk, PT Adhi Karya Tbk, PT Total Bangun Persada Tbk, PT Nusa Raya Cipta Tbk, PT Metropolitan Land Tbk, Shimizu Bangun Cipta Kontraktor, PT Tunas Jaya Sanur, The Mulia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Commercial Construction Market Trends and Innovations
Digital fabrication and regulatory tightening are converging to reshape how commercial structures are designed, certified, and delivered across the archipelago's fragmented geography.
Mass timber hybrid systems are decomposing traditional reinforced concrete dominance in mid-rise commercial buildings. Boutique office developers in Jakarta's peripheral business districts are specifying cross-laminated timber floor plates to accelerate structural erection. This material shift is compressing superstructure schedules from months to weeks while meeting GBCI biogenic carbon criteria.
Indonesia's 2023 revision to seismic building codes has tightened ductility requirements for moment-resisting frames. Engineers must now demonstrate capacity-based design compliance through nonlinear pushover analysis for structures exceeding twelve stories. High-rise hospitality developers in Jakarta are responding by engaging Japanese structural consultants with proven high-seismic expertise.
Integrated project delivery contracts are displacing traditional design-bid-build sequences for complex mixed-use developments. Institutional investors in Greater Jakarta are mandating single-point accountability to reduce interface risk between architecture, MEP, and facade trades. This procurement evolution is most visible in speculative grade-A office towers where lease-up velocity depends on accelerated completion certainty.
Indonesia Commercial Construction Market Segmentation
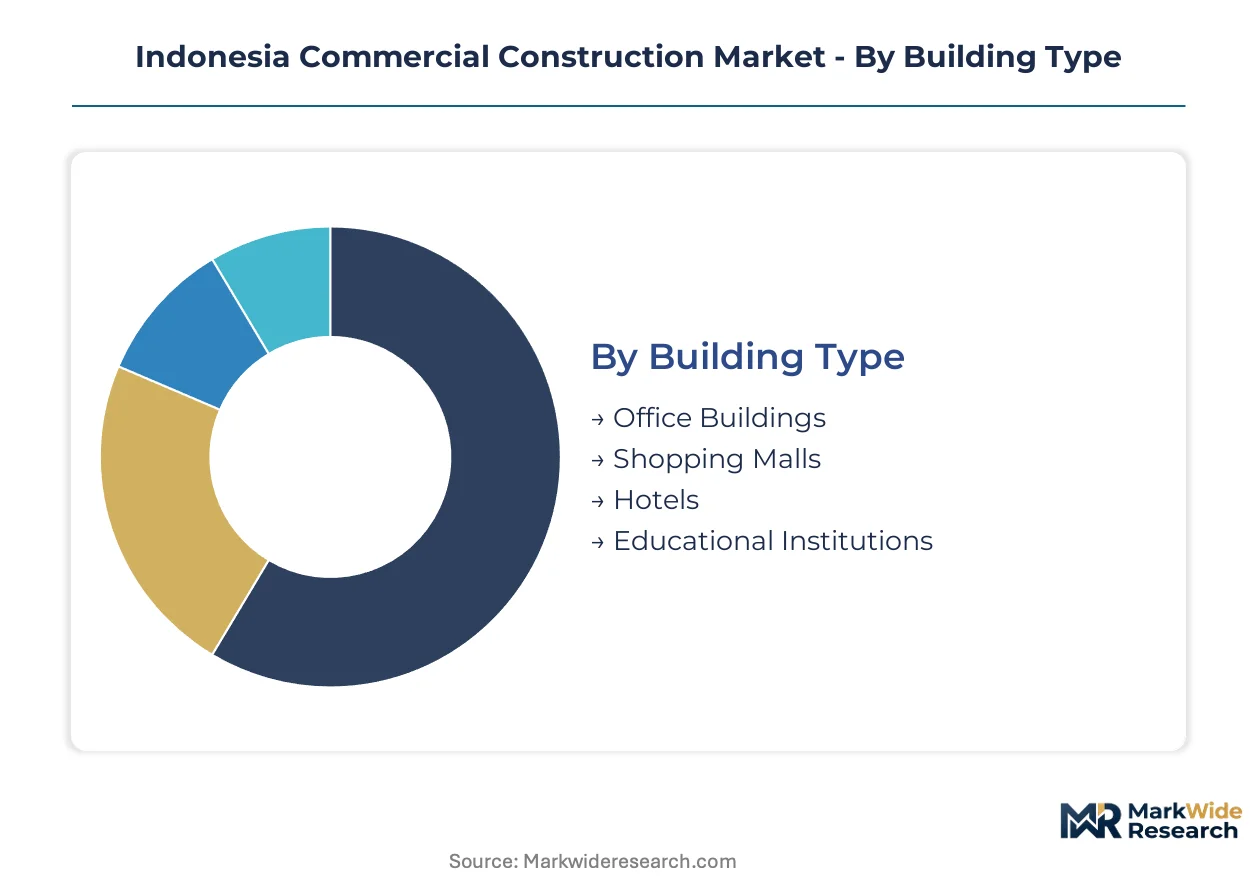
Segmentation reveals how project economics, delivery methods, and capital sources stratify Indonesia's commercial construction landscape. Developers select building types and construction methods based on seismic risk exposure, green certification requirements, and site accessibility across the archipelago's fragmented geography.
Building Type:
Channel mix varies sharply by building type, with hospitality and retail assets attracting foreign institutional capital while office towers rely on domestic bank syndication and state-linked financing.
- Office Buildings:Reinforced concrete core-and-shell structures dominate Jakarta's central business district, where Grade-A towers exceeding thirty stories require performance-based seismic design. Demand concentrates in Greater Jakarta's emerging peripheral sub-markets as tenants seek lower occupancy costs outside the Sudirman corridor.
- Hotels:Mixed-use hospitality developments in Bali and Jakarta integrate conference facilities and retail podiums to maximize land value. International chains drive specification of modular guestroom units to accelerate opening timelines on remote island sites.
- Shopping Malls:Regional retail centers in secondary cities employ traditional beam-column frames with expansive atrium spans.
- Educational Institutions:Campus developments prioritize low-rise reinforced masonry for cost control in provincial markets.
By volume, office buildings lead. By growth pace, hotels are climbing the fastest.
Construction Method:
Cost tier stratification separates premium seismic-engineered systems from labor-intensive traditional methods, with material selection directly tied to project location and certification ambition.
- Modular Construction:Factory-built structural components reduce on-site labor dependency for projects in Sulawesi and Papua, where skilled trades are scarce. Developers in Eastern Indonesia specify prefabricated bathroom pods and MEP racks to compress schedules on logistics-constrained sites.
- Precast Concrete:Hollow-core planks and precast columns accelerate superstructure erection for mid-rise commercial buildings in Greater Jakarta. GBCI certification mandates are pushing specification of low-carbon precast mixes with supplementary cementitious materials.
- Steel Frame:Moment-resisting steel systems serve high-clearance logistics facilities requiring wide column-free spans.
- Traditional Block:Conventional masonry construction retains substantial share in secondary cities where labor arbitrage outweighs speed premiums.
By installed base, traditional block leads. By expansion trajectory, modular construction is gaining share fastest.
Market Player Type:
Customer type segmentation maps how project complexity determines whether developers engage full-service general contractors or fragmented specialist networks.
- General Contractors:Vertically integrated firms with in-house engineering capabilities dominate large-scale mixed-use developments requiring single-point accountability. State-owned contractors anchor public-private partnership pipelines through preferential access to government-backed financing channels.
- Subcontractors:Specialist facade and MEP contractors capture value on complex hospitality projects demanding Japanese precision-engineering protocols.
- Engineers:Seismic design consultants with nonlinear analysis capability command premium fees for high-rise towers exceeding twelve stories.
- Material Suppliers:Cement and steel distributors face margin compression from price volatility in clinker production and imported H-beam markets.
By project count, general contractors lead. By fee expansion, specialized seismic engineers are pulling ahead.
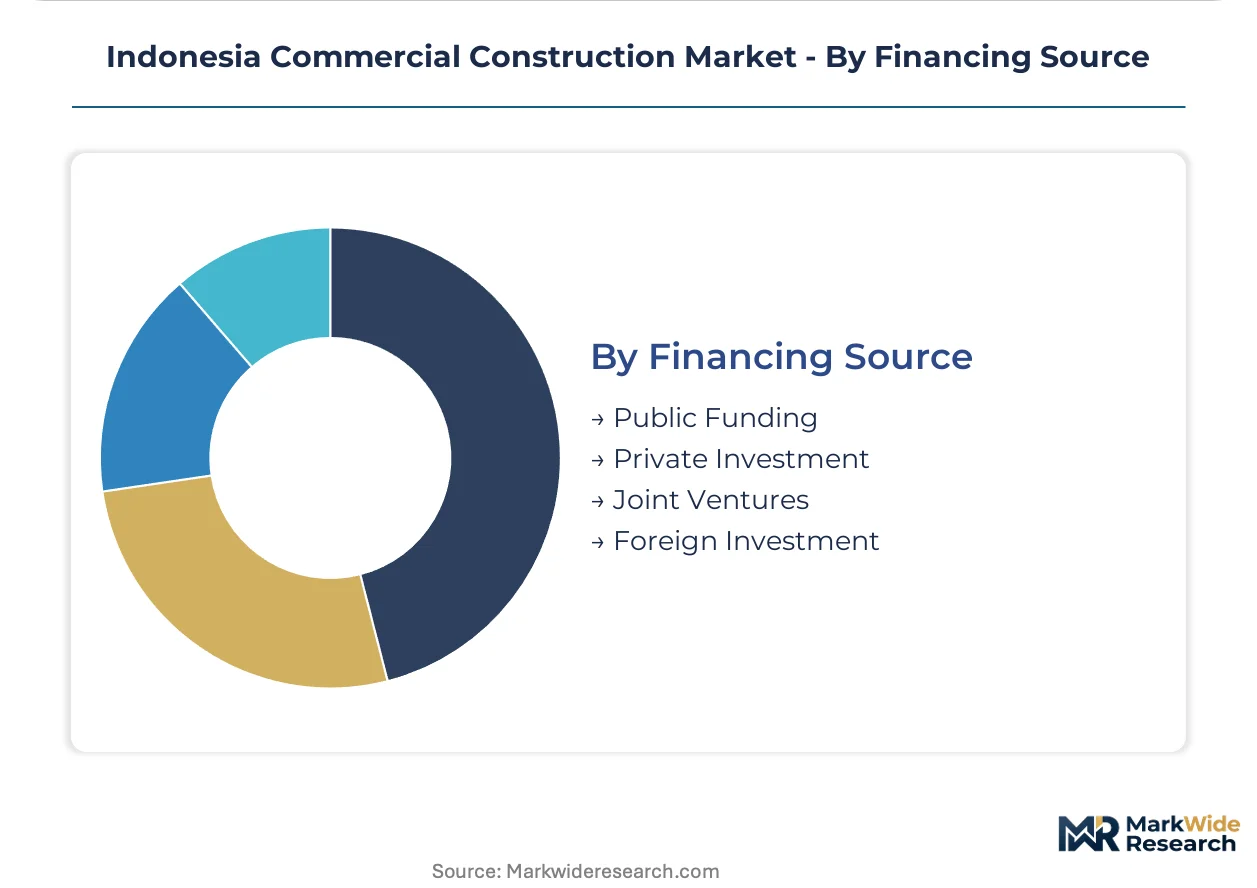
Financing Source:
Maturity-based segmentation distinguishes established public funding mechanisms from emerging foreign capital flows reshaping deal structures.
- Private Investment:Domestic institutional capital and family office wealth fund speculative Grade-A office development in Jakarta's emerging business districts. Investors mandate integrated project delivery contracts to reduce completion risk and accelerate lease-up velocity.
- Joint Ventures:Pairings between local developers and international hotel operators structure risk-sharing for mixed-use hospitality assets in Bali. Foreign partners contribute brand equity and operational expertise while local sponsors secure land and permitting.
- Public Funding:State-linked financing channels support infrastructure-adjacent commercial projects through mandated procurement preferences.
- Foreign Investment:Singaporean and Japanese capital targets logistics facility development in Greater Jakarta's industrial corridors.
By deployment volume, private investment leads. By flow acceleration, joint ventures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta commands premium pricing power over Eastern Indonesia, where logistics costs inflate material landed costs by double-digit margins. Provincial wage arbitrage in Sulawesi and Papua fails to offset shipping surcharges through the Sunda Strait corridor.
Java
Grade-A office towers and mixed-use hospitality complexes dominate investment flows into Jakarta's peripheral business districts. The Green Building Council Indonesia mandates green certification for commercial structures exceeding 10,000 square meters, accelerating specification of low-carbon concrete and photovoltaic-integrated facades. The Greater Jakarta metropolitan corridor anchors national construction volume, with state-linked contractors securing preferential access to government-backed financing channels.
Bali
International hotel chains drive demand for mixed-use developments integrating conference facilities and retail podiums. Regional seismic building codes require performance-based design compliance for structures above twelve stories, extending consultant procurement timelines. The Nusa Dua and Seminyak hospitality clusters attract joint venture structures pairing local land sponsors with foreign brand operators.
Sulawesi
Underserved secondary cities present first-mover opportunities for contractors deploying modular construction capabilities. Provincial permitting variations and GBCI review backlogs create schedule uncertainty for speculative commercial developments. The Makassar industrial corridor is emerging as a logistics facility destination as e-commerce fulfillment demand spreads beyond Java.
Papua
Remote island logistics constraints push developers toward factory-built structural components that reduce on-site labor dependency. Limited domestic capacity for performance-based seismic design fragments contractor qualification for high-rise commercial towers. The Jayapura metropolitan area sees concentrated public funding for infrastructure-adjacent commercial projects through mandated procurement preferences.
Sumatra
Cement price volatility from regional clinker supply imbalances compresses margins for fixed-price contracts across Medan and Palembang development pipelines. Currency exposure on imported H-beam and plate steel exposes contractors to margin erosion. The Batam-Bintan industrial zone attracts Singaporean capital targeting logistics facility development with high-clearance spans and automated loading systems.
Indonesia Commercial Construction Market Competitive Landscape
Concentration sits with state-owned giants possessing vertically integrated engineering and procurement capabilities. The vendor base stratifies across three tiers: full-service general contractors with in-house seismic design capacity, specialist facade and MEP subcontractors, and regional material distributors facing margin compression. Dominant competitive moves include backward integration into precast concrete production and strategic partnerships with international hotel operators for mixed-use hospitality risk-sharing.
Within the state-owned tier, PT Wijaya Karya Tbk and PT PP (Persero) Tbk occupy positions leveraging preferential government financing access. Shimizu Bangun Cipta Kontraktor represents the precision-engineering specialist archetype, deploying Japanese seismic protocols on premium hospitality and office developments. These three entities exemplify how capital intensity divergence between state-backed and private contractors redraws competitive boundaries.
| Leading Market Players |
|---|
| PT Wijaya Karya Tbk |
| PT PP (Persero) Tbk |
| PT Adhi Karya Tbk |
| PT Total Bangun Persada Tbk |
| PT Nusa Raya Cipta Tbk |
| PT Metropolitan Land Tbk |
| Shimizu Bangun Cipta Kontraktor |
| PT Tunas Jaya Sanur |
| The Mulia Group |
| Others |
Pricing and Supply Chain Analysis
Green Building Council Indonesia certification tiers gate both contractor qualification and project fee premiums simultaneously, compressing margins for non-certified players while rewarding GBCI Platinum holders with pricing power on institutional mandates. The interaction between compliance costs and material specification creates a bifurcated market where certified low-carbon concrete commands substantial premiums over conventional mixes.
Pricing Analysis
Configured-to-order pricing for performance-based seismic designs spreads substantially above standard beam-column frame rates. Three-tier pricing structure across premium, standard, and economy levels separates Japanese-engineered hospitality projects from domestic mid-rise office towers and provincial retail centers. Pricing pressure stems from cement price volatility in regional clinker markets, squeezing fixed-price contract margins. Domestic bank-syndicated office developers exhibit highest price sensitivity, while foreign institutional capital funding Grade-A towers tolerates premium engineering fees for completion certainty.
Supply Chain Analysis
Sunda Strait container congestion and H-beam shipping delays through Singapore-Jakarta lanes inflate landed costs for structural steel imports. China, South Korea, and Japan anchor supply for plate steel and seismic-grade rebar, while domestic clinker production feeds regional cement blending. Contractors draw from imported H-beam, low-carbon cementitious materials, and photovoltaic facade components. Single-source vulnerability concentrates in Japanese high-seismic engineering consultancy. Distribution runs through state-linked procurement channels for infrastructure-adjacent projects and direct developer contracting for speculative commercial assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as modular construction capabilities and GBCI certification fast-tracks create specialist niches unclaimed by state-owned giants. The hospitality pipeline's acceleration in Eastern Indonesia fragments demand geography, opening entry points for agile mid-tier contractors.
For Market Incumbents: Consolidate backward into precast concrete production to capture margin from low-carbon mix specification mandated by GBCI thresholds. Lock in long-term clinker supply agreements to defend against energy cost volatility eroding fixed-price contract profitability. State-owned contractors should deepen government financing channel access before provincial permitting reforms open public-private partnership bidding to foreign entrants. For New Entrants and Emerging Players: GBCI certification fast-track programs offer entry velocity into Jakarta's Grade-A office segment where incumbent backlog creates delivery gaps. Target modular construction deployment in Sulawesi and Papua where logistics constraints exclude traditional block methods. Partner with international hotel operators for risk-sharing on mixed-use hospitality assets, contributing factory-built component expertise while foreign partners supply brand equity. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate construction divisions seeking non-core asset divestiture to focus on residential development. Long-term viability centers on contractors with captive modular fabrication capability and proven GBCI Platinum project delivery. Watch for provincial zoning reform announcements as inflection signals for public-private partnership pipeline expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Production | Captures margin from GBCI-mandated low-carbon concrete specification in Greater Jakarta towers. |
| Modular Fabrication Facility Deployment | Reduces Sunda Strait logistics exposure for Eastern Indonesia hospitality and logistics projects. |
| Joint Venture with International Hotel Operator | Structures risk-sharing for Bali mixed-use assets requiring Japanese precision-engineering protocols. |
| GBCI Platinum Certification Investment | Unlocks institutional capital mandates and carbon credit revenue stacking for commercial developments. |
| Seismic Engineering Consultancy Acquisition | Addresses capacity shortage for nonlinear pushover analysis on high-rise towers exceeding twelve stories. |
Research Methodology
Operator-level perspectives from project directors at state-owned contractors, procurement leads at international hotel chains, GBCI certification auditors, and seismic engineering consultants anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through BIS-equivalent national standards documentation, Green Building Council Indonesia certification registries, and provincial permitting authority disclosures. Customs data on H-beam and plate steel imports, cement production statistics from regional clinker facilities, and institutional investor mandate filings supplied quantitative anchors. Bottom-up project pipeline aggregation triangulated against top-down construction value estimates across the analysis window.
Sensitivity analysis tested forecast robustness across GBCI enforcement intensity scenarios and clinker energy cost trajectories. Segmentation dimensions modeled include building type, construction method, market player type, and financing source, with regional geography and certification tier as cross-cutting variables. CAGRs derived from project value aggregation and completion timeline compression factors. Forecast inputs incorporated modular construction adoption curves and foreign capital flow patterns into logistics facility development.
Decision-makers should treat outputs as directional under sustained GBCI mandate enforcement and stable provincial permitting timelines; material deviation would warrant model refresh. Specific risk factors include seismic code revision implementation delays, cement supply disruptions from clinker production energy shocks, and foreign investment restriction tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Europe 3D Printing Construction Market
Building Construction
El Salvador Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Indonesia Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
Japan Construction Market
Building Construction
China Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Spain Construction Market
Building Construction
Malaysia Construction Market
Building Construction
UAE Facade Market
Building Construction
Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
UAE Construction Market