
 Energy-Efficient Building Market | 2026-2036
Energy-Efficient Building Market Size, Share, and Industry Trends Forecast 2026-2036
Energy-Efficient Building Market Intelligence
Modular bundling of HVAC controls with building automation software is hardening as the dominant procurement format across large commercial projects. Johnson Controls leverages its captive supply of chillers and digital controls to anchor turnkey efficiency contracts in North American healthcare campuses. Siemens AG competes through deep R&D intensity in digital twin platforms for building energy optimization. Schneider Electric SE differentiates via its edge-computing architecture that extends real-time load management to mid-rise residential portfolios.
Energy-efficient buildings integrate advanced envelope systems, high-performance HVAC, intelligent controls, and on-site renewable generation to minimize operational energy consumption below baseline code thresholds; insulation materials typically achieve R-values exceeding 30 in roof assemblies and 20 in wall cavities, while LED lighting delivers efficacy above 120 lumens per watt. The commercial segment dominates current retrofit spending as facility managers pursue lease-rate premiums through green certification. Energy management systems represent the fastest-growing technology category, displacing standalone thermostat installations as the default control layer. Solar integration within the energy source dimension remains concentrated in jurisdictions with net-metering frameworks, though biomass and geothermal occupy niche positions in district heating networks.
The EPA's ENERGY STAR certification program and the EU's Energy Performance of Buildings Directive collectively shape product standards and disclosure obligations across the Atlantic, while China's GB standards for building energy efficiency enforce mandatory efficiency ratios for envelope and mechanical systems. Stakeholders must monitor how tightening disclosure mandates in multiple jurisdictions will reshape competitive positioning for component suppliers versus integrated platform providers.
Market Dynamics
Modular bundling of HVAC controls with building automation software is hardening as the dominant procurement format across large commercial projects, compressing standalone component margins while elevating integrated platform providers.
Growth Catalysts
- EU Green Deal performance standards:Commercial office developers in Germany now bundle LED lighting with energy management systems under single procurement contracts, tightening envelope and mechanical efficiency thresholds.
- China's Yangtze River Delta municipal codes:Smart thermostat integration is now mandated in new construction across Shanghai, Suzhou, and Hangzhou, concentrating demand for intelligent control layers.
- Healthcare campus retrofit wave:North American hospital facility managers pursue lease-rate premiums through green certification, accelerating turnkey efficiency contract adoption.
Market Restraints
- Copper and rare-earth input volatility:HVAC compressor motors and permanent-magnet generators face raw material cost swings that destabilize equipment pricing.
- Geographic supply concentration:Lithium-ion battery storage systems for building-integrated renewables depend heavily on East Asian cell manufacturing.
- Legacy building stock technical limitations:Pre-1990s concrete structures resist envelope retrofit without structural reinforcement, capping addressable floor area.
Strategic Opportunities
- Mid-rise residential edge-computing penetration:Real-time load management architectures remain underdeployed in 4-12 story rental portfolios outside premium urban cores.
- US Inflation Reduction Act commercial tax credits:Section 179D deductions for energy-efficient building upgrades create immediate capital recovery pathways for retrofit sponsors.
- Digital twin convergence with BIM workflows:Building information modeling platforms are merging with operational energy optimization software, opening new subscription revenue pools.
Industry Challenges
- Controls integration specialist scarcity:Facility engineering teams lack personnel fluent in both BACnet protocols and cloud-native API architectures.
- Multi-certification timeline compression:Pursuit of simultaneous ENERGY STAR, LEED, and WELL certifications strains project management bandwidth.
- Existing BAS protocol fragmentation:Proprietary legacy systems from multiple vintages resist seamless integration with open IoT platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy-Efficient Building Market |
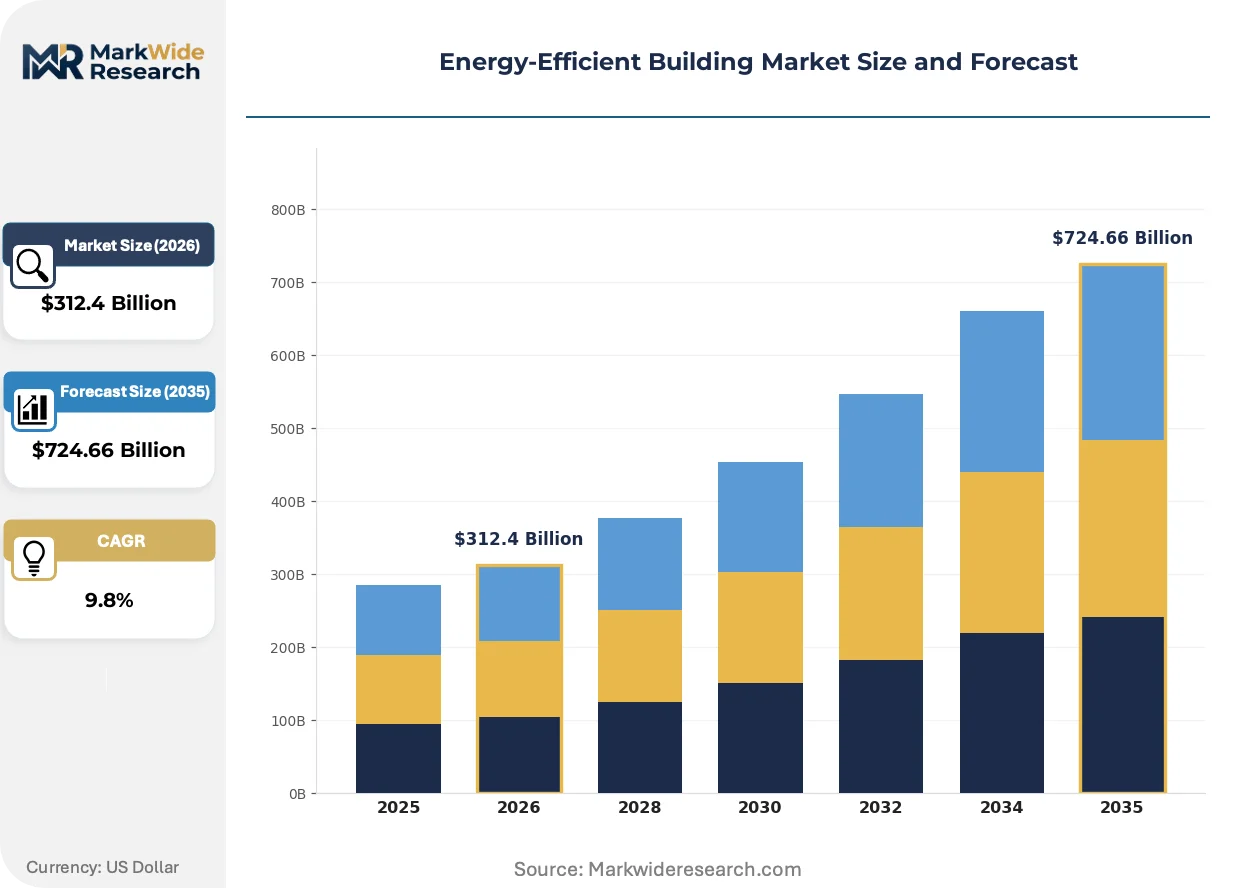
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $724.66 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Energy Source: Solar, Wind, Biomass, Geothermal Technology: LED Lighting, Smart Thermostats, Energy Management Systems, Insulation Materials End User: Homeowners, Contractors, Architects, Facility Managers |
| Companies Covered | Johnson Controls, Siemens AG, Honeywell International Inc., Schneider Electric SE, ABB Ltd., Trane Technologies, Daikin Industries Ltd., Rockwool International A/S, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy-Efficient Building Market Strategic Shifts & Innovations
Building energy management is undergoing a platform consolidation wave where discrete hardware categories are collapsing into unified software-defined systems, altering vendor competitive boundaries and procurement evaluation criteria.
Building operating systems is unifying previously siloed HVAC, lighting, and security controls into single-pane management environments. Large commercial landlords in Class A office towers are adopting these platforms at accelerating pace, compressing the addressable market for standalone thermostat and lighting control vendors while expanding contract values for integrated providers.
CSRD disclosure mandates are forcing real estate investment trusts to install granular sub-metering infrastructure across their portfolios. This regulatory pressure is reshaping capital allocation toward data acquisition hardware and third-party verification services, with European commercial REITs now treating energy performance transparency as a portfolio risk management function rather than a marketing exercise.
Facility managers are consolidating vendor relationships around turnkey performance contracts that guarantee absolute kilowatt-hour reductions rather than equipment specifications. This buying-pattern shift is displacing traditional equipment-only procurement in North American healthcare and education verticals, with payment structures now tying contractor compensation to measured utility savings over multi-year terms.
Energy-Efficient Building Market Segmentation
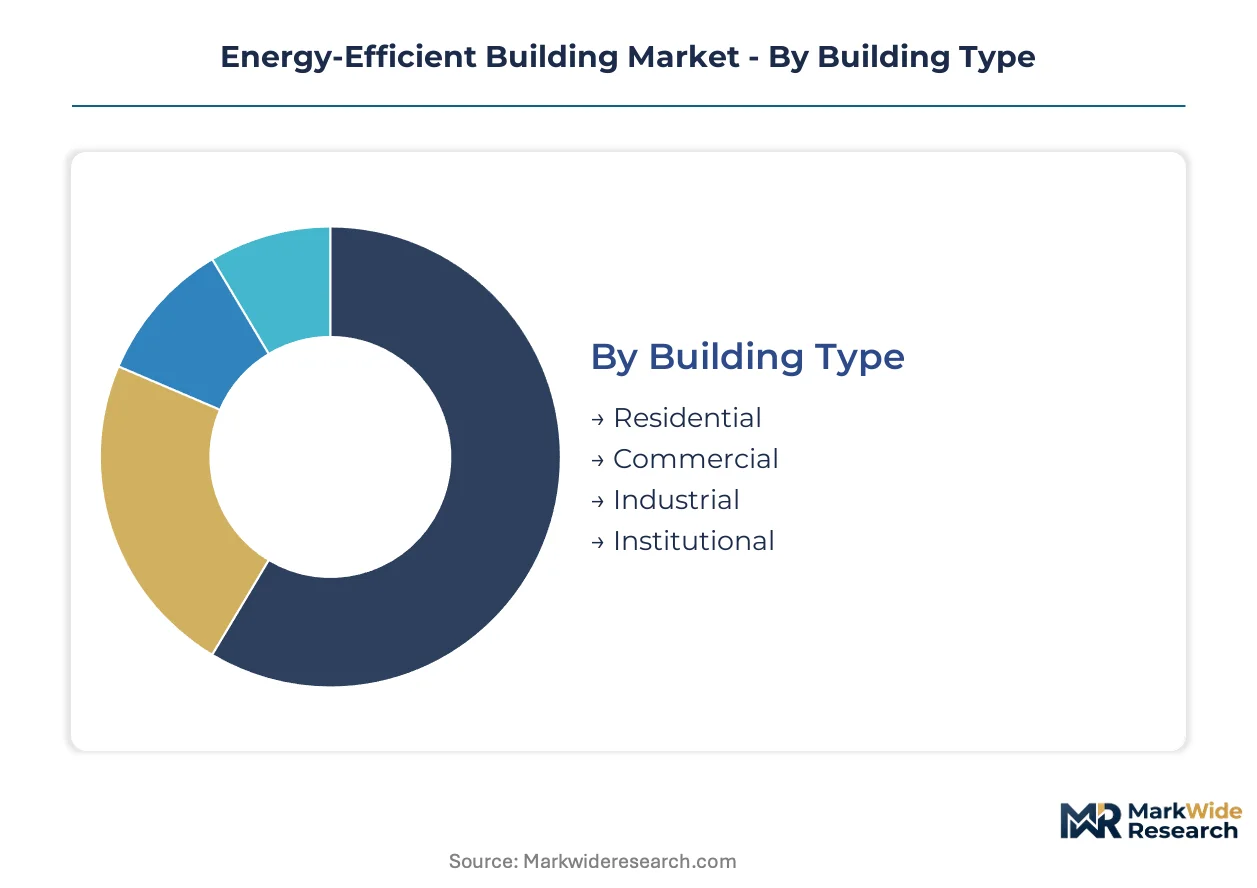
Segmentation in energy-efficient buildings reveals how procurement power concentrates across buyer types and how technology bundling reshapes vendor competitive boundaries. Understanding these divides exposes where margin pools migrate and which specifications dominate capital allocation decisions.
Building Type:
Supply concentration in turnkey efficiency contracting has elevated commercial and institutional segments as the primary revenue anchors for integrated platform providers.
- Commercial:Class A office towers and retail portfolios drive bundled LED-HVAC-automation procurement under single contracts. Germany's commercial developers now consolidate envelope and mechanical efficiency specifications under unified procurement vehicles per EU Green Deal mandates.
- Residential:Mid-rise rental buildings (4-12 stories) remain underpenetrated by edge-computing architectures despite code mandates in China's Yangtze River Delta cities. Technical constraints in pre-1990s concrete structures cap retrofit addressability.
- Industrial:Manufacturing facilities prioritize process-load optimization over envelope upgrades, favoring energy management systems with sub-metering granularity.
- Institutional:North American healthcare campuses anchor the retrofit wave, with facility managers tying contractor compensation to measured kilowatt-hour reductions over multi-year terms.
Today's leader: Commercial. Tomorrow's challenger: Institutional.
Energy Source:
Cost tier differentiation separates capital-intensive on-site generation from grid-purchased efficiency, with net-metering frameworks determining solar penetration depth.
- Solar:Building-integrated photovoltaics concentrate in jurisdictions with favorable net-metering policies. Lithium-ion storage dependencies on East Asian cell manufacturing create supply concentration risks.
- Geothermal:District heating networks in Nordic and Central European clusters exploit stable subsurface temperatures for baseload thermal supply.
- Biomass:Combined heat-and-power installations serve campus-scale thermal loads in forestry-rich regions with established fuel logistics.
- Wind:Urban micro-turbines occupy niche positions in high-rise commercial towers with sufficient rooftop exposure and local permitting tolerance.
Current volume anchor: Solar. Emerging infrastructure play: Geothermal.
Technology:
Application intensity varies sharply across end-use verticals, with energy management systems displacing standalone controls as the default procurement layer.
- Energy Management Systems:Real-time load optimization platforms unify HVAC, lighting, and security into single-pane environments. Large commercial landlords adopt these systems at accelerating pace, compressing margins for discrete thermostat and lighting vendors.
- LED Lighting:Efficacy exceeding 120 lumens per watt is now baseline for new commercial construction, with German developers bundling specifications into unified procurement contracts.
- Smart Thermostats:Municipal mandates in Shanghai, Suzhou, and Hangzhou concentrate demand for intelligent control layers in new residential construction.
- Insulation Materials:Roof assemblies achieving R-values above 30 and wall cavities exceeding R-20 face technical limitations in legacy concrete structures requiring structural reinforcement.
Platform consolidation winner: Energy Management Systems. Commoditization pressure point: LED Lighting.
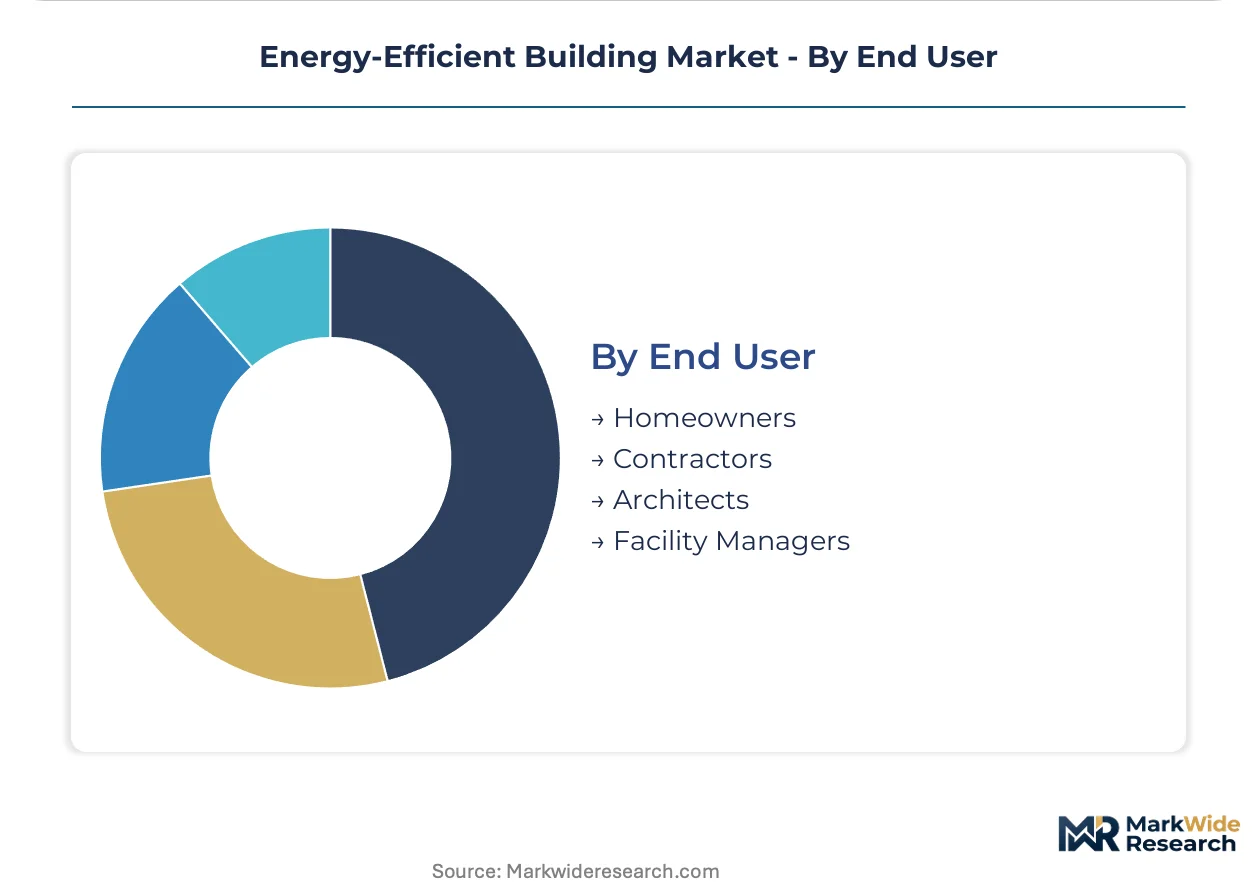
End User:
Customer type determines specification authority and procurement format, with facility managers consolidating vendor relationships around outcome-based contracts.
- Facility Managers:Class A commercial landlords and healthcare campus operators now demand guaranteed kilowatt-hour reductions rather than equipment specifications, reshaping contractor compensation structures.
- Contractors:Turnkey efficiency specialists capture escalating contract values by integrating HVAC, controls, and verification services under performance guarantees.
- Architects:Digital twin convergence with BIM workflows creates subscription revenue opportunities for energy optimization software embedded in design-phase tooling.
- Homeowners:Fragmented decision-making and capital constraints limit penetration of integrated systems outside premium urban cores and subsidy-eligible retrofits.
Procurement power center: Facility Managers. Specification influence: Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern building energy codes through its EnEV standards in the early 2000s, establishing the regulatory template that shaped EU-wide efficiency mandates. The country's Passivhaus movement scaled high-performance envelope construction across Central Europe before spreading to North American and Asian markets.
Germany
Commercial office developers in Frankfurt and Munich bundle LED lighting with energy management systems under unified procurement contracts. The EU Green Deal's Energy Performance of Buildings Directive tightens envelope and mechanical efficiency thresholds through 2030. Bavaria's industrial building stock leads retrofit intensity, with facility managers tying contractor compensation to measured kilowatt-hour reductions.
United States
Healthcare campuses in Texas and Illinois anchor the North American retrofit wave, with hospital facility managers pursuing lease-rate premiums through green certification. The EPA's ENERGY STAR program and Section 179D deductions under the Inflation Reduction Act create immediate capital recovery pathways. Greater Boston's Class A office towers adopt building operating systems at accelerating pace, compressing margins for standalone control vendors.
China
Municipal building codes in Shanghai, Suzhou, and Hangzhou mandate smart thermostat integration in new residential construction across the Yangtze River Delta. The country's GB standards enforce mandatory efficiency ratios for envelope and mechanical systems under dual carbon goals. Beijing-Tianjin-Hebei's commercial districts concentrate demand for integrated HVAC-automation platforms in premium office developments.
Japan
Tokyo's commercial landlords consolidate vendor relationships around turnkey performance contracts guaranteeing absolute kilowatt-hour reductions. METI's building energy efficiency standards and Top Runner programs drive equipment replacement cycles in Kansai and Chubu regions. Osaka's healthcare and education verticals displace traditional equipment-only procurement with multi-year savings-linked payment structures.
United Kingdom
London's real estate investment trusts install granular sub-metering infrastructure to comply with CSRD disclosure mandates, treating energy performance transparency as portfolio risk management. The country's Building Regulations Part L tightens operational efficiency requirements for new construction. Manchester and Birmingham's Class A office markets accelerate adoption of unified software-defined building management environments.
Energy-Efficient Building Market Key Industry Players
The competitive structure tilts toward integrated platform providers with captive hardware supply and deep software capabilities. Consolidation pressure compresses standalone component margins while elevating contract values for turnkey efficiency specialists. Three archetypes dominate: diversified industrial conglomerates with building automation divisions, pure-play energy management software vendors, and building materials suppliers extending into digital services. Geographic expansion through performance contracting and strategic partnerships for protocol interoperability constitute the dominant competitive moves.
Among diversified industrial conglomerates, Johnson Controls and Siemens AG exemplify the integrated platform archetype, anchoring turnkey efficiency contracts through captive supply of chillers, digital controls, and optimization software. Schneider Electric SE occupies a distinct position with edge-computing architectures extending real-time load management to mid-rise residential portfolios outside premium urban cores. Honeywell International Inc. represents the controls-to-software transition path, consolidating previously siloed HVAC, lighting, and security environments into single-pane management systems for large commercial landlords.
| Leading Market Players |
|---|
| Johnson Controls |
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric SE |
| ABB Ltd. |
| Trane Technologies |
| Daikin Industries Ltd. |
| Rockwool International A/S |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Turnkey efficiency contractors in North American healthcare and education verticals now dominate procurement volumes, compressing margins for standalone component vendors while elevating integrated platform providers to price-setter status. This buyer concentration forces pricing discipline around outcome-based contracts rather than equipment specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified integrated platforms from code-compliant baseline systems and unbundled component sales. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because LED efficacy gains have commoditized standalone lighting hardware. Healthcare facility managers show least price sensitivity due to lease-rate premium capture, while mid-rise residential developers remain most cost-constrained.
Supply Chain Analysis
Direct-to-institutional channels handle hyperscale buyer demand for turnkey efficiency contracts, bypassing traditional distribution layers. Manufacturing concentration in China, South Korea, and Germany anchors HVAC compressor and digital control production. Raw material dependencies on copper for motor windings, rare-earth elements for permanent-magnet generators, and lithium-ion cells from East Asian suppliers create input cost volatility. Single-source vulnerability in East Asian battery cell manufacturing presents structural supply risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Energy-Efficient Building Market functions as a stable compounder anchored by regulatory ratchet effects that tighten efficiency thresholds across successive code cycles. EU Green Deal mandates and China's dual carbon goals institutionalize demand visibility.
For Market Incumbents: Deepen captive supply integration into chiller and digital control manufacturing to defend margin position against pure-play software entrants. Prioritize BACnet-to-cloud protocol interoperability investments to neutralize emerging API-native competitors. Expand performance contracting capacity in Germany's Bavarian industrial corridor where measured kilowatt-hour reduction guarantees command premium pricing. For New Entrants and Emerging Players: Cloud-native API platforms offer the most penetrable entry vector for mid-rise residential portfolios outside China's Yangtze River Delta premium cores. Target 4-12 story rental buildings in secondary US metros where edge-computing architectures remain underdeployed. Lead with subscription-based energy optimization software that bypasses capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Building automation conglomerates with captive hardware supply are the most active acquirer in this space, consolidating digital twin and edge-computing specialists. The five-to-ten year viability window favors platforms with demonstrated protocol interoperability across legacy BAS vintages. Watch CSRD disclosure mandate enforcement intensity across European REITs as the inflection signal for sub-metering hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Performance Contracting | Guaranteed kilowatt-hour reductions displace equipment-specification procurement in healthcare verticals. |
| Digital Twin Platform Integration | BIM workflow convergence creates recurring subscription revenue pools for energy optimization software. |
| Edge-Computing Architecture Deployment | Real-time load management extends addressable market to mid-rise residential portfolios beyond premium cores. |
| Protocol Interoperability Investment | BACnet-to-cloud bridging neutralizes proprietary legacy BAS fragmentation for integrated providers. |
| Sub-Metering Infrastructure Buildout | CSRD disclosure mandates force European REITs to treat energy transparency as risk management function. |
Research Approach
Bottom-up building type and end-user modeling reconciled against top-down technology supply tracking forms the analytical core. Primary interviews with facility managers, turnkey efficiency contractors, controls integration specialists, and EPC procurement officers combine with secondary validation from EPA ENERGY STAR certification databases, EU Energy Performance of Buildings Directive filings, and China GB standards documentation. Triangulation against customs data for HVAC equipment trade flows and lithium-ion battery cell shipments anchors supply-side calibration.
Historical trendline analysis of efficiency code adoption rates and retrofit spending patterns across commercial, residential, and institutional segments underpins projection modeling. Segmentation dimensions include building type, energy source, technology category, and end-user archetype. CAGRs derive from regression analysis of technology penetration curves and regulatory mandate implementation timelines. Forecast inputs incorporate ENERGY STAR certification velocity and Section 179D tax credit utilization rates.
The model assumes a particular technology adoption path; alternative pathways for building operating system convergence would alter the outlook. Forecasts reflect base-case assumptions regarding EU Green Deal enforcement continuity and China's dual carbon goal commitment durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Italy Construction Market
Building Construction
China Building Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Egypt Construction Market
Building Construction
China Modular Construction Market
Building Construction
El Salvador Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
GCC Green Buildings Market
Building Construction
Bangladesh Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Middle East Building Construction Market
Building Construction
Poland Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
India Construction Market