
 India Pre-Engineered Buildings Market | 2026-2036
India Pre-Engineered Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
India Pre-Engineered Buildings Market Outlook
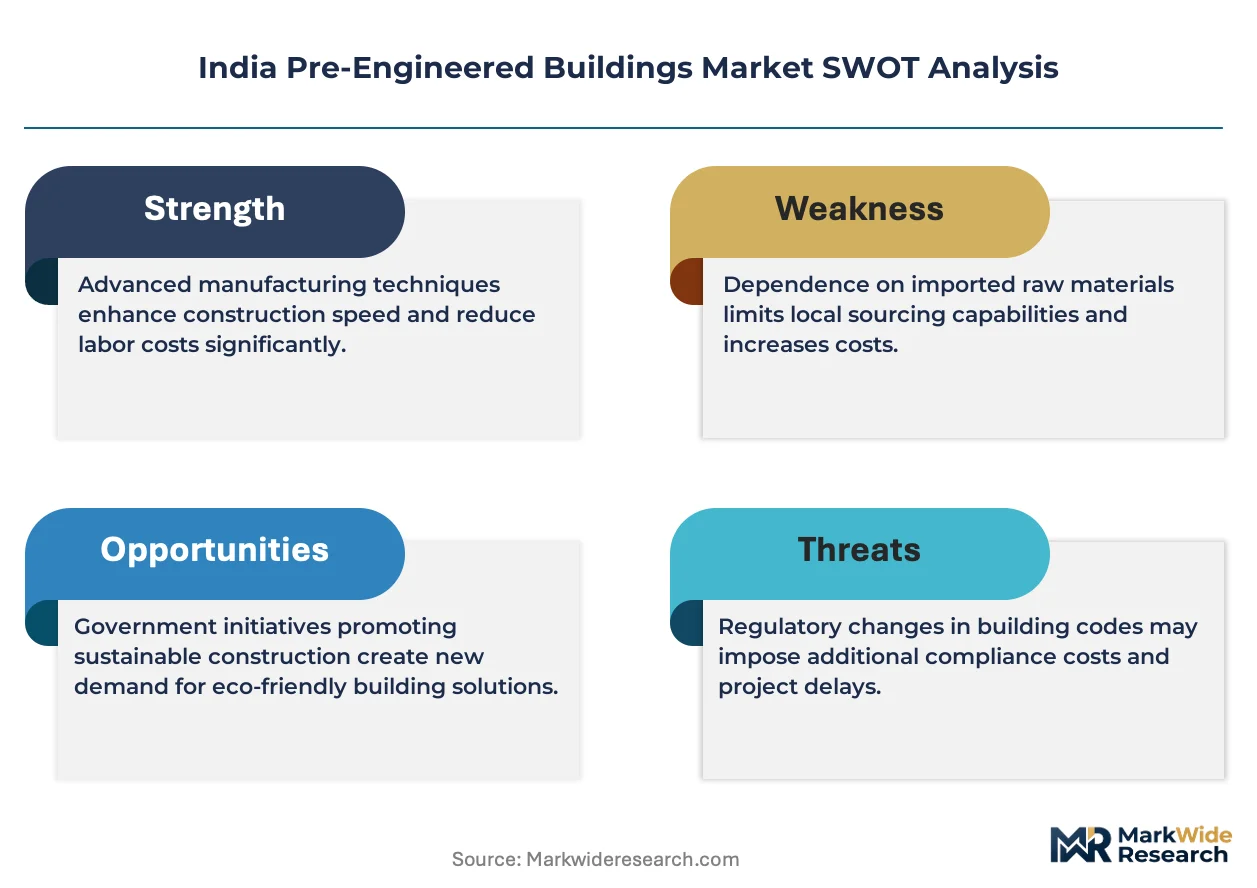
The PLI scheme for specialty steel is pivoting investment toward domestic fabrication capacity. Tata BlueScope Steel leverages its integrated color-coated steel supply to dominate premium industrial projects. Interarch Building Products anchors its position through turnkey solutions across warehousing and airport terminals. Kirby Building Systems sustains cost competitiveness via captive engineering centers in southern India.
Pre-engineered buildings are factory-built steel assemblies using high-tensile galvanized sections bolted on-site, designed for spans exceeding 30 meters without intermediate columns. Steel Structure products lead volume due to their dominance in factory sheds and logistics hubs, while Modular Building segments capture expanding margin pools from data center and cold-chain applications. Turnkey Solutions within Installation Type are growing fastest as real estate developers outsource complete project risk to PEB vendors.
BIS structural steel standards, CEA electrical safety mandates, and state-level factory licensing rules collectively shape product specifications and vendor qualification across India. The central bank's infrastructure lending guidelines influence project finance availability for PEB-based industrial parks. Stakeholders must monitor how state-level single-window clearance reforms affect project velocity in emerging manufacturing clusters.
Market Dynamics
Warehousing developers across Maharashtra and Gujarat are consolidating procurement around single-source PEB vendors to compress project timelines and transfer structural liability risk.
Growth Catalysts
- PLI scheme for specialty steel:Domestic fabrication capacity is expanding as incentive structures favor local cold-rolled coil production over imports.
- Logistics park clusters:Industrial corridor development along the Delhi-Mumbai Industrial Corridor is generating contiguous demand for large-span factory sheds.
- BIS structural steel certification mandate:Quality standardization is filtering out unorganized fabricators and concentrating volume with certified vendors.
Market Restraints
- Galvanized steel price volatility:Input cost swings from international zinc and hot-rolled coil markets compress margin visibility for fixed-price contracts.
- Fabrication capacity concentration:Southern India hosts disproportionate engineering center density, creating geographic supply bottlenecks for northern projects.
- Cast-in-situ concrete substitution:Traditional construction retains preference among public sector buyers with rigid tender specifications.
Strategic Opportunities
- Cold-chain infrastructure:Temperature-controlled warehousing for pharmaceuticals and food processing remains underpenetrated by PEB methods.
- Data center shell construction:Hyperscale facility developers in Hyderabad and Chennai are specifying clear-span PEB structures for rapid deployment.
- State single-window clearance reforms:Karnataka and Tamil Nadu are streamlining factory licensing to accelerate project velocity.
Industry Challenges
- Structural engineer scarcity:PEB-specific design expertise remains concentrated among a limited pool of certified professionals.
- BIS compliance timelines:Steel grade certification delays are extending pre-construction phases by 8-12 weeks.
- Legacy warehouse retrofit integration:Expansion projects face complexity anchoring new PEB bays to existing conventional structures.
Report Scope
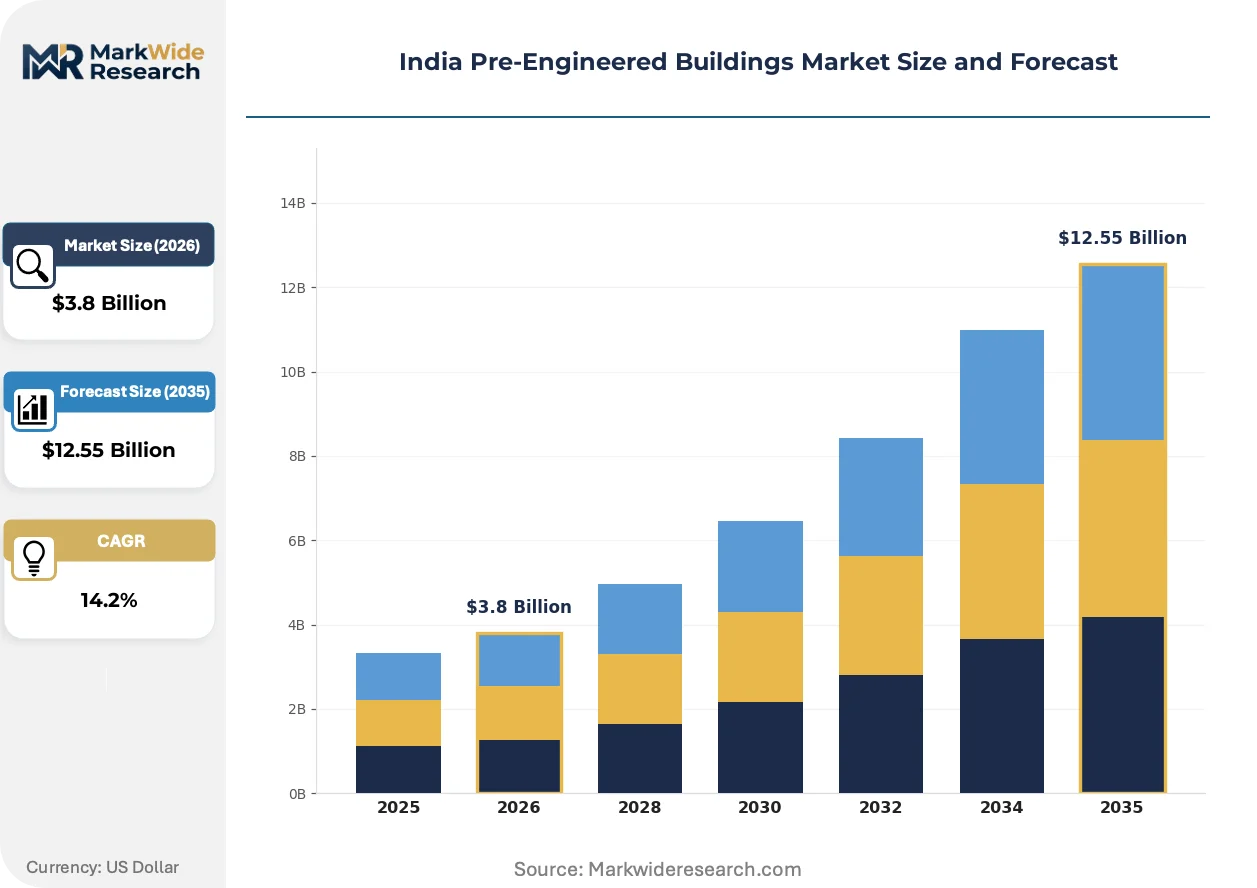
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pre-Engineered Buildings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Structure, Modular Building, Customized Building, Lightweight Structure Application: Commercial, Industrial, Residential, Public Infrastructure End User: Construction Companies, Real Estate Developers, Government Agencies, Private Enterprises Installation Type: On-Site Assembly, Off-Site Fabrication, Hybrid Installation, Turnkey Solutions |
| Companies Covered | Tata BlueScope Steel, Interarch Building Products, Kirby Building Systems, Pennar Industries, Jindal Buildsys, Everest Industries, Zamil Steel Buildings, PEBS Pennar, Epack Prefab, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pre-Engineered Buildings Market Strategic Shifts
Digital fabrication workflows and modular assembly methods are compressing the traditional design-to-occupancy cycle for industrial construction across Indian manufacturing corridors.
High-tensile galvanized steel framing systems are absorbing the structural load requirements for spans exceeding 40 meters without intermediate columns. E-commerce fulfillment operators in the Mumbai-Pune belt are specifying these systems for automated warehouse configurations. The technology is absorbing market share from truss-based conventional steel by reducing on-site welding and enabling just-in-time delivery.
BIS structural steel quality standards are tightening material traceability requirements from mill to site. Fabricators must now maintain batch-level documentation for zinc coating thickness and yield strength. Cold-storage PEB applications face the steepest compliance burden as BIS certification intersects with FSSAI food safety mandates.
Developer procurement patterns are pivoting from component sourcing to integrated turnkey contracts. Real estate funds deploying industrial assets in Gujarat now mandate single-point accountability for design, fabrication, and installation. This consolidation is most pronounced in Ahmedabad and Surat where foreign direct investment into logistics infrastructure is concentrating buyer power.
India Pre-Engineered Buildings Market Segmentation
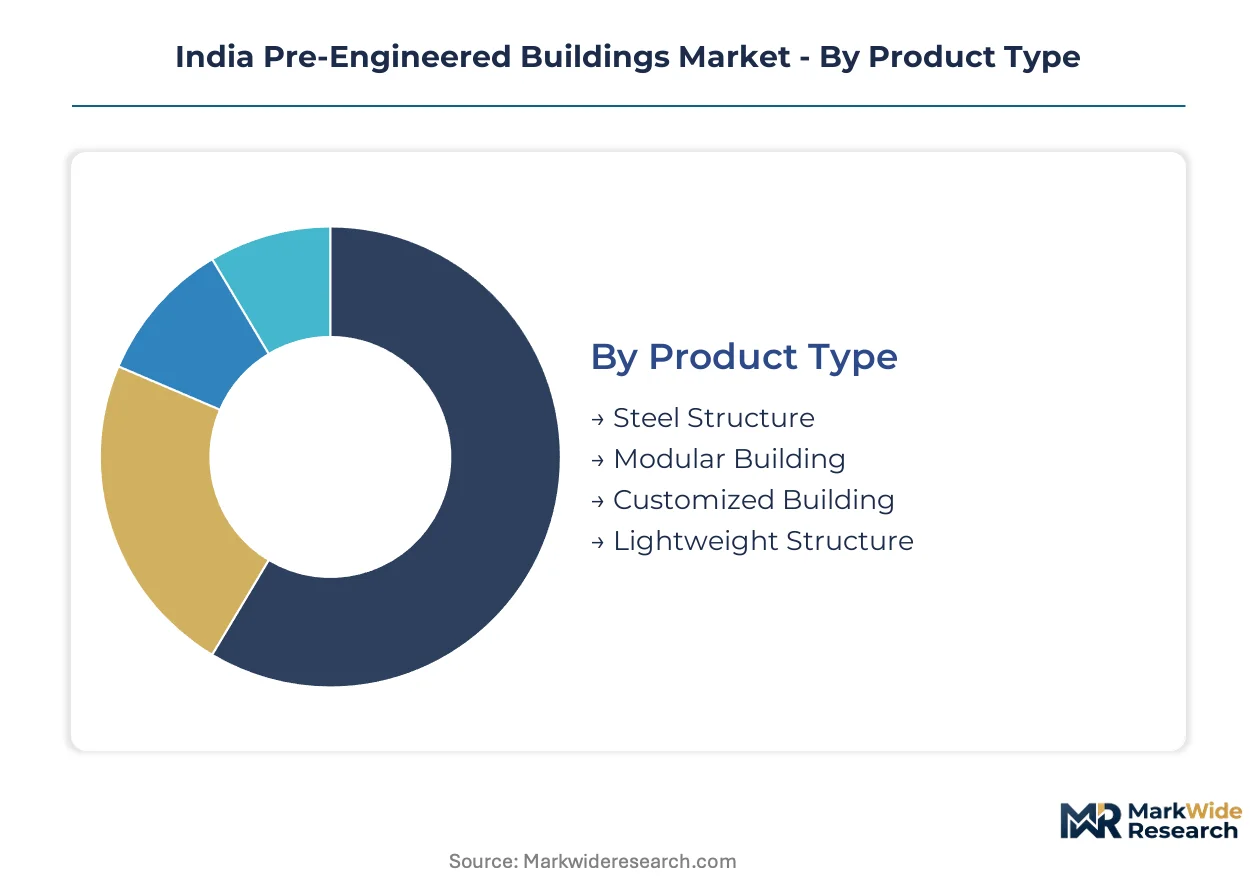
Segmentation in the India PEB market reveals divergent margin structures across product architectures and procurement models. Steel Structure products dominate volume flows through logistics corridor development, while Modular Building segments command premium pricing from data center and cold-chain specifications. Understanding these splits enables vendors to align fabrication capacity with the highest-return installation types.
Product Type:
Steel Structure products anchor mass-market volume, while Modular Building segments capture technology-intensive premiums from specialized thermal and acoustic applications.
- Steel Structure:Factory-built assemblies using high-tensile galvanized sections bolted on-site, engineered for clear spans exceeding 30 meters. Maharashtra and Gujarat warehousing developers specify these systems for rapid logistics park deployment under compressed construction timelines. BIS certification mandates for structural steel quality are filtering out unorganized fabricators and concentrating procurement with certified vendors.
- Modular Building:Precision-fabricated volumetric units assembled under controlled factory conditions before transport. Data center developers in Hyderabad and Chennai are specifying these for hyperscale shell construction, driven by FSSAI and thermal compliance requirements for pharmaceutical cold-chain integration. This segment gains share fastest from conventional cast-in-situ methods.
- Customized Building:Architecturally adapted PEB systems incorporating non-standard facades, multi-level configurations, or hybrid material integration. Airport terminal projects in Bangalore and Delhi specify these for passenger-facing aesthetics.
- Lightweight Structure:Cold-formed steel framing systems for ancillary structures, mezzanines, and equipment enclosures. Secondary applications in industrial parks across Tamil Nadu absorb this output.
Today's leader: Steel Structure. Tomorrow's challenger: Modular Building.
Application:
Industrial applications concentrate procurement volume through corridor development, while Commercial segments fragment across retail and office specifications with diverging design standards.
- Industrial:Factory sheds, manufacturing facilities, and processing plants requiring column-free spans for material handling systems. The Delhi-Mumbai Industrial Corridor generates contiguous demand for large-span structures from automotive and electronics manufacturing investments. PLI scheme incentives for specialty steel are pivoting fabrication capacity toward domestic supply chains serving this segment.
- Commercial:Retail centers, office complexes, and exhibition halls incorporating PEB frames with conventional facade systems. Ahmedabad and Surat real estate funds are consolidating procurement around turnkey vendors to transfer structural liability risk.
- Residential:Low-rise housing and worker accommodation using lightweight steel framing. Affordable housing projects in Karnataka are testing PEB methods for speed-to-delivery.
- Public Infrastructure:Railway stations, metro depots, and civic facilities with extended tender cycles and rigid specification requirements. Cast-in-situ concrete substitution pressure remains strongest here.
Industrial commands current procurement volume. Commercial exhibits the steepest expansion trajectory as private capital flows into logistics-adjacent real estate.
End User:
Construction companies intermediate project risk for institutional capital, while real estate developers are consolidating vendor relationships to compress design-to-occupancy cycles.
- Construction Companies:Engineering-procurement-construction contractors executing industrial and infrastructure projects on fixed-price contracts. These firms absorb galvanized steel price volatility through hedging and long-term supply agreements with Tata BlueScope and similar integrated suppliers.
- Real Estate Developers:Asset owners and fund managers deploying warehousing and logistics parks across Gujarat and Maharashtra. Single-window clearance reforms in Karnataka and Tamil Nadu are accelerating project velocity for this buyer class.
- Government Agencies:Public sector undertakings and state industrial development corporations with rigid tender specifications favoring conventional construction. BIS compliance timelines extend pre-construction phases by 8-12 weeks for these buyers.
- Private Enterprises:Manufacturing firms and logistics operators building captive facilities. E-commerce fulfillment operators in the Mumbai-Pune belt specify high-tensile systems for automated warehouse configurations.
Construction companies dominate transaction flow. Real estate developers are capturing decision-making authority through integrated turnkey mandates.
Installation Type:
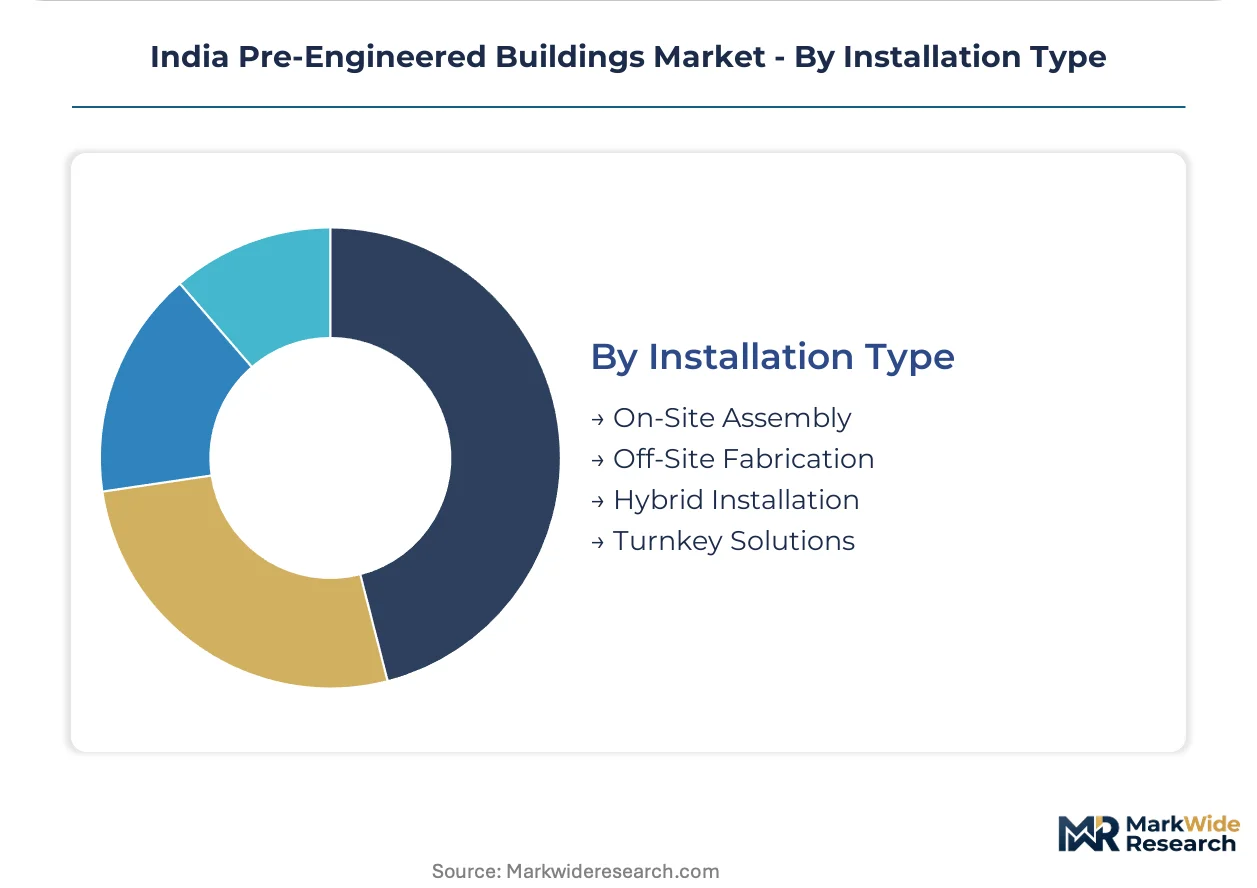
Turnkey Solutions are displacing component sourcing as developers outsource complete project risk, while On-Site Assembly retains cost-sensitive industrial applications.
- Turnkey Solutions:Integrated contracts covering design, fabrication, transportation, and installation with single-point accountability. Interarch Building Products anchors market position through this model across warehousing and airport terminal projects. Real estate funds now mandate this structure to compress timelines and transfer liability.
- On-Site Assembly:Bolt-together erection of factory-delivered structural components using local labor crews. Cost-sensitive factory shed projects in secondary industrial clusters retain this approach.
- Off-Site Fabrication:Complete structural module production in controlled factory environments before transport to site. Modular data center applications favor this method for quality control.
- Hybrid Installation:Combination of pre-fabricated primary frames with locally sourced secondary elements. Legacy warehouse retrofit projects use this approach to anchor new PEB bays to existing conventional structures.
Turnkey Solutions are expanding most quickly through institutional capital deployment. On-Site Assembly defends position in price-driven secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural engineer talent pools concentrate in southern India, creating geographic asymmetries in design capacity that reshape project economics across state boundaries.
Maharashtra
Logistics park developers in Mumbai and Pune drive PEB procurement for e-commerce fulfillment centers. The state industrial development corporation streamlines factory licensing through single-window clearance mechanisms. The Mumbai-Pune belt absorbs premium high-tensile systems for automated warehouse configurations requiring 40-meter clear spans.
Gujarat
Foreign direct investment into port-linked industrial zones generates contiguous demand for large-span factory sheds. The Bureau of Indian Standards certification mandate filters procurement toward certified vendors with documented steel traceability. Ahmedabad and Surat warehousing developers consolidate around turnkey contracts to transfer structural liability risk.
Karnataka
Data center hyperscale projects in Hyderabad and Chennai specify modular PEB shells for rapid deployment timelines. State-level single-window clearance reforms compress pre-construction phases by standardizing factory licensing workflows. The Bangalore industrial corridor anchors premium fabrication capacity serving pharmaceutical cold-chain specifications.
Tamil Nadu
Automotive manufacturing investments along the Chennai-Detroit corridor generate demand for column-free assembly facilities. Central Electricity Authority electrical safety mandates intersect with state factory rules to shape vendor qualification requirements. The Sriperumbudur-Oragadam belt concentrates captive engineering centers serving northern project pipelines.
Telangana
Pharmaceutical warehousing operators specify thermally compliant PEB systems for temperature-controlled storage. Food Safety and Standards Authority of India mandates intersect with BIS structural standards to create dual certification burdens. The Hyderabad pharma cluster drives modular building adoption for rapid facility expansion cycles.
India Pre-Engineered Buildings Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where integrated steel suppliers anchor premium industrial projects while regional fabricators defend cost-sensitive secondary markets. The vendor base stratifies into three archetypes: integrated steel-to-building suppliers, turnkey solution providers, and component-focused regional fabricators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players seek to bridge geographic supply gaps.
Among integrated steel suppliers, Tata BlueScope Steel exemplifies the backward-integrated archetype with captive color-coated coil production. Interarch Building Products and Kirby Building Systems occupy positions within the turnkey solutions tier, anchoring procurement consolidation trends among institutional real estate developers. These three entities represent distinct strategic postures: upstream supply control, integrated project delivery, and regional engineering density.
| Leading Market Players |
|---|
| Tata BlueScope Steel |
| Interarch Building Products |
| Kirby Building Systems |
| Pennar Industries |
| Jindal Buildsys |
| Everest Industries |
| Zamil Steel Buildings |
| PEBS Pennar |
| Epack Prefab |
| Others |
Value Chain & Pricing Dynamics
Turnkey certification premiums versus component-only commodity tiers split the India PEB market into divergent pricing architectures, with BIS-traceable steel commanding structural liability transfer value that unbundled procurement cannot match. Southern engineering center density feeds northern project premiums through logistics and talent arbitrage, while galvanized coil price volatility transmits directly into fixed-contract margin compression.
Pricing Analysis
Turnkey versus component-only procurement splits dominate pricing architecture. Three-tier pricing structure across certified-premium, standard-BIS, and unorganized-economy levels tracks steel traceability depth and engineering accountability scope. Price differentiation hinges on BIS certification grade and bundled installation liability. Pricing pressure stems from international zinc and hot-rolled coil volatility eroding fixed-price contract visibility. Real estate developers exhibit lowest price sensitivity due to risk-transfer mandates, while secondary industrial cluster buyers retain acute cost focus.
Supply Chain Analysis
BIS structural steel certification gates vendor qualification and filters procurement toward documented mill-to-site traceability systems. Domestic supply concentrates in Maharashtra, Gujarat, and Karnataka industrial corridors, with southern engineering centers anchoring design capacity. Raw material dependencies rest on imported zinc, hot-rolled coil, and color-coated steel from integrated suppliers. Supply chain risk centers on single-source vulnerability for high-tensile galvanized sections. Distribution runs through direct vendor-developer contracting with limited intermediary channel presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India PEB market functions as a geographic-arbitrage play where southern engineering density enables northern project premiums, with BIS compliance timelines creating regulatory differentiation between certified and unorganized vendor tiers.
For Market Incumbents: Extend captive engineering center footprints into Tamil Nadu and Karnataka to compress lead times for northern corridor projects. Deepen backward integration into color-coated coil production to absorb galvanized steel price volatility. Defensive positioning requires pre-emptive BIS certification investment before mandate expansion filters additional unorganized competitors from procurement pools. For New Entrants and Emerging Players: Begin with cold-chain infrastructure specifications in Telangana and Andhra Pradesh where FSSAI-BIS dual certification burdens deter incumbent commoditization. Pharmaceutical warehousing and temperature-controlled food processing offer the most penetrable white-space. A design-build-operate contracting angle bypasses turnkey incumbent relationships while capturing recurring facility management revenue. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS compliance capital requirements exceed unorganized fabricator balance sheet capacity. Long-term viability favors regional fabricators with demonstrated certification maintenance and southern engineering access. Acquisition targets should exhibit captive project pipelines from logistics-adjacent real estate funds. The signal to watch is state-level single-window clearance implementation velocity as inflection indicator for project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Color-Coated Coil | Tata BlueScope's captive supply anchors margin defense against zinc price volatility. |
| Turnkey Contract Consolidation | Single-point accountability compresses developer risk transfer timelines across Gujarat logistics parks. |
| Cold-Chain Certification Investment | FSSAI-BIS dual compliance opens pharmaceutical warehousing margins in Hyderabad clusters. |
| Engineering Center Geographic Expansion | Southern talent density enables northern project premium capture through logistics arbitrage. |
| Digital Fabrication Workflow Deployment | Modular assembly methods compress design-to-occupancy cycles for data center developers. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with PEB vendor procurement heads, logistics park developers, structural engineering consultants, and steel mill account managers combined with secondary validation from BIS certification databases, CEA electrical safety filings, state industrial development corporation project registries, and customs import data for zinc and hot-rolled coil. Triangulation between demand-side project pipelines and supply-side engineering center capacity yields volume estimates.
Input-output matrices map steel tonnage requirements by application segment across product type, installation method, and regional corridor. Segmentation dimensions span steel structure versus modular architecture, turnkey versus on-site assembly, and industrial versus commercial end-use. CAGRs derive from project pipeline velocity indexed to PLI scheme disbursement schedules and single-window clearance reform implementation. Forecast inputs incorporate galvanized steel price elasticity and structural engineer labor availability constraints.
Several conditions sit outside the modeled scope, including geopolitical trade policy shifts affecting zinc import tariffs, force majeure disruptions to steel mill operations, and accelerated cast-in-situ concrete substitution in public infrastructure tenders. Forecasts reflect documented assumptions regarding BIS certification timeline standardization and logistics park FDI continuity. Deviation in state-level clearance reform implementation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Qatar Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
China Building Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Bangladesh Construction Market
Building Construction
Honduras Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Dominican Republic Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Spain Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Asia Pacific Modular Construction Market