
 Africa Oil Refining Market | 2026-2036
Africa Oil Refining Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Oil Refining Market Outlook
AFRI-4 fuel standards is broadening the cost-of-entry calculus for refiners across the continent, mandating maximum sulfur content of 50 parts per million in gasoline and diesel. Dangote Refinery leverages its single-train crude distillation capacity to capture margin pools previously lost to European product imports. Egyptian Refining Company (ERC) anchors the Mediterranean supply architecture with hydrocracking configurations tuned for regional crude slates. Sonatrach competes through captive feedstock access and pipeline-linked distribution across North African markets.
Africa oil refining encompasses thermal and catalytic processes that transform crude petroleum into transportation fuels, petrochemical feedstocks, and heating oils through atmospheric distillation, vacuum distillation, and conversion units operating at temperatures exceeding 400 degrees Celsius. The primary purpose centers on reducing import dependence and capturing value from domestically produced crude. Diesel commands the largest share of product output, reflecting heavy-duty transport and power generation demand across markets with unreliable grid infrastructure. Jet Fuel represents the fastest-expanding product category, driven by aviation route expansion between Lagos, Nairobi, and Addis Ababa. Cracking technology leads capital deployment, though Hydroprocessing investment is accelerating as refiners retrofit for AFRI-4 compliance.
South Africa's Department of Mineral Resources and Energy enforces Clean Fuels 2 specifications, while Nigeria's Department of Petroleum Resources administers the SON cap on sulfur and benzene content; both frameworks compel refinery upgrade cycles and filter out marginal operators. The African Petroleum Producers' Organization coordinates crude-for-product swap arrangements that shape regional trade flows. Stakeholders must monitor feedstock availability against committed offtake agreements as brownfield upgrade timelines stretch across multiple development cycles.
Market Dynamics
AFRI-4 fuel standards are compressing the operating envelope for Africa's legacy refineries, forcing simultaneous investment in desulfurization trains and hydrotreater capacity while margins on high-sulfur fuel oil collapse. The regulatory cascade is separating facilities with upgrade capital from stranded assets.
Growth Catalysts
- AFRI-4 Sulfur Caps:Nigeria's Department of Petroleum Resources and South Africa's Department of Mineral Resources and Energy are enforcing 50 ppm sulfur limits in gasoline and diesel, compelling refinery upgrade cycles that filter out marginal operators and concentrate volume among compliant facilities.
- Aviation Route Expansion:Jet fuel offtake is accelerating as carriers expand frequencies between Lagos, Nairobi, and Addis Ababa, creating dedicated product demand that justifies hydrocracker investment for kerosene yield optimization.
- Import Substitution Economics:West African governments are prioritizing domestic refining capacity to capture margin pools previously lost to European product imports, with pipeline-linked distribution corridors reducing coastal tanker dependence.
Market Restraints
- Crude Feedstock Volatility:Regional refiners face exposure to Brent-linked crude differentials and local production shortfalls, with Nigerian crude output instability disrupting committed offtake agreements for nameplate capacity.
- Capital Intensity Barriers:Hydroprocessing and desulfurization retrofits require nine-figure dollar commitments that exceed balance sheet capacity for state-owned refineries without sovereign guarantee structures.
- European Product Competition:Northwest European refineries with excess gasoline yield and lower sulfur baselines continue to arbitrage into West African markets during regional demand peaks, compressing domestic margin capture.
Strategic Opportunities
- East African Greenfield Development:Uganda and Kenya present undeveloped demand centers with no legacy refinery infrastructure, enabling purpose-built facilities configured for regional crude slates and AFRI-4 compliance from commissioning.
- Petrochemical Integration:Refiners with FCC and steam cracker adjacencies can pivot naphtha output into polyethylene and polypropylene feedstocks as East African packaging and construction demand expands.
- Swap Arrangement Structuring:The African Petroleum Producers' Organization coordinates crude-for-product barter mechanisms that allow crude-rich members to secure refined product without hard currency exposure.
Industry Challenges
- Hydroprocessing Talent Scarcity:The specialized welding, catalyst handling, and process control expertise required for hydrotreater commissioning and operation is concentrated among a limited pool of expatriate contractors, stretching project timelines.
- Legacy Asset Stranding:Simple refineries with atmospheric distillation-only configurations face asset-level obsolescence as product specifications tighten, with decommissioning liabilities exceeding residual book value.
- Certification Timeline Compression:AFRI-4 compliance testing and product certification through national standards bodies creates batch-release bottlenecks that disrupt just-in-time distribution to retail networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Oil Refining Market |
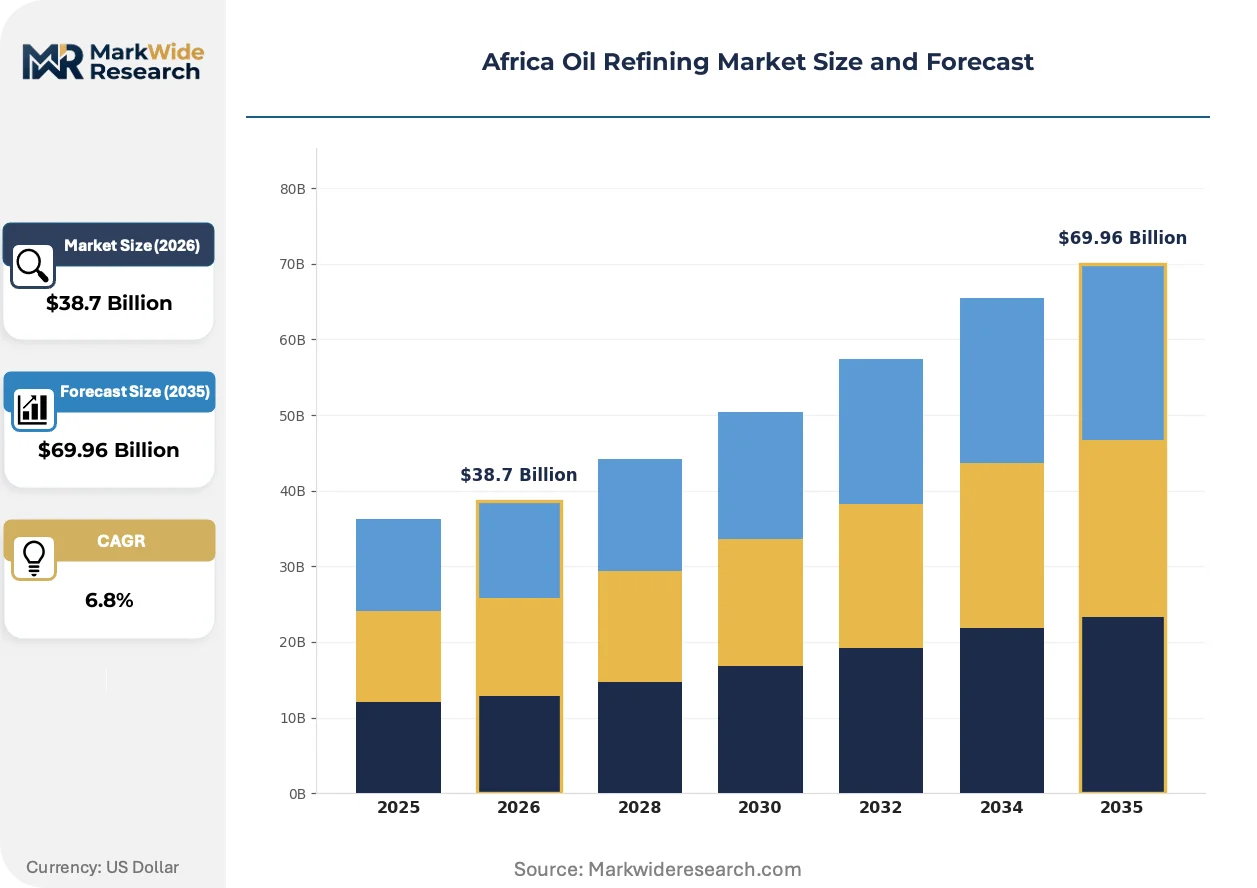
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Liquefied Petroleum Gas End User: Industrial, Transportation, Residential, Commercial Technology: Cracking, Hydroprocessing, Reformation, Distillation Installation: Greenfield, Brownfield, Upgradation, Decommissioning |
| Companies Covered | Dangote Refinery, Egyptian Refining Company (ERC), Nigerian National Petroleum Corporation (NNPC), Sonatrach, Midoil Refining & Petrochemicals Company Ltd, Engen Petroleum Ltd, Indorama Eleme Petrochemicals Ltd, NDEP PLC, Oryx Energies SA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Oil Refining Market Strategic Shifts
Digital process control and modular reactor design are compressing construction schedules for new capacity, while regulatory harmonization across African economic blocs is standardizing product specifications that previously fragmented procurement.
Single-train crude distillation with integrated hydrocracking is unifying the refinery configuration favored for new African projects. Nigerian and Egyptian operators are adopting this architecture to maximize diesel and jet fuel yields from regional crude slates. The technology is unifying the investment calculus for import-substitution projects that previously required European engineering consortiums for complex multi-train layouts.
South Africa's Clean Fuels 2 specifications and Nigeria's SON caps on benzene content are forcing simultaneous gasoline and diesel quality upgrades that legacy hydrotreaters cannot achieve in single-pass operation. Refiners are responding with two-stage hydrotreater sequences and hydrogen plant expansions that consume 15-20% of facility energy balance. West African transport operators face the steepest cost pass-through as they absorb the compliance premium on high-volume diesel consumption.
Long-term offtake contracting is displacing spot market procurement for refined product in West African power generation and mining verticals. Industrial buyers in Ghana and Senegal are locking in 3-5 year supply agreements with fixed differentials to European benchmarks, replacing the previous reliance on tender-based spot purchases. This pattern is most visible in captive power installations for gold mining operations in the Ashanti belt, where fuel security now outweighs price optimization in procurement criteria.
Africa Oil Refining Market Segmentation
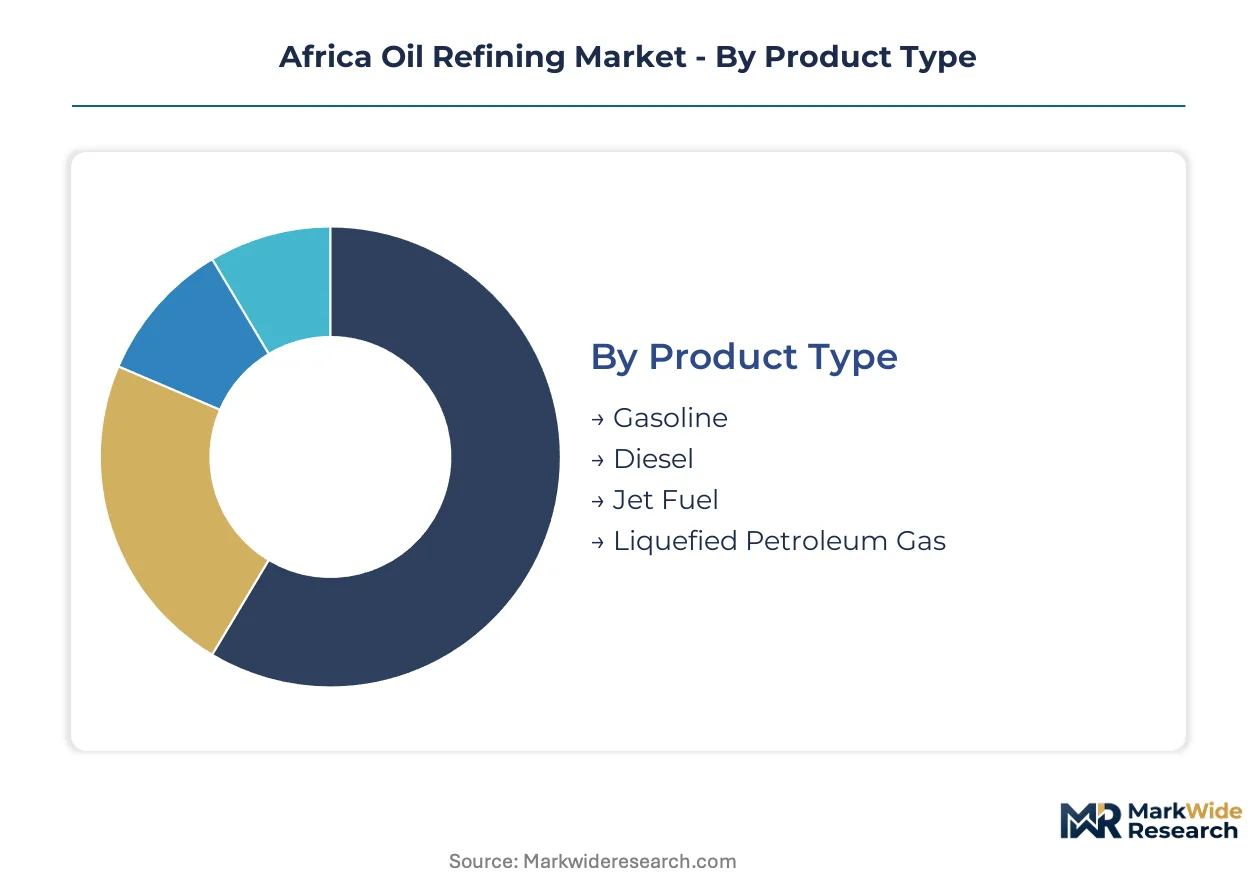
Refinery configuration choices in Africa's oil refining market hinge on product slate optimization and regulatory compliance costs. Each segmentation dimension carries distinct capital intensity profiles and margin structures that determine project viability across the continent's disparate demand centers.
Product Type:
AFRI-4 sulfur specifications and national benzene caps impose differentiated compliance burdens across fuel categories, with diesel and gasoline facing the most stringent testing protocols.
- Diesel:High-cetane middle distillate formulated for compression-ignition engines across heavy-duty transport and captive power generation. Demand concentrates in Nigeria's Lagos-Ibadan corridor and South Africa's mining belt, where grid instability forces reliance on diesel-fired backup systems. AFRI-4 sulfur limits of 50 ppm require hydrotreater investment that elevates production costs above legacy fuel oil pricing.
- Jet Fuel:Kerosene-range aviation turbine fuel meeting stringent freeze point and smoke point specifications for commercial aviation. Route expansion between Lagos, Nairobi, and Addis Ababa is concentrating offtake at hub airports, with Dangote Refinery and Egyptian Refining Company competing for supply contracts through dedicated jetty infrastructure.
- Gasoline:Light distillate for spark-ignition engines subject to benzene content caps under Nigeria's SON standards and South Africa's Clean Fuels 2 framework.
- Liquefied Petroleum Gas:Propane-butane blend serving residential cooking and commercial heating applications, with import dependence persisting in East African markets lacking fractionation capacity.
Leading the category by volume: Diesel. Growing fastest: Jet Fuel.
End User:
Customer procurement patterns split between long-term contract security and spot market flexibility, with industrial buyers prioritizing supply certainty over price optimization.
- Transportation:Fleet operators and aviation carriers consuming 60-70% of refined product output across African markets. West African road freight operators face steepest cost pass-through from AFRI-4 compliance premiums on high-volume diesel consumption.
- Industrial:Mining, manufacturing, and power generation facilities with captive fuel demand and storage infrastructure. Gold mining operations in Ghana's Ashanti belt are locking in 3-5 year supply agreements with fixed European benchmark differentials.
- Residential:Household consumers of LPG for cooking and kerosene for lighting in markets with unreliable electricity access.
- Commercial:Retail fuel stations, logistics depots, and distributed power installations serving urban commercial centers.
Highest contract coverage: Industrial. Most price-sensitive: Residential.
Technology:
Capital deployment splits between conversion intensity and desulfurization depth, with hydroprocessing commanding premium engineering resources.
- Cracking:Thermal and catalytic processes breaking heavy hydrocarbons into lighter, higher-value products. FCC units at Egyptian Refining Company and Dangote Refinery maximize gasoline and propylene yields from regional crude slates.
- Hydroprocessing:Hydrogen addition reactions removing sulfur, nitrogen, and metals while upgrading product quality. Hydrotreater commissioning faces talent scarcity, with specialized welding and catalyst handling expertise concentrated among limited expatriate contractor pools.
- Reformation:Catalytic restructuring of naphtha into high-octane gasoline blendstock.
- Distillation:Atmospheric and vacuum separation of crude into fractionated product streams.
Dominant by installed base: Distillation. Fastest capital inflow: Hydroprocessing.
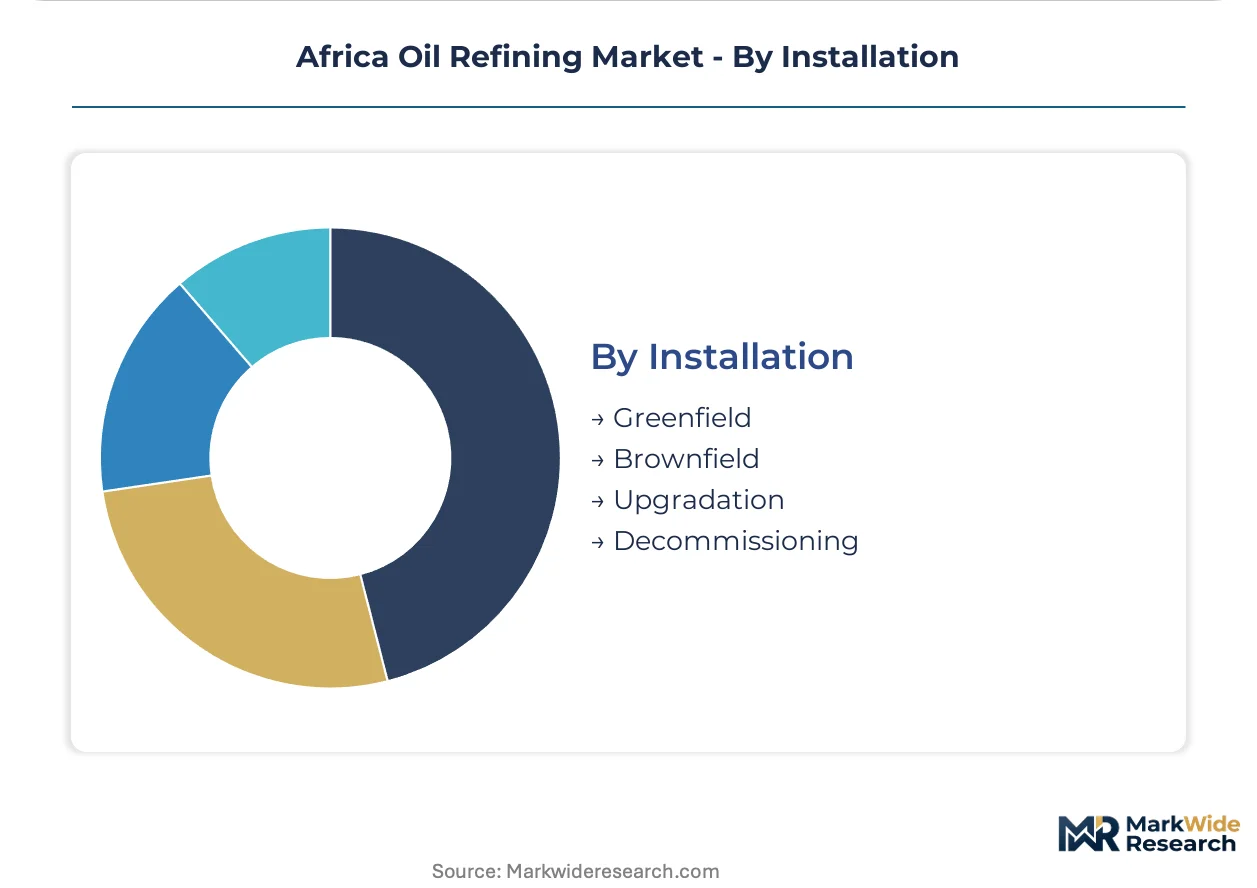
Installation:
Project delivery mode determines regulatory approval pathways and financing structure complexity.
- Greenfield:New-build facilities on undeveloped sites, prevalent in East African markets lacking legacy infrastructure. Uganda and Kenya present undeveloped demand centers enabling purpose-built AFRI-4-compliant configurations from commissioning.
- Brownfield:Expansion of existing refinery complexes with incremental capacity additions. Nigerian brownfield upgrades stretch across multiple development cycles, exposing sponsors to feedstock availability risks against committed offtake agreements.
- Upgradation:Retrofit of existing units for specification compliance or yield optimization.
- Decommissioning:Closure of stranded simple refineries with atmospheric distillation-only configurations.
Maximum capital deployment: Greenfield. Rising liability exposure: Decommissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lekki Free Trade Zone in Nigeria concentrates refinery investment through tax holidays and duty exemptions on capital equipment imports, anchoring West Africa's largest single-train distillation complex.
Nigeria
Dangote Refinery's 650,000 barrels per day capacity dominates Lagos corridor supply, displacing European gasoline and diesel imports that previously satisfied 90% of domestic demand. The Department of Petroleum Resources enforces SON caps on sulfur and benzene content, compelling upgrade cycles at legacy Warri and Kaduna facilities. Port Harcourt refineries remain under rehabilitation, exposing feedstock availability risks against committed offtake agreements with power generation and mining operators.
Egypt
Egyptian Refining Company anchors Mediterranean supply architecture with hydrocracking configurations tuned for regional crude slates, serving Cairo-Alexandria industrial demand. The Egyptian General Petroleum Corporation coordinates crude-for-product swap arrangements through the African Petroleum Producers' Organization, reducing hard currency exposure. Mostafa Kamel refinery complex near Alexandria processes heavy sour crudes into low-sulfur diesel compliant with AFRI-4 specifications for re-export to North African markets.
South Africa
Sasolburg and Durban refineries process domestic coal-to-liquids and imported crude respectively, supplying Johannesburg-Pretoria mining belt diesel demand for captive power generation. The Department of Mineral Resources and Energy enforces Clean Fuels 2 specifications that exceed AFRI-4 sulfur limits, filtering marginal operators from the compliant facility pool. Engen's Durban refinery upgrade stretches across multiple development cycles, exposing sponsors to Brent-linked crude differential volatility.
Algeria
Sonatrach leverages captive Saharan crude feedstock access and pipeline-linked distribution across Maghreb markets, competing on delivered cost against European product arbitrage. The national oil company operates hydroskimming and conversion capacity at Arzew and Skikda complexes, with hydrotreater investment accelerating for gasoline sulfur reduction. Algiers corridor concentrates domestic offtake as the government phases out high-sulfur fuel oil subsidies in power generation.
Kenya
Mombasa import terminal and proposed Lamu refinery greenfield development present undeveloped East African demand centers without legacy infrastructure constraints. The Energy and Petroleum Regulatory Authority coordinates national standards alignment with AFRI-4 specifications ahead of regional refinery commissioning. Nairobi aviation hub expansion drives jet fuel offtake growth, justifying hydrocracker investment for kerosene yield optimization from regional crude slates.
Africa Oil Refining Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Africa's refining sector, creating a tiered structure where state-linked entities hold feedstock access advantages and private operators capture margin through conversion intensity. The market separates into three strategic archetypes: national oil companies with captive crude supply, independent refiners with single-train scale economies, and integrated petrochemical operators with FCC-steam cracker adjacencies. Dominant competitive moves include brownfield upgrade cycles for AFRI-4 compliance and long-term offtake contracting with industrial power generation and mining verticals.
Among Nigeria-based operators, Dangote Refinery exemplifies the independent scale archetype with single-train crude distillation capacity capturing margin pools previously lost to European imports. Egyptian Refining Company occupies the Mediterranean supply position with hydrocracking configurations tuned for regional crude slates. Sonatrach represents the state-linked feedstock-integrated model, leveraging captive Saharan crude access and pipeline distribution across North African markets.
| Leading Market Players |
|---|
| Dangote Refinery |
| Egyptian Refining Company (ERC) |
| Nigerian National Petroleum Corporation (NNPC) |
| Sonatrach |
| Midoil Refining & Petrochemicals Company Ltd |
| Engen Petroleum Ltd |
| Indorama Eleme Petrochemicals Ltd |
| NDEP PLC |
| Oryx Energies SA |
| Others |
Value Chain & Pricing Dynamics
Brent crude futures differentials cascade through African refining economics into three distinct pricing tiers: long-term offtake contracts for industrial power generators, medium-term supply agreements for mining operators, and spot market purchases for transport fleets lacking storage infrastructure.
Pricing Analysis
Short lead-time premiums dominate procurement economics as gold mining operations in Ghana's Ashanti belt pay fixed European benchmark differentials for 3-5 year supply security, while spot purchasers absorb volatility from Brent-linked crude differentials. Contract-based long-term offtake structures separate compliant AFRI-4 product from legacy high-sulfur fuel oil, with sulfur certification grade and volume scale as the primary price differentiation drivers. Pricing pressure stems from Northwest European refineries arbitraging excess gasoline yield into West African demand peaks. Transport fleet operators exhibit highest price sensitivity due to thin working capital buffers, whereas captive power installations prioritize fuel security over cost optimization.
Supply Chain Analysis
Nigeria's local-content mandates under petroleum industry regulations reshape equipment sourcing, compelling EPC contractors to source desulfurization catalysts and hydrotreater vessels from domestic fabrication yards in the Lekki corridor. Feedstock supply concentrates in Nigeria, Egypt, and Algeria as crude production basins, with hydroprocessing catalysts and specialized welding services as critical imported inputs. Single-source vulnerability runs through the limited expatriate contractor pool for hydrotreater commissioning. Distribution runs through pipeline-linked corridors reducing coastal tanker dependence, supplemented by coastal product jetties at Lagos, Port Harcourt, and Mombasa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AFRI-4 compliance timelines and hydroprocessing talent scarcity constrain effective capacity expansion, propping margin capture for facilities with certified product streams.
For Market Incumbents: Lock in long-term offtake contracts with mining and power generation verticals before brownfield upgrade cycles at Warri and Kaduna facilities restore competing supply. Secure captive catalyst supply agreements to hedge against hydrotreater commissioning delays that threaten committed delivery schedules. Backward integration into hydrogen plant operations reduces exposure to merchant hydrogen price volatility during two-stage desulfurization retrofits. For New Entrants and Emerging Players: Modular hydrocracker configurations tuned for regional crude slates offer a technology-first wedge into East African greenfield development in Uganda and Kenya, where no legacy refinery infrastructure creates open procurement channels. Target aviation fuel supply contracts at Nairobi and Addis Ababa hubs as the most penetrable segment, with dedicated jetty infrastructure as the critical go-to-market enabler for kerosene yield optimization. For Investors and Strategic Acquirers: Distressed-cycle entries favor brownfield rehabilitation projects in Nigeria's Port Harcourt corridor, where state-owned legacy assets face asset-level obsolescence under AFRI-4 specifications. Five-to-ten year viability hinges on securing sovereign guarantee structures for nine-figure hydroprocessing retrofits. Watch for crude-for-product swap arrangement volumes through the African Petroleum Producers' Organization as the inflection signal for hard currency availability and feedstock security.| Strategic Initiative | Industry Significance |
|---|---|
| AFRI-4 Compliance Retrofit | Two-stage hydrotreater sequences at Egyptian Refining Company anchor Mediterranean low-sulfur diesel supply. |
| Crude-for-Product Swap Structuring | African Petroleum Producers' Organization barter mechanisms reduce hard currency exposure for crude-rich members. |
| Aviation Hub Jetty Development | Dedicated kerosene infrastructure at Lagos and Nairobi airports captures jet fuel margin expansion from route frequency growth. |
| Modular Reactor Deployment | Single-train crude distillation with integrated hydrocracking compresses construction schedules for East African greenfields. |
| Long-term Industrial Offtake Contracting | Fixed-differential agreements with Ghanaian gold mining operations displace tender-based spot procurement patterns. |
Study Parameters
International Energy Agency supply reports, African Petroleum Producers' Organization trade flow databases, and national regulatory filings from Nigeria's Department of Petroleum Resources formed the secondary backbone, cross-referenced against primary interviews with refinery operations managers, EPC project developers, and fuel supply specialists at mining and power generation offtakers. Customs data on catalyst imports and hydroprocessing equipment shipments anchored bottom-up capacity estimates, while top-down triangulation against regional product demand models validated volume assumptions.
Historical trendline analysis of refinery utilization rates and product slate yields across the analysis window informed projection parameters, with segmentation modeling across technology configuration, product type, and installation mode. CAGRs derived from regression against crude price differentials, regulatory compliance cost curves, and aviation demand growth trajectories. Forecast inputs incorporated AFRI-4 implementation timelines and hydroprocessing talent availability constraints.
Several conditions sit outside the modeled scope, including abrupt crude production shortfalls in Nigerian feedstock basins and unilateral subsidy policy reversals in North African power generation markets. Forecasts reflect documented assumptions regarding regulatory harmonization pace and EPC contractor capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Gold Mining Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Well Test Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market