
 Gold Mining Market | 2026-2036
Gold Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Gold Mining Market Analysis
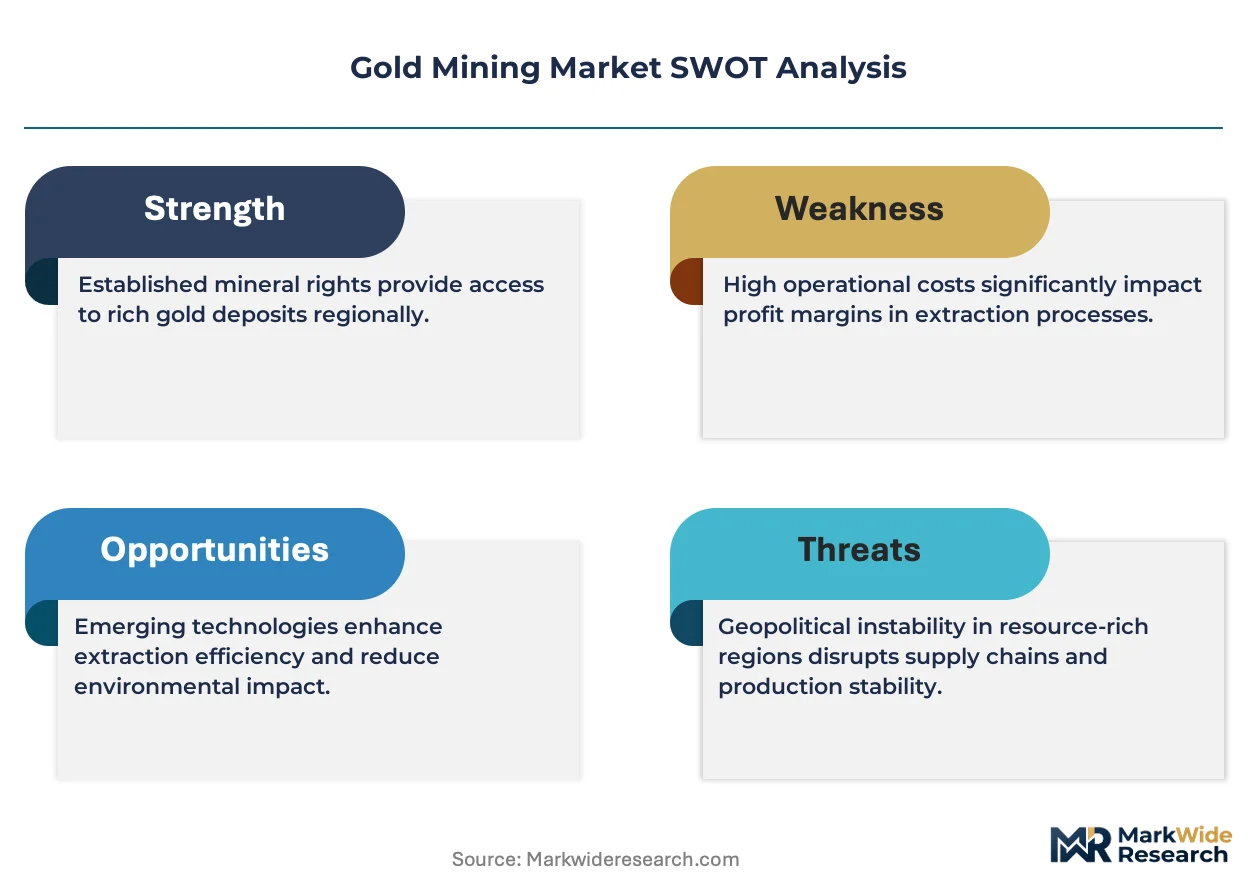
The EU Green Deal is decoupling European gold sourcing from carbon-intensive extraction practices, forcing refiners to verify supply chain emissions. Newmont leverages its Nevada operations to sustain low-carbon output for European buyers. Barrick Mining anchors its copper-gold portfolio in the Americas while competing on all-in sustaining costs. AngloGold Ashanti dominates African deep-level operations and navigates power reliability constraints across its South African shafts.
Gold mining encompasses the extraction and processing of ore bearing elemental gold, typically requiring grades above one gram per tonne for surface operations and sophisticated flotation or cyanidation circuits for recovery. The primary purpose remains the production of monetary reserves, fabricated jewelry, and high-reliability electronics components. Hard rock mining occupies the largest share of volume but carries elevated capital intensity and extended development timelines. Placer mining retains relevance in specific geographies with unconsolidated alluvial deposits. Heap leaching differentiates lower-grade oxide deposits where conventional milling proves uneconomical.
EPA mercury emissions rules in the United States, REACH chemical restrictions in Europe, and the Minamata Convention on Mercury shape permissible extraction chemistries and closure liabilities across jurisdictions. These frameworks elevate compliance costs for artisanal operators while advantaging mechanized producers with established tailings management protocols. Stakeholders must monitor which jurisdictions tighten cyanide use restrictions versus those permitting new heap leach permits, as this divergence will redirect capital flows and concentrate processing capacity in regulatory safe harbors.
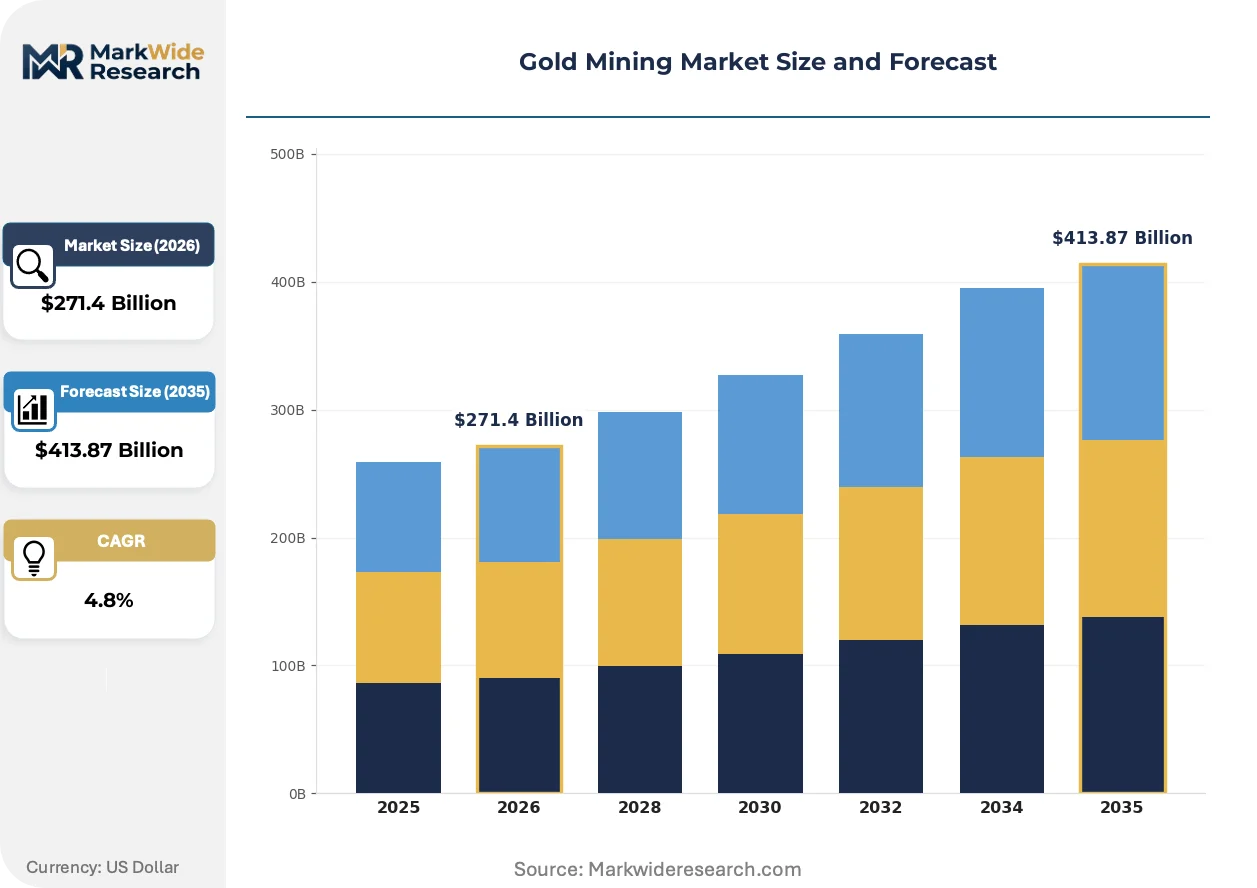
Market Dynamics
Carbon verification requirements under the EU Green Deal are forcing refiners to restructure sourcing relationships, while power reliability constraints in South African deep-level operations compress throughput margins for shaft-dependent producers.
Growth Catalysts
- Central bank reserve accumulation:Monetary authorities in emerging economies are expanding bullion holdings to diversify foreign exchange reserves and reduce dollar dependency.
- REACH chemical compliance frameworks:European refiners now prioritize low-carbon extraction partners, redirecting procurement toward operations with verified emissions profiles.
- Heap leach technology:Oxide deposit processing enables economic recovery from grades below conventional milling thresholds, unlocking previously stranded resources.
Market Restraints
- Energy cost volatility:Diesel and grid electricity price swings directly impact all-in sustaining costs for mechanized open-pit and underground operations.
- Artisanal supply concentration:Burkina Faso and Mali corridors face informal output disruptions from security incidents and export licensing irregularities.
- Cyanide use restrictions:Jurisdictions including Germany and several US states impose permitting moratoriums or enhanced containment requirements for leach circuits.
Strategic Opportunities
- Copper-gold porphyry development:Dual-commodity deposits in the Americas offer revenue diversification as electrification metal demand accelerates.
- Minamata Convention alignment:Mercury-free certification creates premium positioning for mechanized producers serving European electronics and jewelry fabricators.
- Tailings reprocessing:Historical dam inventories contain residual gold recoverable through modern flotation and intensive leach methods.
Industry Challenges
- Deep-level mining expertise scarcity:South African shaft operations struggle to replace retiring engineers and rock mechanics with qualified successors.
- Closure liability provisioning:EPA and state-level bonding requirements in the United States demand escalating financial assurances for post-mining reclamation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gold Mining Market |
| Market Size in 2026 | $271.4 Billion |
| Market Size in 2035 | $413.87 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Gold, Gold Bars, Gold Coins, Gold Nuggets Extraction Method: Hard Rock Mining, Placer Mining, By-Product Mining, Heap Leaching End User: Jewelry Manufacturers, Investment Firms, Electronics Industry, Central Banks Distribution Channel: Online Retail, Wholesale Dealers, Auction Platforms, Direct Sales |
| Companies Covered | Newmont, Agnico Eagle Mines, Barrick Mining, Zijin Mining Group, Polyus, AngloGold Ashanti, Gold Fields, Franco-Nevada, Kinross Gold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gold Mining Market Emerging Trajectories
Automation and alternative chemistries are compressing labor exposure and environmental footprint simultaneously, while procurement patterns favor verified low-carbon supply chains over traditional spot-market sourcing.
Autonomous haulage and drilling systems are expanding into open-pit operations across Nevada and Western Australia, where labor costs and safety incident exposure drive adoption. Tier-1 miners deploy these fleets to sustain 24-hour throughput during shift changes and weather events. The technology is expanding into mid-tier acquisitions as capital constraints ease and vendor financing structures mature.
The EU Green Deal's carbon border adjustment mechanism imposes embodied emissions reporting on imported refined gold, effective for large-volume shipments. European fabricators now require supply chain documentation from mine to bar. African and South American producers lacking measurement infrastructure face exclusion or price discounts versus verified low-carbon competitors.
Long-term offtake contracting is displacing spot market liquidity for institutional-grade bullion, as central banks and sovereign wealth funds seek supply certainty. Major refiners in Switzerland and the United Arab Emirates are restructuring inventory management around committed flows rather than merchant trading. This pattern concentrates sourcing relationships with tier-1 miners possessing multi-decade reserve bases and transparent governance frameworks.
Gold Mining Market Segmentation
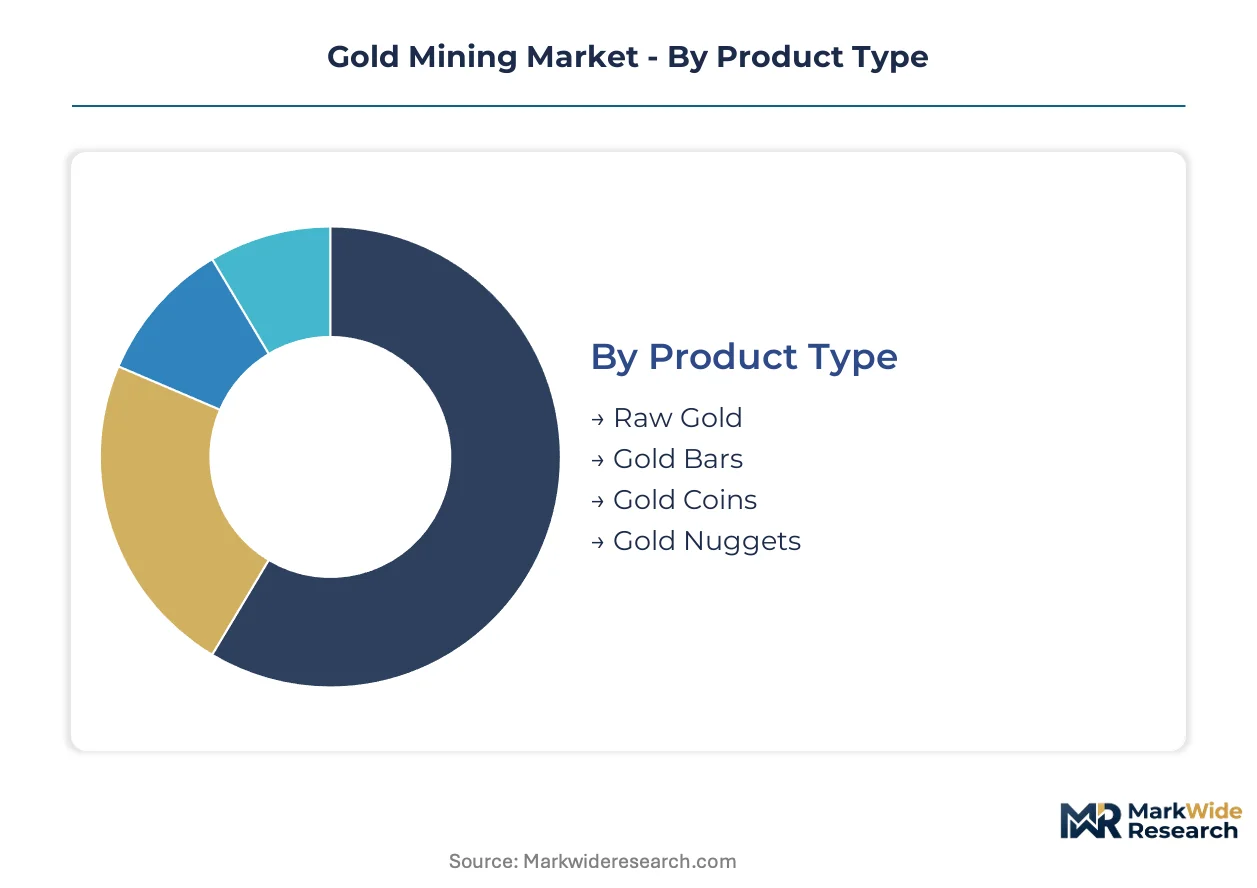
Segmentation in gold mining reveals how physical form, extraction technology, and buyer type concentrate margin capture across radically different operational and commercial profiles. Supply chain configuration varies dramatically between investment-grade bar flows and artisanal nugget circuits.
Product Type:
Supply concentration in fabricated forms is tilting procurement power toward integrated refiners with London Bullion Market Association accreditation.
- Raw Gold:Unrefined dore bars and precipitate from mine-site electrowinning circuits, typically assaying 60-85% gold content with silver and base metal impurities. Demand concentrates with Swiss and UAE refiners seeking feedstock for 99.99% London Good Delivery certification, constrained by EU Green Deal carbon verification requirements that disadvantage high-emission artisanal sources.
- Gold Bars:Cast or minted ingots meeting LBMA, COMEX, or Tokyo Commodity Exchange specifications, ranging from 1 kilogram wholesale units to 1 gram retail denominations. Investment firms in Singapore and Dubai are accumulating tonnage through allocated storage programs, driving demand for serialized chain-of-custody documentation.
- Gold Coins:Government-minted legal tender with numismatic and bullion hybrid value, including American Eagle, Canadian Maple Leaf, and Australian Kangaroo programs. Central European retail distributors favor these for private wealth preservation.
- Gold Nuggets:Alluvial fragments retaining natural crystalline structure, traded primarily through artisanal networks in West African corridors and Australian prospecting regions. Jewelry manufacturers in Istanbul and Mumbai source these for bespoke high-margin pieces.
Today's leader: Gold Bars. Tomorrow's challenger: Raw Gold with verified low-carbon provenance.
Extraction Method:
Cost tier stratification separates capital-intensive underground development from surface operations with shorter payback horizons.
- Hard Rock Mining:Underground or open-pit excavation of gold-bearing quartz veins and sulfide ores, requiring drilling, blasting, crushing, and milling circuits with flotation or cyanidation recovery. Nevada and Western Australian operations dominate institutional investment allocations due to power reliability and permitting predictability.
- Placer Mining:Mechanical or hydraulic recovery of unconsolidated alluvial deposits in riverbeds and terrace gravels, employing sluice boxes, trommels, or centrifugal concentrators. Siberian and Yukon seasonal operations supply nugget-specific demand from jewelry fabricators.
- By-Product Mining:Gold recovery as secondary credit from copper-gold porphyry or polymetallic base metal concentrates, common in Chilean and Indonesian copper operations. Electronics industry offtake agreements favor this source for supply security.
- Heap Leaching:Percolation cyanide or thiosulfate through crushed oxide ore piles for low-grade deposit economics, prevalent in Nevada Carlin-type deposits and Kazakh stand-alone operations. Heap leach technology is expanding most quickly where conventional milling thresholds exclude development.
Cost leadership sits with Heap Leaching. Margin resilience favors Hard Rock Mining with copper-gold by-product credits.
End User:
Application-driven purity and form requirements fragment procurement specifications across radically different custody and fabrication workflows.
- Jewelry Manufacturers:Fabricators in India, China, and Turkey consuming 22-karat and 18-karat alloy feedstock, with Istanbul's Grand Bazaar and Mumbai's Zaveri Bazaar anchoring physical trading liquidity. These buyers prioritize 995+ purity granules and recycled scrap integration.
- Investment Firms:Wealth managers, exchange-traded fund sponsors, and private banks seeking unallocated or allocated bullion custody, with Singapore Freeport and Zurich vaulting infrastructure dominating institutional preference.
- Electronics Industry:Connector, bonding wire, and semiconductor packaging producers requiring 99.99%+ purity with controlled impurity profiles for thermal and electrical conductivity.
- Central Banks:Monetary authorities in Poland, Hungary, and Turkey expanding reserve holdings through sovereign purchases from primary dealers, with repatriation-to-domestic-vault preferences complicating custody logistics.
Volume concentration: Jewelry Manufacturers. Steepest expansion trajectory: Central Banks in emerging economies.
Distribution Channel:
Customer type and transaction size dictate channel selection, with institutional flows bypassing retail infrastructure entirely.
- Online Retail:E-commerce platforms offering fractional gram purchases, home delivery, and digital wallet integration, with German and Swiss fintech entrants capturing millennial allocation preferences.
- Wholesale Dealers:LBMA-member banks and specialized merchants providing spot and forward contracting, loco London and loco Zurich price discovery, and financing against pledged metal.
- Auction Platforms:Sotheby's, Christie's, and specialized numismatic houses transacting rare coins and specimen nuggets, with Hong Kong and Geneva sales calendar concentration.
- Direct Sales:Mine-site offtake contracts and streaming agreements where producers sell future production to royalty companies, bypassing merchant intermediaries.
Institutional gravity centers on Wholesale Dealers. Retail innovation is concentrating fastest in Online Retail with blockchain-verified provenance features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Witwatersrand Basin established modern deep-level mining in the late nineteenth century, setting technical standards that persist across African, Australian, and North American operations today.
Australia
Superannuation fund allocations and Asian jewelry demand drive Western Australian output expansion. The country's national environmental regulator enforces strict tailings storage facility standards under state-level mining acts. Kalgoorlie's Golden Mile and the Pilbara iron ore-gold corridor host autonomous haulage deployments that compress all-in sustaining costs.
China
State reserve accumulation and electronics fabrication demand concentrate purchasing power with state-owned refiners. The Ministry of Ecology and Environment enforces dual carbon goals that restrict diesel-powered open-pit expansion. Shandong Province's Jiaodong Peninsula anchors mechanized underground development where Zijin Mining Group operates integrated milling circuits.
United States
Investment fund inflows and central bank custody demand sustain Nevada's Carlin-type production. EPA mercury emissions rules and state-level bonding requirements elevate closure liability provisioning for new projects. The Battle Mountain-Eureka trend hosts heap leach operations that supply London Good Delivery refiners with verified low-carbon documentation.
South Africa
Deep-level ore reserves and residual reef extensions sustain shaft-dependent output despite throughput constraints. The Department of Mineral Resources and Energy regulates mine closure certificates and financial provisioning for environmental rehabilitation. The Witwatersrand Basin's West Rand and Free State goldfields struggle with power reliability from Eskom's grid instability.
Russia
Domestic bullion monetization and Asian offtake agreements sustain Siberian placer and hard rock operations. Federal subsoil use licensing frameworks govern extraction rights in remote Arctic and Far East jurisdictions. The Krasnoyarsk Krai and Magadan Oblast concentrate alluvial seasonal mining that supplies Moscow refiners with doré feedstock.
Gold Mining Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reserve quality and jurisdictional risk profiles. Tier-1 diversified miners with multi-decade reserve bases command forward offtake premiums from European refiners. Three archetypes dominate: integrated majors with copper-gold portfolios, pure-play gold specialists with deep African expertise, and royalty-streaming firms with capital-light exposure. Competitive moves concentrate on portfolio rationalization through non-core asset divestitures and carbon verification partnerships with LBMA-accredited refiners.
Within the integrated major tier, Newmont and Barrick Mining represent capital-disciplined operators with Americas-focused reserve bases. AngloGold Ashanti exemplifies the Africa-centric specialist archetype navigating power and depth constraints. Franco-Nevada occupies the royalty-streaming position with exposure to production economics without operational execution risk.
| Leading Market Players |
|---|
| Newmont |
| Agnico Eagle Mines |
| Barrick Mining |
| Zijin Mining Group |
| Polyus |
| AngloGold Ashanti |
| Gold Fields |
| Franco-Nevada |
| Kinross Gold |
| Others |
Supply Flow & Price Mechanics
Deep-level mining engineers concentrated in South Africa's Witwatersrand Basin command wage premiums that compress margins at the economy tier while sustaining spreads between mechanized and artisanal output. Labor-cost differentials between Nevada's autonomous operations and West African shaft-dependent sites translate directly into pricing-tier stratification across London Good Delivery, dore bar, and nugget markets.
Pricing Analysis
Long-term offtake contracting anchored to verified low-carbon provenance separates institutional-grade bar flows from spot-market dore transactions. Price differentiation rests on LBMA accreditation status and EU Green Deal carbon documentation completeness, with European fabricators paying premiums for measured emissions profiles. Cost compression in artisanal corridors intensifies because security disruptions and licensing irregularities in Burkina Faso and Mali force distressed selling. Central banks exhibit lowest price sensitivity, while jewelry manufacturers in Istanbul and Mumbai negotiate aggressively on granule purity and alloy feedstock terms.
Supply Chain Analysis
Dual-sourcing mandates from Swiss and UAE refiners require mine-site electrowinning circuits and third-party toll milling qualifications simultaneously. Supply concentrates in Nevada's Carlin-type deposits, Western Australia's Golden Mile, and South Africa's Witwatersrand Basin, with each node feeding distinct purity and documentation requirements. Raw material dependencies include cyanide reagents, diesel fuel for haulage fleets, and grid electricity for shaft hoisting. Single-source vulnerability runs through Eskom's power reliability for South African deep-level operations. Distribution runs through LBMA-member wholesale dealers providing loco London and loco Zurich price discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gold mining functions as a stable compounder, with central bank reserve accumulation providing non-cyclical demand underpinning through monetary policy shifts.
For Market Incumbents: Anchor portfolio rationalization around copper-gold porphyry assets in the Americas that diversify revenue streams as electrification metal demand accelerates. Defensive consolidation should prioritize Nevada and Western Australian operations with autonomous haulage deployments that compress all-in sustaining costs. Threat substitution from mercury-free certification requirements under the Minamata Convention pressures operators lacking measurement infrastructure. Certification investment in carbon verification partnerships with LBMA-accredited refiners represents the critical lever for European market access. For New Entrants and Emerging Players: Blockchain-verified provenance platforms offer a direct-channel route to bypass established wholesale dealer networks and capture millennial allocation preferences in German and Swiss fintech markets. White-space targets include tailings reprocessing projects in historical dam inventories containing residual gold recoverable through modern flotation methods. The most penetrable segment sits in online retail fractional gram purchases with home delivery integration. Go-to-market execution should emphasize serialized chain-of-custody documentation that satisfies Singapore Freeport vaulting infrastructure requirements. For Investors and Strategic Acquirers: Royalty-streaming firms are the most active acquirer in this space, deploying capital-light structures that capture production economics without operational execution risk. Long-term viability over a five-to-ten year window favors tier-1 miners with multi-decade reserve bases and transparent governance frameworks that qualify for sovereign wealth fund mandates. Acquisition target archetype: mechanized producers with verified low-carbon output serving European electronics and jewelry fabricators. The signal to watch is tightening cyanide use restrictions in German and several US state jurisdictions that would redirect capital flows toward regulatory safe harbors.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Verification Partnership | EU Green Deal documentation requirements from LBMA-accredited refiners secure European offtake premiums. |
| Autonomous Haulage Deployment | Nevada and Western Australian fleets sustain throughput during shift changes and weather events. |
| Copper-Gold Porphyry Development | Dual-commodity deposits in the Americas offer revenue diversification as electrification metal demand accelerates. |
| Tailings Reprocessing Investment | Historical dam inventories yield residual gold through modern flotation and intensive leach methods. |
| Mercury-Free Certification | Minamata Convention alignment creates premium positioning for mechanized producers serving European fabricators. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with mine operations executives, refinery procurement managers, central bank reserve officers, and LBMA accreditation specialists combined with secondary validation from SEC 10-K filings, customs and trade data, EPA emissions disclosures, and sovereign wealth fund allocation reports. Triangulation between extraction method cost curves and fabricated product demand flows ensures consistency across volume and value outputs.
Input-output matrices map ore grade, recovery method, and refining pathway to end-use purity requirements across the projection horizon. Segmentation dimensions modeled include product type, extraction technology, end-user application, and regional regulatory cluster. CAGRs were derived from supply-demand balance iterations rather than extrapolation. Industry-specific forecast inputs include power reliability indices for South African shaft operations and carbon intensity measurements for EU Green Deal compliance pathways.
The model assumes a particular technology adoption path; alternative pathways for thiosulfate leaching chemistry or solid-state gold recovery would alter the outlook for oxide deposit economics. Forecasts reflect documented assumptions regarding central bank accumulation rates, artisanal supply stability in West African corridors, and cyanide permitting trajectories in restrictive jurisdictions. Deviation in Eskom grid reliability or REACH chemical restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Coal Mining Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Thailand Oil and Gas Market