
 AI in Oil and Gas Market | 2026-2036
AI in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Oil and Gas Market Intelligence
The capital-intensity divergence between cloud-native AI specialists and legacy industrial software incumbents is redrawing competitive boundaries in oilfield intelligence. C3.ai Inc. leverages its pre-built enterprise AI applications to anchor relationships with supermajors seeking rapid deployment. IBM sustains competitive relevance through its hybrid cloud architecture and deep energy sector consulting heritage. Microsoft dominates the infrastructure layer, extending Azure's edge computing capabilities to remote drilling sites where latency constraints rule out centralized processing.
Artificial intelligence in oil and gas encompasses machine learning algorithms, computer vision systems, and natural language processing tools deployed to analyze seismic data, optimize well placement, predict equipment failures, and automate subsurface interpretation. These technologies process terabyte-scale sensor streams from downhole tools, surface facilities, and satellite imagery to reduce operational downtime and improve hydrocarbon recovery rates. Predictive analytics leads product-type revenue generation because operators prioritize failure prevention over exploratory data management investments. Reservoir management commands the largest application share as mature fields require AI-driven decline curve analysis to sustain output. Machine learning underpins most deployed solutions, though computer vision is gaining traction in automated flare monitoring and offshore platform inspection workflows.
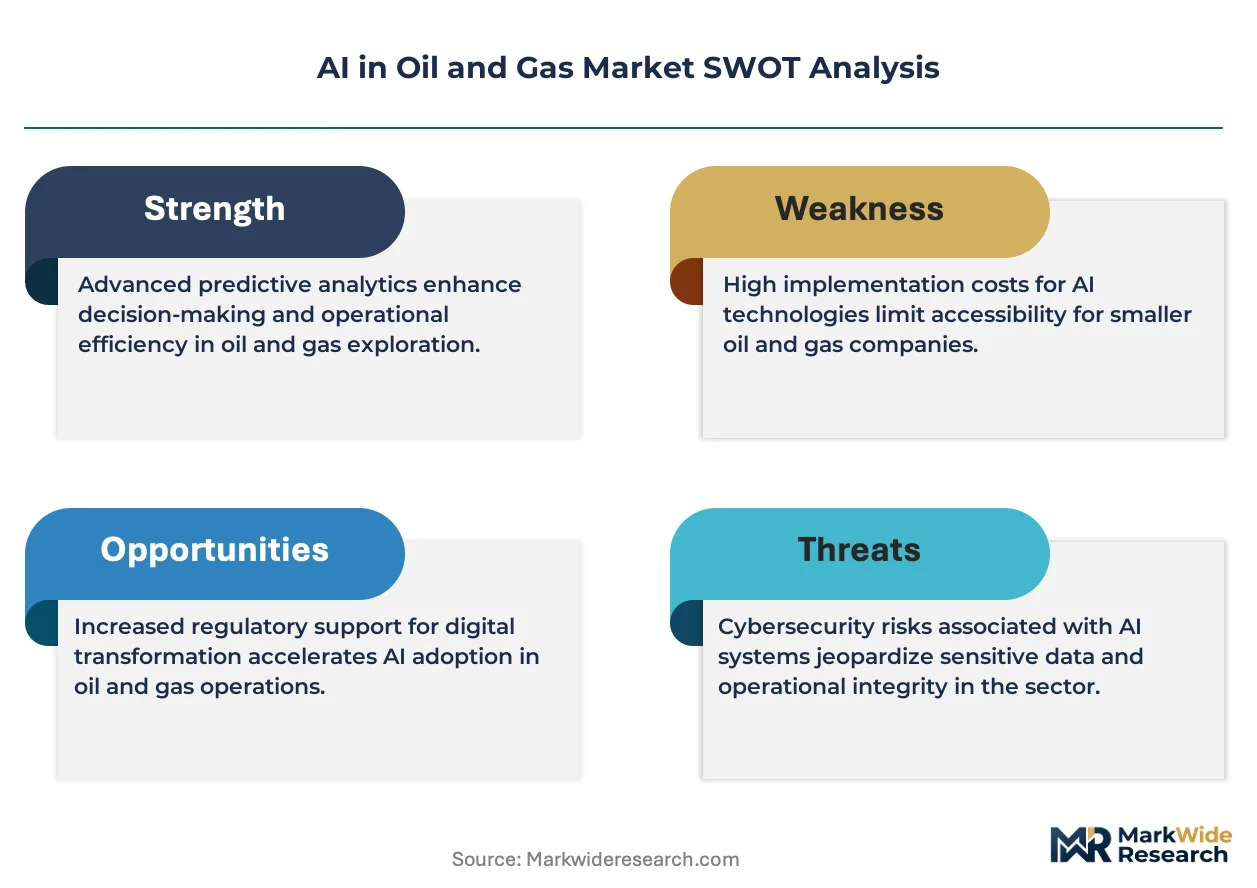
The US EPA enforces methane performance standards under the Clean Air Act that compel operators to install continuous emissions monitoring backed by AI anomaly detection. The Pipeline and Hazardous Materials Safety Administration mandates integrity management protocols where predictive models prioritize inspection schedules and replacement timelines. OSHA process safety regulations intersect with AI deployments as refiners deploy natural language processing to extract operational insights from incident reports and near-miss databases. Stakeholders must decide whether to build proprietary AI capabilities in-house or accept vendor lock-in from cloud platforms that control the data infrastructure layer.
Market Dynamics
The US EPA's methane performance standards under the Clean Air Act are compressing deployment timelines for AI-driven emissions monitoring, forcing upstream operators to choose between rapid vendor adoption or accelerated in-house capability builds.
Growth Catalysts
- Regulatory Enforcement:The US EPA mandates continuous emissions monitoring under Clean Air Act methane rules, compelling Permian Basin operators to deploy predictive analytics for leak detection and flaring reduction.
- Shale Decline Curves:Mature fields in Texas and North Dakota require AI-driven reservoir management to sustain output economics as natural production rates deteriorate.
- Edge Computing:Latency constraints at remote drilling sites are driving adoption of localized processing architectures that enable real-time downhole decision-making.
Market Restraints
- Data Infrastructure Concentration:Cloud platform dominance creates vendor lock-in risks as hyperscalers control the underlying compute layer for AI deployments.
- Specialized Talent Scarcity:The intersection of petroleum engineering and machine learning expertise remains concentrated in Houston and Austin, limiting deployment velocity.
- Legacy System Integration:Decades-old SCADA architectures in established fields impose technical debt that complicates AI overlay implementation.
Strategic Opportunities
- Underpenetrated Basins:Bakken operators lag Permian peers in AI adoption, creating whitespace for reservoir optimization vendors to establish beachheads.
- Computer Vision Expansion:Automated offshore platform inspection workflows remain nascent relative to onshore applications, offering expansion vectors for visual analytics providers.
- Regulatory Tailwinds:The Pipeline and Hazardous Materials Safety Administration's integrity management protocols create mandated demand for predictive inspection scheduling tools.
Industry Challenges
- Subsurface Data Integration:Seismic interpretation, well logs, and production histories reside in incompatible formats that require expensive normalization before AI model training.
- Cybersecurity Certification:NERC CIP compliance timelines for critical energy infrastructure extend procurement cycles for AI-enabled operational technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Oil and Gas Market |
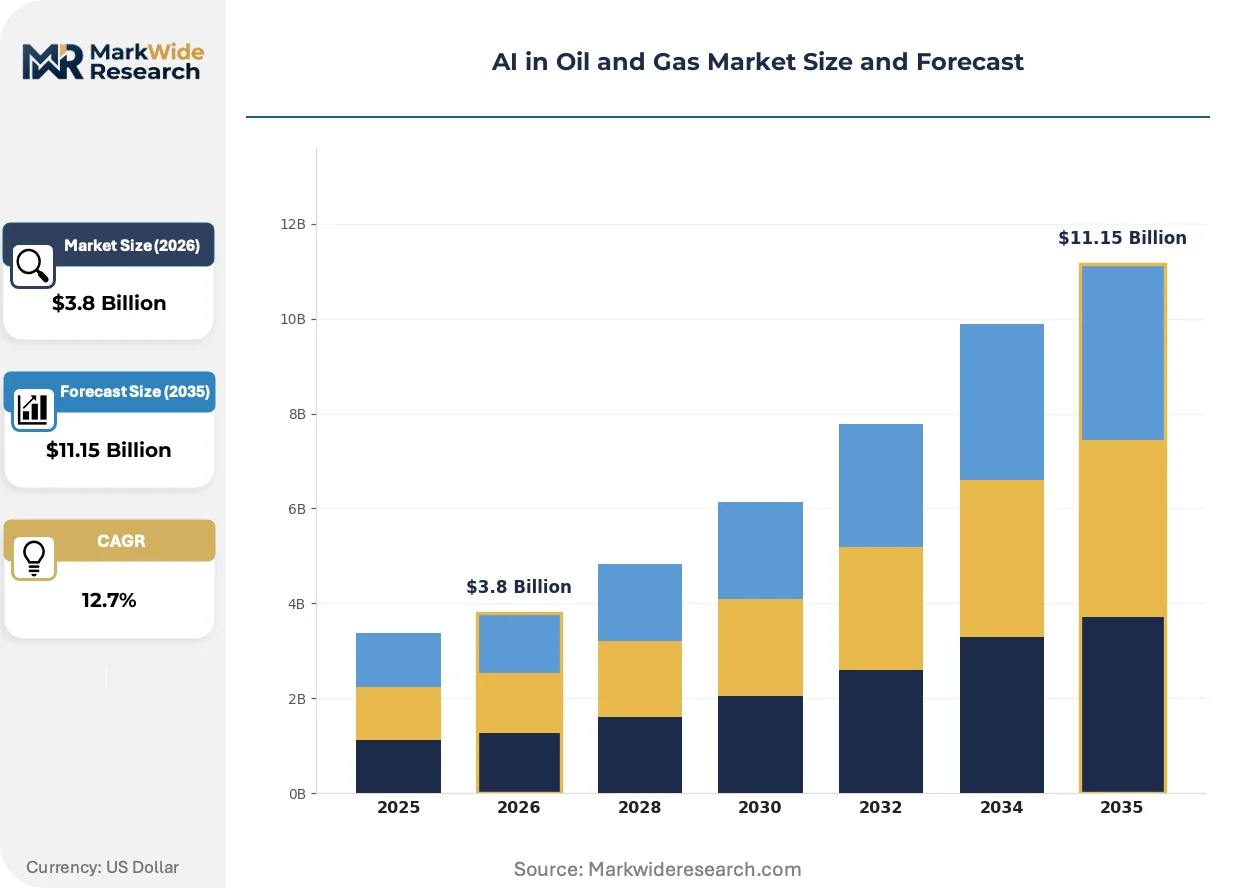
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Automation Tools, Data Management Platforms, Exploration Software Application: Reservoir Management, Asset Optimization, Drilling Automation, Production Enhancement End User: Oil Operators, Service Companies, Equipment Manufacturers, Consulting Firms Technology: Machine Learning, Natural Language Processing, Computer Vision, Cloud Computing |
| Companies Covered | C3.ai Inc., SparkCognition Inc., Uptake Technologies Inc., Tachyus Corporation, Akselos SA, AIQ, IBM, Microsoft, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Oil and Gas Market Strategic Shifts & Innovations
Edge-native processing architectures are displacing centralized cloud workflows in upstream operations, while regulatory pressure on methane intensifies the pace of automated monitoring deployment across unconventional basins.
Downhole sensor arrays are miniaturizing from bulky wired assemblies to compact wireless nodes capable of transmitting pressure, temperature, and flow data at reduced power budgets. Shale producers in the Permian are retrofitting existing wells with these devices faster than greenfield deployment cycles. This sensor density is miniaturizing the unit economics of real-time reservoir characterization, compressing the feedback loop between data acquisition and completion design adjustments.
The US EPA's supplemental methane proposal under the Clean Air Act tightens leak detection and repair requirements for existing sources, not merely new facilities. Operators must install continuous monitoring systems rather than periodic optical gas imaging surveys. Midstream gathering and boosting stations face the steepest compliance cost escalation, driving demand for AI anomaly detection that reduces false-positive dispatch rates.
Supermajors are unbundling after-sales service contracts from equipment procurement, creating standalone AI analytics subscriptions priced on production uplift rather than software seats. Independent producers in North Dakota prefer this model because it aligns vendor compensation with measurable barrel recovery improvements. This contractual innovation is most visible among Permian-focused private equity-backed operators seeking to minimize upfront capital commitments during drilling program pauses.
AI in Oil and Gas Market Segmentation
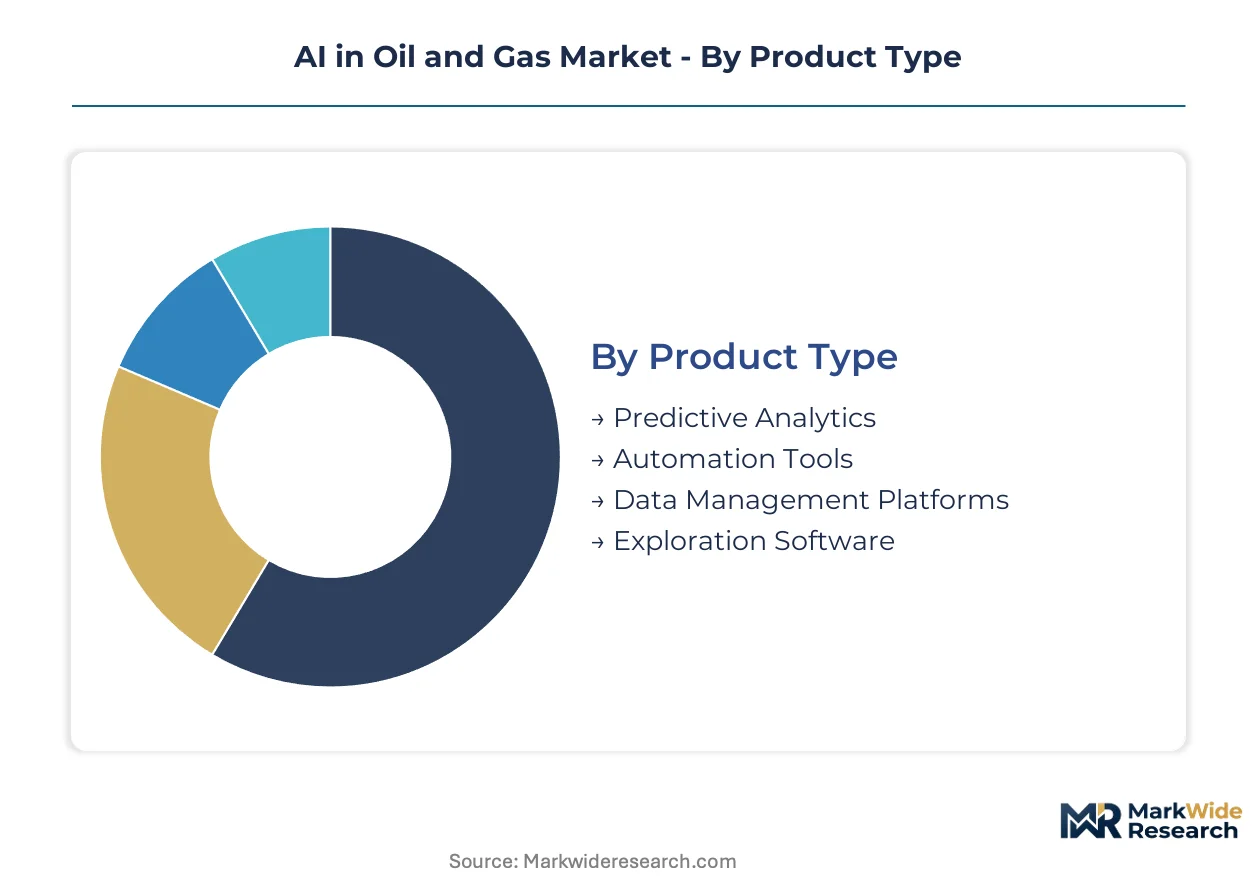
Segmentation in oilfield AI reveals how value migrates between infrastructure layers and operational workflows. Vendors must align capabilities with the specific physics of extraction economics and the regulatory compliance burdens facing operators.
Product Type:
Predictive analytics commands the deepest margin pools in this category due to its direct linkage to failure prevention economics and methane compliance mandates.
- Predictive Analytics:Algorithms process sensor telemetry to forecast equipment failures, well performance degradation, and emissions anomalies before they trigger regulatory penalties or production losses. Permian Basin operators prioritize these tools to compress mean-time-to-repair and satisfy EPA continuous monitoring requirements.
- Automation Tools:Control systems execute autonomous adjustments to drilling parameters, artificial lift settings, and surface facility operations without human intervention. North Dakota shale producers deploy these for remote wellpad management where labor scarcity drives operational urgency.
- Data Management Platforms:Unified architectures normalize seismic, log, and production data into AI-trainable formats. These systems reduce preprocessing overhead for operators burdened by decades of incompatible legacy datasets.
- Exploration Software:Subsurface interpretation tools accelerate prospect evaluation and reserve estimation workflows. Supermajors retain these capabilities in-house while independents increasingly subscribe to cloud-hosted alternatives.
Predictive analytics holds installed capacity. Automation tools are rotating up the share rankings.
Application:
Volume concentrates in applications that extend the economic life of existing assets rather than greenfield development.
- Reservoir Management:Decline curve analysis, infill drilling optimization, and enhanced recovery design sustain output from mature fields. Texas operators apply machine learning to Permian well spacing and completion design to maximize per-section recovery.
- Asset Optimization:Cross-facility performance tuning matches production rates to gathering system capacity and processing constraints. Midstream operators in the Bakken deploy these tools to minimize flaring events that trigger regulatory scrutiny.
- Drilling Automation:Real-time downhole steering and rate-of-penetration optimization reduce non-productive time. Remote drilling sites with latency constraints drive edge-native deployment architectures for this application.
- Production Enhancement:Artificial lift optimization and well intervention targeting improve flow rates from existing completions. Private equity-backed operators favor these tools during drilling program pauses to protect cash flow.
Reservoir management anchors current deployment. Production enhancement is gaining share fastest as capital discipline extends field development timelines.
End User:
Procurement authority varies sharply by organizational scale and technical sophistication.
- Oil Operators:Upstream companies with leasehold positions purchase AI tools to optimize extraction economics and satisfy environmental compliance. Supermajors maintain internal data science teams while independents rely on vendor-managed solutions.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes embed AI into drilling, completion, and intervention service offerings. These firms capture value through performance-based contracts tied to measurable operational improvements.
- Equipment Manufacturers:OEMs integrate predictive maintenance and autonomous control into pumps, compressors, and rotating equipment. Equipment-as-a-service business models are displacing traditional capital sales in this segment.
- Consulting Firms:Engineering advisors deploy AI to accelerate reservoir characterization and facilities design. These engagements concentrate among operators lacking internal technical depth for complex unconventional development.
Oil operators retain the largest installed base. Service companies are climbing the fastest as integrated service-AI bundles displace point solutions.
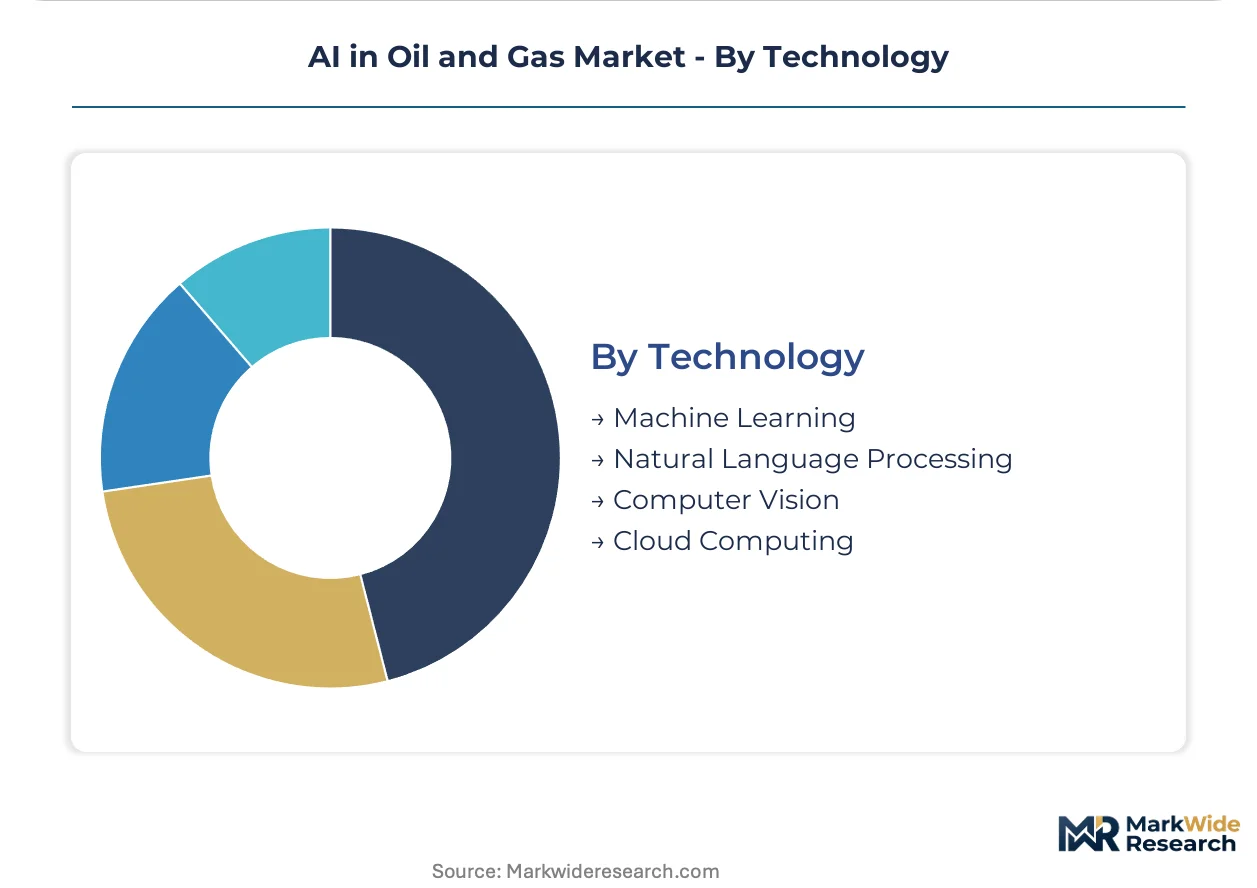
Technology:
Technology selection follows the latency and data gravity requirements of specific oilfield workflows.
- Machine Learning:Supervised and unsupervised algorithms dominate deployed solutions, processing structured production data for forecasting and classification tasks. Neural network architectures underpin most reservoir characterization and equipment health monitoring applications.
- Computer Vision:Automated image analysis detects methane leaks, inspects offshore platforms, and monitors flare combustion efficiency. EPA methane rules are accelerating adoption beyond early offshore pilot programs.
- Natural Language Processing:Text extraction from incident reports, regulatory filings, and technical documents supports operational knowledge management. Refiners deploy these tools for OSHA process safety compliance and near-miss analysis.
- Cloud Computing:Hyperscaler infrastructure enables model training at scale, though edge-native processing is displacing centralized workflows for latency-sensitive drilling applications. Microsoft Azure and AWS dominate the infrastructure layer.
Machine learning holds installed capacity. Computer vision is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in AI oilfield solutions concentrates in US shale basins where regulatory compliance costs and production optimization urgency create premium vendor economics. European operators face stricter emissions frameworks but slower deployment timelines due to fragmented asset ownership. Middle Eastern national oil companies leverage sovereign capital to build proprietary capabilities rather than subscribe to vendor platforms.
United States
Permian Basin operators deploy predictive analytics for methane leak detection under EPA Clean Air Act mandates. The Pipeline and Hazardous Materials Safety Administration requires integrity management protocols that prioritize AI-driven inspection scheduling. Houston anchors the largest concentration of petroleum engineering and machine learning talent, with Austin emerging as a secondary hub for cloud-native AI specialists serving upstream clients.
Saudi Arabia
Aramco's digital transformation program drives demand for reservoir simulation and autonomous drilling systems at scale. The kingdom's Vision 2030 diversification agenda channels sovereign investment into domestic AI capability building rather than vendor dependency. Dhahran's King Abdulaziz Center for World Energy concentrates R&D partnerships between national oil companies and international technology providers.
Norway
North Sea operators apply machine learning to offshore platform maintenance and subsea equipment monitoring in harsh environments. The Norwegian Petroleum Directorate mandates digital readiness standards that accelerate AI adoption for production optimization. Stavanger's energy technology cluster hosts specialized vendors focused on offshore automation and predictive maintenance workflows.
Canada
Alberta oil sands producers deploy computer vision for tailings pond monitoring and emissions detection amid intensifying environmental scrutiny. The Alberta Energy Regulator enforces methane reduction targets that mirror US EPA stringency. Calgary's corporate headquarters concentration drives procurement authority for AI-enabled asset optimization across oil sands and conventional basins.
Brazil
Pre-salt deepwater developments require AI-driven reservoir characterization to manage complex carbonate geology and high-pressure conditions. Petrobras maintains in-house digital capabilities while selectively partnering for edge computing infrastructure. Rio de Janeiro's research centers concentrate subsurface expertise, with São Paulo hosting the primary vendor relationships for cloud and analytics platforms.
AI in Oil and Gas Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Cloud hyperscalers dominate infrastructure layer economics through edge computing deployments at remote drilling sites. Specialized AI vendors capture value through pre-built applications for reservoir management and predictive maintenance. Incumbent industrial software providers defend position through deep energy sector consulting relationships and hybrid cloud architectures.
Within the enterprise AI application tier, C3.ai Inc. and IBM exemplify contrasting approaches to supermajor relationships. Microsoft anchors the infrastructure layer through Azure's energy sector deployments. SparkCognition Inc. occupies a position among industrial AI specialists focused on operational technology integration. These archetypes reflect the market's segmentation between platform infrastructure, vertical applications, and hybrid service bundles.
| Leading Market Players |
|---|
| C3.ai Inc. |
| SparkCognition Inc. |
| Uptake Technologies Inc. |
| Tachyus Corporation |
| Akselos SA |
| AIQ |
| IBM |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Performance-based contracts that tie vendor compensation to measurable barrel recovery improvements lock in supply access for shale operators while anchoring price visibility against volatile commodity cycles. This contractual structure concentrates procurement authority among private equity-backed Permian producers seeking to minimize upfront capital commitments during drilling program pauses.
Pricing Analysis
The customization-premium spread separates configured-to-order AI reservoir management deployments from standardized predictive analytics subscriptions. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and after-sales service bundling, with supermajors absorbing premium tiers for proprietary capability builds while independents cluster in standard SaaS tiers. Pricing pressure stems from hyperscaler infrastructure commoditization compressing margins at the platform layer. Independent shale producers in North Dakota exhibit highest price sensitivity, driving demand for outcome-based contractual structures.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native AI specialists serving upstream clients, while strategic stockpiling characterizes national oil companies building sovereign capability reserves. Supply concentrates in the United States, Saudi Arabia, and Norway as primary centers for petroleum engineering-machine learning talent and edge computing infrastructure. The supply chain draws from specialized GPU clusters, downhole sensor arrays, and seismic data processing hardware. Single-source vulnerability around hyperscaler cloud platforms creates concentration risk. Distribution runs through direct enterprise sales teams anchored in Houston, Dhahran, and Stavanger energy technology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among supermajors and large independents capable of unbundling service contracts, fragmenting the vendor landscape into specialized niche players and integrated platform providers.
For Market Incumbents: Compound defensive positioning through hybrid cloud architecture investments that preserve energy sector consulting relationships against cloud-native disintermediation. Deepen backward integration into edge computing hardware to reduce hyperscaler dependency. Prioritize EPA methane compliance certification as a channel control lever to lock in regulatory-driven replacement cycles. For New Entrants and Emerging Players: Anchor in Bakken basin whitespace where AI adoption lags Permian penetration by multiple deployment cycles. Target automated offshore platform inspection workflows as the most penetrable computer vision application. Pursue equipment-as-a-service business models that align compensation with production uplift metrics favored by capital-constrained independents. For Investors and Strategic Acquirers: Cloud-native AI specialists with pre-built reservoir management applications represent the highest-conviction acquisition archetype for capability consolidation. Long-term viability hinges on regulatory enforcement durability across methane monitoring mandates. Watch EPA supplemental methane proposal implementation timelines as the primary inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | Microsoft Azure's remote drilling site installations overcome latency constraints that centralized processing cannot satisfy. |
| Performance-Based Contract Unbundling | Supermajors separating AI analytics subscriptions from equipment procurement reshapes vendor compensation structures. |
| Methane Monitoring Certification Investment | EPA Clean Air Act compliance creates mandated replacement cycles for continuous emissions monitoring systems. |
| Reservoir Management Application Pre-Building | C3.ai's enterprise AI applications compress deployment timelines for operators seeking rapid capability acquisition. |
| Petroleum Engineering-Machine Learning Talent Acquisition | Houston and Austin talent scarcity limits deployment velocity, creating competitive advantage for concentrated hiring. |
Research Approach
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings for this oilfield intelligence assessment. Primary fieldwork encompassed reservoir engineers at Permian and Bakken operators, EPA compliance officers, procurement leads at supermajors, cloud platform energy sector specialists, and petroleum engineering faculty at research universities. Secondary validation drew from EPA enforcement actions, PHMSA integrity management protocols, FERC filings on critical infrastructure, EIA production databases, and hyperscaler energy vertical disclosures. Bottom-up segment sizing triangulates against top-down market construct validation.
Sensitivity analysis around regulatory enforcement timelines and commodity price scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow, end-user organizational scale, and technology deployment architecture, with regional regulatory cluster as an additional oilfield-specific dimension. CAGRs derive from installation base growth rates and per-seat value evolution. Forecast inputs incorporate shale decline curve deterioration rates and methane detection equipment replacement cycles.
Decision-makers should treat outputs as directional under sustained EPA enforcement and moderate commodity price assumptions; material deviation would warrant model refresh. Revision becomes warranted when methane regulatory stringency or edge computing cost curves cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Malaysia Oilfield Services Market