
 Grouting Machine Market | 2026-2036
Grouting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Grouting Machine Market Outlook
The performance gap between premium and commodity grouting equipment is broadening as automated mixing and precision injection systems command wider price bands against basic mortar pumps. Putzmeister leverages its German engineering heritage to dominate high-pressure hydraulic platforms for tunnel boring applications. EZG Manufacturing competes aggressively in the portable mortar segment through Midwest US distribution density. XCMG anchors its position in Asia via integrated chassis-pump combinations for infrastructure scale.
Grouting machines are engineered pumping systems designed to inject cementitious, chemical, or epoxy slurries under controlled pressure into voids, fractures, or soil matrices to achieve structural consolidation or water sealing; operating pressures typically span 10 to 700 bar depending on material viscosity and injection depth. Cement grout retains the largest volume share across foundation and dam rehabilitation work, though chemical grout accelerates fastest in mining void filling where rapid set times reduce operational downtime. Electric technology gains share in European urban construction zones where noise ordinances and indoor emission limits restrict combustion-powered alternatives.
OSHA silica standards and EPA Tier 4 final emission regulations constrain diesel-hydraulic deployment in US construction, redirecting procurement toward pneumatic and electric architectures that reduce respirable dust and exhaust exposure. China's MIIT equipment certification and GB standards for construction machinery enforce safety interlocks and pressure relief protocols that elevate manufacturing compliance costs for domestic and imported units. Stakeholders must weigh total cost of ownership against regulatory compliance trajectories when selecting technology platforms for multi-year project pipelines.
Market Dynamics
Automated mixing and precision injection systems are compressing the competitive landscape between premium and commodity equipment tiers, forcing manufacturers to differentiate through pressure control accuracy and real-time monitoring capabilities rather than raw pumping capacity alone.
Growth Catalysts
- China's MIIT equipment certification:Safety interlocks and pressure relief protocols under GB standards elevate manufacturing compliance costs, filtering out low-cost competitors and strengthening positions of certified domestic and imported suppliers.
- Tunnel boring applications:High-pressure hydraulic platforms for mechanized tunneling create sustained equipment procurement cycles across Asia-Pacific infrastructure corridors.
- Epoxy slurry injection:Rapid set times in mining void filling reduce operational downtime, accelerating adoption of chemical grout systems over traditional cementitious alternatives.
Market Restraints
- Steel and hydraulic component costs:Volatility in high-pressure pump castings and precision valve assemblies squeezes margin structures for mid-tier manufacturers without captive supply arrangements.
- EPA Tier 4 final emission regulations:Diesel-hydraulic deployment faces escalating compliance burdens in US construction zones, constraining equipment utilization windows and resale liquidity.
- Electric motor power density limits:Battery weight and energy storage constraints restrict electric platform mobility for remote mining and dam rehabilitation sites lacking grid access.
Strategic Opportunities
- India's PLI scheme for construction machinery:Domestic manufacturing incentives create localized production pathways for integrated chassis-pump combinations serving South Asian infrastructure buildouts.
- Urban noise ordinances:European municipal emission limits accelerate electric platform penetration in metro expansion and building foundation work where combustion alternatives face operational restrictions.
- Telematics-integrated preventive maintenance:IoT-enabled pressure monitoring and predictive component replacement reshape aftermarket service models toward subscription-based uptime guarantees.
Industry Challenges
- Certified grout technician scarcity:Specialized training for high-pressure injection safety and mix proportioning creates bottlenecks in project ramp-up phases across emerging infrastructure markets.
- Legacy fleet integration complexity:Retrofitting automated control systems onto existing pneumatic and hydraulic units demands custom engineering that extends deployment timelines and elevates total project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grouting Machine Market |
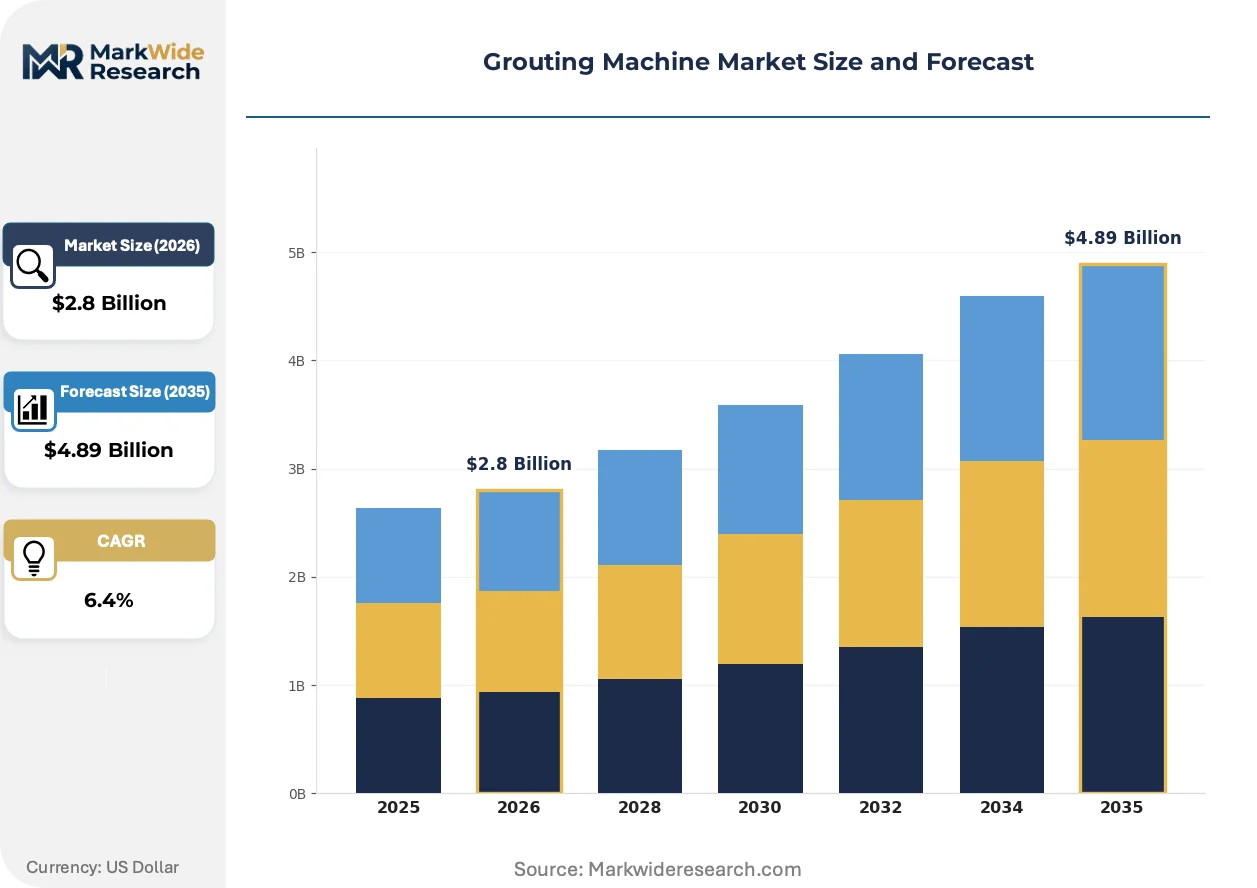
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mortar Grout, Chemical Grout, Epoxy Grout, Cement Grout End User: Construction, Infrastructure, Mining, Utilities Technology: Pneumatic, Hydraulic, Electric, Manual Application: Seepage Control, Structural Repair, Soil Stabilization, Tunnel Construction |
| Companies Covered | ChemGrout, Putzmeister, EZG Manufacturing, Schwing, Graco, TOHO CHIKAKOKI, Kenrich Products, MAI International GmbH, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grouting Machine Market Strategic Shifts
Electrification architectures are reshaping equipment design priorities as manufacturers balance power output against battery weight, while regulatory pressure on emissions and silica exposure accelerates technology substitution timelines across construction verticals.
Variable frequency drive electric pump systems are electrifying medium-pressure grouting applications previously dominated by diesel-hydraulic units. European metro contractors and indoor foundation specialists are adopting these platforms at accelerating rates to comply with urban noise ordinances and ventilation constraints. The shift is compressing the addressable market for combustion-powered equipment in densely populated construction zones.
OSHA silica exposure rules and EPA emission standards are forcing equipment redesigns across North American construction. Contractors face simultaneous pressure to reduce respirable dust generation and exhaust particulates, redirecting procurement specifications toward sealed mixing systems and electric or pneumatic powertrains. Tunnel and foundation segments are responding fastest through accelerated fleet turnover and rental channel preference shifts.
Equipment-as-a-service contracting is displacing traditional capital purchase models in large-scale infrastructure programs. Mining operators and dam rehabilitation specialists now prioritize uptime guarantees and bundled maintenance over asset ownership, compressing supplier margins while extending customer lock-in durations. This pattern is most visible in Australia's resources sector and China's state-owned construction consortia.
Grouting Machine Market Segmentation
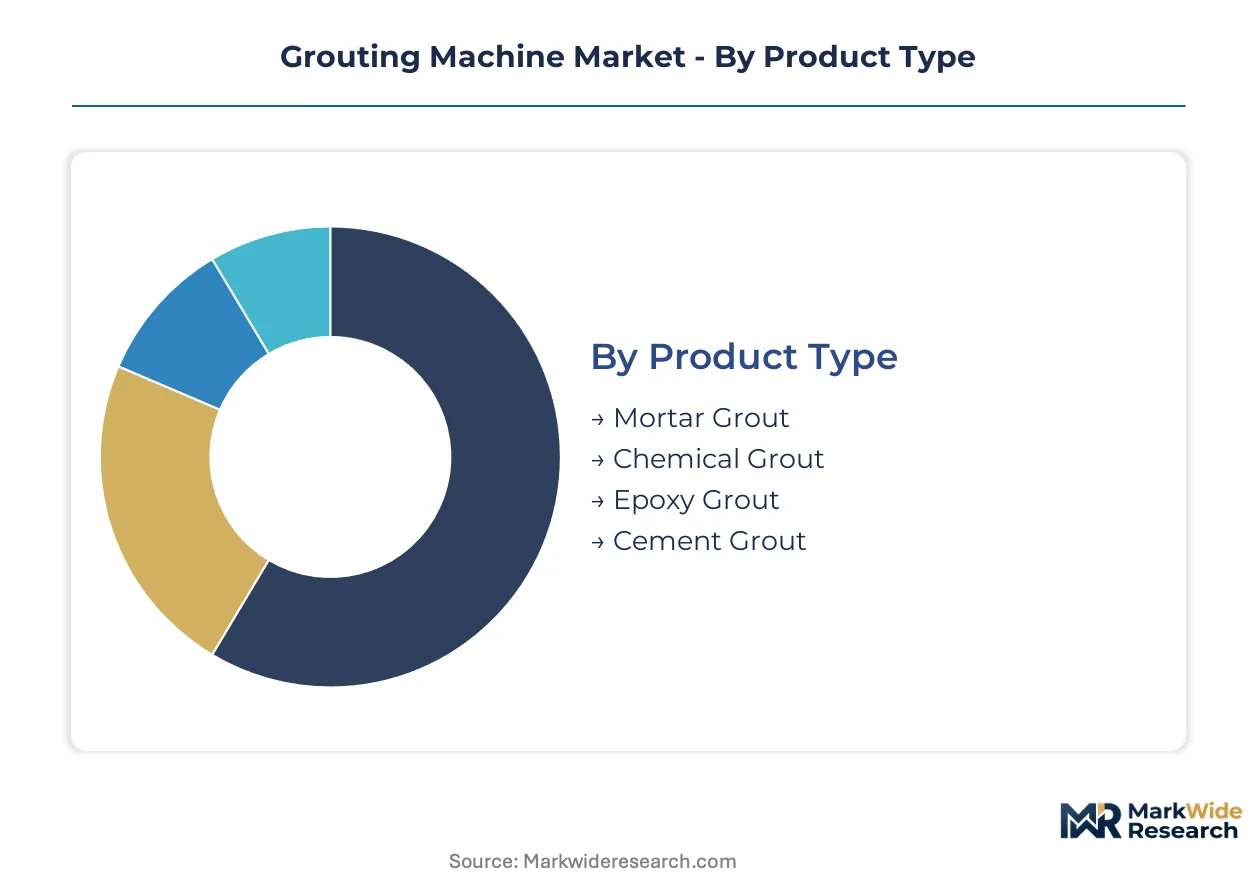
Grouting equipment procurement varies sharply by material chemistry, power architecture, and project scale. Contractors segment purchases around set-time requirements, emission constraints, and injection pressure specifications rather than treating pumps as interchangeable commodities.
Product Type:
Capital intensity escalates from simple cement slurry systems through precision chemical injection platforms requiring pressurized storage and metering infrastructure.
- Cement Grout:Standard Portland-based slurries dominate foundation and dam rehabilitation work where bulk void filling tolerates longer cure cycles. Demand concentrates in China's high-speed rail corridor and India's dam safety programs where volume economics override set-time urgency. Equipment requirements stay relatively modest—batch mixers and medium-pressure piston pumps suffice.
- Chemical Grout:Acrylate and polyurethane formulations achieve rapid gelation for mining void stabilization and pre-excavation ground conditioning. Underground operators in Australia's coal basins and South Africa's platinum belts specify these systems to compress project schedules where water inflow risks threaten tunnel advance rates. Capital requirements spike due to hazardous material handling infrastructure.
- Epoxy Grout:High-strength resin systems for precision machinery baseplates and structural crack injection.
- Mortar Grout:Pre-mixed cementitious products for masonry restoration and tile setting applications.
Cement grout absorbs the bulk of installed capacity; chemical grout is expanding most quickly.
End User:
Customer sophistication separates specification-driven mining procurement from price-sensitive construction rental channels.
- Infrastructure:State-owned rail and metro authorities drive the largest equipment orders through multi-year tunnel boring programs. China's state construction consortia and India's NHAI specify integrated high-pressure hydraulic platforms with real-time pressure telemetry. Procurement cycles extend 18-24 months with heavy compliance documentation.
- Mining:Underground operators prioritize rapid set chemical systems for ground consolidation ahead of mechanized extraction. Australian iron ore producers and Chilean copper majors contract equipment-as-a-service to transfer uptime risk onto vendors. Safety interlocks for explosive atmospheres elevate platform costs substantially.
- Construction:General contractors and specialty foundation firms.
- Utilities:Water authority and power transmission operators.
Infrastructure commands the dominant share of annual procurement value; mining exhibits the steepest expansion trajectory.
Technology:
Power source selection increasingly reflects regulatory geography rather than pure performance optimization.
- Hydraulic:Diesel-hydraulic platforms retain dominance in remote mining and dam sites lacking grid infrastructure. High-pressure output up to 700 bar supports deep injection and rock fissure sealing. EPA Tier 4 compliance costs and OSHA silica exposure rules are compressing the addressable market in US construction zones.
- Electric:Variable frequency drive systems penetrate European metro expansion and indoor foundation work where municipal noise ordinances and ventilation limits restrict combustion alternatives. Battery weight constraints still restrict mobility for off-grid applications.
- Pneumatic:Compressed air systems for explosive atmosphere mining environments.
- Manual:Hand-operated pumps for small-scale repair and maintenance tasks.
Hydraulic platforms retain the largest installed base; electric architectures are gaining share fastest in regulated urban construction zones.
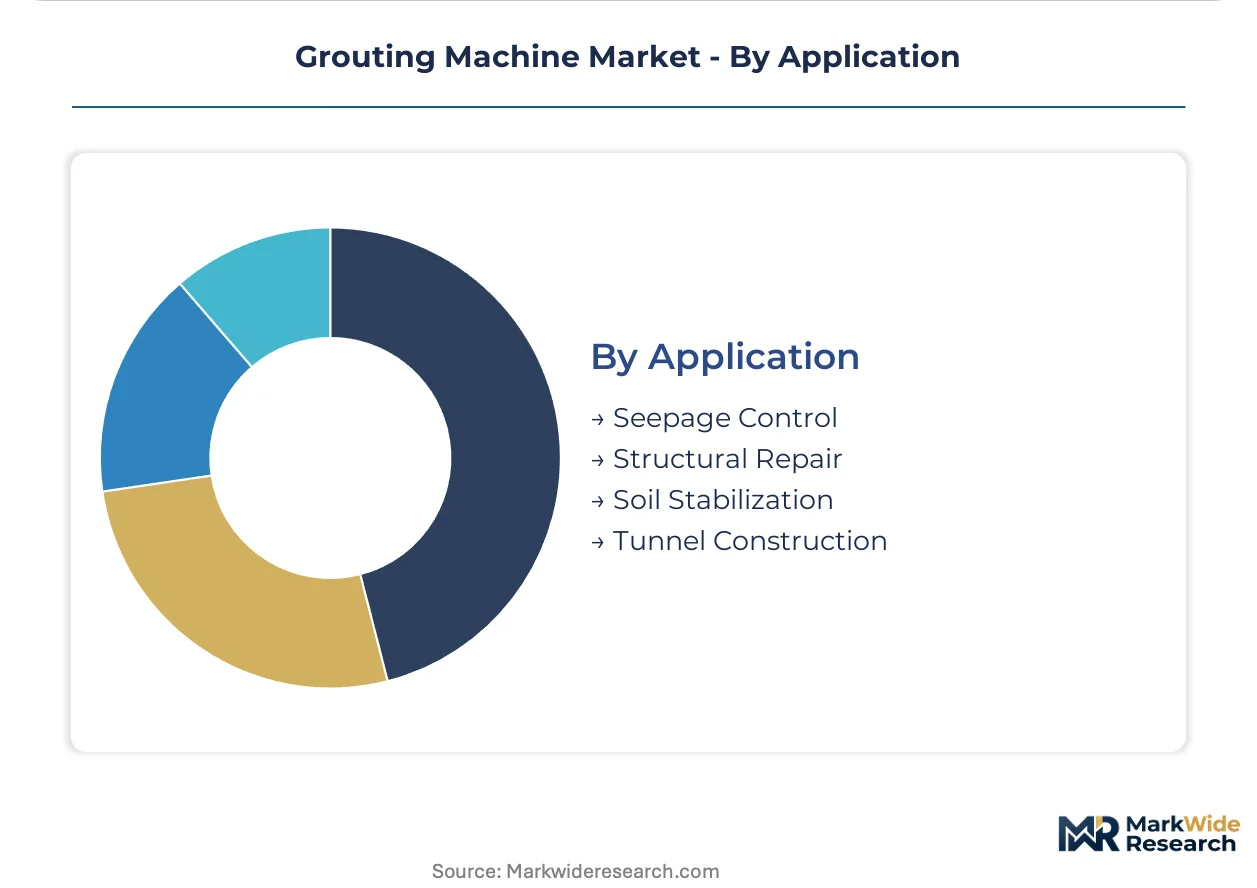
Application:
Injection depth and pressure requirements stratify equipment specifications across structural versus geotechnical use cases.
- Tunnel Construction:Mechanized tunnel boring drives sustained demand for high-pressure synchronous grouting systems that fill annular voids behind segmental linings. Asia-Pacific rail corridors—China's metro expansion, India's Mumbai-Ahmedabad bullet train, and Vietnam's North-South express—anchor procurement volumes. Pressure control accuracy prevents ground settlement damage to surface structures.
- Soil Stabilization:Permeation and compaction grouting for foundation support and liquefaction mitigation. Japanese port authorities and Dutch delta works operators specify these applications for seismic and flood resilience infrastructure.
- Seepage Control:Water cutoff curtains and dam foundation curtains.
- Structural Repair:Crack injection and delamination repair in concrete structures.
Tunnel construction claims the greatest equipment deployment; soil stabilization is climbing the fastest as climate resilience infrastructure accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the densest concentration of grouting equipment procurement, driven by China's metro expansion and high-speed rail corridors. Equipment demand radiates from this hub across Asia-Pacific infrastructure markets, with regulatory divergence shaping technology selection in North America and Europe.
China
Beijing-Tianjin-Hebei and Yangtze River Delta corridors drive sustained orders for high-pressure hydraulic platforms serving tunnel boring machines. MIIT equipment certification and GB standards for construction machinery enforce safety interlocks that filter uncertified suppliers. XCMG anchors domestic production through integrated chassis-pump combinations manufactured in Xuzhou.
United States
EPA Tier 4 final emission regulations and OSHA silica exposure rules redirect procurement toward pneumatic and electric architectures in urban construction zones. Midwest distribution networks concentrate portable mortar equipment serving foundation contractors. California and New York metro noise ordinances accelerate electric platform penetration ahead of federal mandates.
Germany
Ruhr industrial heritage sustains engineering-intensive high-pressure hydraulic platform production for export markets. CE marking and EU machinery directives elevate compliance documentation burdens for non-European suppliers. Putzmeister leverages Stuttgart-area manufacturing to dominate precision injection systems for mechanized tunneling across European rail corridors.
India
Mumbai-Ahmedabad bullet train and NHAI highway tunnel programs generate multi-year equipment procurement cycles. PLI scheme incentives for construction machinery create localized production pathways for integrated systems. Maharashtra and Karnataka infrastructure clusters concentrate demand for medium-pressure cement grout platforms in dam rehabilitation work.
Australia
Queensland and Western Australia mining belts prioritize rapid-set chemical grout systems for ground consolidation ahead of mechanized extraction. Equipment-as-a-service contracting displaces capital purchases among iron ore and copper majors. Explosive atmosphere safety interlocks elevate platform costs for underground coal basin operators.
Grouting Machine Market Competitive Environment
Premium-margin players sit above commodity-margin players across pressure-control accuracy and real-time monitoring capabilities. The vendor base stratifies between German-engineered high-pressure hydraulic specialists, Midwest US portable mortar distributors, and Chinese integrated chassis manufacturers. Three archetypes dominate: precision tunnel-boring platform builders, volume-scale portable equipment fabricators, and state-backed infrastructure machinery conglomerates. Competitive moves concentrate on telematics-integrated service models and geographic certification acquisition.
Within the German-engineered tier, Putzmeister and Schwing exemplify precision-focused archetypes anchored in Stuttgart-area manufacturing heritage. MAI International GmbH occupies a comparable position among specialized chemical injection platform builders. XCMG represents the state-backed infrastructure conglomerate model, leveraging domestic certification advantages across Asia-Pacific rail corridors. ChemGrout and EZG Manufacturing sit within the portable equipment segment, with the latter exemplifying Midwest distribution density strategies.
| Leading Market Players |
|---|
| ChemGrout |
| Putzmeister |
| EZG Manufacturing |
| Schwing |
| Graco |
| TOHO CHIKAKOKI |
| Kenrich Products |
| MAI International GmbH |
| XCMG |
| Others |
Value Chain & Pricing Dynamics
China's MIIT equipment certification mandates for safety interlocks and pressure relief protocols are forcing manufacturers to absorb elevated compliance costs or pass them downstream, compressing margins for uncertified suppliers while certified players gain pricing power. This specification tightening reshapes procurement patterns across Asia-Pacific infrastructure corridors.
Pricing Analysis
Equipment-as-a-service uptime guarantees anchor value-based pricing for mining and dam rehabilitation contracts, with Australian iron ore producers and Chinese state construction consortia prioritizing subscription models over capital purchase. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered precision platforms from Midwest portable mortar distributors and Chinese integrated chassis manufacturers. Cost compression in mid-tier hydraulic platforms intensifies because steel and precision valve assembly volatility squeezes manufacturers without captive supply arrangements. Construction rental channels exhibit highest price sensitivity; mining operators under equipment-as-a-service contracts show lowest sensitivity due to bundled maintenance coverage.
Supply Chain Analysis
Freight costs for high-pressure pump castings and precision valve assemblies from Germany and China elevate landed costs for North American and Asia-Pacific contractors, particularly for urgent tunnel boring machine integrations. Manufacturing concentrates in Germany for precision hydraulic platforms, China for integrated chassis-pump combinations, and the United States for portable mortar equipment. Component sourcing draws from Japanese specialty steel suppliers, Italian hydraulic component fabricators, and domestic foundries in each production hub. Single-source vulnerability for precision metering infrastructure creates procurement risk during multi-year rail corridor buildouts. Distribution runs through OEM-direct channels for large infrastructure projects and rental networks for general construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grouting machine market sits in a technology-transition phase where variable frequency drive electric systems are displacing diesel-hydraulic dominance in regulated urban construction zones.
For Market Incumbents: To counter electric platform penetration in European metro expansion corridors, hydraulic specialists must accelerate certification investment for sealed mixing systems that reduce respirable dust generation. Backward integration into precision valve assembly production defends margin structures against steel cost volatility. Channel control through telematics-integrated preventive maintenance subscriptions extends customer lock-in durations beyond equipment replacement cycles. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for construction machinery manufacturing by establishing localized production of medium-pressure cement grout platforms serving NHAI highway tunnel programs. India's dam rehabilitation clusters present the most penetrable geography given procurement cycle immaturity and technician scarcity bottlenecks. Partner with state construction consortia for integrated chassis-pump demonstration projects to bypass established distribution barriers. For Investors and Strategic Acquirers: The window for entry favors telematics-enabled service model specialists over pure equipment fabricators given the shift toward subscription-based uptime guarantees. Long-term viability hinges on regulatory compliance trajectory alignment across EPA, OSHA, and MIIT certification requirements. Watch electric motor power density breakthroughs as the inflection signal for remote mining site electrification feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | IoT-enabled pressure monitoring transforms aftermarket service into recurring revenue streams for tunnel contractors. |
| Electric Architecture Transition | Battery-electric platforms penetrate European metro expansion zones where noise ordinances restrict combustion alternatives. |
| Certification Investment | MIIT safety interlock compliance filters uncertified competitors from China's high-speed rail equipment procurement. |
| Backward Integration | In-house production of precision valve assemblies insulates margin structures from steel casting cost volatility. |
| Geographic Manufacturing Footprint | India PLI scheme localization reduces landed costs for South Asian dam rehabilitation and highway tunnel projects. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with tunnel project engineers, mining equipment procurement managers, construction rental fleet directors, and aftermarket service heads. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level outputs. Secondary sources included MIIT equipment certification databases, EPA Tier 4 compliance filings, OSHA silica exposure documentation, and construction machinery customs import records.
Segmentation granularity modeled product type, power architecture, end-use industry, and injection pressure specification across the analysis window. CAGRs derived from equipment procurement cycle analysis, infrastructure pipeline tracking, and technology substitution rate modeling. Forecast inputs incorporated tunnel boring machine deployment schedules, mining void filling activity indices, and regulatory compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density improvements, steel price volatility, and certification regime harmonization across jurisdictions. Forecasts reflect documented assumptions about infrastructure spending continuity and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market