
 Electric Mobility Market | 2026-2036
Electric Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Mobility Market Intelligence
Lithium iron phosphate is realigning battery economics across the Electric Mobility value chain by displacing nickel-cobalt chemistries in cost-sensitive segments. BYD leverages captive cell production to sustain margin control from mine to module. Tesla anchors North American demand through integrated charging infrastructure and software-defined vehicle architecture. NIO differentiates via battery-swapping networks that reduce upfront ownership costs.
Electric mobility encompasses battery-electric, plug-in hybrid, and fuel-cell propulsion systems designed for zero- or near-zero tailpipe emissions, with powertrains typically rated between 50 kW and 500 kW continuous output for passenger and commercial duty cycles. Battery Electric Vehicles occupy the dominant volume position, while Fast Charging Stations represent the fastest-expanding infrastructure category as fleet operators demand sub-30-minute turnaround times. Solid-state Batteries command concentrated R&D investment despite lithium-ion's current manufacturing scale, reflecting a margin pool migration toward next-generation energy density.
The EPA tailpipe standards and EU Green Deal binding targets jointly mandate fleet-average CO2 reductions that eliminate internal-combustion sales channels by statutory deadlines. China's MIIT new-energy vehicle credit system enforces domestic production quotas that BYD and XPeng satisfy through vertical battery-cell operations. Stakeholders must monitor regulatory credit arbitrage between jurisdictions and solid-state battery readiness timelines that could render incumbent lithium-ion capacity stranded.
Market Dynamics
Lithium iron phosphate chemistry is consolidating battery procurement economics while fleet operators demand sub-30-minute charging turnaround. This chemistry shift compresses nickel-cobalt supply exposure and realigns cell manufacturing location decisions toward phosphate-rich jurisdictions.
Growth Catalysts
- EU Green Deal binding targets:Fleet-average CO2 mandates eliminate internal-combustion sales channels by statutory deadlines, forcing zero-tailpipe powertrain procurement across logistics networks.
- China's MIIT credit system:Domestic production quotas enforce new-energy vehicle output minimums that manufacturers satisfy through vertical battery-cell operations.
- Fleet electrification:Urban logistics operators expand electric vehicle procurement to meet last-mile emission restrictions in municipal zones.
Market Restraints
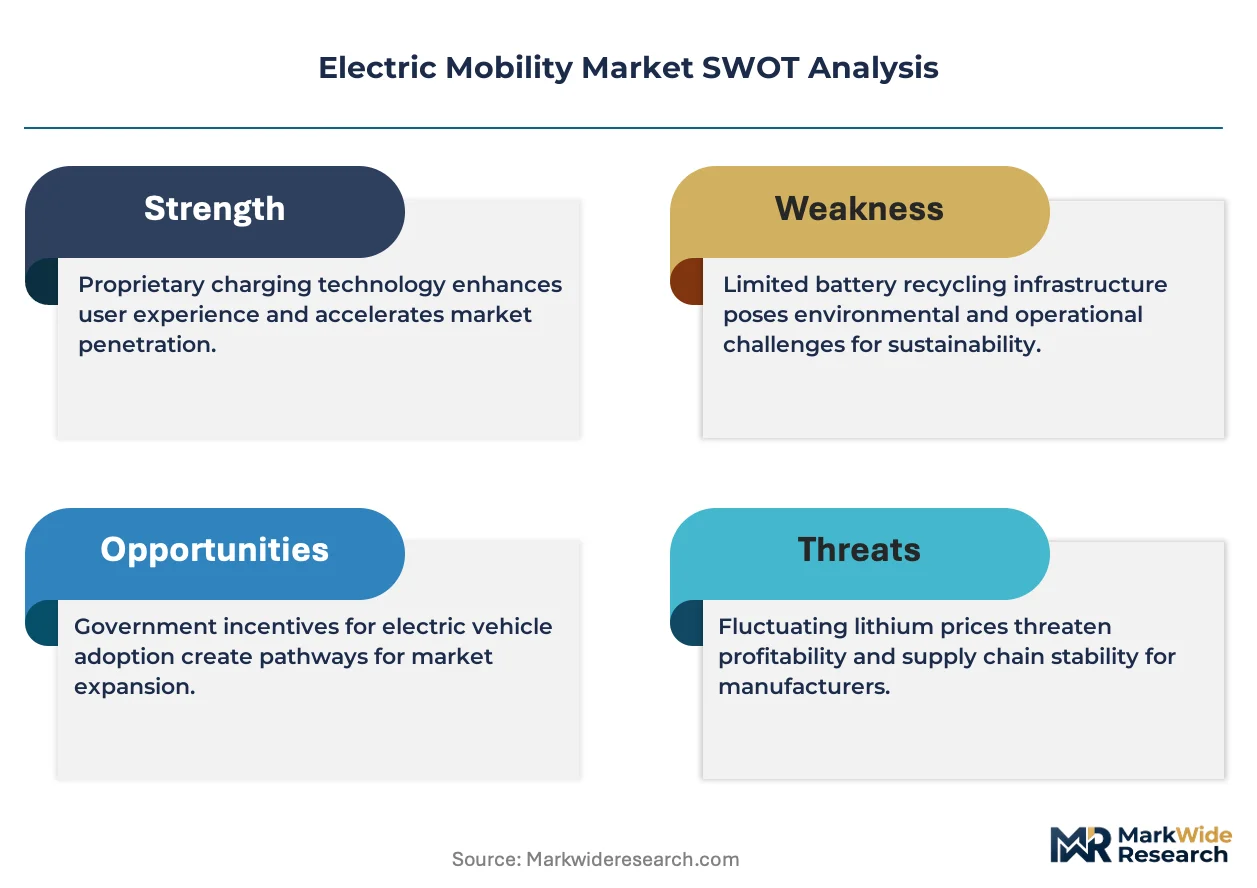
- Lithium carbonate price volatility:Cell input costs fluctuate with South American brine extraction capacity and Australian spodumene concentrate availability.
- Charging infrastructure gaps:Fast-charging station density remains insufficient along intercity corridors outside China, limiting range confidence for commercial duty cycles.
- Grid capacity constraints:Distribution network upgrades lag behind depot charging demand in Germany and California, delaying fleet conversion timelines.
Strategic Opportunities
- India's PLI scheme:Advanced chemistry cell manufacturing incentives attract investment to underpenetrated demand centers with limited incumbent battery supply.
- Battery-as-a-service models:Swapping networks reduce upfront ownership costs for price-sensitive commercial segments in dense urban environments.
- Solid-state convergence:Next-generation energy density technologies enable aviation and marine applications currently blocked by lithium-ion weight limitations.
Industry Challenges
- Power electronics talent scarcity:Inverter and onboard charger engineering expertise concentrates among semiconductor veterans in Taiwan and Germany.
- Certification timeline compression:UN ECE R100 battery safety testing and EPA tailpipe compliance create sequential bottlenecks for new model launches.
- Legacy fleet integration:Mixed-powertrain maintenance facilities require technician retraining and diagnostic tool upgrades that strain operator capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Mobility Market |
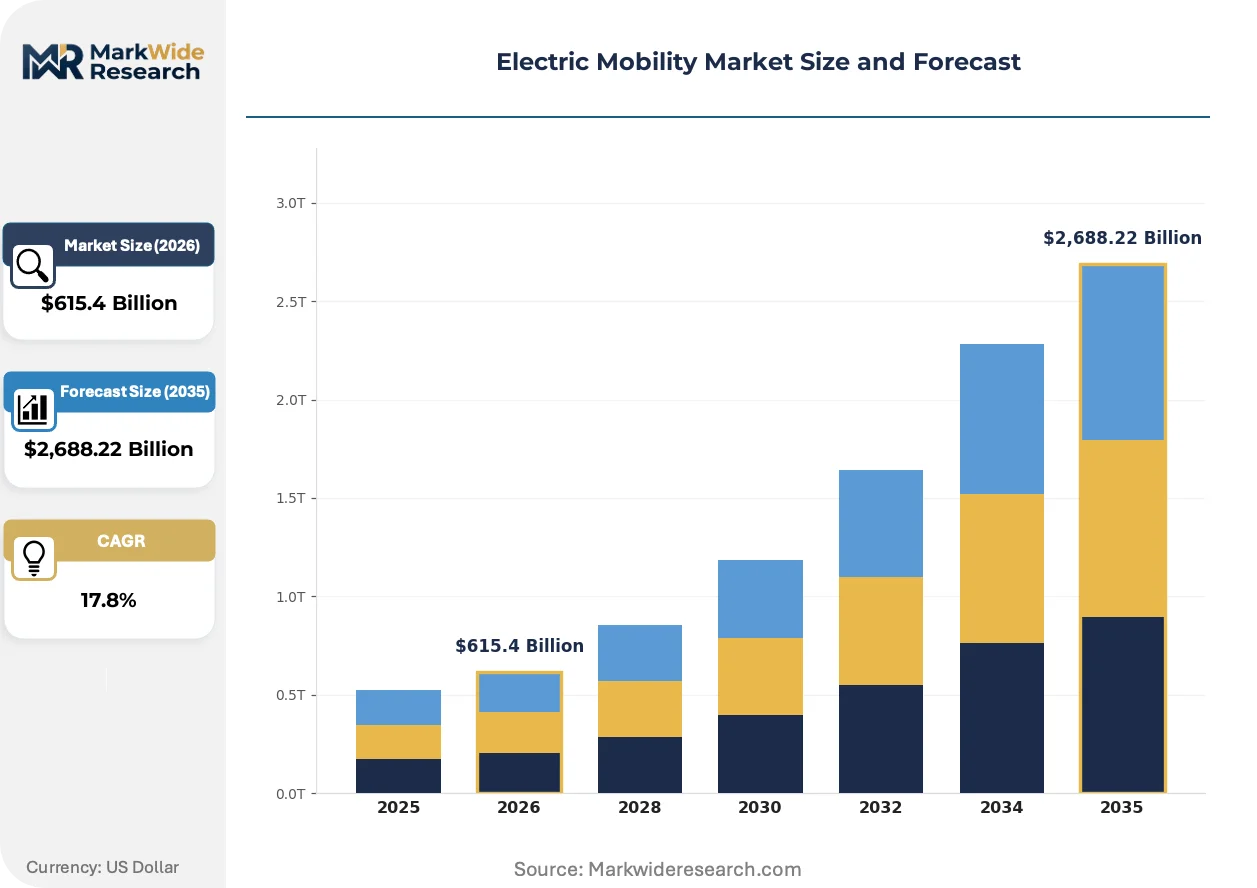
| Market Size in 2026 | $615.4 Billion |
| Market Size in 2035 | $2,688.22 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Light Electric Vehicles Charging Infrastructure: Home Charging Stations, Public Charging Stations, Fast Charging Stations, Wireless Charging Solutions End User: Individual Consumers, Fleet Operators, Ride-sharing Services, Government Agencies Battery Technology: Lithium-ion, Solid-state Batteries, Nickel Metal Hydride, Lead Acid |
| Companies Covered | Xiaomi, NIO, Tesla, Lucid Motors, XPeng, BYD, Rivian, Li Auto, Volkswagen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Mobility Market Strategic Shifts & Innovations
Software-defined vehicle architecture is redefining competitive differentiation beyond powertrain specifications. This shift elevates over-the-air update capability and charging network integration above traditional hardware metrics.
Lithium iron phosphate cathode formulations are consolidating cost-sensitive segments by eliminating nickel and cobalt from bill-of-materials. Mass-market passenger vehicles and urban delivery vans adopt these cells fastest. This consolidation is compressing margin pools for nickel-cobalt cathode suppliers and redirecting cell factory investment toward phosphate precursor supply chains.
EPA tailpipe standards and EU Green Deal mandates are tightening fleet-average emission ceilings through binding statutory deadlines. Automakers respond by accelerating battery-electric model introductions and phasing internal-combustion platforms. Commercial vehicle segments face the steepest compliance gradients and are deploying plug-in hybrid bridging technologies where charging infrastructure remains sparse.
Fleet procurement is fragmenting across ownership models that separate asset from energy. Logistics operators lease vehicles while contracting battery capacity through swapping subscriptions or third-party charging service agreements. This unbundling is most advanced in Chinese metropolitan zones where NIO and state grid operators coordinate swap station networks with municipal permit preferences.
Electric Mobility Market Segmentation
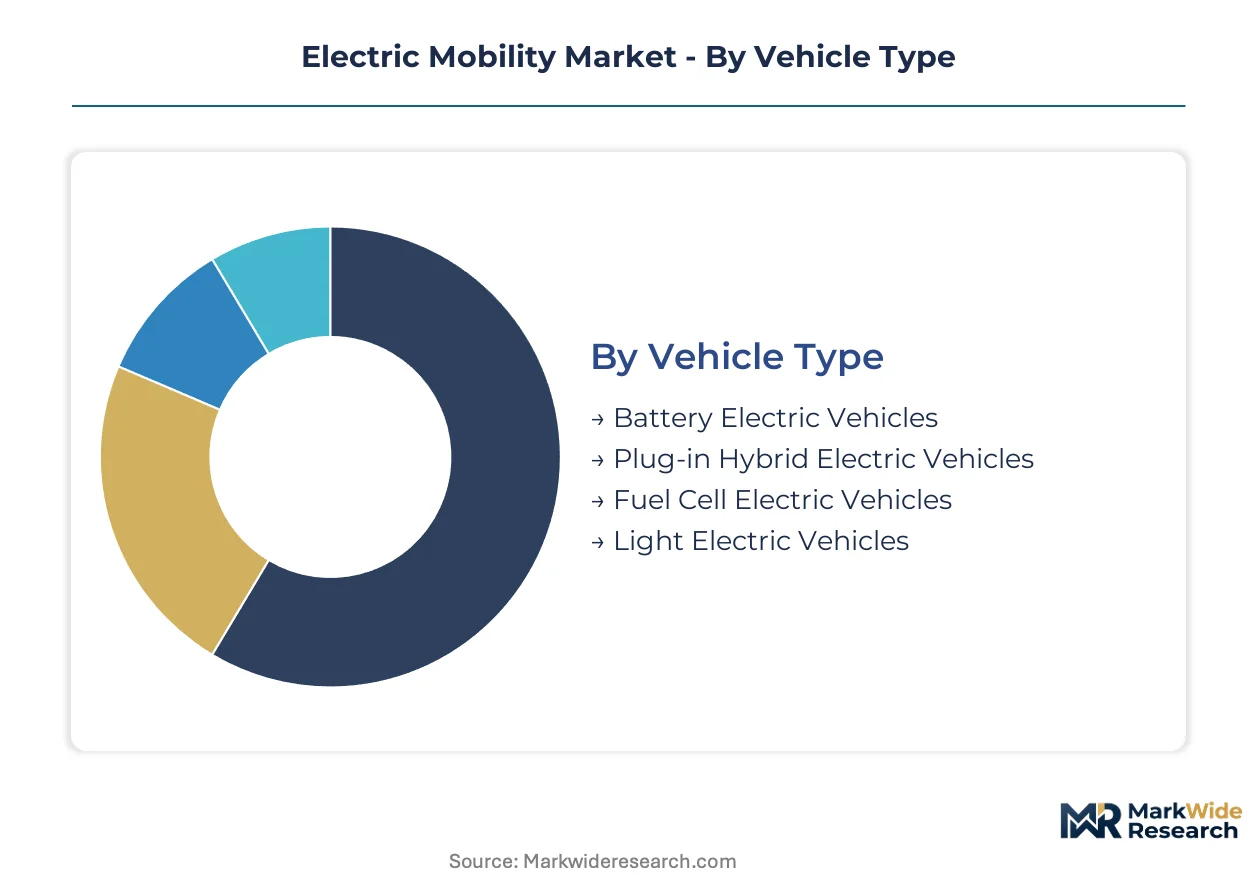
Segmentation in electric mobility reveals how powertrain diversity, infrastructure maturity, and customer procurement patterns fragment addressable value pools. Manufacturers must align product portfolios across vehicle classes, charging modalities, and battery chemistries to capture differentiated margin structures.
Vehicle Type:
Standardized platforms dominate high-volume segments while bespoke architectures serve niche duty cycles across this vehicle taxonomy.
- Battery Electric Vehicles:Pure-electric powertrains with 50-500 kW continuous output eliminate tailpipe emissions entirely. Fleet operators in Germany and California concentrate procurement here to satisfy EPA tailpipe standards and EU Green Deal mandates for urban logistics.
- Plug-in Hybrid Electric Vehicles:Dual-powertrain systems combine internal-combustion range extension with electric-only urban operation. Commercial segments in charging-sparse corridors adopt these most heavily where depot infrastructure lags grid capacity upgrades.
- Fuel Cell Electric Vehicles:Hydrogen fuel cell stacks rated 100-300 kW target heavy-duty freight corridors with sub-15-minute refueling requirements.
- Light Electric Vehicles:Two- and three-wheelers with sub-15 kW motors address last-mile delivery density in Indian and Southeast Asian metropolitan zones.
Leading the category by volume: Battery Electric Vehicles. Expanding most quickly: Light Electric Vehicles.
Charging Infrastructure:
Cost tier stratification separates consumer-installed hardware from utility-scale fast-charging networks requiring distribution network reinforcement.
- Home Charging Stations:Level 1 (120V) and Level 2 (240V) residential units deliver 3-19 kW overnight charging for individual consumers. Suburban single-family dwellings in the United States and Australia drive installation volume where off-street parking availability exceeds 70%.
- Fast Charging Stations:DC fast chargers rated 150-350 kW enable sub-30-minute turnaround for commercial duty cycles. Fleet operators along German autobahn corridors and California interstate highways demand these most aggressively where range anxiety blocks battery-electric adoption.
- Public Charging Stations:Level 2 curbside and parking garage installations serve urban dwellers without residential charging access.
- Wireless Charging Solutions:Inductive pad systems eliminate connector wear for autonomous shuttle and taxi applications in controlled-access zones.
Fast Charging Stations claim the steepest expansion trajectory. Home Charging Stations retain the installed base majority.
End User:
Volume concentration versus margin capture diverges sharply across customer archetypes with divergent total-cost-of-ownership horizons.
- Fleet Operators:Logistics and delivery enterprises procure vehicles through leasing structures with battery-as-a-service unbundling. Municipal last-mile restrictions in Paris, London, and Shenzhen force conversion timelines that outpace charging infrastructure deployment.
- Individual Consumers:Private buyers prioritize purchase price parity and charging network confidence over total ownership cost optimization. China's MIIT credit system subsidies and the U.S. IRA tax credits reshape affordability calculations in each jurisdiction.
- Ride-sharing Services:High-utilization operators demand vehicles with 300,000+ km durability warranties and swap-compatible battery architectures.
- Government Agencies:Municipal procurement mandates specify domestic content minimums and union assembly requirements that filter supplier eligibility.
Fleet Operators drive volume procurement. Ride-sharing Services represent the fastest-climbing customer segment.
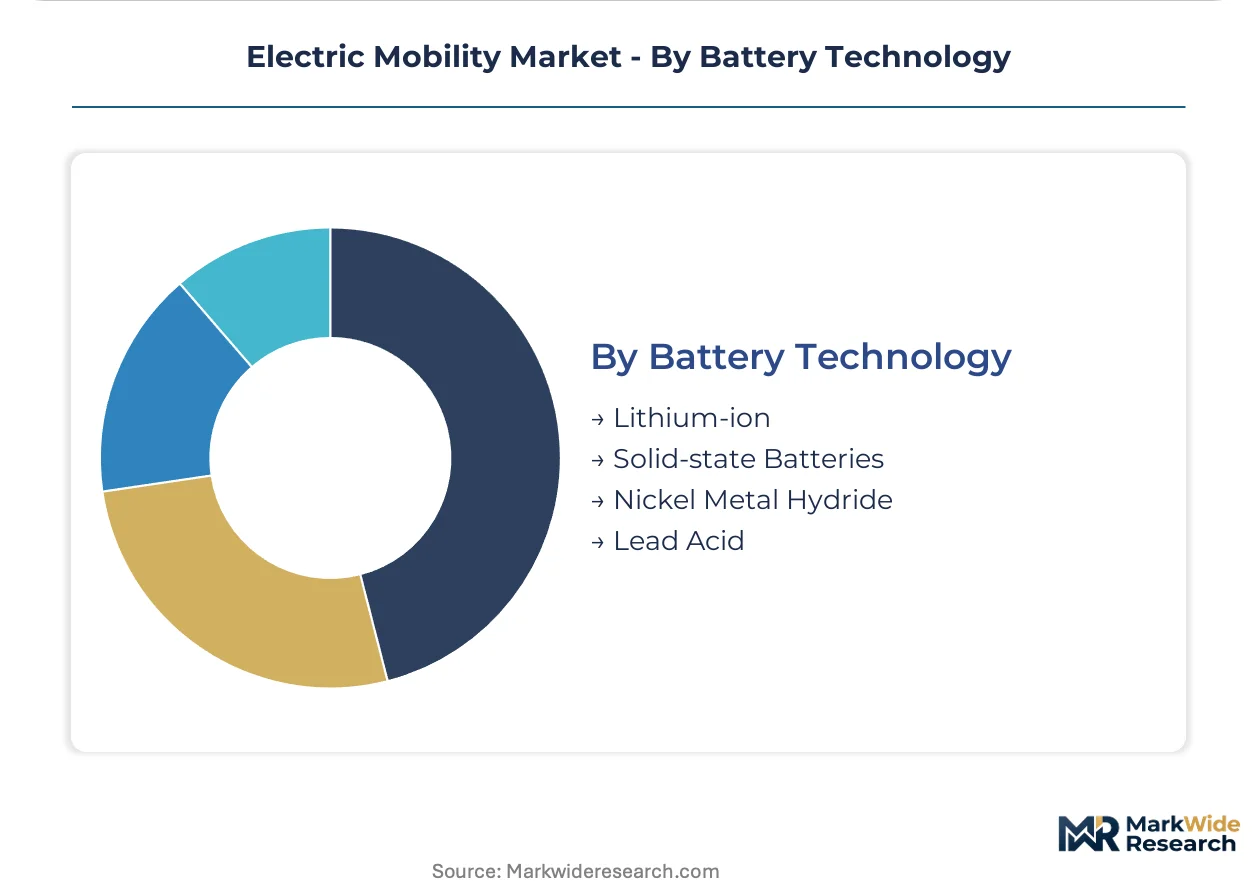
Battery Technology:
Supply concentration versus performance differentiation defines competitive positioning across cell chemistries with divergent raw material exposure profiles.
- Lithium-ion:Nickel-cobalt-manganese and lithium iron phosphate cathodes dominate manufacturing scale with 150-300 Wh/kg energy density. BYD's captive phosphate production and CATL's ternary cell output anchor supply chains in China where MIIT production quotas concentrate capacity expansion.
- Solid-state Batteries:Ceramic or polymer electrolytes promise 400+ Wh/kg density with reduced thermal runaway risk. Aviation and marine applications in Japan and South Korea fund pilot production where lithium-ion weight limitations block electrification.
- Nickel Metal Hydride:Mature chemistry retains hybrid vehicle applications where battery size constraints are less stringent than pure-electric platforms.
- Lead Acid:Ancillary power and low-speed vehicle segments utilize this chemistry where energy density requirements remain minimal and cost sensitivity peaks.
Lithium-ion leads by installed capacity. Solid-state Batteries gain share fastest in premium and industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing scale and battery supply chain density. Germany and the United States anchor premium vehicle development and fleet electrification. Regulatory mandates in the EU and EPA jurisdictions force conversion timelines that outpace infrastructure deployment elsewhere.
China
MIIT production quotas enforce new-energy vehicle output minimums that manufacturers satisfy through vertical battery-cell operations. The country's MIIT credit system subsidizes domestic procurement while penalizing non-compliance. The Yangtze River Delta and Pearl River Delta clusters concentrate BYD and CATL manufacturing capacity alongside NIO and XPeng assembly plants.
United States
EPA tailpipe standards mandate fleet-average CO2 reductions that eliminate internal-combustion sales channels by statutory deadlines. The IRA tax credits reshape affordability calculations for battery-electric passenger vehicles and commercial trucks. California's Advanced Clean Trucks regulation forces logistics operators in Los Angeles and the San Francisco Bay Area to accelerate zero-tailpipe procurement.
Germany
KBA certification requirements and EU Green Deal binding targets jointly enforce zero-tailpipe powertrain adoption across automotive OEM supply chains. The country's national automotive regulator coordinates UN ECE R100 battery safety testing with EPA-equivalent compliance frameworks. Bavaria and Baden-Württemberg host Volkswagen Group electrification engineering while North Rhine-Westphalia concentrates fast-charging corridor deployment along autobahn freight routes.
India
FAME-II subsidies and the PLI scheme for advanced chemistry cell manufacturing attract investment to underpenetrated demand centers with limited incumbent battery supply. The country's central electricity authority coordinates distribution network upgrades for depot charging in metropolitan zones. Maharashtra and Gujarat anchor Tata Motors and Mahindra electric vehicle assembly while Karnataka concentrates battery pack integration facilities.
South Korea
METI-coordinated solid-state battery R&D funding targets aviation and marine applications where lithium-ion weight limitations block electrification. The country's national industrial policy directs Samsung SDI and LG Energy Solution toward next-generation energy density technologies. The Seoul Capital Area and Busan-Ulsan corridor concentrate cathode precursor chemical processing and cell manufacturing export capacity.
Electric Mobility Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs controlling premium passenger vehicle positioning while component suppliers capture margin pools in battery and charging infrastructure. The structure concentrates around three strategic archetypes: vertically integrated automakers with captive cell production, pure-play battery manufacturers serving multiple OEMs, and charging network operators unbundling energy from vehicle assets. Competitive moves center on backward integration into raw material supply and geographic expansion of manufacturing footprint to satisfy regional content requirements.
Within the integrated OEM tier, BYD and Tesla exemplify divergent approaches to margin control through upstream supply chain positioning, while NIO occupies a distinct position via battery-swapping network architecture. Chinese manufacturers concentrate manufacturing scale advantages, whereas US-based players anchor software-defined vehicle differentiation. These three companies represent the dominant competitive archetypes shaping procurement patterns and technology roadmaps across the analysis window.
| Leading Market Players |
|---|
| Xiaomi |
| NIO |
| Tesla |
| Lucid Motors |
| XPeng |
| BYD |
| Rivian |
| Li Auto |
| Volkswagen Group |
| Others |
Cost & Logistics Intelligence
Power electronics engineering talent clustering in Taiwan and Germany creates labor-cost differentials that widen pricing spreads between mass-market and premium vehicle tiers. These regional wage disparities compound with raw material exposure to stratify final assembly economics across OEM portfolios.
Pricing Analysis
Volume-mass-market segments sacrifice margin for procurement scale while premium tiers capture software-defined vehicle premiums. Three-tier pricing structure across premium, standard, and economy levels separates NIO's swap-enabled subscriptions from BYD's phosphate-cell value positioning and entry-level light electric vehicles. Price differentiation hinges on battery chemistry grade and charging speed certification, with fleet operators in California and Germany showing lowest sensitivity due to total-cost-of-ownership optimization. Cost compression in economy tiers is intensifying because lithium carbonate volatility feeds through to cell bill-of-materials.
Supply Chain Analysis
UN ECE R100 battery safety certification and EPA tailpipe compliance create dual qualification gates that filter supplier eligibility to established cell manufacturers. Geographic supply concentrates in China, South Korea, and Japan where cathode precursor processing and cell finishing anchor manufacturing gravity. The supply chain draws from Australian spodumene concentrate, Chilean lithium brine, and Indonesian nickel laterite for critical mineral feedstocks. Single-source vulnerability in semiconductor power modules for inverters and onboard chargers threatens production continuity. Distribution runs through OEM captive networks for passenger vehicles and third-party leasing structures for commercial fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated cell producers as lithium iron phosphate economics and MIIT production quotas force dependent assemblers toward acquisition or exit.
For Market Incumbents: Cement phosphate chemistry scale advantages through backward integration into precursor chemical processing in Yunfu or Changzhou clusters. Lock in long-term spodumene offtake from Australian concentrate producers to insulate against South American brine supply disruptions. Solid-state battery readiness timelines represent the primary substitution threat requiring R&D hedging. For New Entrants and Emerging Players: Municipal fleet operators in Indian metropolitan zones present the most penetrable buyer archetype given FAME-II subsidy eligibility and limited incumbent battery supply. Target last-mile logistics operators in charging-sparse corridors with plug-in hybrid bridging products where grid capacity lags depot demand. A battery-as-a-service unbundling model reduces upfront capital barriers for price-sensitive commercial procurement. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state battery specialists given aviation and marine application funding from METI-coordinated programs in Japan and South Korea. Long-term viability favors cell manufacturers with ceramic electrolyte pilot lines and OEM qualification progress. The signal to watch is UN ECE R100 certification timeline compression for next-generation energy density platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD phosphate cell commitments secure raw material allocation for European OEM electrification timelines. |
| Backward Integration | Captive lithium extraction in Sichuan brine operations reduces carbonate price exposure for cost-sensitive segments. |
| Software-Defined Vehicle Investment | Tesla's over-the-air architecture commands subscription revenue streams beyond hardware margin capture. |
| Charging Infrastructure Partnership | NIO swap station networks with state grid operators reduce fleet operator range anxiety in Chinese municipal zones. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract cell assembly to Karnataka and Tamil Nadu for regional content compliance. |
Research Approach
Multi-period observation of MIIT production quota compliance, EPA tailpipe standard adoption curves, and lithium carbonate spot price movements anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator logistics directors, and battery cell manufacturing executives. Secondary validation drew from EPA regulatory filings, EU Green Deal implementation progress reports, China Association of Automobile Manufacturers production statistics, and UN ECE R100 certification databases. Bottom-up vehicle registration data triangulated against top-down OEM revenue disclosures established market sizing boundaries.
Input-output matrix modeling connected battery chemistry cost curves, charging infrastructure deployment rates, and regulatory mandate phase-in schedules to project segment-level adoption trajectories across the analysis window. Segmentation dimensions included vehicle class taxonomy, propulsion architecture, battery chemistry tier, charging modality, and regional production cluster. CAGRs were derived from slope-intercept calibration against historical penetration curves with lithium iron phosphate cost reduction trajectories and solid-state battery pilot production timelines as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization timelines, lithium supply expansion from South American brine operations, and EU Green Deal enforcement stringency across member state automotive markets. A model refresh is warranted upon material change in UN ECE R100 certification requirements or MIIT credit system subsidy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
South Korea E-Bike Market