
 Global Automotive Carpeting Market | 2026-2036
Global Automotive Carpeting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Carpeting Market Intelligence
Southeast Asia is reconfiguring its supplier base as Thailand and Vietnam add thermoforming capacity for molded carpet assemblies. Lear Corporation leverages vertical integration across resin compounding and finished goods to control cost positions in North America. Toyota Boshoku anchors Japanese OEM relationships through dedicated design centers in Aichi Prefecture. Autoneum Holding AG specializes in acoustic-optimized carpet systems that reduce NVH for premium electric platforms.
Automotive carpeting encompasses tufted, needle-punched, and thermoformed textile assemblies bonded to polyurethane foam or rubber backing layers, typically weighing between 1,500 and 3,000 grams per square meter depending on vehicle class and acoustic requirements. These systems provide interior aesthetics, footwell cushioning, thermal insulation, and sound absorption while integrating with vehicle safety structures for pedal entrapment prevention. Floor mats and trunk liners in nylon and polypropylene formulations occupy mature volume positions with stable OEM pricing. Sound insulation segments in polyurethane foam and multi-layer composites capture expanding value pools as electric vehicle architectures eliminate engine masking noise and amplify cabin acoustic requirements. Passenger vehicle applications dominate unit demand while commercial vehicle specifications sustain higher per-vehicle material weights and durability standards.
EPA fuel economy standards and NHTSA safety regulations in the United States mandate flammability resistance and pedal interference testing that shape carpet substrate selection and attachment system design. REACH chemical restrictions and the EU Green Deal's circular economy requirements in Europe are accelerating recycled PET and bio-based polyamide validation programs among Tier 1 suppliers. China's MIIT dual carbon goals and GB standards for interior air quality are forcing reformulation of adhesives and foam backings across the Yangtze and Pearl River Delta manufacturing corridors. Stakeholders must monitor regulatory divergence between VOC emission limits and recycled content mandates when allocating R&D budgets across regional product portfolios.
Market Dynamics
Electric vehicle platform architectures are eliminating engine masking noise, forcing carpet suppliers to engineer multi-layer acoustic systems that compensate for amplified cabin noise signatures while meeting weight reduction mandates.
Growth Catalysts
- EU Green Deal CO2 Fleet Targets:German OEMs are expanding orders for lightweight interior materials to comply with tightening emission standards, directly stimulating demand for thermoformed carpet assemblies with reduced mass.
- China MIIT Dual Carbon Goals:Domestic OEMs in the Yangtze River Delta are localizing supply chains for interior components, creating captive demand for regional carpet manufacturing capacity.
- Polyurethane Foam Innovation:Advanced multi-layer composite backings are capturing expanding value pools as acoustic requirements intensify across premium electric vehicle segments.
Market Restraints
- Petrochemical Input Volatility:Nylon and polypropylene resin prices fluctuate with crude oil markets, compressing margin predictability for tufted carpet producers dependent on synthetic fiber feedstocks.
- Yangtze River Delta Concentration:Manufacturing corridor clustering creates geographic supply risk from single-region weather disruptions or logistics bottlenecks affecting just-in-time OEM delivery schedules.
- REACH Chemical Restrictions:ECHA reformulation mandates for adhesives and flame retardants extend validation timelines and increase R&D overhead for European market access.
Strategic Opportunities
- Thailand Thermoforming Capacity:Southeast Asian suppliers are adding molded carpet assembly lines to serve Japanese OEM expansion into ASEAN production bases.
- Recycled PET Validation:Circular economy requirements under EU Green Deal are accelerating post-consumer fiber adoption programs among Tier 1 suppliers seeking regulatory preference.
- Acoustic-Optimized Systems:NVH reduction specifications for electric platforms are creating premium pricing tiers for carpet systems integrating mass-damping layers and tuned resonant cavities.
Industry Challenges
- Adhesive Reformulation Expertise:GB standards for interior air quality in China are forcing technical staff retraining across Pearl River Delta manufacturing facilities to manage low-VOC bonding chemistry.
- Multi-Material Integration Complexity:Carpet systems must now interface with battery thermal management structures and pedal entrapment safety architectures, expanding design validation scope.
- Recycled Content Certification Timelines:Third-party verification for post-industrial and post-consumer material claims extends product qualification cycles by 8-14 months for EU-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Carpeting Market |
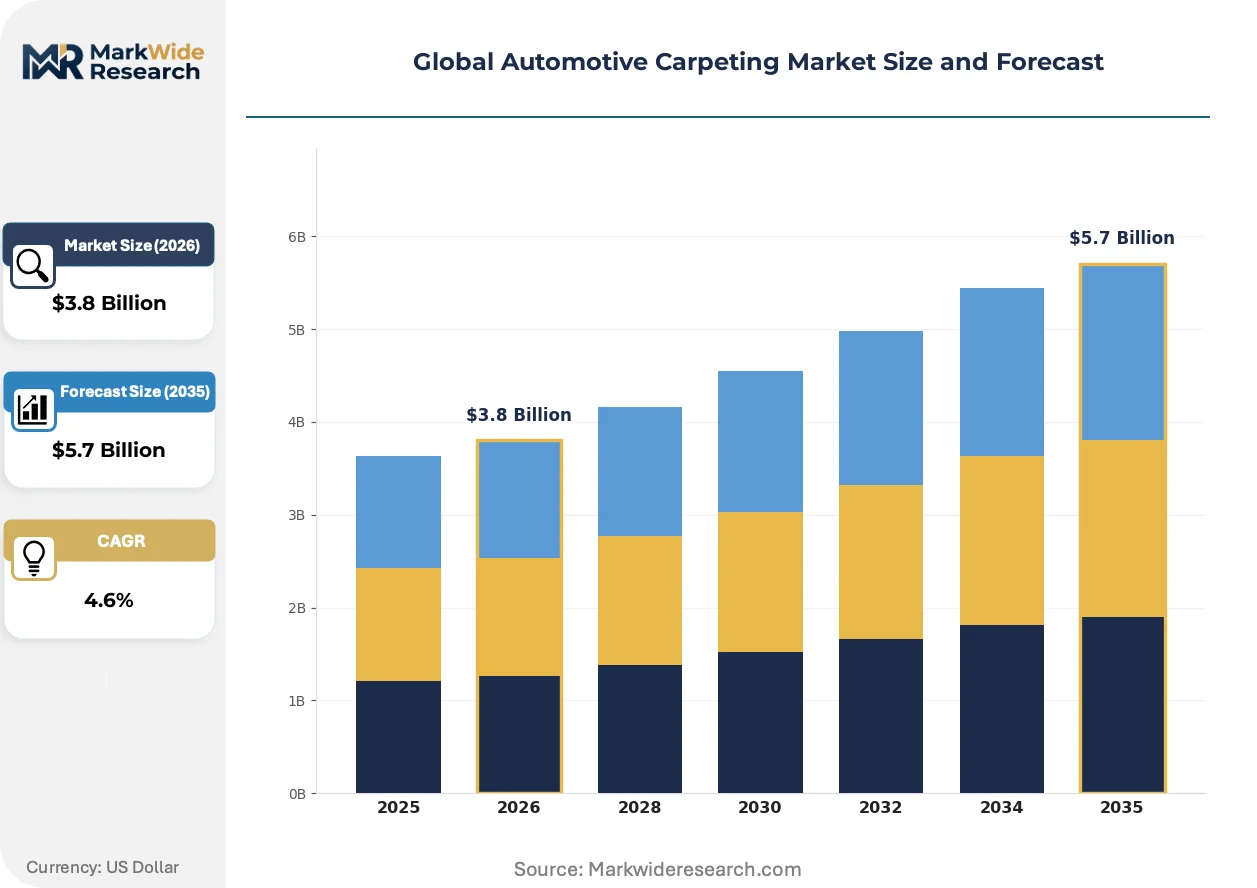
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Mats, Trunk Liners, Sound Insulation, Roof Liners, Door Panels Material: Nylon, Polyester, Polypropylene, Polyurethane Foam, Rubber, PVC Application: Passenger Vehicles, Commercial Vehicles, Off-road Vehicles, Specialty Vehicles Customer Type: OEMs, Aftermarket Suppliers, Vehicle Refinishing Shops, Fleet Operators |
| Companies Covered | Lear Corporation, Adient plc, Magna International Inc., Autoneum Holding AG, Toyota Boshoku Corporation, Faurecia, IAC Group, Freudenberg Performance Materials, Hyosung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Carpeting Market Strategic Shifts & Innovations
Digital manufacturing workflows and material science advances are compressing development cycles for acoustic-optimized interior systems while regulatory chemistry mandates force systematic reformulation of legacy bonding and backing technologies.
Thermoforming simulation software is digitizing mold flow prediction and fiber orientation optimization for complex three-dimensional footwell geometries. Tier 1 suppliers in Germany and Japan are adopting these tools to reduce physical prototyping iterations by half. The technology is digitizing supplier-OEM collaboration models, enabling real-time design iteration through shared cloud-based simulation environments.
REACH authorization requirements for flame retardants and plasticizers are compelling systematic substitution of halogenated chemistries in carpet backings and adhesives. ECHA substance evaluation is forcing suppliers to maintain dual formulation tracks during transition periods. European premium electric vehicle programs are most affected, with validation programs now spanning 18-24 months for alternative chemistry qualification.
Fleet procurement consolidation among German and Chinese OEMs is concentrating specification authority at platform-architecture levels rather than individual vehicle programs. Long-term supply agreements with fixed pricing bands are displacing annual spot negotiations for high-volume carpet assemblies. This pattern is most visible in China's Yangtze River Delta cluster, where SAIC, Geely, and NIO have centralized interior sourcing decisions.
Global Automotive Carpeting Market Segmentation
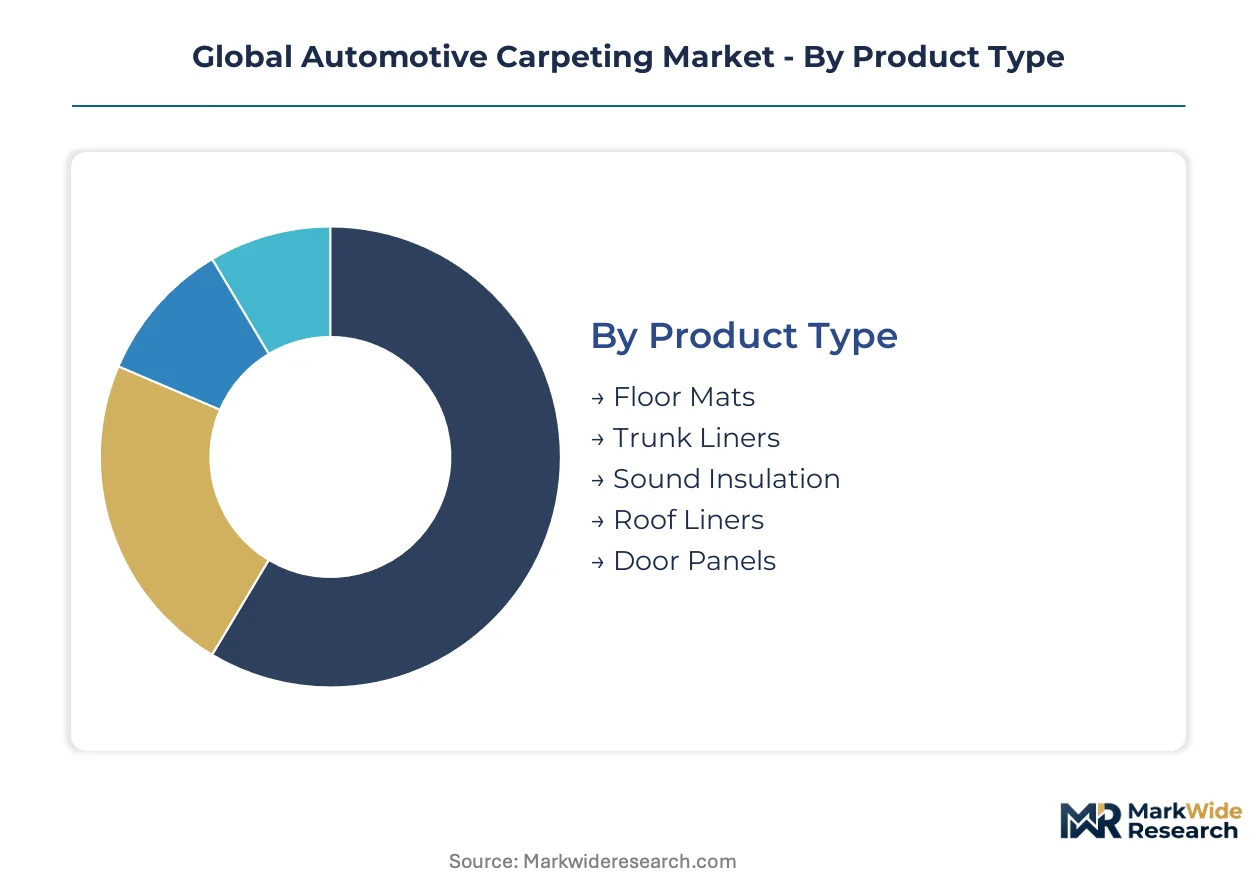
Automotive carpeting segmentation reflects divergent technical requirements across vehicle architectures, material science capabilities, and procurement channel economics. Each dimension captures distinct margin profiles and regulatory exposure that shape supplier portfolio allocation.
Product Type:
Cost tier differentiation separates commodity floor protection from engineered acoustic systems commanding premium pricing.
- Floor Mats:Nylon and polypropylene tufted assemblies with rubber or PVC backing provide entry-level interior protection. Demand concentrates in aftermarket channels across India's NCR and Maharashtra clusters where UV degradation resistance drives specification.
- Sound Insulation:Multi-layer polyurethane foam composites with mass-damping substrates address amplified cabin noise in electric platforms. German OEMs in Stuttgart and Munich are expanding orders for tuned resonant cavity designs that compensate for eliminated engine masking.
- Trunk Liners:Thermoformed polypropylene sheets with anti-abrasion coatings serve mature volume positions with stable OEM pricing.
- Roof Liners:Lightweight needle-punched fabrics bonded to foam backings integrate with headliner modules for head impact protection.
- Door Panels:Compression-molded fiber assemblies with decorative surfacing complete interior aesthetic systems.
Sound insulation holds installed capacity. Floor mats is rotating up the share rankings.
Material:
Application-specific performance requirements drive material selection across durability, acoustic, and weight targets.
- Polyurethane Foam:Open-cell and closed-cell formulations provide tunable sound absorption coefficients for NVH engineering. China's Yangtze River Delta automotive corridor is localizing supply chains for low-VOC foam backings compliant with MIIT dual carbon goals.
- Nylon:High-tenacity polyamide 6 and 6,6 fibers deliver abrasion resistance for high-traffic footwell zones. REACH chemical restrictions are forcing reformulation of halogenated flame retardants in European-bound nylon carpet systems.
- Polyester:Recycled PET staple fibers are gaining regulatory preference under EU Green Deal circular economy mandates.
- Polypropylene:Lower-cost olefin fibers serve economy vehicle programs with adequate wear performance.
- Rubber:Natural and synthetic latex backings provide moisture barrier and dimensional stability.
- PVC:Phthalate-plasticized vinyl backings face substitution pressure from bio-based alternatives.
Polyurethane foam commands specification authority in premium platforms. Recycled polyester is climbing the fastest.
Application:
Vehicle class determines material weight, durability standards, and acoustic investment intensity.
- Passenger Vehicles:Light-duty specifications prioritize weight reduction and cabin refinement over commercial-grade durability. Thailand's expanding thermoforming capacity serves Japanese OEM ASEAN production bases for molded carpet assemblies.
- Commercial Vehicles:Heavy-duty nylon constructions with reinforced backings sustain higher per-vehicle material weights and extended service life requirements. Fleet operators in the US specify replaceable wear layers to minimize total cost of ownership.
- Off-road Vehicles:Moisture-resistant rubber-backed systems with drainage channels address mud and water ingress.
- Specialty Vehicles:Custom acoustic and fire-retardant specifications serve ambulance, limousine, and armored vehicle conversions.
Passenger vehicles anchor production volume. Commercial vehicles is gaining specification complexity.
Customer Type:
Procurement channel structure shapes pricing transparency, contract duration, and technical collaboration depth.
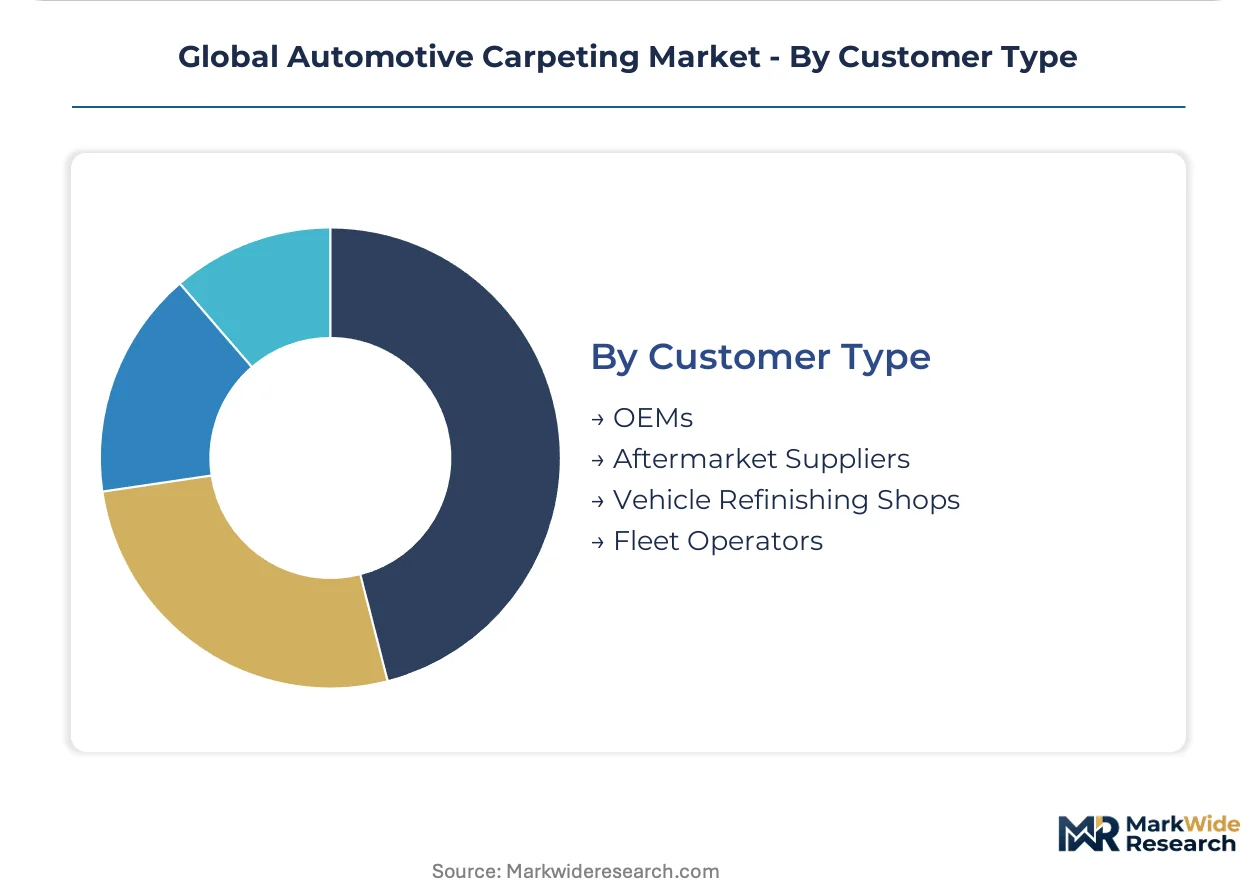
- OEMs:Platform-level supply agreements with fixed pricing bands are displacing annual spot negotiations. SAIC, Geely, and NIO in China's Yangtze River Delta have centralized interior sourcing decisions for high-volume carpet assemblies.
- Aftermarket Suppliers:Catalog-driven demand for replacement floor mats and trunk liners operates on shorter lead times and lower technical barriers.
- Fleet Operators:Volume procurement of standardized wear components emphasizes total lifecycle cost over initial acquisition price.
- Vehicle Refinishing Shops:Small-batch custom interiors for restoration and premium upgrade segments capture artisan pricing premiums.
OEMs concentrate specification authority. Aftermarket suppliers is fragmenting across digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs prioritize acoustic-optimized systems for electric platforms, while Chinese manufacturers emphasize localized supply chains for cost control. Japanese producers anchor relationships through dedicated design centers. The United States sustains demand through fleet replacement cycles and regulatory compliance mandates.
United States
Fleet operators drive replacement demand for heavy-duty commercial vehicle carpeting with extended service life specifications. EPA fuel economy standards and NHTSA safety regulations mandate flammability resistance and pedal interference testing that shape substrate selection. Manufacturing concentrates in the Midwest automotive corridor serving Detroit-based OEM platform architectures.
Germany
Electric vehicle manufacturers expand orders for lightweight interior materials as EU Green Deal mandates tighten CO2 fleet targets. ECHA REACH authorization requirements for flame retardants and plasticizers compel systematic substitution of halogenated chemistries. Stuttgart and Munich anchor premium electric vehicle program development with tuned resonant cavity acoustic designs.
China
Domestic OEMs localize supply chains for interior components under MIIT dual carbon goals and GB standards for interior air quality. Reformulation of adhesives and foam backings forces technical staff retraining across manufacturing facilities. The Yangtze River Delta automotive cluster concentrates SAIC, Geely, and NIO centralized interior sourcing decisions.
Japan
Toyota Boshoku anchors OEM relationships through dedicated design centers in Aichi Prefecture supporting platform-level integration. METI industrial policy emphasizes domestic supply chain resilience for critical automotive components. Kyushu and Kansai regions host specialized needle-punched fabric production for hybrid and electric vehicle programs.
Thailand
Southeast Asian suppliers add thermoforming capacity for molded carpet assemblies serving Japanese OEM ASEAN production base expansion. Regional trade integration under RCEP reduces tariff exposure for cross-border component shipments. Eastern Economic Corridor industrial zones attract Tier 1 supplier co-location with final assembly operations.
Global Automotive Carpeting Market Key Industry Players
Capability concentration sits with acoustic engineering specialists; scale advantage sits with diversified Tier 1 interior systems integrators. The vendor base stratifies across three tiers: global platform suppliers with OEM co-development relationships, regional specialists with thermoforming expertise, and commodity producers serving aftermarket channels. Dominant competitive moves include backward integration into resin compounding and geographic expansion through ASEAN manufacturing bases.
Among diversified interior systems integrators, Lear Corporation and Adient plc exemplify scale-driven platform suppliers with OEM co-development relationships. Autoneum Holding AG occupies a specialist position in acoustic-optimized carpet systems. Toyota Boshoku Corporation anchors Japanese OEM relationships through dedicated design center proximity. These three represent distinct archetypes: diversified global integrator, acoustic engineering specialist, and regionally anchored relationship supplier.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient plc |
| Magna International Inc. |
| Autoneum Holding AG |
| Toyota Boshoku Corporation |
| Faurecia |
| IAC Group |
| Freudenberg Performance Materials |
| Hyosung |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility in nylon and polypropylene resin markets compresses margin predictability for synthetic fiber feedstock-dependent producers while simultaneously widening spreads between premium acoustic-optimized systems and commodity floor protection tiers. This feedstock uncertainty forces tiered pricing stratification across certification-grade polyurethane foam backings, recycled PET validation status, and regional manufacturing footprint advantages.
Pricing Analysis
Price differentiation between German electric vehicle acoustic systems and Indian aftermarket floor mats spans three performance tiers anchored by NVH engineering intensity, REACH-compliant chemistry certification, and volume-scale contract structures. OEM platform agreements with Lear Corporation and Autoneum command premium positioning through tuned resonant cavity designs, while Yangtze River Delta suppliers compete on cost for standardized needle-punched assemblies. Cost compression in economy vehicle segments intensifies as domestic Chinese OEMs centralize procurement authority under MIIT dual carbon compliance timelines. Fleet operators exhibit highest price sensitivity through total lifecycle cost calculations, whereas premium electric vehicle programs prioritize acoustic performance over unit economics.
Supply Chain Analysis
Upstream nylon and polypropylene resin production draws from petrochemical complexes in Germany, China, and the United States, with polyurethane foam precursor supply anchored in the Yangtze River Delta and Aichi Prefecture manufacturing corridors. Finished carpet assembly concentrates in Thailand's Eastern Economic Corridor, Mexico's Bajío automotive cluster, and the US Midwest serving Detroit-based OEM platform architectures. Single-source vulnerability in halogenated flame retardant chemistries under REACH authorization timelines creates regulatory chokepoint exposure for European-bound shipments. Distribution runs through Tier 1 supplier direct-to-OEM channels with just-in-time sequencing, supplemented by aftermarket catalog fulfillment through India's NCR and Maharashtra distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform architectures eliminate engine masking noise, creating a high-growth disruption where acoustic engineering capabilities capture expanding value pools as cabin NVH requirements intensify across premium segments.
For Market Incumbents: Entrench acoustic engineering specialization through backward integration into polyurethane foam compounding and resonant cavity simulation software deployment. Lear Corporation and Autoneum must defend against emerging Asian thermoforming specialists by locking German OEM platform agreements before ASEAN capacity ramps. Certification investment in ECHA REACH-compliant halogen-free chemistry tracks preserves European market access against reformulation-disrupted competitors. For New Entrants and Emerging Players: Pursue white-space capture in Thailand's Eastern Economic Corridor thermoforming capacity expansion serving Japanese OEM ASEAN production bases. India's aftermarket floor mat replacement demand offers lowest technical barriers with UV degradation resistance specifications as the penetrable entry point. Direct sourcing relationships with Yangtze River Delta domestic OEMs bypass established Tier 1 incumbents through MIIT dual carbon-aligned recycled PET validation programs. For Investors and Strategic Acquirers: EU Green Deal circular economy mandates reshape the acquisition landscape toward suppliers with validated post-consumer fiber supply chains and low-VOC adhesive chemistry portfolios. Long-term viability over the next decade hinges on electric vehicle platform penetration rates and acoustic content per vehicle expansion. Acquisition target archetype: mid-cap acoustic specialists with German OEM co-development relationships and ASEAN manufacturing optionality. Watch ECHA substance evaluation timelines for flame retardant authorization delays as the signal forcing accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive nylon and polyurethane supply secures margin control against crude oil volatility. |
| ASEAN Thermoforming Capacity Buildout | Thailand Eastern Economic Corridor positioning captures Japanese OEM regional expansion. |
| REACH-Compliant Chemistry Transition | Halogen-free adhesive validation preserves European premium electric vehicle program access. |
| Recycled PET Supply Chain Certification | Post-consumer fiber verification unlocks EU Green Deal procurement preference scoring. |
| Acoustic Simulation Software Deployment | Digital mold flow prediction compresses German OEM platform development cycles. |
Research Approach
Desk research of vehicle production databases, IHS Markit registration data, customs trade flows, and SEC Tier 1 supplier filings preceded structured interviews with OEM platform engineers, Tier 1 procurement directors, aftermarket distributors, and dealership operations managers. Primary fieldwork captured specification authority shifts, contract structure evolution, and chemistry reformulation timelines across Germany, China, Japan, Thailand, and the United States. Secondary validation drew from ECHA substance evaluation notices, MIIT dual carbon policy releases, and EPA fuel economy regulatory filings. Bottom-up segment sizing triangulated against top-down macro automotive production forecasts.
Assumptions held fixed include EU Green Deal CO2 fleet target enforcement intensity, REACH authorization timelines for halogenated flame retardants, and MIIT dual carbon goal implementation pace across the Yangtze River Delta. Variables modeled encompass electric vehicle platform penetration by vehicle class, acoustic content per vehicle by propulsion architecture, and regional production cluster growth rates across the projection horizon. CAGRs derived from regression analysis of historical material intensity trends, weighted by OEM platform launch schedules and regulatory compliance deadlines. Industry-specific inputs included NVH engineering specification evolution and recycled content certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, automotive production volumes, or currency exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption pacing. Material shifts in ECHA REACH authorization delays, EU Green Deal circular economy mandate acceleration, or electric vehicle platform architecture standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market