
 Automotive Leather Upholstery Market | 2026-2036
Automotive Leather Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Leather Upholstery Market Analysis
A capital-intensity divergence between fully integrated tanneries and cut-and-seat assemblers is redrawing competitive boundaries in automotive leather upholstery. Lear Corporation leverages captive finishing operations across multiple continents to sustain margin control on high-volume OEM programs. Adient plc anchors its position through dedicated seating architectures that integrate leather procurement directly into module design. Eagle Ottawa specializes in premium full-hide applications for luxury nameplates, occupying a niche where brand heritage commands procurement priority.
Automotive leather upholstery encompasses treated animal hides and engineered polymer surfaces applied to vehicle interior surfaces, typically specified for abrasion resistance exceeding 100,000 Martindale cycles and VOC emissions below 50 micrograms per cubic meter. Its primary purpose is to deliver tactile quality, durability, and cabin air quality compliance in passenger and commercial vehicles. Synthetic leather formulations are expanding fastest among battery-electric platforms seeking weight reduction and thermal management advantages over natural hides. OEM direct procurement channels concentrate the largest value pools, though aftermarket custom builders represent a growing margin segment for specialized finishing and personalized embossing.
REACH restrictions on chromium VI compounds and the EU Green Deal's embodied-carbon tracking requirements are forcing tanneries to certify wet-white processing alternatives or risk exclusion from European OEM supply bases. EPA VOC regulations in the United States and China's GB standards for interior air quality impose parallel compliance costs that favor suppliers with cross-certified laboratory networks. Stakeholders must monitor how OEM sustainability scorecards recalibrate leather sourcing criteria before committing to long-term hide procurement contracts or synthetic capacity expansions.
Market Dynamics
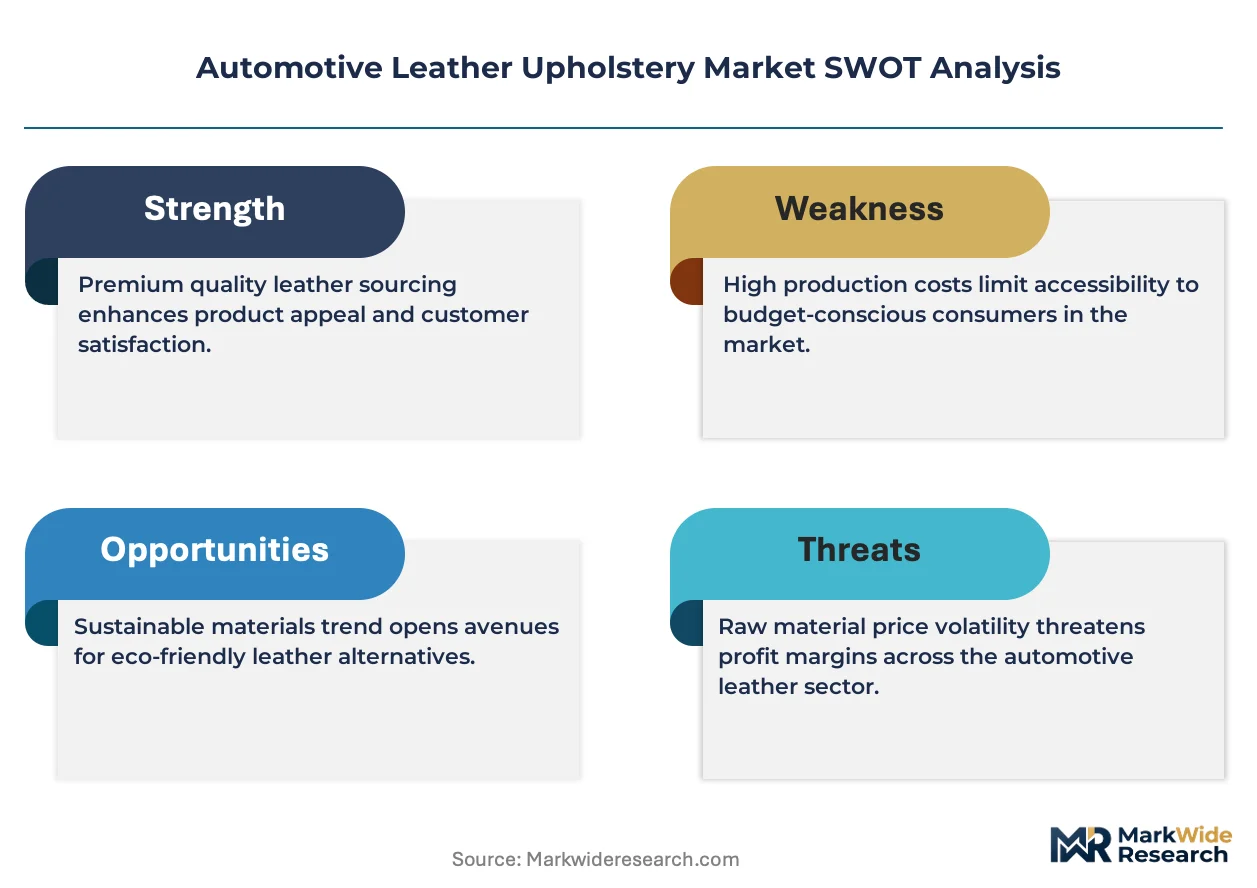
Chrome-free wet-white tanning technology is forcing capital reallocation across tannery operations as REACH and EU Green Deal compliance deadlines eliminate chromium VI from European OEM supply chains. This single technical mandate is compressing legacy processors while rewarding early adopters with locked-in procurement relationships.
Growth Catalysts
- REACH Phase-Out Deadlines:ECHA restrictions on chromium VI compounds are compelling tanneries to certify alternative processing methods or forfeit access to German and Italian luxury OEM programs.
- Battery-Electric Vehicle Expansion:Premium EV nameplates specify leather-trimmed cabins as tactile differentiation against synthetic-heavy mass-market competitors, concentrating demand in high-margin hide grades.
- GB Standards Alignment:China's interior air quality regulations are accelerating wet-white adoption among export-oriented tanneries serving joint-venture OEM assembly plants.
Market Restraints
- Hide Supply Volatility:Cattle herd fluctuations in Brazil and Argentina generate raw material price instability that compresses tannery margins during contract renegotiations with seat assemblers.
- Processing Capital Intensity:Wet-white line conversions require seven-figure equipment outlays that exclude smaller Italian and Indian tanneries from European OEM qualification.
- Polyurethane Substitution:Advanced microfiber synthetics from Japanese and Korean chemical suppliers capture volume in cost-sensitive compact vehicle segments.
Strategic Opportunities
- Indian Domestic OEM Expansion:Maruti Suzuki and Tata Motors are localizing leather-trimmed variants for upper-middle-class buyers, creating first-mover advantage for tanneries with BIS-certified finishing.
- Aftermarket Customization Channels:Specialized embossing and personalized color-matching services for classic vehicle restoration bypass OEM pricing pressure.
- Carbon Accounting Integration:EU Green Deal embodied-carbon tracking requirements favor suppliers with lifecycle-certified processing, enabling premium positioning against uncertified competitors.
Industry Challenges
- Cross-Certification Complexity:Tanneries must maintain parallel laboratory accreditations for EPA VOC, REACH, and GB standards simultaneously, stretching technical staff capacity.
- Finishing Talent Scarcity:Experienced technicians capable of color-matching across chrome-free and chrome-tanned batches command compensation premiums that inflate operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Leather Upholstery Market |
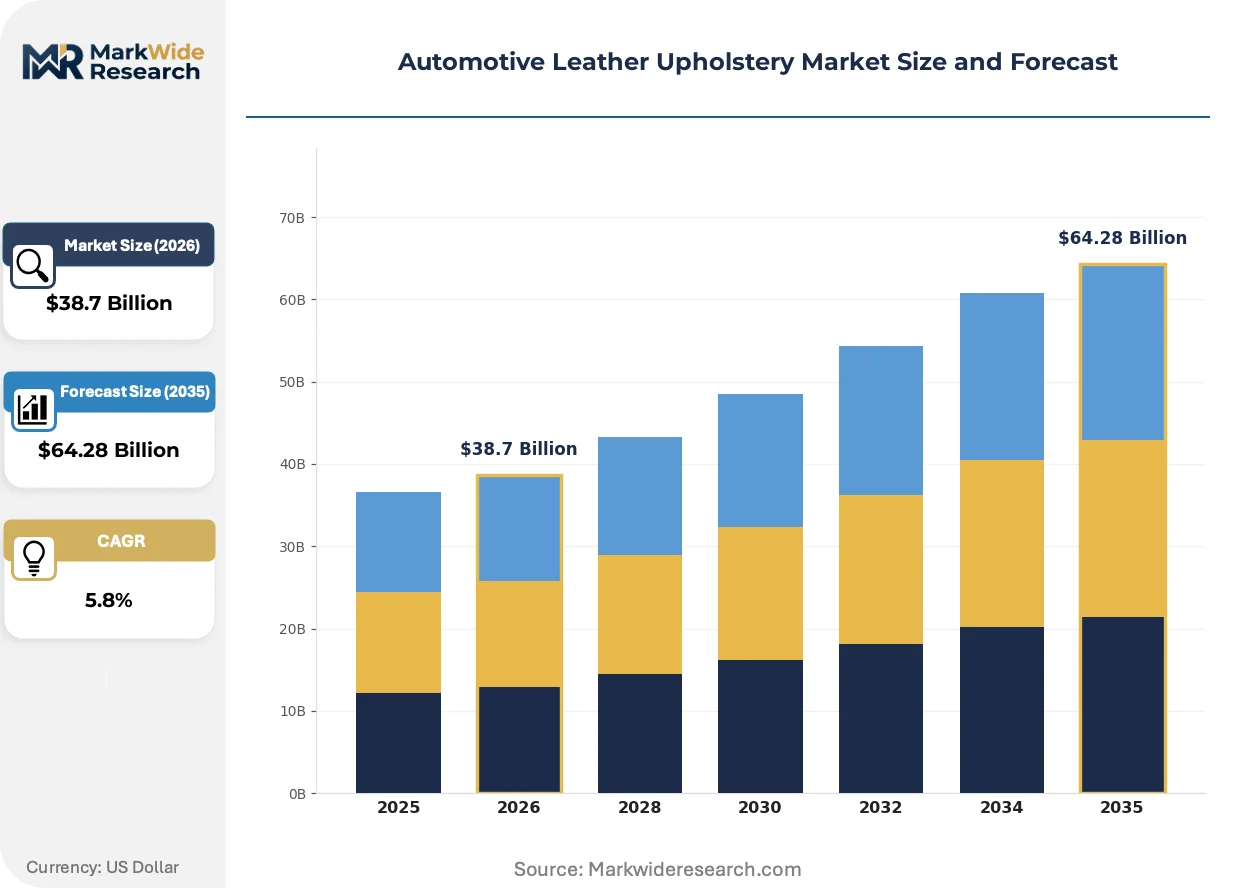
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Leather, Synthetic Leather, Artificial Leather, Suede Application: Seats, Steering Wheels, Door Panels, Consoles Customer Type: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Custom Builders Manufacturing Stage: Raw Material Procurement, Processing, Finishing, Assembly |
| Companies Covered | GST Autoleather Inc, Forvia SE, Adient plc, BASF SE, Katzkin Leather Inc, Lear Corporation, Eagle Ottawa, Seiren Co. Ltd, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Leather Upholstery Market Emerging Trajectories
Processing chemistry, regulatory tracking architecture, and procurement specifications are converging to redefine competitive advantage in automotive leather supply. Technical differentiation now hinges on certification breadth rather than traditional craftsmanship metrics.
Silicone-coated microfiber formulations are supplanting conventional polyurethane synthetics in luxury EV cabin programs. NIO and Lucid Motors specify these materials for thermal stability during rapid charging cycles. The shift is compressing demand for mid-grade natural hides in vehicles below premium price thresholds.
EU Green Deal carbon border adjustments are forcing tanneries to document Scope 3 emissions from raw hide sourcing through finished leather delivery. German OEM sustainability scorecards now weight embodied carbon at fifteen percent of total supplier rating. Argentine and Uruguayan processors with verified grassland management certifications are capturing preferential sourcing status.
Direct OEM-tannery contracting is displacing traditional hide merchant intermediaries in high-volume programs. BMW and Mercedes-Benz now specify leather grades at the wet-blue stage, bypassing commodity traders. This pattern concentrates most visibly in Bavaria and Stuttgart, where development engineers co-locate with tannery technical teams for color and grain matching.
Automotive Leather Upholstery Market Segmentation
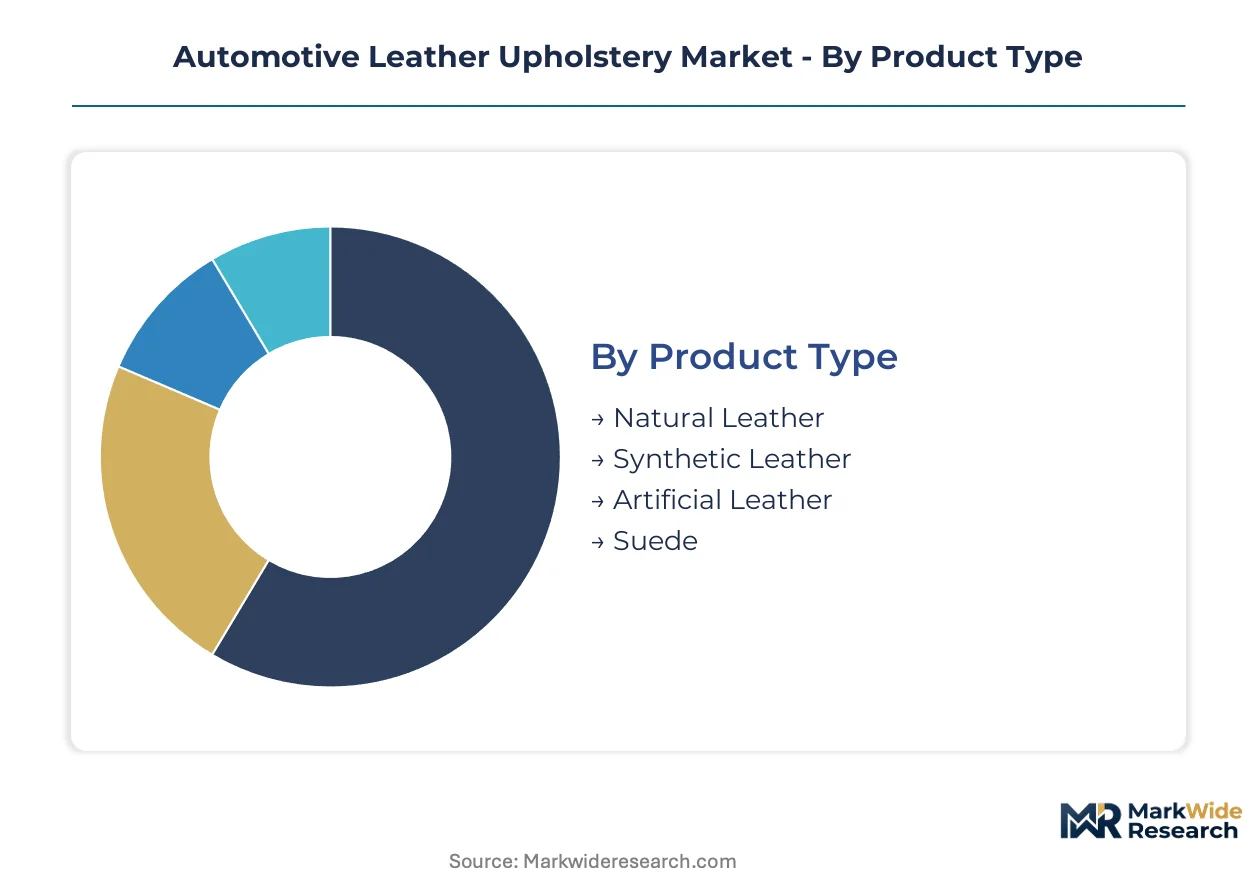
Automotive leather upholstery segments reflect divergent supply chain pressures across natural and synthetic material streams. OEM procurement patterns and regulatory compliance thresholds fragment the market into distinct technical and commercial categories.
Product Type:
Natural leather dominates European domestic programs, while synthetic formulations capture export-led volume into Asia-Pacific assembly plants.
- Natural Leather:Chrome-tanned and wet-white processed hides deliver abrasion resistance exceeding 100,000 Martindale cycles for luxury seating applications. German OEM development centers in Bavaria specify full-grain grades for flagship sedan programs, though REACH Phase-Out deadlines are compressing chrome-dependent supply sources.
- Synthetic Leather:Silicone-coated microfiber and advanced polyurethane formulations reduce cabin thermal load during battery-electric vehicle rapid charging cycles. NIO and Lucid Motors specify these materials for thermal stability, displacing mid-grade natural hides in premium EV configurations below heritage luxury price thresholds.
- Artificial Leather:PVC-based and early-generation polyurethane surfaces serve cost-sensitive compact vehicle segments in emerging markets.
- Suede:Alcantara and similar microfiber suedes accent headliners and steering wheel grips in sport-trim variants.
Natural leather commands the established base. The steepest expansion runs through synthetic leather.
Application:
Seat programs concentrate the highest value per vehicle, while steering wheel and console applications follow distinct finishing specifications.
- Seats:Full-hide upholstery and precision-cut panels require color-matching across chrome-free and chrome-tanned batches. Lear Corporation and Adient plc integrate leather procurement directly into seating module architecture, locking in multi-year supply agreements.
- Steering Wheels:Wrapped leather surfaces demand enhanced grip texture and sweat resistance specifications. Italian tanneries with automotive certification dominate this niche through co-located technical teams in Stuttgart.
- Door Panels:Accent inserts and armrest surfaces balance tactile quality against assembly-line handling durability.
- Consoles:Center stack and armrest coverings prioritize abrasion resistance in high-contact zones.
Seats absorb the dominant share of leather procurement value. Console applications are climbing fastest as EV platforms expand storage and interface surface area.
Customer Type:
OEM direct contracting is displacing traditional hide merchant intermediaries in high-volume programs.
- OEMs:BMW and Mercedes-Benz now specify leather grades at the wet-blue stage, bypassing commodity traders. This pattern concentrates in Bavaria and Stuttgart, where development engineers co-locate with tannery technical teams.
- Aftermarket Suppliers:Specialized embossing and personalized color-matching services for classic vehicle restoration bypass OEM pricing pressure.
- Vehicle Assemblers:Joint-venture plants in China source through GB-certified tanneries with cross-aligned REACH documentation.
- Custom Builders:Low-volume specialty manufacturers commission bespoke finishing for limited-production nameplates.
OEMs anchor procurement volume. Aftermarket channels are expanding most quickly as classic restoration and personalization demand accelerates.
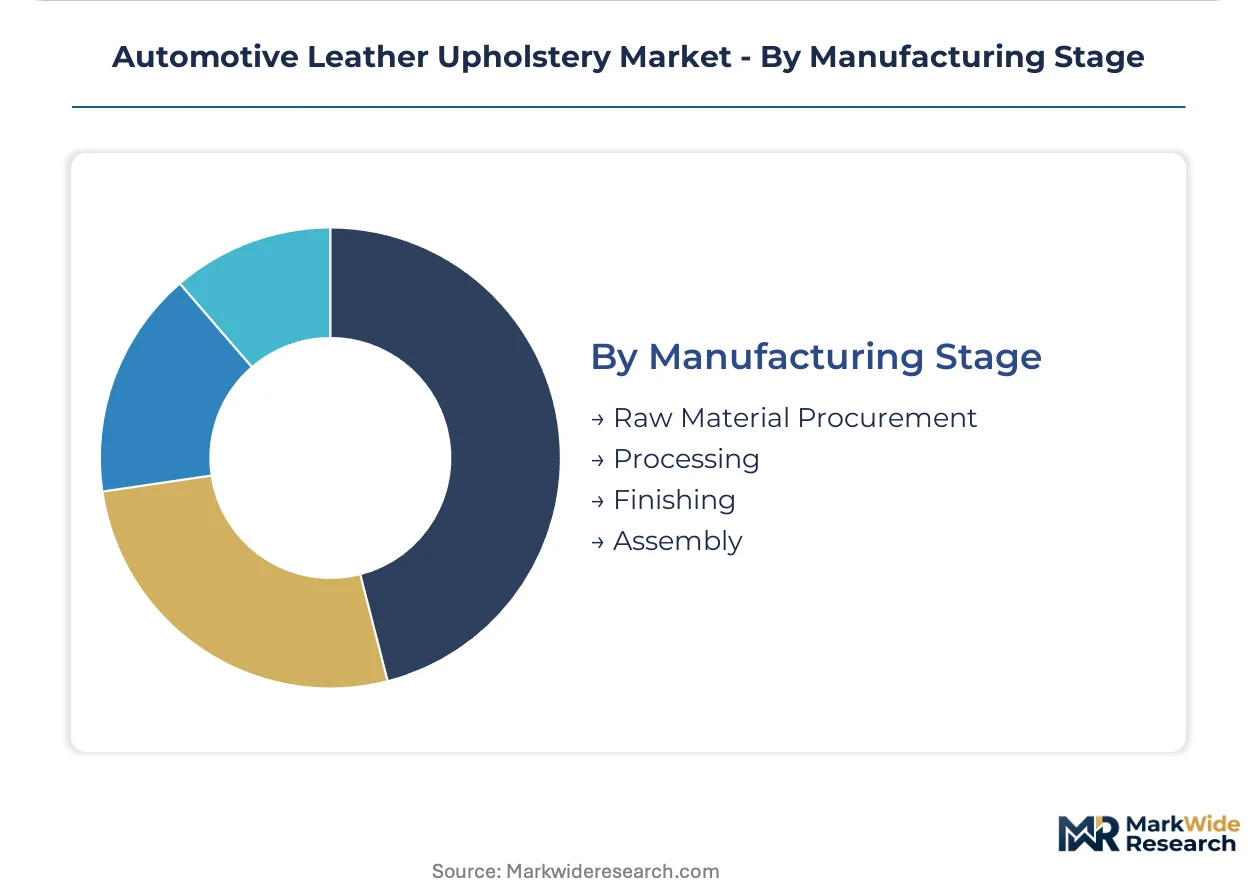
Manufacturing Stage:
Processing and finishing stages concentrate margin capture, while raw material procurement faces hide supply volatility.
- Raw Material Procurement:Cattle herd fluctuations in Brazil and Argentina generate price instability that compresses tannery margins during contract renegotiations.
- Processing:Wet-white line conversions require seven-figure equipment outlays that exclude smaller Italian and Indian tanneries from European OEM qualification.
- Finishing:Experienced technicians capable of color-matching across processing methods command compensation premiums that inflate operating costs.
- Assembly:Cut-and-seat operations integrate finished leather into seating modules and interior trim components.
Processing commands the highest technical barrier. Finishing is gaining share fastest as sustainability scorecards weight embodied carbon and certification breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM specification power commands premium hide pricing, while Brazilian raw material volatility compresses tannery margins in South America. This asymmetry redirects investment toward European finishing capacity and certified wet-white processing hubs.
Germany
Luxury OEM development centers in Bavaria and Stuttgart specify full-grain leather grades at the wet-blue stage, bypassing traditional commodity traders. REACH Phase-Out deadlines enforced by ECHA accelerate chrome-free wet-white adoption among supplier tanneries. Technical teams from Lear Corporation and Eagle Ottawa co-locate with BMW and Mercedes-Benz engineers for real-time color matching.
United States
EPA VOC regulations and NHTSA safety standards shape leather procurement for domestic pickup and SUV programs. The Inflation Reduction Act incentivizes domestic manufacturing investment among seat assemblers serving Detroit Three OEMs. Michigan and Ohio host concentrated cut-and-seat operations that integrate finished leather directly into seating module architecture.
China
GB standards for interior air quality accelerate wet-white adoption among export-oriented tanneries serving joint-venture assembly plants. NMPA and MIIT oversight extends to material certification for premium EV nameplates from NIO and BYD. Yangtze River Delta tanneries with cross-aligned REACH documentation capture preferential sourcing status from German OEM local production.
India
Maruti Suzuki and Tata Motors localize leather-trimmed variants for upper-middle-class buyers, creating demand for BIS-certified finishing capacity. PLI scheme incentives support domestic tannery modernization toward chrome-free processing compliance. Tamil Nadu and Gujarat industrial corridors attract seat assembler investment from Adient plc and Toyota Boshoku Corporation.
Brazil
Cattle herd fluctuations generate raw material price instability that compresses tannery margins during contract renegotiations with export markets. ANVISA oversight parallels EPA VOC thresholds for leather destined to North American OEM supply chains. São Paulo and Minas Gerais processing centers face capital constraints that exclude smaller operators from European qualification programs.
Automotive Leather Upholstery Market Vendor Landscape
Concentration sits with fully integrated seating suppliers that control captive finishing operations across multiple continents. The vendor base stratifies into three tiers: global seat assemblers with in-house leather procurement, specialized tanneries serving luxury nameplates, and regional cut-and-seat operators. Dominant competitive moves include backward integration into wet-white processing and strategic partnerships for carbon-accounting certification.
Within the integrated seating tier, Lear Corporation and Adient plc exemplify archetypes that embed leather sourcing directly into module design architecture. Eagle Ottawa occupies a position representing heritage-focused specialists in premium full-hide applications. Among chemical suppliers, BASF SE anchors the materials-science vector that enables silicone-coated microfiber formulations displacing conventional synthetics.
| Leading Market Players |
|---|
| GST Autoleather Inc |
| Forvia SE |
| Adient plc |
| BASF SE |
| Katzkin Leather Inc |
| Lear Corporation |
| Eagle Ottawa |
| Seiren Co. Ltd |
| Toyota Boshoku Corporation |
| Others |
Supply Flow & Price Mechanics
REACH Phase-Out deadlines on chromium VI compounds gate both supplier qualification and price differentiation simultaneously, compressing chrome-dependent tanneries into commodity tiers while rewarding wet-white certified processors with premium positioning in German OEM programs.
Pricing Analysis
Configured-to-order pricing for bespoke embossing and personalized color-matching commands substantial premiums over standard program pricing for volume OEM contracts. Three-tier pricing structure across premium full-grain, standard corrected-grain, and economy split-hide levels stratifies the market, with certification grade and volume scale as primary differentiation drivers. Cost compression in mid-grade natural hides is intensifying because silicone-coated microfiber formulations from Japanese chemical suppliers capture thermal-management specifications in battery-electric vehicle cabins. Aftermarket custom builders exhibit lowest price sensitivity, while compact vehicle assemblers serving emerging markets face acute procurement pressure.
Supply Chain Analysis
Inventory cycles for wet-blue hides stretch lead times to sixteen weeks, forcing seat assemblers to pre-position finished leather stock near OEM assembly plants. Raw material supply concentrates in Brazil, Argentina, and Uruguay for cattle hides, while processing capacity clusters in Germany, Italy, and China's Yangtze River Delta. The supply chain draws from chromium-free tanning chemicals, full-grain hide selections, and silicone microfiber substrates, with commodity price volatility in cattle herds presenting persistent margin risk. Distribution runs through direct OEM-tannery contracting that displaces traditional hide merchant intermediaries in high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chrome-free wet-white tanning technology is disrupting established competitive positions, with regulatory compliance deadlines compressing legacy processors while creating first-mover advantages for certified suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into captive wet-blue processing capacity in Bavaria and Stuttgart, where BMW and Mercedes-Benz engineers co-locate for real-time color matching. Lock in multi-year supply agreements with seat assemblers before REACH Phase-Out deadlines eliminate chrome-dependent competitors from European qualification. Prioritize carbon-accounting certification to capture premium positioning under EU Green Deal embodied-carbon tracking requirements. For New Entrants and Emerging Players: ECHA fast-track certification for chrome-free processing offers entry pathway into German luxury OEM supply chains previously closed to uncertified tanneries. Target aftermarket customization channels for classic vehicle restoration, where specialized embossing services bypass OEM pricing pressure and command margin premiums. Pursue joint-venture partnerships with Yangtze River Delta tanneries holding cross-aligned REACH documentation to serve export-oriented assembly plants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wet-white processing equipment, excluding smaller Italian and Indian operators from European OEM qualification and creating consolidation targets. Focus acquisition screening on mid-cap tanneries with verified grassland management certifications from Argentine or Uruguayan raw material sources, positioned for preferential sourcing under sustainability scorecards. Monitor German OEM procurement team expansion as signal of direct contracting acceleration and intermediary displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Wet-White Processing Certification | ECHA compliance locks in German OEM supply relationships before Phase-Out deadlines eliminate competitors. |
| Carbon-Accounting Integration | EU Green Deal tracking requirements favor lifecycle-certified suppliers with fifteen percent scorecard weighting. |
| Direct OEM-Tannery Contracting | BMW and Mercedes-Benz wet-blue specification bypasses commodity traders, concentrating value capture. |
| Aftermarket Customization Channel Development | Specialized embossing services for classic restoration bypass OEM pricing pressure with margin premiums. |
| Joint-Venture Processing Hubs | China's Yangtze River Delta tanneries with REACH alignment capture preferential sourcing from German OEM local production. |
Methodological Framework
The analysis maps natural leather, synthetic leather, and suede sub-sectors, each validated through procurement directors at Tier 1 seat assemblers, tannery technical managers, and OEM platform engineers across Germany, China, and the United States. Primary interviews with Lear Corporation and Adient plc supply chain executives, Eagle Ottawa finishing specialists, and BASF SE materials scientists combined with secondary validation from EPA VOC filings, ECHA REACH registrations, and GB standards documentation. Bottom-up hide procurement volume estimates and top-down OEM seating program values underwent cross-triangulation against vehicle production databases.
Consistency checks validated segment outputs against IHS Markit registration data and customs records for finished leather trade flows across the analysis window. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis of historical OEM specification trends and projected battery-electric vehicle penetration rates, with leather grade mix and sustainability certification adoption as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained German luxury OEM demand or accelerated silicone microfiber substitution would require recalibration. Forecasts reflect documented assumptions regarding REACH enforcement timelines and cattle herd stability in South America. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market