
 Mexico Automotive OEM Coatings Market | 2026-2036
Mexico Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive OEM Coatings Market Outlook
Aftermarket service revenue is tilting toward captive OEM touch-up and warranty repair programs. PPG Industries leverages its Guadalajara technical center to sustain color-matching dominance across Mexican assembly plants. Axalta Coating Systems anchors volume supply through direct pipeline connections to Volkswagen and Nissan facilities in Puebla. BASF SE differentiates via integrated electrocoat-primer-base coat systems that reduce line complexity for vehicle manufacturers.
Mexico Automotive OEM Coatings are liquid or powder-applied protective and decorative layers, typically formulated with polyurethane, epoxy, or acrylic resin binders and cured at temperatures between 120°C and 160°C, designed to prevent corrosion, enhance appearance, and extend vehicle body life in assembly-line conditions. The primary commercial purpose is to provide durable, color-stable surface protection that meets manufacturer warranty terms and regulatory emission limits during high-speed production. Clear coat and base coat formulations together command the dominant value share, as OEMs prioritize scratch resistance and color depth in premium passenger vehicle segments. Electric vehicle applications represent the fastest-growing coating demand category, driven by specialized dielectric properties and lightweight substrate compatibility requirements.
SEMARNAT administers NOM-085-SEMARNAT-2011 volatile organic compound limits that constrain solvent-borne coating formulations in Mexican automotive plants. PROFEPA conducts facility inspections that enforce environmental compliance and influence supplier qualification decisions by OEMs. The Secretariat of Economy coordinates with NOM certification bodies to align Mexican automotive standards with USMCA technical requirements. Stakeholders must monitor whether pending updates to Mexican environmental regulations will accelerate waterborne conversion timelines beyond current plant retooling schedules.
Market Dynamics
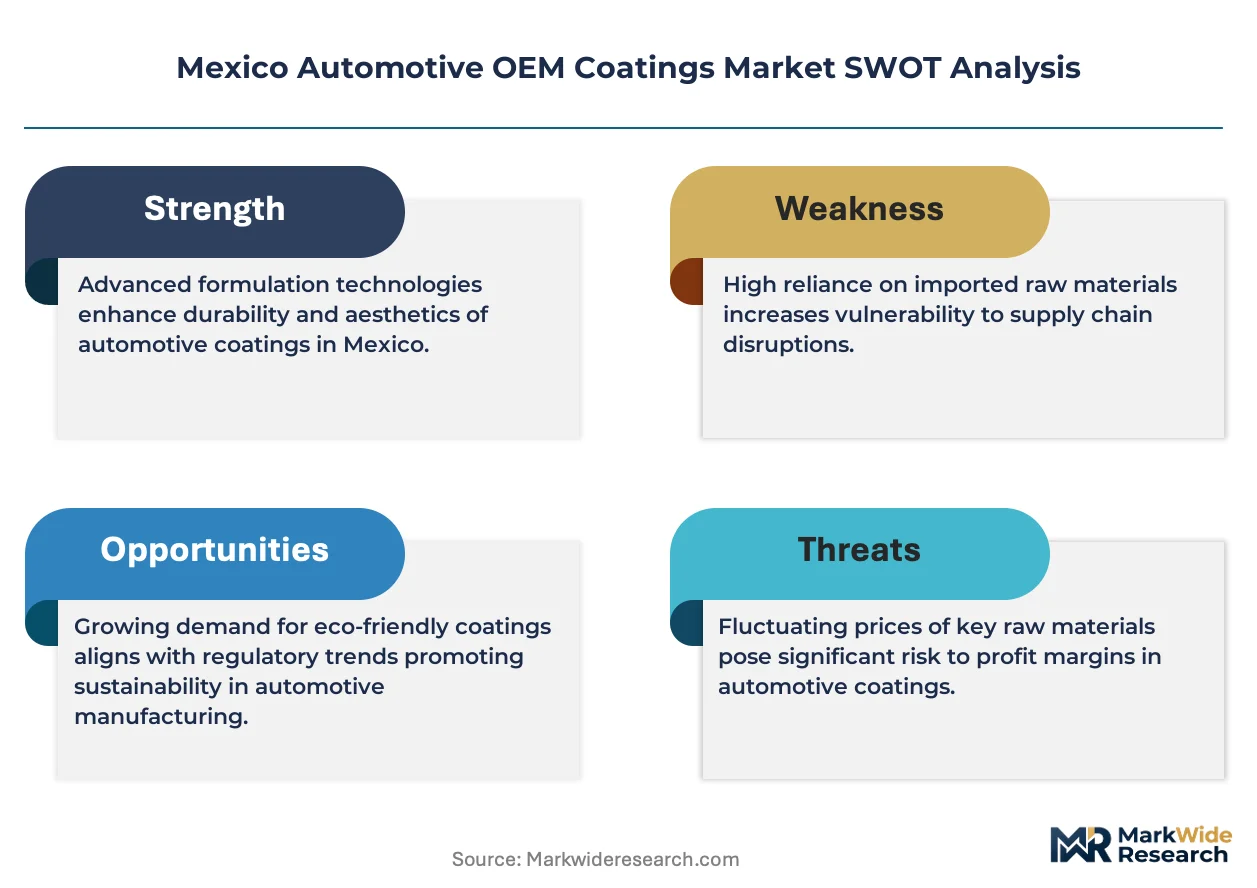
PROFEPA's enforcement of NOM-085-SEMARNAT-2011 is compressing solvent-borne coating cycles across Mexican assembly plants and forcing accelerated waterborne conversion timelines that outpace current capital allocation schedules in the Bajío cluster.
Growth Catalysts
- USMCA rules of origin:North American content requirements sustain high-volume vehicle production in Mexican export corridors, maintaining coating demand density across Puebla and Guanajuato assembly corridors.
- Dielectric coating specifications:Battery enclosure protection standards for electric vehicles require specialized base coat formulations with thermal management properties, opening technical specification windows for advanced material suppliers.
- Bajío automotive cluster expansion:Volkswagen, Nissan, and BMW facility concentration around Silao-Irapuato-Celaya creates localized demand pull for just-in-time coating supply infrastructure.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs fluctuate with Gulf Coast propylene pricing, compressing formulation margins for domestic coating producers without backward integration into raw material supply.
- Waterborne curing energy intensity:Extended bake cycles for low-VOC formulations increase natural gas consumption per vehicle, raising operating costs at PROFEPA-monitored facilities during NOM-085 compliance transitions.
- Capital equipment lock-in:Existing electrocoat and spray booth infrastructure designed for solvent-borne systems requires complete retooling for waterborne compatibility, extending payback periods beyond typical automotive program lifecycles.
Strategic Opportunities
- Querétaro aerospace coating cross-application:Durability specifications developed for aircraft exterior protection transfer to premium electric vehicle clear coat segments, leveraging existing technical centers in central Mexico.
- SEMARNAT green credit incentives:Pending environmental compliance certification programs would accelerate waterborne adoption through tax-advantaged capital expenditure treatment for coating line upgrades.
- Integrated primer-base coat systems:Single-application film build technologies reduce booth footprint and VOC capture requirements, aligning with Bajío plant space constraints and PROFEPA emission budgets.
Industry Challenges
- Color-matching technician scarcity:Spectrophotometry and computerized tinting system operation requires specialized training unavailable in Guanajuato and Puebla technical institutes, constraining OEM touch-up program expansion.
- NOM certification timeline compression:SEMARNAT approval cycles for reformulated waterborne products lag behind vehicle launch schedules, forcing parallel regulatory submissions that increase compliance overhead.
- Legacy inventory synchronization:Solvent-borne stockpiles must deplete during waterborne line conversions without disrupting assembly plant supply continuity, requiring precise transition choreography with OEM procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive OEM Coatings Market |
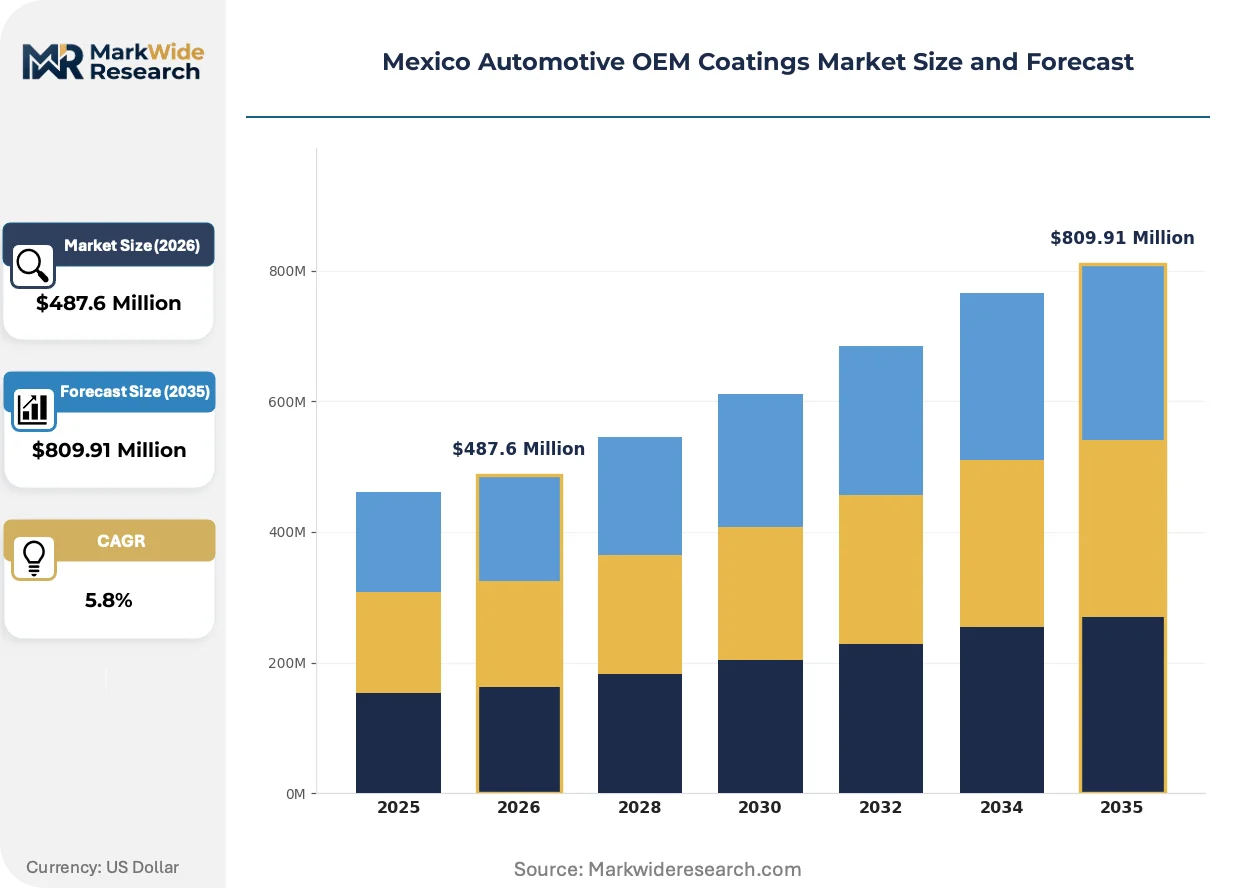
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Clear Coat, Primer, Specialty Coatings Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Sports Cars Delivery Mode: Bulk, Small Packs, On-Site Mixing, Pre-Mixed End User: Vehicle Manufacturers, Parts Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | PPG Industries, Henkel AG & Co KGaA, Akzo Nobel N V, Jotun, Nippon Paint Holdings Co Ltd, Axalta Coating Systems, The Sherwin-Williams Company, Sika AG, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive OEM Coatings Market Strategic Shifts
Coating chemistry and application technology are converging around sustainability mandates and electric vehicle substrate requirements, with Mexican assembly plants serving as testbeds for next-generation film build specifications.
UV-curable clear coat technology is hybridizing with conventional thermal cure systems to reduce energy consumption in base coat-clear coat sequences. BMW's San Luis Potosí facility pilots hybrid cure lines that cut bake oven dwell time by forty percent. This convergence is compressing total applied cost per vehicle while maintaining scratch resistance warranties.
NOM-085-SEMARNAT-2011 amendment discussions at SEMARNAT are tightening VOC mass limits for automotive topcoats beyond current waterborne baselines. Formulation houses must recalibrate resin solids content and solvent blends to maintain compliance. The Puebla-Nissan supply corridor faces the steepest reformulation burden given its high-volume sedan production profile.
Captive OEM touch-up programs are displacing independent aftermarket distributors for warranty repair and certified collision work. Nissan Mexicana consolidates color-matching and small-batch supply through direct Axalta pipeline connections. This channel consolidation concentrates service revenue within OEM-controlled networks across the Bajío cluster.
Mexico Automotive OEM Coatings Market Segmentation
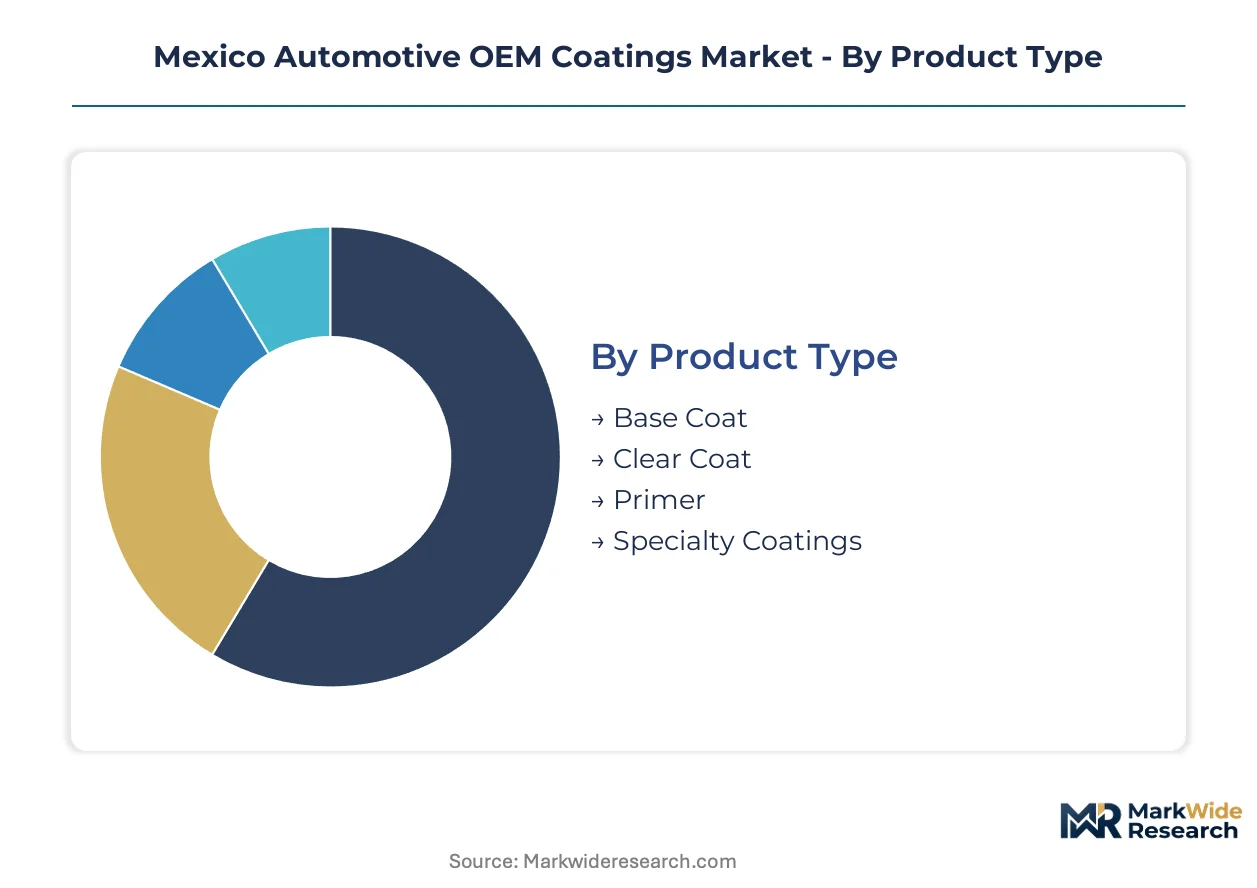
Segmentation in Mexico's automotive OEM coatings market reveals how formulation chemistry, vehicle architecture, and supply logistics intersect. Cycle times vary dramatically across product and application categories, dictating inventory strategies and capital allocation for suppliers serving the Bajío cluster.
Product Type:
Clear coat cycles through inventory fastest due to premium vehicle throughput, while specialty coatings turn slowest given batch production schedules.
- Clear Coat:Polyurethane-acrylic hybrid formulations deliver scratch resistance and gloss retention for premium passenger segments. Volkswagen's Puebla facility consumes the highest volumes as SUV exports to North American markets accelerate. PROFEPA emission audits prioritize clear coat booths for VOC capture upgrades.
- Base Coat:Pigmented layers containing metallic or pearlescent effects determine color depth and hide properties. Waterborne conversions concentrate here first, driven by NOM-085-SEMARNAT-2011 enforcement at Nissan's Aguascalientes complex. Dielectric formulations for electric vehicle battery enclosures represent a technical specification frontier.
- Primer:Electrocoat and surfacer systems provide corrosion protection and substrate adhesion. Cathodic epoxy electrocoats dominate high-volume lines.
- Specialty Coatings:Anti-chip, sound-dampening, and underbody formulations serve niche protection requirements. Low-batch production extends lead times.
Clear coat dominates installed base. Base coat is where expansion concentrates.
Application:
Passenger vehicle coating lines run at maximum utilization, while sports car applications command margin premiums despite minimal volume.
- Electric Vehicles:Battery enclosure dielectric coatings and lightweight substrate primers require thermal management properties. BMW's San Luis Potosí assembly plant sources specialized base coats for its electric SUV platform. NOM-085 compliance timelines accelerate waterborne adoption here faster than conventional segments.
- Passenger Vehicles:Sedan and SUV body-in-white coating represents the volume anchor for Mexican suppliers. Nissan Mexicana's Aguascalientes and Celaya facilities drive demand density for standard clear coat-base coat sequences.
- Commercial Vehicles:Heavy-duty truck cab coatings prioritize durability over aesthetic depth. Extended warranty terms drive specification rigor.
- Sports Cars:Low-volume, high-customization coating requires manual spray operations and extended color-matching protocols.
Passenger vehicles anchor production volume. Electric vehicles are climbing the fastest.
Delivery Mode:
Bulk delivery minimizes per-liter logistics cost for high-throughput plants, while on-site mixing preserves color flexibility for multi-platform facilities.
- Bulk:Tanker-truck delivery of base resins and solvents to dedicated pipeline connections. Axalta's direct feed to Volkswagen Puebla exemplifies this model. Capital intensity locks in supplier-OEM relationships across program lifecycles.
- On-Site Mixing:Automated tinting systems at assembly plant paint shops enable real-time color matching. PPG Industries' Guadalajara technical center supports this capability for premium programs.
- Pre-Mixed:Factory-blended formulations for standardized colors reduce booth complexity. Inventory carrying costs favor high-volume shades.
- Small Packs:Drum and pail quantities serve touch-up, warranty repair, and prototype build requirements.
Bulk delivery commands the largest share of coating volume. On-site mixing is gaining share fastest.
End User:
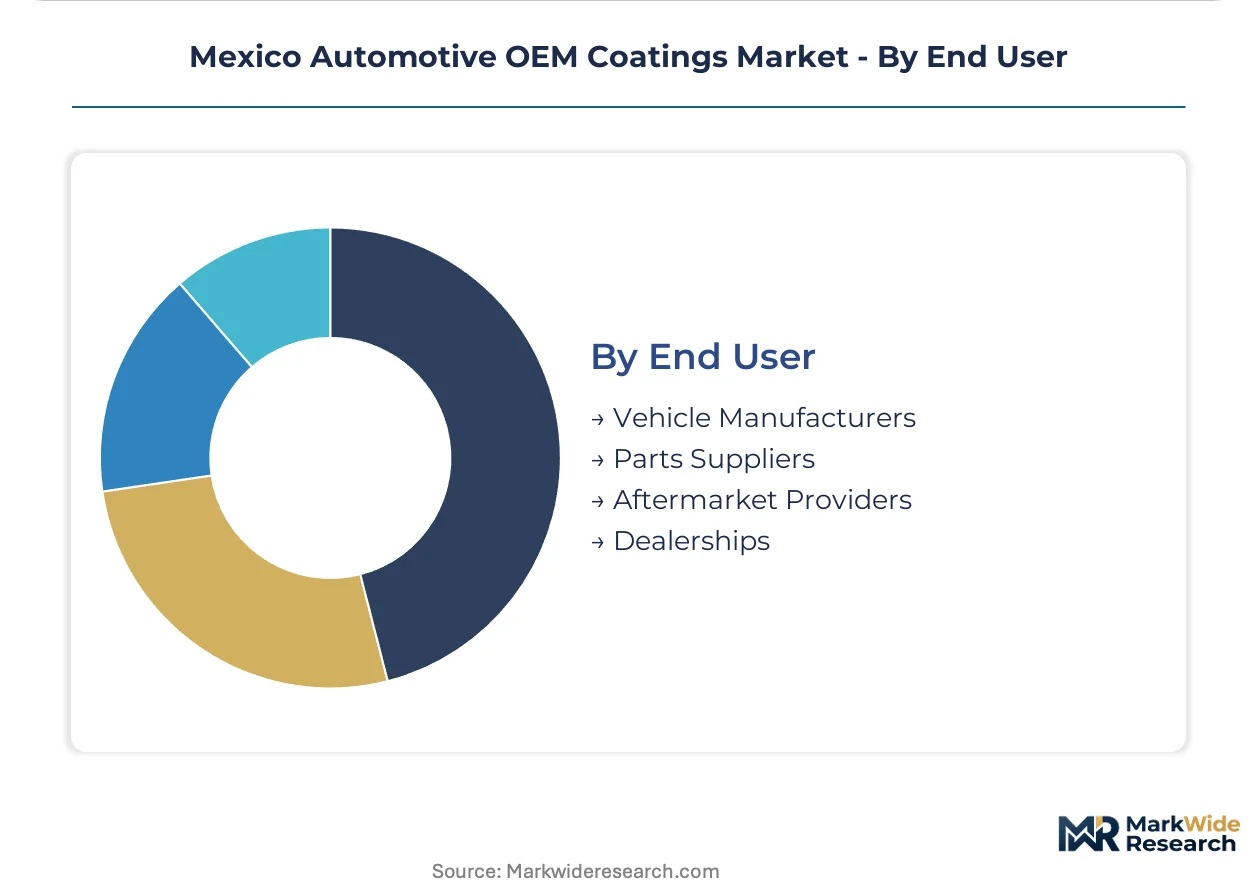
Vehicle manufacturers internalize the highest coating expenditure per unit, while aftermarket providers fragment across uncertified independent channels.
- Vehicle Manufacturers:OEM assembly plants specify, procure, and apply coatings under warranty-integrated supply agreements. BMW, Nissan, and Volkswagen Mexico negotiate multi-year contracts with formulation houses. PROFEPA compliance risk transfers fully to supplier qualification processes.
- Parts Suppliers:Tier-1 bumper, hood, and door module producers operate captive coating lines for component-level finishing. Plastic substrate compatibility drives specialized primer demand.
- Aftermarket Providers:Independent collision repair shops source through distributor networks. Color-matching technician scarcity constrains service quality.
- Dealerships:OEM-captive touch-up programs consolidate warranty repair revenue within manufacturer-controlled channels.
Vehicle manufacturers dominate procurement value. Parts suppliers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Bajío cluster exhibit the highest price elasticity for coating procurement, while Mexico City Metro manufacturers absorb premium formulations with minimal volume sensitivity. This demand-elasticity contrast shapes supplier pricing power across Mexican sub-regions.
Bajío Region
Volkswagen's Silao assembly plant and BMW's San Luis Potosí facility drive concentrated demand for waterborne base coats and dielectric formulations. PROFEPA enforcement of NOM-085-SEMARNAT-2011 accelerates solvent-borne phaseouts across Guanajuato coating lines. The Irapuato-Celaya corridor anchors Mexico's highest-density automotive coating consumption.
Nuevo León
Heavy-duty truck manufacturers in Monterrey sustain demand for commercial vehicle primer systems with extended durability specifications. SEMARNAT regional offices coordinate emission audits with Nuevo León environmental authorities. Apodaca industrial parks host captive coating operations for tier-1 bumper and hood module suppliers.
Jalisco
PPG Industries' Guadalajara technical center supports color-matching infrastructure for premium passenger vehicle programs. The state's automotive supplier base concentrates in El Salto and Tlajomulco municipalities. Jalisco's coating demand tilts toward on-site mixing systems for multi-platform assembly flexibility.
Mexico City Metro
Corporate procurement headquarters for Nissan Mexicana and Volkswagen de México concentrate strategic coating contract negotiations. The Secretariat of Economy coordinates NOM certification alignment with USMCA technical requirements from central offices. Toluca automotive corridors absorb specialized clear coat volumes for export-oriented SUV production.
Northern Border States
Chihuahua and Coahuila assembly plants serving USMCA export markets prioritize bulk delivery infrastructure for just-in-time coating supply. Customs coordination for resin imports from Texas petrochemical corridors shapes inventory strategies. Saltillo's Daimler truck facility commands dedicated primer supply lines from regional coating depots.
Mexico Automotive OEM Coatings Market Competitive Environment
Capability concentration sits with integrated formulation houses; scale advantage sits with direct-pipeline suppliers. The Mexico automotive OEM coatings market structures around three tiers: global resin-integrated majors, regional distribution specialists, and captive OEM supply units. Strategic archetypes include waterborne conversion specialists, dielectric coating developers, and integrated primer-base coat system providers. Dominant competitive moves encompass direct pipeline investments to assembly plants and technical center expansions for color-matching proximity.
Within the integrated formulation tier, PPG Industries, Axalta Coating Systems, and BASF SE anchor supplier positioning across Mexican assembly corridors. PPG occupies a position exemplifying technical center-led color-matching dominance. Axalta represents the direct-pipeline supply archetype through dedicated connections to high-volume OEM facilities. BASF SE sits within the integrated system provider category, reducing line complexity for vehicle manufacturers through combined electrocoat-primer-base coat offerings. These three entities collectively illustrate how global coating houses adapt Mexican operations to PROFEPA compliance timelines and electric vehicle substrate requirements.
| Leading Market Players |
|---|
| PPG Industries |
| Henkel AG & Co KGaA |
| Akzo Nobel N V |
| Jotun |
| Nippon Paint Holdings Co Ltd |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Sika AG |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
The Bajío automotive cluster around Silao-Irapuato-Celaya concentrates Mexico's highest coating consumption density, and this geographic supply concentration grants bulk-delivery suppliers substantial pricing leverage over OEM procurement teams negotiating multi-year supply agreements.
Pricing Analysis
Captive OEM touch-up and warranty repair programs now drive the dominant lifetime value capture mechanism, shifting revenue models from transactional per-liter coating sales toward integrated service contracts. Three-tier pricing structure across premium, standard, and economy levels separates dielectric formulations for electric vehicle battery enclosures from conventional base coat-clear coat sequences. Pricing pressure stems from petrochemical feedstock volatility tied to Gulf Coast propylene pricing, compressing margins for domestic formulators lacking upstream resin control. Tier-1 bumper and hood module suppliers exhibit the highest price sensitivity due to plastic substrate compatibility requirements, while BMW and Volkswagen Mexico absorb premium formulations with minimal volume negotiation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now anchor supplier-OEM relationships across Mexican assembly corridors, with Axalta's direct pipeline connections to Volkswagen Puebla exemplifying capital-intensive partnership lock-in. Raw material sourcing draws from United States petrochemical corridors for acrylic and polyurethane resins, German specialty chemical imports for cathodic epoxy electrocoats, and domestic Mexican production for solvent blends. Single-source vulnerability concentrates in cathodic epoxy electrocoat supply, where backward-integrated majors control formulation IP. Distribution runs through tanker-truck bulk delivery to dedicated pipeline connections, with on-site mixing systems gaining share for multi-platform color flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico automotive OEM coatings market functions as a service-attach opportunity where captive touch-up programs and warranty repair networks expand faster than base hardware sales, rewarding suppliers who integrate color-matching infrastructure with after-sales revenue capture.
For Market Incumbents: Insulate market position by deepening direct pipeline investments in the Bajío cluster before PROFEPA enforcement of NOM-085-SEMARNAT-2011 accelerates waterborne conversion timelines. Prioritize certification investment for dielectric battery enclosure formulations to capture BMW and Nissan electric vehicle platform specifications. Vertical integration into cathodic epoxy electrocoat resin production reduces exposure to Gulf Coast propylene volatility threatening margin stability. For New Entrants and Emerging Players: Establish a beachhead in tier-1 bumper and hood module coating lines serving plastic substrate compatibility requirements, where incumbent concentration remains lowest and procurement openness highest. Target the Irapuato-Celaya corridor's expanding parts supplier ecosystem rather than competing for direct OEM assembly plant supply. Lead with on-site mixing system partnerships that reduce capital barriers for multi-platform facilities seeking color flexibility without bulk delivery infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated primer-base coat system providers who reduce line complexity for vehicle manufacturers navigating PROFEPA compliance transitions. Long-term viability hinges on waterborne formulation IP and electric vehicle dielectric certification portfolios rather than solvent-borne legacy assets. Monitor SEMARNAT green credit incentive announcements as the critical inflection signal for accelerated capital expenditure into coating line upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Conversion Investment | PROFEPA enforcement of NOM-085-SEMARNAT-2011 mandates solvent-borne phaseouts across Guanajuato coating lines. |
| Dielectric Formulation Development | BMW's San Luis Potosí electric SUV platform requires specialized base coats with thermal management properties. |
| Direct Pipeline Infrastructure | Axalta's dedicated connections to Volkswagen Puebla demonstrate capital-intensive supplier-OEM relationship lock-in. |
| Technical Center Expansion | PPG Industries' Guadalajara facility sustains color-matching dominance across Mexican premium vehicle programs. |
| Integrated System Offering | BASF SE's combined electrocoat-primer-base coat systems reduce booth footprint and VOC capture requirements. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement leads, coating formulation R&D directors, and aftermarket service operations managers, and refined through secondary validation across vehicle production databases, customs and trade flow records, SEMARNAT regulatory filings, and IHS Markit registration data. Bottom-up volume estimates triangulated against top-down market sizing across coating chemistry segments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning clear coat-base coat-primer-specialty product tiers, electric-passenger-commercial-sports vehicle applications, bulk-on-site mixing-pre-mixed-small pack delivery modes, and OEM-parts supplier-aftermarket-dealership end users. CAGRs derived from production volume forecasts, content-per-vehicle assumptions, and pricing trajectory analysis incorporating resin cost pass-through mechanics and PROFEPA compliance investment cycles.
Stress conditions across petrochemical feedstock volatility, NOM-085 amendment timelines, and electric vehicle platform ramp rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts incorporate documented assumptions regarding USMCA rules of origin continuity and SEMARNAT enforcement intensity. Macroeconomic contraction, regulatory acceleration beyond modeled timelines, or breakthrough UV-cure hybrid technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market