
 Aesthetic Surgery Procedures Market | 2026-2036
Aesthetic Surgery Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Surgery Procedures Market Analytics
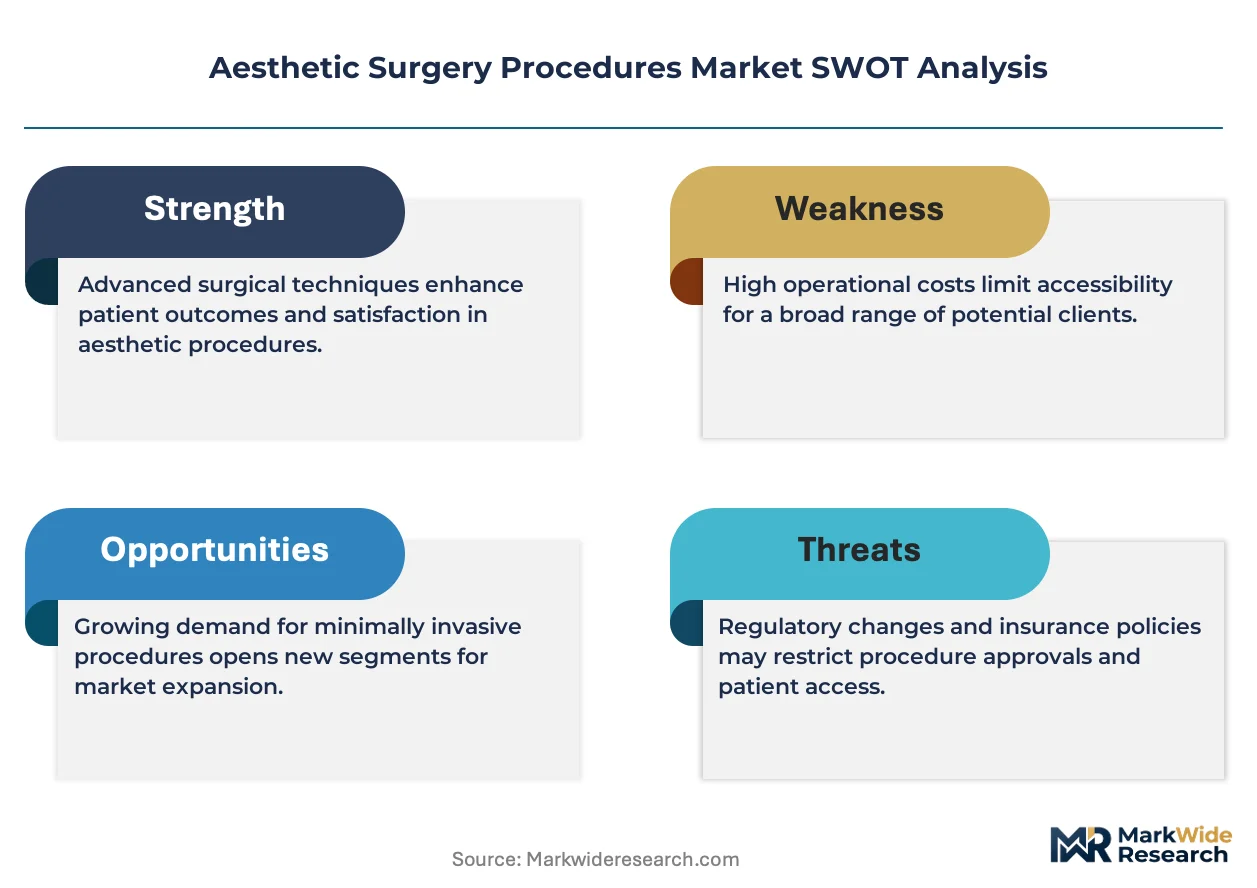
The capital-intensity divergence between integrated device manufacturers and standalone clinic chains is unwinding competitive stability in aesthetic surgery. AbbVie Inc. leverages its Allergan Aesthetics portfolio to control injectable and implant supply chains across North America and Europe. Johnson & Johnson Services, Inc. (MENTOR) anchors breast implant and body contouring device segments through sustained R&D investment in silicone gel technologies. Galderma competes in the injectable space with hyaluronic acid and biostimulator portfolios, differentiating through physician training ecosystems rather than hardware ownership.
Aesthetic surgery procedures encompass invasive and minimally invasive interventions that reshape, reconstruct, or enhance facial and bodily structures through surgical incision, tissue manipulation, or energy-based modalities such as laser, ultrasound, and radiofrequency systems. These procedures serve commercial purposes spanning cosmetic enhancement, reconstructive correction, and age-related restoration across outpatient and surgical settings. Breast augmentation and liposuction within procedure type segments command established volume positions, while laser and ultrasound technologies are gaining structural share as patients prioritize reduced downtime and lower complication profiles. Clinics and medical spas within end user segments concentrate margin pools through high-frequency, lower-acuity services that offset hospital-based surgical overhead.
FDA 510(k) clearances and EU MDR conformity assessments govern device commercialization, with the FDA requiring clinical evidence for novel energy-based systems and the EU MDR extending post-market surveillance obligations for implantable aesthetics. Brazil's ANVISA and South Korea's MFDS impose additional localization requirements that shape multinational market entry sequencing. Stakeholders must monitor regulatory divergence between accelerated approval pathways in Asia-Pacific markets and the evidence thresholds tightening in the United States and European Union.
Market Dynamics
Energy-based modalities are compressing surgical volume as patients prioritize reduced downtime, forcing traditional incision-based procedures to defend margin through outcome differentiation rather than volume capture.
Growth Catalysts
- MFDS fast-track pathways:South Korea's abbreviated approval routes for laser and ultrasound devices accelerate commercialization timelines for energy-based systems targeting facial contouring.
- Medical spa outpatient migration:Ambulatory settings capture high-frequency injectable and skin tightening demand that hospitals cannot match operationally.
- Hyaluronic acid formulation advances:Cross-linking density improvements extend product longevity and reduce touch-up frequency for facial volumization procedures.
Market Restraints
- Silicone gel supply concentration:Breast implant manufacturers face input dependency on a narrow supplier base for cohesive gel formulations.
- EU MDR post-market surveillance extension:Implantable aesthetics now carry mandatory clinical follow-up obligations that inflate regulatory compliance costs.
- Non-invasive body contouring substitution:Cryolipolysis and radiofrequency fat reduction capture patients who previously selected liposuction.
Strategic Opportunities
- Turkey's medical tourism infrastructure:Istanbul and Ankara clinic clusters attract price-sensitive European patients seeking packaged surgical procedures.
- Biostimulator-dermal filler convergence:Combination protocols using poly-L-lactic acid and calcium hydroxylapatite address both volume loss and collagen induction.
- Telemedicine pre-consultation channels:Virtual assessment workflows reduce geographic friction for patients evaluating cross-border surgical options.
Industry Challenges
- Energy-based device certification timelines:FDA 510(k) clinical evidence requirements for novel laser wavelengths extend development cycles.
- Physician injector training standardization:Inconsistent competency frameworks across jurisdictions create liability exposure and outcome variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Surgery Procedures Market |
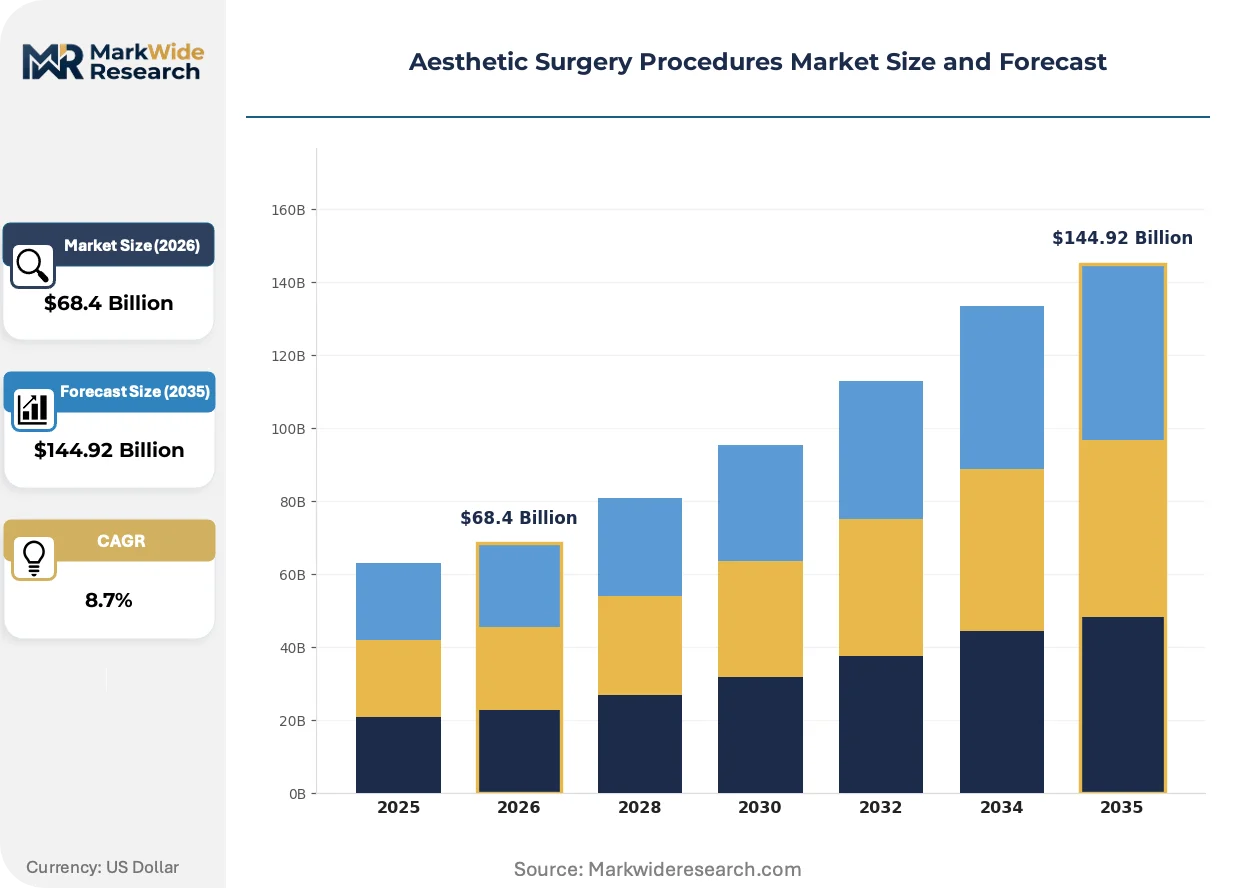
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Facelift, Rhinoplasty, Liposuction, Breast Augmentation End User: Clinics, Hospitals, Medical Spas, Surgeons Technology: Laser, Ultrasound, Fillers, Tumescent Service Type: Consultation, Post-Operative Care, Anesthesia, Surgical Services |
| Companies Covered | AbbVie Inc., Johnson & Johnson Services, Inc. (MENTOR), Galderma, Bausch Health Companies Inc., Cutera, Inc., Cynosure, Merz Pharma, Westlake Dermatology, Piedmont Plastic Surgery & Dermatology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Surgery Procedures Market Evolving Landscape
Device miniaturization and algorithmic treatment planning are redistributing capability from hospital surgical suites toward outpatient settings, altering where margin accumulates in the value chain.
Microfocused ultrasound with visualization is displacing traditional surgical lifts for moderate skin laxity cases. Dermatology and plastic surgery practices in Seoul and Los Angeles deploy these systems for brow and submental contouring. The technology is displacing lower-face rhytidectomy volume among patients aged 35-50 who prioritize scar avoidance.
EU MDR technical documentation requirements for implantable devices now mandate clinical evaluation reports with post-market clinical follow-up data. Breast implant manufacturers must maintain patient registries and periodic safety update reports. The obligation compresses product lifecycle economics for European market participants.
Subscription-based maintenance programs for injectable portfolios are replacing transactional per-procedure purchasing. Aesthetic clinic chains in São Paulo and Miami bundle hyaluronic acid touch-ups into annual membership tiers. Brazil's dense network of independent practitioners shows fastest uptake of this retention-focused commercial model.
Aesthetic Surgery Procedures Market Segmentation
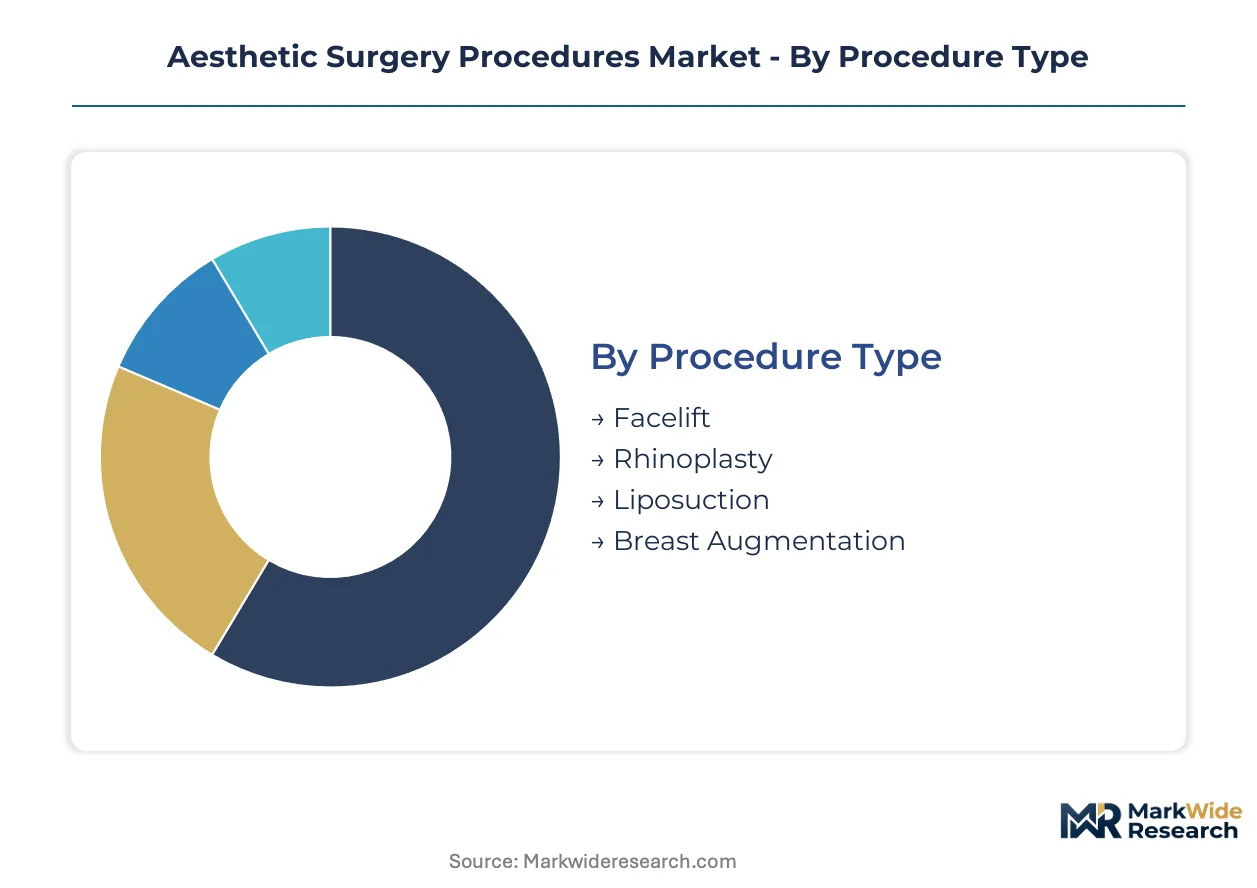
Segmentation in aesthetic surgery reveals how procedure economics, technology adoption, and care delivery settings fragment margin capture across the value chain. Distinct patient risk tolerances and recovery preferences create parallel demand tracks that manufacturers and providers must navigate simultaneously.
Procedure Type:
Geographic concentration varies sharply: breast augmentation and liposuction dominate domestic volume in established markets, while rhinoplasty and facelift procedures drive medical tourism flows to lower-cost surgical hubs.
- Breast Augmentation:Silicone and saline implant procedures constitute the revenue anchor for device manufacturers. United States and Brazil concentrate demand through high-volume clinic chains that bundle implant selection with surgical facility fees.
- Liposuction:Suction-assisted lipectomy and power-assisted variants remain the reference standard for adipose tissue reduction. Turkey and South Korea absorb cross-border patient flows seeking cost arbitrage on multi-site body contouring packages.
- Facelift:Rhytidectomy procedures target advanced skin laxity through SMAS manipulation techniques. Demand clusters among patients aged 55-70 in Germany and the United States.
- Rhinoplasty:Nasal reshaping surgeries address both aesthetic and functional septal concerns. Iran and South Korea maintain specialized surgical reputations that attract international patients.
Breast augmentation holds the largest share; momentum sits with liposuction as energy-based alternatives redirect lower-BMI patients toward non-invasive options.
End User:
Cost tier stratification separates high-overhead hospital surgical suites from lean outpatient models that capture frequency-driven injectable and skin tightening demand.
- Medical Spas:Hybrid clinical-retail environments deploy physician extenders for high-volume, lower-acuity services. Miami and São Paulo clusters demonstrate how membership pricing models stabilize recurring revenue from neurotoxin and hyaluronic acid protocols.
- Clinics:Dedicated aesthetic surgery centers concentrate surgical volume through specialized staffing and equipment utilization. Single-specialty facilities in Seoul and Los Angeles achieve margin advantages through case volume density.
- Hospitals:Acute care settings retain complex reconstructive cases and high-risk patient populations requiring anesthesia support. Reimbursement frameworks in Germany and Switzerland sustain hospital-based aesthetic volumes.
- Surgeons:Independent practitioner models persist in Brazil's fragmented market structure, where solo operators compete through direct patient relationships and social media visibility.
Medical spas are climbing the fastest; clinics defend position through surgical outcome differentiation that hospital systems struggle to replicate.
Technology:
Application focus determines adoption velocity: facial technologies penetrate faster than body applications due to lower patient risk tolerance for facial complications.
- Fillers:Hyaluronic acid and biostimulator injectables enable tissue volumization without surgical recovery. Cross-linking density improvements from Galderma and AbbVie extend product longevity and reduce touch-up frequency.
- Laser:Ablative and non-ablative fractional systems address photodamage and textural irregularities. FDA 510(k) clearance pathways for novel wavelengths impose clinical evidence requirements that extend development timelines.
- Ultrasound:Microfocused ultrasound with visualization delivers thermal coagulation points for skin tightening. Seoul and Los Angeles practices deploy these systems for brow and submental contouring among scar-averse patients.
- Tumescent:Infiltration-based local anesthesia protocols enable awake liposuction with reduced systemic risk. The technique remains foundational for office-based surgical procedures.
Fillers command the largest share; ultrasound systems show steepest expansion trajectory as visualization capabilities improve treatment precision.
Service Type:
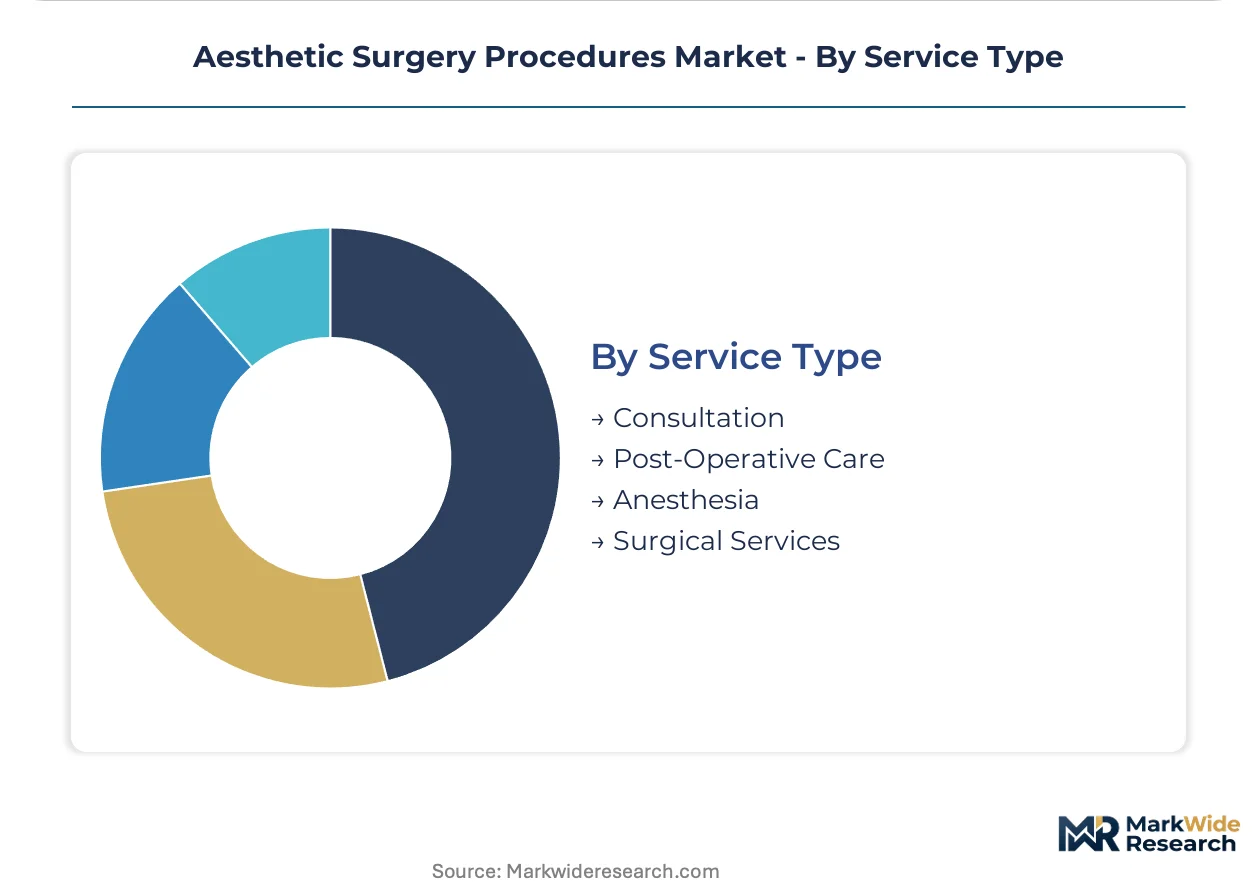
Customer type fragmentation separates one-time surgical purchasers from ongoing maintenance relationships that anesthesia and post-operative services sustain.
- Surgical Services:Procedure fees encompass facility, surgeon, and implant costs in bundled pricing structures. Istanbul clinic clusters package multiple procedures into fixed-price offerings that attract European medical tourists.
- Post-Operative Care:Follow-up protocols, compression garment fitting, and complication management extend patient touchpoints. EU MDR post-market surveillance obligations now mandate systematic follow-up for implantable aesthetics.
- Consultation:Pre-procedure assessment and surgical planning represent the conversion funnel entry point. Telemedicine channels reduce geographic friction for patients evaluating cross-border surgical options.
- Anesthesia:General, sedation, and tumescent local techniques vary by procedure invasiveness and patient comorbidity profile. Anesthesiologist availability constrains hospital-based surgical scheduling.
Surgical services generate the largest revenue pool; post-operative care is gaining share fastest as regulatory surveillance requirements and retention economics intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across surgical hubs: the United States and Brazil concentrate high-volume implant demand, while South Korea and Turkey absorb cross-border patients seeking cost-efficient facial procedures. Germany sustains hospital-based reconstructive volumes through insurance frameworks absent elsewhere.
United States
Breast augmentation and liposuction dominate domestic procedure economics, with silicone implant selection driving device revenue concentration. FDA 510(k) clearances govern energy-based system commercialization, extending development timelines for novel laser wavelengths. Los Angeles and Miami clinic clusters bundle surgical facility fees with implant costs, capturing premium pricing through outcome differentiation.
Brazil
Independent practitioner density sustains the world's most fragmented aesthetic surgery market structure. ANVISA imposes localization requirements on implantable device imports, shaping multinational entry sequencing. São Paulo's clinic chains pioneer subscription-based injectable membership models, stabilizing recurring revenue from neurotoxin and hyaluronic acid protocols.
South Korea
Facial contouring procedures command disproportionate volume relative to body interventions, reflecting cultural preference for scar-minimizing outcomes. MFDS fast-track pathways accelerate laser and ultrasound device approvals, compressing commercialization timelines for energy-based systems. Seoul practices deploy microfocused ultrasound with visualization for brow and submental tightening among patients aged 35-50.
Germany
Reimbursement frameworks sustain hospital-based aesthetic volumes for complex reconstructive cases requiring anesthesia support. EU MDR post-market surveillance obligations now mandate systematic clinical follow-up for implantable aesthetics, inflating compliance costs. Frankfurt and Munich surgical centers concentrate SMAS manipulation techniques for patients aged 55-70.
Turkey
Medical tourism infrastructure attracts price-sensitive European patients seeking packaged surgical procedures at 40-60% cost differentials. The country's national medical device regulator aligns with EU MDR technical documentation standards for market access. Istanbul and Ankara clinic clusters bundle rhinoplasty and liposuction into fixed-price offerings with airport transfer and accommodation.
Aesthetic Surgery Procedures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-device hybrids controlling injectable supply chains while standalone energy-device manufacturers compete on wavelength differentiation. Three archetypes dominate: diversified healthcare conglomerates with aesthetic divisions, pure-play dermatology device specialists, and regional clinic chains with captive patient flows. Competitive moves concentrate on physician training ecosystem lock-in and subscription-based commercial model adoption.
Within the integrated healthcare tier, AbbVie Inc. and Johnson & Johnson Services, Inc. occupy positions exemplifying pharmaceutical-device hybrid strategies, while Galderma represents the dermatology-focused pure-play archetype. AbbVie leverages its Allergan Aesthetics portfolio across North American and European supply chains. Johnson & Johnson's MENTOR division anchors breast implant segments through sustained investment in silicone gel technologies. Galderma differentiates through hyaluronic acid and biostimulator portfolios coupled with physician training infrastructure rather than hardware ownership.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson Services, Inc. (MENTOR) |
| Galderma |
| Bausch Health Companies Inc. |
| Cutera, Inc. |
| Cynosure |
| Merz Pharma |
| Westlake Dermatology |
| Piedmont Plastic Surgery & Dermatology |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance pathways and EU MDR conformity assessments gate both device manufacturer qualification and the price premiums that cleared products command over uncertified alternatives in aesthetic surgery markets.
Pricing Analysis
Long-term offtake contracts dominate breast implant procurement between manufacturers and high-volume clinic chains, while spot purchasing persists for energy-based devices in fragmented medical spa settings. Pricing stratifies across premium, standard, and economy tiers based on silicone gel cohesivity grades and FDA clearance vintage. Cost compression in economy-tier hyaluronic acid fillers is intensifying because South Korean manufacturers are expanding cross-border distribution. Independent practitioners in Brazil exhibit highest price sensitivity; integrated hospital systems in Germany show lowest sensitivity due to reimbursement frameworks.
Supply Chain Analysis
Strategic stockpiling of cohesive silicone gel precursors dominates inventory strategy among breast implant manufacturers facing narrow supplier bases. Raw material concentration centers on the United States, Germany, and South Korea for medical-grade silicone formulations; device assembly concentrates in Costa Rica, Ireland, and Malaysia. Supply chains rest on single-source vulnerability for cross-linked hyaluronic acid polymers. Distribution runs through specialized medical device distributors with cold-chain capabilities for biologic fillers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through clinic chain consolidation in São Paulo and Miami, shifting procurement leverage toward high-volume purchasers capable of demanding subscription-based pricing models.
For Market Incumbents: Secure exclusive supply agreements with cohesive gel manufacturers to defend against South Korean entrants expanding hyaluronic acid portfolios. Lock in physician training certification pathways as a channel control mechanism against independent injector networks eroding brand loyalty. Expand backward integration into raw material purification to offset silicone gel supply concentration risks. For New Entrants and Emerging Players: Lead with telemedicine-enabled pre-consultation platforms targeting Turkey's medical tourism corridor, where cross-border patient acquisition friction remains highest. Capture white-space in subscription-based maintenance programs for biostimulator combinations, a segment showing fastest uptake in Brazil's independent practitioner market. Deploy direct-to-clinic digital distribution to bypass established distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across energy-based device manufacturing as semiconductor laser components commoditize, compressing hardware margin sustainability. Target acquisition profiles should emphasize software-enabled treatment planning platforms with recurring revenue models rather than capital-heavy device manufacturers. Watch FDA 510(k) clearance velocity for novel ultrasound wavelengths as the inflection signal for energy-based modality substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Physician Training Ecosystem Lock-in | AbbVie and Galderma deploy certification programs that bind injectors to proprietary filler portfolios. |
| Subscription-Based Injectable Memberships | São Paulo clinic chains stabilize recurring revenue through annual neurotoxin and hyaluronic acid bundles. |
| EU MDR Post-Market Surveillance Compliance | Breast implant manufacturers must maintain patient registries, inflating compliance costs for European market access. |
| Telemedicine Pre-Consultation Channels | Turkish clinic clusters reduce geographic friction for European medical tourists evaluating cross-border surgical options. |
| Biostimulator-Dermal Filler Convergence | Combination protocols using poly-L-lactic acid address both volume loss and collagen induction in single treatment sessions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plastic surgeons, medical spa medical directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, ANVISA registration records, and hospital procurement databases. Bottom-up procedure volume estimates were triangulated against top-down device shipment data reported in regulatory filings.
Across the analysis window, the forecasting framework modeled procedure type segmentation, technology adoption curves, end-user channel mix, and geographic regulatory cluster variations. CAGRs were derived from trend extrapolation of historical volume data adjusted for substitution effects between surgical and energy-based modalities. Key inputs included MFDS fast-track approval velocity, medical tourism flow estimates for Turkey and South Korea, and silicone gel supply capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance timelines and stable medical tourism policy environments would require recalibration. Forecasts reflect assumptions regarding physician training standardization and energy-based device substitution rates. Revision becomes warranted when EU MDR post-market surveillance cost burdens cross thresholds that trigger manufacturer market exit decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Global Facial Fat Transfer Market