
 Colombia Facial Aesthetics Market | 2026-2036
Colombia Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Facial Aesthetics Market Insights
A capital-intensity divergence between installed-laser portfolios and injectable-only service lines is reorganizing competitive tiers across Colombia's facial aesthetics landscape. Alma Lasers Ltd leverages its multi-wavelength platform dominance to anchor premium positioning in Bogotá's clinic corridor. Merz Aesthetics sustains deep channel relationships with dermatology networks through specialized training academies. Johnson & Johnson competes on brand recognition among first-time aesthetic consumers entering the market.
Facial aesthetics encompasses minimally invasive and non-invasive procedures that modify skin texture, volume distribution, and structural contours through injectable biologics, energy-based devices, or chemical resurfacing agents. Hyaluronic acid fillers and botulinum toxin formulations constitute the dominant injectable modalities, requiring cold-chain logistics and precise rheological properties for predictable tissue integration. Injectable products occupy the largest revenue pool, while laser treatments represent the fastest-growing segment as radiofrequency and fractional technologies displace older ablative systems. Aesthetic centers and specialized dermatology clinics command disproportionate margins due to bundled procedure pricing and repeat-visit patient economics.
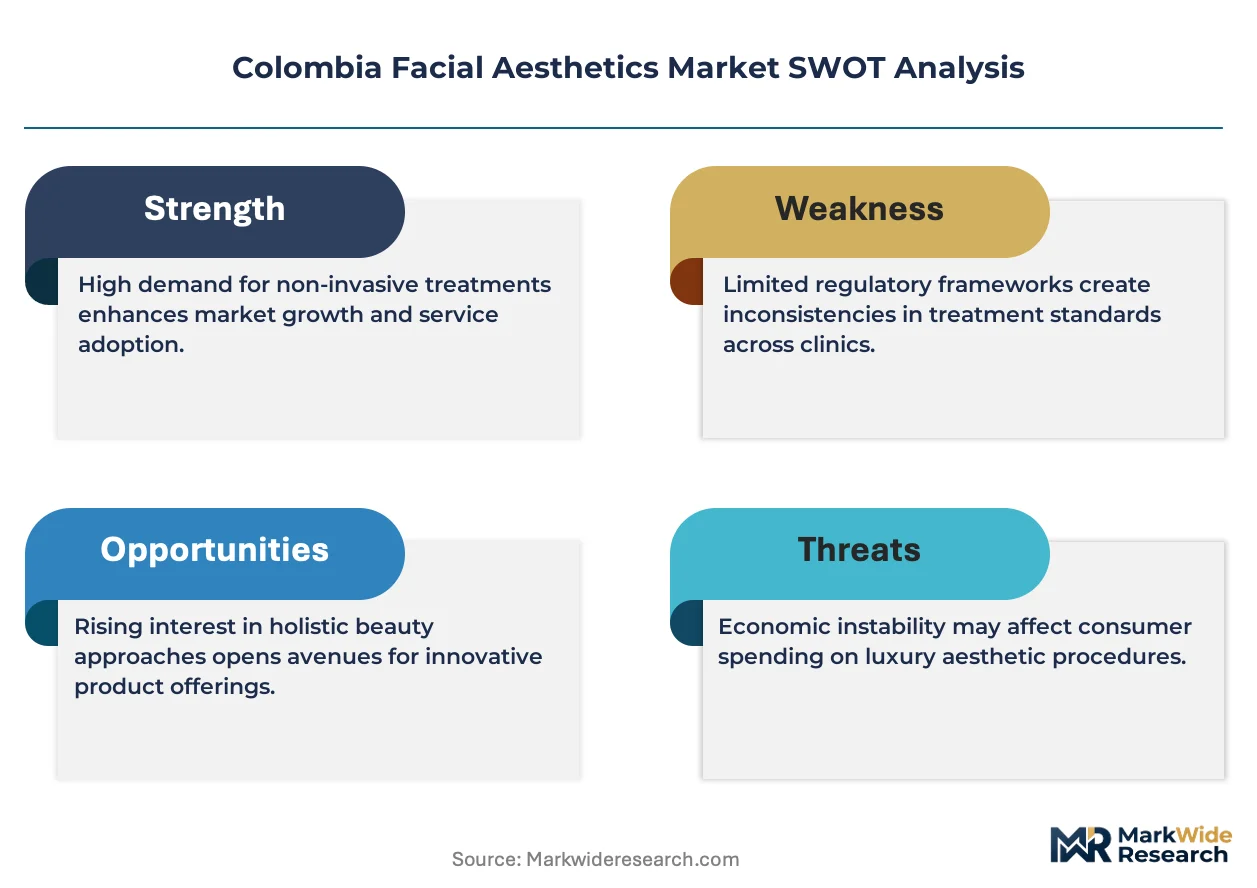
Colombia's INVIMA medical device registry, supplemented by Ministry of Health cosmetic procedure guidelines and mandatory adverse-event reporting protocols, shapes product registration timelines and clinical training requirements for device operators. These frameworks elevate compliance costs for imported devices while creating protected windows for established suppliers with regulatory dossier expertise. Stakeholders must monitor how INVIMA's alignment with international harmonization initiatives reshapes competitive access for new market entrants.
Market Dynamics
INVIMA's regulatory modernization for medical devices is compressing registration timelines while elevating compliance thresholds, forcing suppliers to rebuild dossier capabilities or cede position to established registrants with Bogotá-based regulatory infrastructure.
Growth Catalysts
- Medical tourism flows:Latin American patients concentrate demand in Bogotá and Medellín aesthetic corridors, amplifying procedure volume at premium centers with multilingual service capabilities.
- INVIMA harmonization initiatives:Alignment with international medical device standards accelerates import pathways for dermal fillers and laser systems, reducing time-to-market for compliant suppliers.
- Urban middle-class expansion:Colombia's metropolitan consumer base drives repeat-visit economics for minimally invasive skin rejuvenation procedures, anchoring clinic revenue predictability.
Market Restraints
- Cold-chain logistics costs:Hyaluronic acid fillers and botulinum toxin formulations require temperature-controlled distribution infrastructure that elevates landed costs for imported biologics.
- Capital intensity divergence:Multi-wavelength laser platforms demand seven-figure capital commitments that exclude injectable-only service lines from premium positioning tiers.
- Operator certification requirements:Ministry of Health cosmetic procedure guidelines mandate clinical training hours that constrain workforce scalability and elevate labor costs.
Strategic Opportunities
- Secondary city penetration:Cali, Barranquilla, and Bucaramanga aesthetic markets remain underdeveloped relative to Bogotá-Medellín corridor density, offering first-mover positioning for branded clinic networks.
- Radiofrequency-fractional convergence:Combination platforms integrating radiofrequency energy with fractional delivery modes create procedure bundling opportunities that lift per-visit revenue.
- Specialized training academy models:Dermatology network partnerships that embed device-specific certification programs lock in recurring equipment purchases and consumable commitments.
Industry Challenges
- Adverse-event reporting infrastructure:Mandatory protocols require clinic-level documentation systems that many independent operators lack, creating compliance vulnerability and inspection risk.
- Device-operator skill matching:Fractional and radiofrequency technologies demand precise parameter calibration that outpaces available training pipeline capacity, elevating liability exposure.
- Import documentation complexity:INVIMA medical device registry requirements for rheological property verification and biocompatibility dossiers delay product launches and strain distributor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Facial Aesthetics Market |
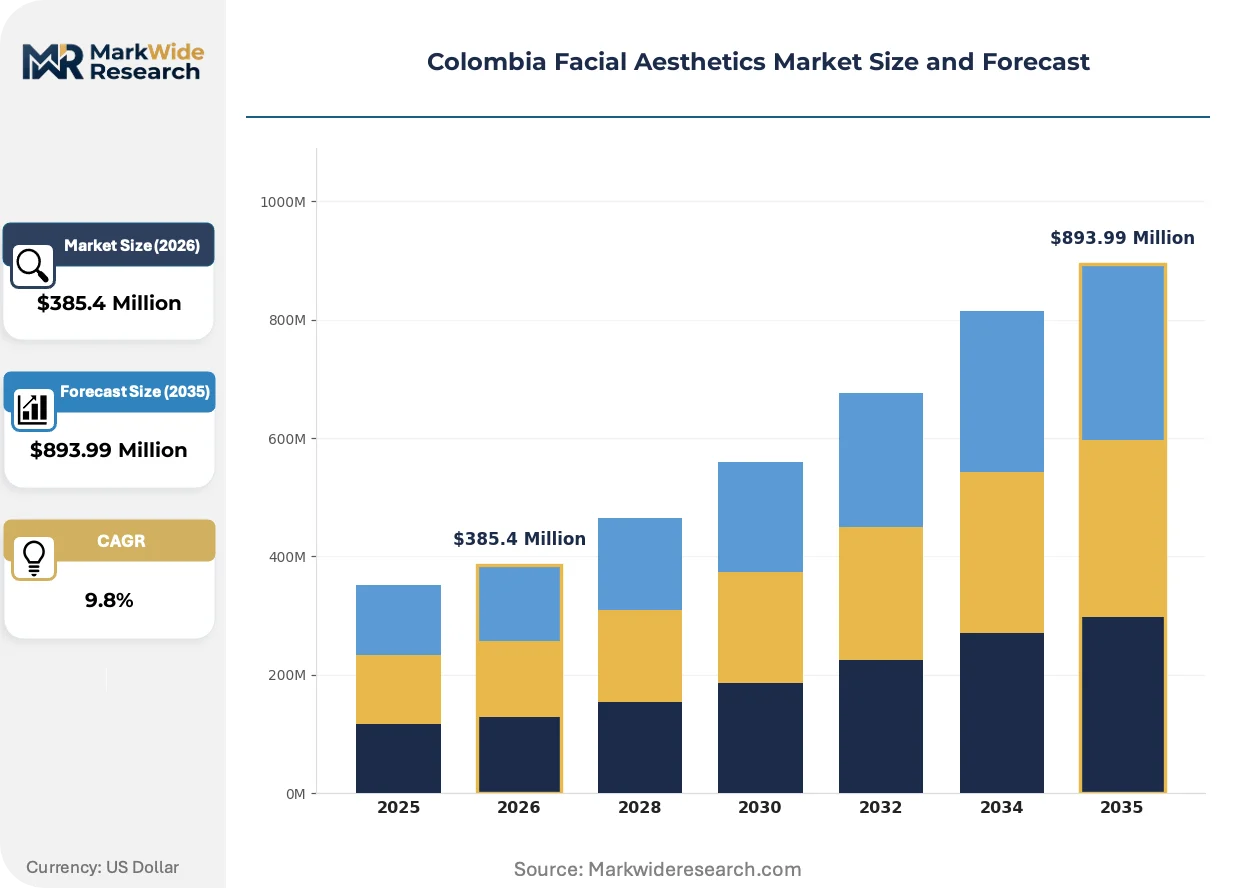
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $893.99 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Dermal Fillers, Chemical Peels, Laser Treatments End User: Clinics, Dermatologists, Plastic Surgeons, Aesthetic Centers Application: Wrinkles, Skin Rejuvenation, Acne Scar Treatment, Skin Tightening Technology: Minimally Invasive, Non-Invasive, Laser-Based, Radiofrequency |
| Companies Covered | Cutera Inc, Fotona, Alma Lasers Ltd, Lumenis, Candela Medical, Cynosure, Merz Aesthetics, Johnson & Johnson, Allergan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Facial Aesthetics Market Trends and Innovations
Energy-based modalities are compressing the competitive distance between dermatology clinics and medical spas, while regulatory alignment is reshaping which suppliers can sustain market access.
Radiofrequency-fractional combination platforms are fragmenting the historical dominance of standalone ablative lasers in Colombia's premium clinic segment. Aesthetic centers in Bogotá's financial district are adopting these systems at replacement-cycle pace, displacing older CO2 devices. The technology is fragmenting procedure pricing power across service tiers as mid-market clinics acquire comparable capabilities.
INVIMA's medical device registry alignment with international harmonization standards is compressing registration timelines for established dossier holders while elevating barriers for new entrants. The industrial consequence is protected market windows for suppliers with Bogotá-based regulatory infrastructure. Dermal filler and laser system categories are most affected, with established registrants accelerating product line extensions to exploit access advantages.
Urban consumers are compressing decision cycles between initial consultation and procedure commitment, driven by social media-facilitated outcome visualization and peer referral density. The traditional dermatology referral channel is losing share to direct-to-clinic digital booking platforms. This behavioral shift is most visible in Medellín's El Poblado corridor, where aesthetic centers report shortened patient acquisition funnels and elevated same-day conversion rates.
Colombia Facial Aesthetics Market Segmentation
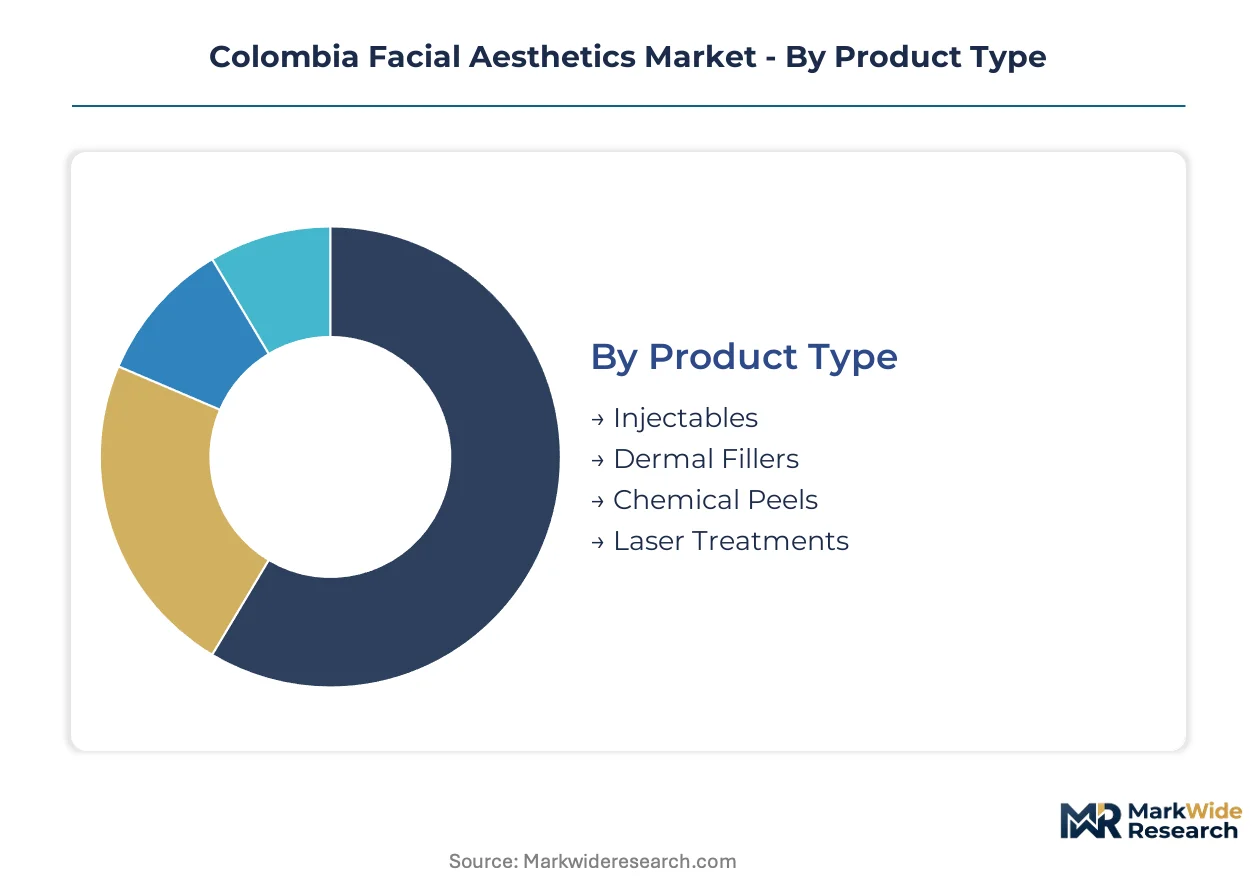
Channel economics in Colombia's facial aesthetics market vary sharply by segment. Injectable products flow through distributor networks with cold-chain requirements, while energy-based devices sell direct to capital-equipped clinics.
Product Type:
Distribution channels diverge sharply across product categories, with consumable injectables flowing through pharmaceutical distributors and capital equipment requiring direct manufacturer relationships.
- Injectables:Botulinum toxin formulations require precise cold-chain logistics from import through final administration. Demand concentrates among Bogotá dermatology networks seeking predictable per-unit economics and Ministry of Health training compliance.
- Dermal Fillers:Hyaluronic acid gels with varied rheological profiles target specific facial zones. Urban middle-class consumers in Medellín's El Poblado corridor drive repeat-visit purchasing patterns for lip and cheek augmentation procedures.
- Chemical Peels:Acid-based resurfacing agents offer lower capital barriers for clinic entry. Aesthetic centers in secondary cities favor these for margin preservation without device financing requirements.
- Laser Treatments:Fractional and ablative systems command premium positioning through technological sophistication.
Injectables dominate installed base. Laser treatments are where expansion concentrates.
End User:
Procurement authority and patient volume shape how suppliers allocate field resources across provider types.
- Clinics:Multi-service aesthetic centers in Bogotá's financial district bundle procedures across injectable and energy-based modalities. These operators negotiate volume-based consumable pricing and demand flexible equipment financing.
- Dermatologists:Board-certified specialists anchor referral networks and influence device purchasing decisions for affiliated clinics. Their training academies create lock-in effects for specific filler and laser brands.
- Plastic Surgeons:Surgical practices extending into non-invasive services seek premium positioning through exclusive technology access.
- Aesthetic Centers:Standalone facilities in Medellín and Cali concentrate on minimally invasive procedures with rapid patient turnover.
Dermatologists anchor professional influence. Aesthetic centers are gaining share fastest.
Application:
Patient demographics and price sensitivity create distinct competitive arenas across treatment objectives.
- Wrinkles:Botulinum toxin applications for glabellar and forehead lines represent the most penetrated consumer segment. First-time aesthetic patients in urban Colombia typically enter through this entry point.
- Skin Rejuvenation:Combination protocols using fillers, peels, and light-based modalities target middle-aged professionals. Clinics in Bogotá's Zona Rosa report strong same-day conversion for bundled rejuvenation packages.
- Acne Scar Treatment:Fractional laser and radiofrequency microneedling address underserved demand among younger demographics.
- Skin Tightening:Non-invasive lifting procedures using ultrasound or radiofrequency energy attract patients avoiding surgical intervention.
Wrinkles command procedure volume. Skin rejuvenation shows the steepest expansion trajectory.
Technology:
Capital requirements and operator training intensity stratify competitive positioning across technical approaches.
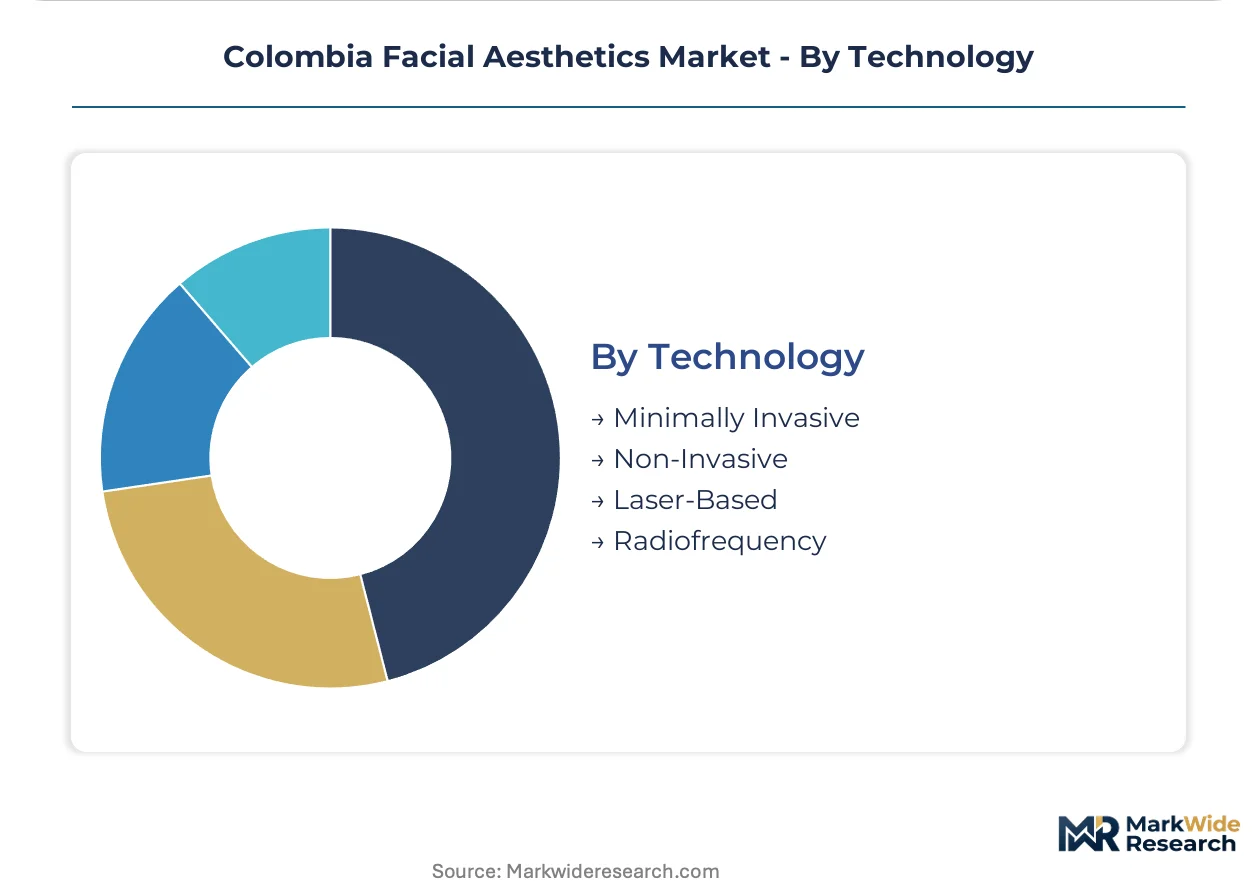
- Minimally Invasive:Injectable delivery and microneedling procedures balance efficacy with rapid recovery. These modalities dominate patient acquisition in Colombia's cost-conscious secondary cities.
- Non-Invasive:Topical and energy-based treatments without breach of skin barrier appeal to risk-averse first-time patients. Aesthetic centers promote these for their zero-downtime value proposition.
- Laser-Based:Ablative and fractional systems demand substantial capital investment and certified operator training.
- Radiofrequency:Tissue heating technologies for tightening and contouring applications integrate with microneedling platforms.
Minimally invasive approaches anchor clinic economics. Radiofrequency is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Colombia's facial aesthetics landscape, with Bogotá and Medellín patients showing lower price sensitivity for premium laser protocols while secondary city consumers prioritize injectable entry points.
Bogotá
Colombia's capital concentrates the highest per-capita spending on combination rejuvenation protocols among urban middle-class professionals. INVIMA's medical device registry requirements shape import timelines for dermal fillers and laser systems entering through El Dorado International logistics corridors. The Zona Rosa and financial district clinic clusters anchor premium positioning through bundled procedure pricing and multilingual service capabilities targeting medical tourism flows.
Medellín
El Poblado corridor aesthetic centers report accelerated patient acquisition funnels driven by social media-facilitated outcome visualization. The Ministry of Health cosmetic procedure guidelines mandate clinical training hours that constrain workforce scalability across Antioquia's expanding clinic network. Medellín's metro area generates disproportionate repeat-visit economics for hyaluronic acid filler applications among younger demographics seeking lip and cheek augmentation.
Cali
Valle del Cauca's aesthetic market remains underdeveloped relative to Bogotá-Medellín density, offering first-mover positioning for branded clinic networks. Cold-chain logistics costs for botulinum toxin formulations elevate landed costs for Pacific-facing distribution routes. Cali's emerging aesthetic centers favor chemical peel modalities for margin preservation without capital-intensive device financing requirements.
Barranquilla
Caribbean coastal demand concentrates on minimally invasive entry points with rapid recovery profiles suited to tropical climate patient preferences. INVIMA's regulatory modernization for medical devices is compressing registration timelines for established dossier holders with Bogotá-based regulatory infrastructure. Barranquilla's clinic operators are adopting radiofrequency-fractional combination platforms at replacement-cycle pace, displacing older standalone ablative systems.
Bucaramanga
Santander's metropolitan consumer base drives emerging demand for non-invasive skin tightening procedures using ultrasound or radiofrequency energy. Mandatory adverse-event reporting protocols require clinic-level documentation systems that many independent operators in secondary cities lack, creating compliance vulnerability. Bucaramanga's aesthetic centers are concentrating on acne scar treatment applications using fractional laser technologies to capture underserved younger demographic demand.
Colombia Facial Aesthetics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Colombia's facial aesthetics market, with capital-intensity divergence between installed-laser portfolios and injectable-only service lines reorganizing competitive tiers. Multi-wavelength platform suppliers anchor premium positioning through technological sophistication, while consumable-focused players compete on distributor network density and cold-chain reliability. Strategic archetypes include integrated device-consumable suppliers, specialized training academy operators, and pharmaceutical distributors with regulatory dossier expertise. Dominant competitive moves center on specialized training academy models that embed device-specific certification programs, and secondary city penetration strategies targeting Cali, Barranquilla, and Bucaramanga markets.
Within the integrated device tier, Alma Lasers Ltd and Lumenis exemplify capital-intensive positioning through multi-wavelength platform dominance in Bogotá's clinic corridor. Merz Aesthetics occupies a position within the consumable-specialist archetype, sustaining channel relationships through dermatology network partnerships. Among pharmaceutical distributors with regulatory infrastructure, Johnson & Johnson represents established registrant advantages under INVIMA's harmonization initiatives. These three companies illustrate how regulatory dossier expertise and training academy lock-in effects separate sustainable market access from distributor-dependent positioning.
| Leading Market Players |
|---|
| Cutera Inc |
| Fotona |
| Alma Lasers Ltd |
| Lumenis |
| Candela Medical |
| Cynosure |
| Merz Aesthetics |
| Johnson & Johnson |
| Allergan |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with Bogotá-based regulatory infrastructure providers lock in both INVIMA dossier access and predictable landed cost structures for hyaluronic acid fillers and multi-wavelength laser systems entering Colombia's facial aesthetics market.
Pricing Analysis
Consumable replenishment contracts drive lifetime value for dermal filler and botulinum toxin suppliers serving Colombia's aesthetic centers. Three-tier pricing structure across premium, standard, and economy levels separates Alma Lasers' multi-wavelength platforms from mid-market radiofrequency-fractional systems and entry-level chemical peel modalities. Cost compression in the injectable tier intensifies because cold-chain logistics elevate landed costs for imported biologics. First-time aesthetic consumers in Cali and Barranquilla show highest price sensitivity, while Bogotá's financial district clinics demonstrate lowest sensitivity for bundled rejuvenation protocols.
Supply Chain Analysis
Just-in-time inventory preferences dominate consumable injectables, while strategic stockpiling of laser system spare parts mitigates extended lead times for specialized optical components. Manufacturing concentration for hyaluronic acid fillers rests on Switzerland, South Korea, and the United States, with radiofrequency device assembly centering on Israel and Germany. Supply chain vulnerability stems from single-source dependency for precision laser optics and fractional handpiece components. Distribution runs through pharmaceutical distributors with cold-chain certification for injectables, while capital equipment moves through direct manufacturer relationships with Bogotá and Medellín clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's facial aesthetics market sits in a medical tourism-driven expansion cycle that favors regulatory-dossier-equipped suppliers with established INVIMA infrastructure.
For Market Incumbents: Consolidate position by acquiring secondary city distributor networks in Cali, Barranquilla, and Bucaramanga before branded clinic networks establish first-mover presence. Deepen vertical integration into cold-chain logistics to defend margin position against rising import documentation complexity under INVIMA harmonization initiatives. For New Entrants and Emerging Players: Differentiate on specialized training academy models that embed device-specific certification programs within Antioquia's expanding dermatology network. Target acne scar treatment applications in Bucaramanga and skin tightening procedures in secondary cities where capital intensity requirements exclude laser-only competitors. Pursue direct-to-clinic digital booking platform partnerships to bypass traditional dermatology referral channels losing share in Medellín's El Poblado corridor. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors consumable-specialist archetypes with regulatory dossier expertise over capital-intensive device manufacturers. Long-term viability hinges on INVIMA registration asset durability and dermatology network lock-in effects. Watch for adverse-event reporting infrastructure investments as the signal indicating which clinic operators will survive compliance inspections.| Strategic Initiative | Industry Significance |
|---|---|
| INVIMA Dossier Acceleration | Compresses registration timelines for dermal fillers and laser systems entering through El Dorado logistics corridors. |
| Secondary City Clinic Network Expansion | Captures first-mover positioning in Cali, Barranquilla, and Bucaramanga markets with lower competitive density. |
| Specialized Training Academy Partnership | Locks in recurring equipment purchases through dermatology network certification program embedding. |
| Radiofrequency-Fractional Platform Launch | Displaces older CO2 devices in Bogotá's financial district through combination technology bundling. |
| Cold-Chain Distribution Infrastructure Investment | Reduces landed cost vulnerability for hyaluronic acid fillers requiring temperature-controlled logistics. |
Research Methodology
The analysis maps injectable products, energy-based devices, chemical peels, and combination treatment protocols, each validated through dermatology network directors, aesthetic center procurement managers, biomedical equipment distributors, and INVIMA regulatory consultants. Primary interview findings triangulate against secondary sources including INVIMA medical device registry filings, Ministry of Health cosmetic procedure guidelines, El Dorado International customs import records, and hospital procurement databases. Bottom-up clinic-level procedure volume estimates reconcile with top-down pharmaceutical distributor shipment data.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user category, application objective, and technology approach, with regional regulatory cluster and capital intensity tier as cross-cutting variables. CAGRs derive from procedure volume elasticity coefficients and per-visit revenue trajectories, incorporating medical tourism flow projections and urban middle-class expansion patterns as industry-specific forecast inputs.
Material uncertainties — INVIMA harmonization timeline shifts, cold-chain logistics cost volatility, and adverse-event reporting enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory modernization pace and clinic compliance infrastructure investment. Revision becomes warranted when medical tourism patient volume from Venezuela, Ecuador, or Peru crosses thresholds that strain Bogotá and Medellín aesthetic center capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market