
 Dual and Multi-Energy Computed Tomography (CT) Market | 2026-2036
Dual and Multi-Energy Computed Tomography (CT) Market Size, Share, and Industry Trends Forecast 2026-2036
Dual and Multi-Energy Computed Tomography (CT) Market Foresight
The EU Medical Device Regulation is consolidating procurement standards across European hospital networks, forcing vendors to recertify spectral imaging platforms under stricter clinical evidence requirements. Siemens Healthineers leverages its photon-counting detector manufacturing scale to anchor supply commitments with German university hospitals. GE Healthcare competes through dual-source architecture specialization in North American cardiac imaging centers. Canon Medical Systems Corporation differentiates via iterative reconstruction software integration with existing scanner fleets.
Dual and multi-energy CT refers to imaging systems that acquire attenuation data at two or more distinct energy spectra, typically through dual-source x-ray tubes, rapid kVp switching, or photon-counting detector layers with cadmium zinc telluride semiconductors, enabling material decomposition for improved tissue characterization and reduced beam-hardening artifacts. Photon-counting technology leads investment allocation due to its superior dose efficiency and spatial resolution, while energy-discriminating platforms sustain margin pools in retrofit markets. Software solutions represent the fastest-growing product category as hospitals prioritize AI-enhanced spectral reconstruction workflows over hardware replacement cycles.
The FDA's radiation safety mandates and the EU MDR clinical evidence framework jointly shape product development timelines and market access conditions for spectral CT manufacturers. ISO 13485 quality management standards govern manufacturing consistency across component suppliers in Japan and South Korea. Stakeholders must monitor reimbursement coding decisions for spectral CT-specific procedures, as these will determine hospital capital allocation priority relative to conventional advanced imaging modalities.
Market Dynamics
Photon-counting detector arrays are compressing hardware replacement cycles while spectral reconstruction software captures expanding margin pools from installed base monetization.
Growth Catalysts
- FDA Radiation Dose Optimization:The agency's ongoing refinement of exposure standards forces hospital procurement committees to prioritize dose-efficient platforms, accelerating spectral CT validation protocols in academic medical centers.
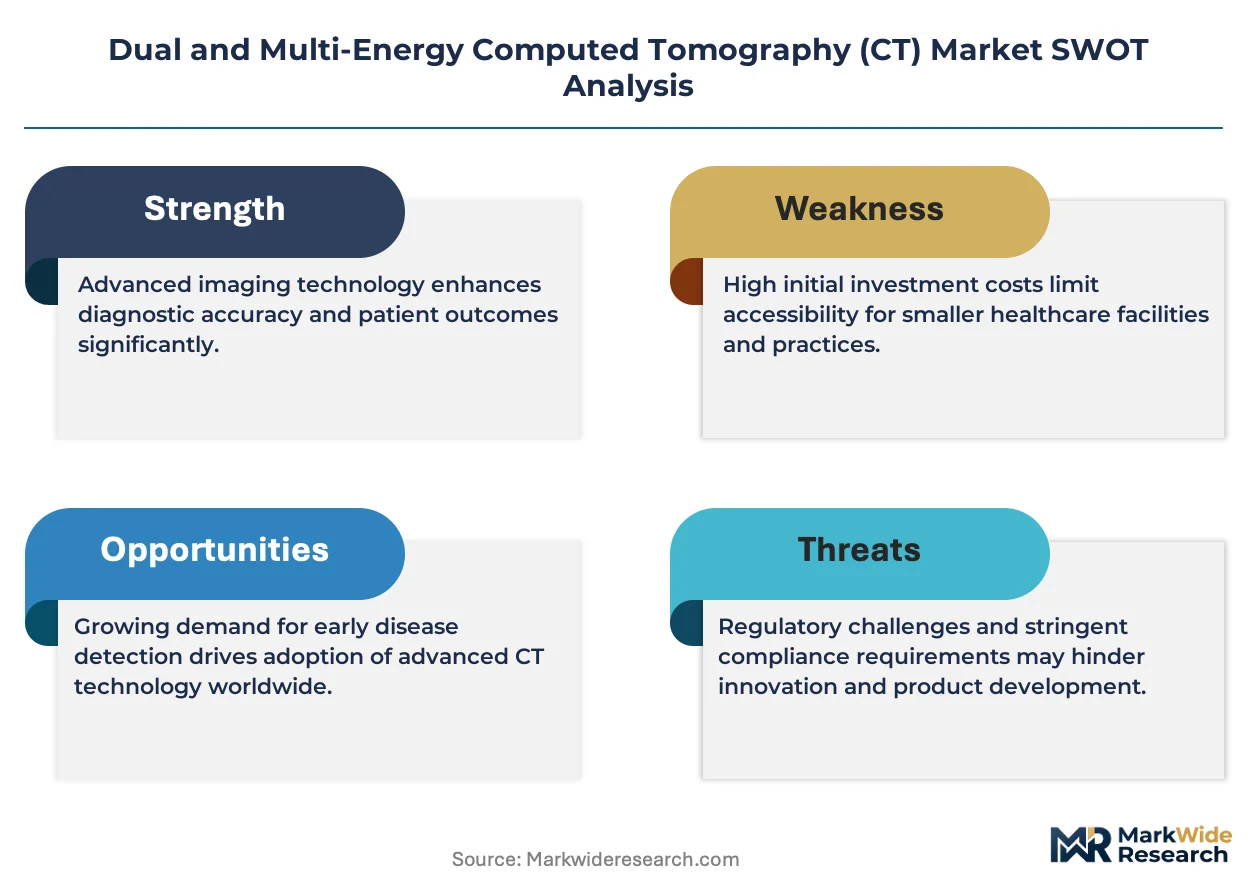
- Oncology Department Expansion:Tertiary hospitals in the United States are deploying spectral imaging protocols for tumor characterization, creating concentrated demand for material decomposition capabilities.
- Cadmium Zinc Telluride Semiconductors:Advances in semiconductor fabrication are improving photon-counting detector yield rates, reducing unit economics for energy-discriminating hardware.
Market Restraints
- Capital Intensity:Photon-counting detector manufacturing requires specialized cleanroom infrastructure, concentrating supply risk among a limited supplier base in Japan and South Korea.
- EU MDR Recertification Burden:The Medical Device Regulation's stricter clinical evidence requirements are extending product approval timelines by 18-24 months for spectral imaging platforms.
- Technical Limitation:Beam-hardening artifact reduction algorithms remain computationally intensive, requiring dedicated GPU clusters that inflate total cost of ownership for mid-tier hospitals.
Strategic Opportunities
- Retrofit Software Markets:Iterative reconstruction solutions enable spectral capability deployment on existing scanner fleets without hardware replacement, opening revenue streams from installed base monetization.
- Cardiac Imaging Centers:North American specialty clinics represent underpenetrated demand for dual-source architecture applications in coronary plaque characterization.
- Reimbursement Coding Tailwinds:Pending CPT code decisions for spectral CT-specific procedures will determine hospital capital allocation priority relative to conventional advanced imaging modalities.
Industry Challenges
- Workflow Integration Complexity:AI-enhanced spectral reconstruction requires radiologist retraining and PACS system upgrades, creating adoption friction in community hospital settings.
- ISO 13485 Compliance Timeline:Component suppliers must maintain quality management certification across fragmented manufacturing footprints, delaying supply chain scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual and Multi-Energy Computed Tomography (CT) Market |
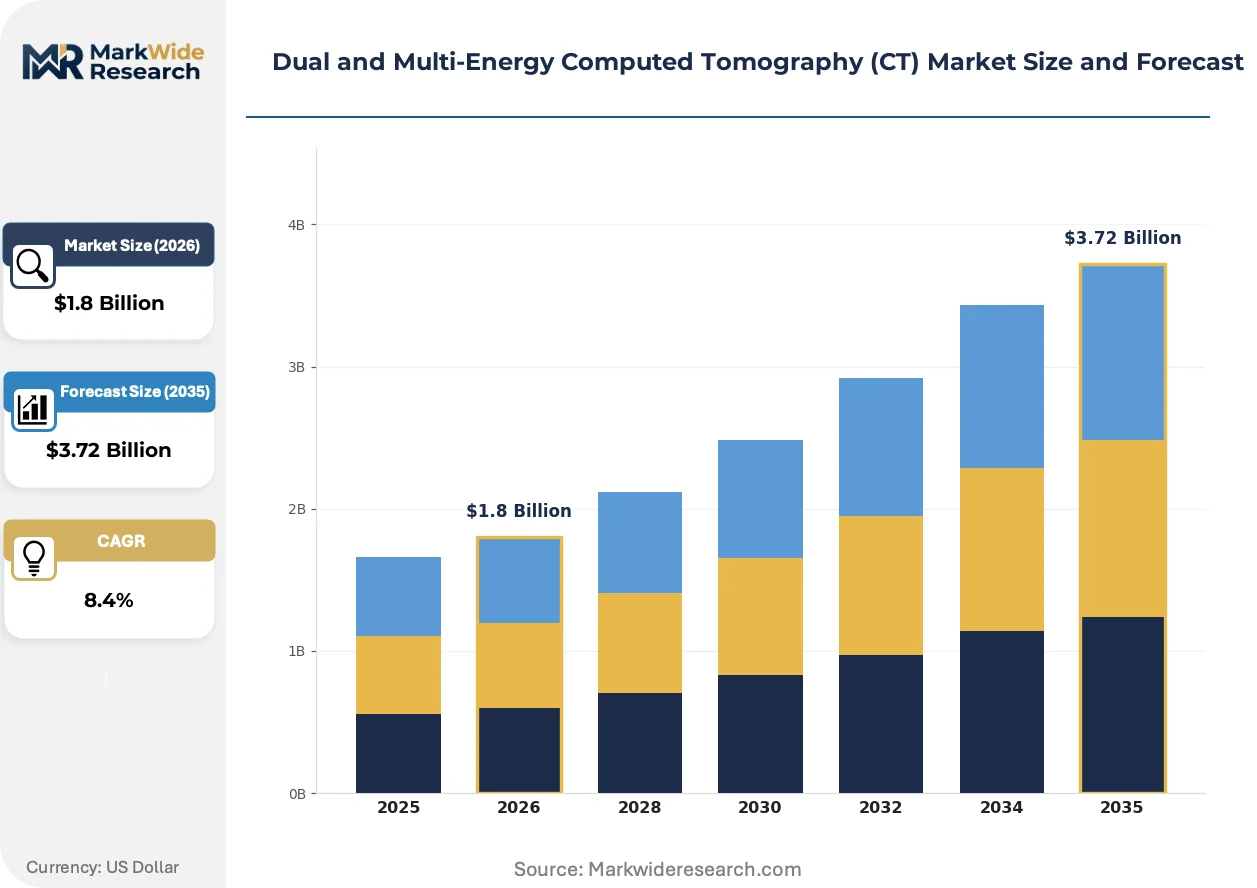
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photon Counting, Energy Discriminating, Iterative Reconstruction, Dual Source Product Type: Clinical Systems, Mobile CT Scanners, Accessories, Software Solutions End User: Hospitals, Imaging Centers, Research Institutions, Specialty Clinics Application: Oncology, Cardiovascular Imaging, Neurology, Musculoskeletal |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Shimadzu Corporation, Hitachi Ltd, Neusoft Medical Systems Co. Ltd, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual and Multi-Energy Computed Tomography (CT) Market Shifts & Advancements
Spectral CT technology trajectories center on detector physics advances, regulatory evidence frameworks, and procurement model evolution in hospital capital planning.
Photon-counting detector layers with cadmium zinc telluride semiconductors are integrating energy-resolved data acquisition directly into detector hardware, bypassing conventional scintillator-photodiode architectures. Academic medical centers in Germany and the United States are piloting these platforms for ultra-low-dose protocols. This integration is compressing the performance gap between premium-tier and mid-tier scanner configurations, forcing vendors to differentiate through software rather than raw hardware specifications.
The EU Medical Device Regulation's clinical evidence requirements are mandating prospective validation studies for material decomposition algorithms, extending development timelines but raising barriers to entry for software-only competitors. Manufacturers must now submit patient outcome data alongside technical performance metrics. German university hospitals are responding by consolidating procurement through framework agreements that bundle equipment, training, and longitudinal validation commitments.
Hospital capital committees are unbundling after-sales service contracts from equipment purchases, negotiating software maintenance and detector calibration as separate line items. This disintermediation pressures vendor margin structures while creating openings for third-party spectral reconstruction software providers. The pattern is most visible in United States academic medical centers, where CIOs are prioritizing interoperability with existing enterprise imaging archives over single-vendor ecosystem lock-in.
Dual and Multi-Energy Computed Tomography (CT) Market Segmentation
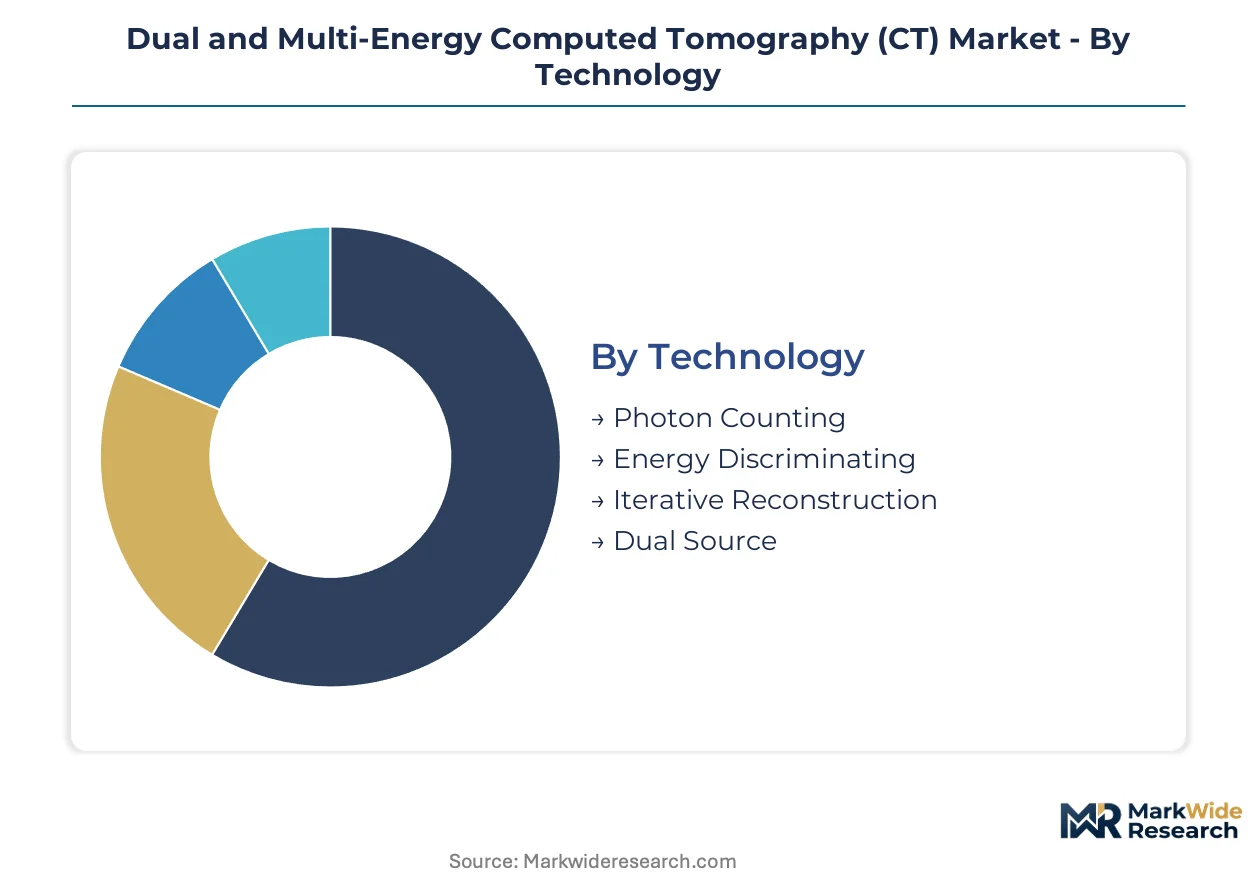
Spectral CT procurement patterns diverge sharply across technology generations and deployment settings. Hospital capital committees weight dose efficiency against total cost of ownership when segmenting vendor proposals. Understanding these fault lines clarifies where margin pools concentrate and which segments compress replacement cycles.
Technology:
Supply concentration in detector fabrication determines which platforms scale economically versus which remain boutique deployments.
- Photon Counting:Cadmium zinc telluride semiconductor layers enable energy-resolved data acquisition directly at the detector plane, bypassing conventional scintillator architectures. Academic medical centers in the United States and Germany are piloting ultra-low-dose protocols on these platforms, though cleanroom manufacturing constraints in Japan and South Korea limit supplier diversity.
- Energy Discriminating:Rapid kVp switching between high and low tube potentials generates dual-energy datasets without specialized detector hardware. Mid-tier hospitals in community settings favor this approach for its retrofit compatibility with existing gantry infrastructure, even as dose efficiency lags photon-counting alternatives.
- Iterative Reconstruction:Algorithmic noise reduction and spectral decomposition executed through GPU-accelerated compute clusters.
- Dual Source:Orthogonal x-ray tube pairs acquiring simultaneous high and low energy projections.
Today's leader: Photon Counting. Tomorrow's challenger: Iterative Reconstruction.
Product Type:
Cost tier stratification separates capital-intensive hardware from recurring software revenue streams.
- Clinical Systems:Fixed-installation spectral CT platforms with integrated detector arrays, reconstruction engines, and patient handling subsystems. Tertiary hospitals in the United States concentrate procurement here, driven by oncology department expansion and FDA radiation dose optimization mandates.
- Software Solutions:AI-enhanced spectral reconstruction workflows deployable across heterogeneous scanner fleets. This segment captures expanding margin pools as hospital CIOs prioritize interoperability with existing PACS archives over single-vendor ecosystem lock-in.
- Mobile CT Scanners:Self-contained spectral-capable units with integrated power and climate systems for point-of-care deployment.
- Accessories:Detector calibration phantoms, contrast injection protocols, and spectral-specific patient positioning aids.
Software Solutions are climbing the fastest as hospitals defer hardware replacement cycles.
End User:
Customer type dictates procurement authority structure and validation evidence requirements.
- Hospitals:Integrated delivery networks with centralized capital committees and enterprise imaging archives. These buyers negotiate unbundled service contracts and demand ISO 13485 compliance documentation across component supply chains.
- Imaging Centers:Outpatient facilities with high throughput requirements and price-sensitive equipment financing.
- Research Institutions:Academic medical centers conducting prospective validation studies for material decomposition algorithms under EU MDR frameworks.
- Specialty Clinics:Cardiac imaging centers in North America pursuing coronary plaque characterization applications.
Volume concentrates with Hospitals. Margin concentrates with Specialty Clinics.
Application:
Maturity gradients separate established reimbursement pathways from emerging clinical evidence bases.
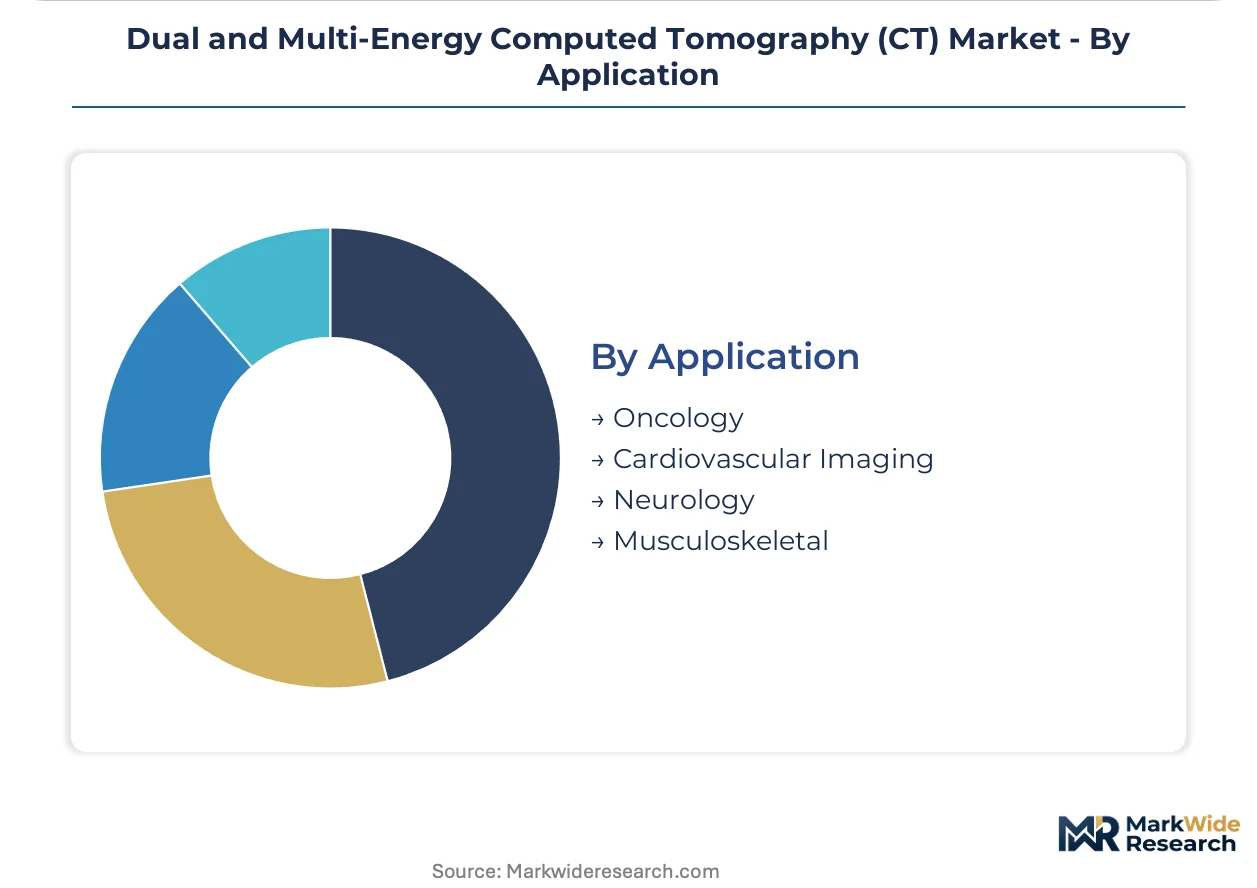
- Oncology:Material decomposition for tumor characterization and treatment response monitoring. United States tertiary hospitals are expanding spectral protocol adoption here, though CPT code finalization for spectral-specific procedures remains pending.
- Cardiovascular Imaging:Coronary plaque composition analysis and myocardial perfusion quantification. North American specialty clinics represent underpenetrated demand for dual-source architecture in this domain.
- Neurology:Cerebral perfusion imaging and hemorrhage characterization through iodine mapping.
- Musculoskeletal:Gout crystal deposition detection and bone marrow edema quantification.
Oncology holds current share. Cardiovascular Imaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spectral CT technology originated in German university hospitals during the early 2000s, with Siemens Healthineers pioneering dual-source architecture in Erlangen. Academic medical centers across four countries now anchor clinical validation and procurement concentration.
United States
Oncology departments at tertiary hospitals in Boston and Houston are expanding spectral imaging protocols for tumor characterization. FDA radiation dose optimization mandates are reshaping procurement criteria toward dose-efficient platforms. Academic medical centers in the Research Triangle and Greater Cleveland lead photon-counting detector array validation studies.
Germany
University hospitals in Munich and Heidelberg anchor framework agreements bundling equipment, training, and longitudinal validation commitments. EU MDR recertification requirements are extending product approval timelines for spectral imaging platforms. The Erlangen-Dresden corridor concentrates photon-counting detector manufacturing scale and supply commitments.
Japan
Cleanroom infrastructure for cadmium zinc telluride semiconductor fabrication concentrates in Osaka and Nagoya industrial zones. METI quality management standards govern manufacturing consistency across component suppliers. Tokyo academic medical centers are piloting ultra-low-dose protocols on next-generation detector platforms.
South Korea
MFDS certification timelines are synchronizing with ISO 13485 compliance requirements for detector component exports. Seoul National University Hospital and Samsung Medical Center are conducting prospective validation studies for material decomposition algorithms. The Pangyo Techno Valley cluster houses specialized semiconductor fabrication facilities serving spectral CT supply chains.
United Kingdom
Imaging centers in London and Manchester are negotiating unbundled service contracts separating software maintenance from hardware purchases. NHS England procurement frameworks are prioritizing interoperability with existing enterprise imaging archives. The Oxford-Cambridge arc hosts radiology research consortia evaluating AI-enhanced spectral reconstruction workflows.
Dual and Multi-Energy Computed Tomography (CT) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detector technology specialization and software integration depth. The vendor base stratifies into three tiers: integrated imaging conglomerates with captive semiconductor fabrication, mid-tier hardware specialists licensing reconstruction algorithms, and pure-play software vendors targeting retrofit markets. Dominant competitive moves include strategic partnerships between detector manufacturers and academic medical centers for clinical validation, plus portfolio diversification into AI-enhanced reconstruction workflows.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare occupy positions at the premium-tier vector, with the former exemplifying photon-counting detector manufacturing scale and the latter representing dual-source architecture specialization. Canon Medical Systems Corporation sits within the integrated imaging systems tier, anchoring iterative reconstruction software integration strategies for existing scanner fleet deployments.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Shimadzu Corporation |
| Hitachi Ltd |
| Neusoft Medical Systems Co. Ltd |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Cleanroom semiconductor fabrication specialists concentrated in Osaka and Nagoya widen cost spreads between premium photon-counting platforms and retrofit-compatible energy-discriminating systems. Labor-cost differentials in Japanese and South Korean detector manufacturing anchor pricing tiers while European MDR compliance investments compress margins on mid-tier hardware.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photon-counting platforms with integrated AI reconstruction from dual-source hardware and retrofit software licenses. Price differentiation hinges on FDA 510(k) clearance tier and bundled after-sales service scope. Cost compression in the standard tier intensifies because academic medical centers unbundle maintenance contracts. Community hospitals exhibit highest price sensitivity, while German university hospitals accept premium positioning for longitudinal validation commitments.
Supply Chain Analysis
Regional distribution centers in Tokyo, Seoul, and Erlangen operate hub-and-spoke patterns for detector component fulfillment. Supply concentrates in Japan and South Korea for cadmium zinc telluride semiconductor fabrication, with Germany anchoring dual-source gantry assembly. Raw material dependencies include high-purity tellurium, specialized ceramic substrates, and rare-earth scintillator crystals. Single-source vulnerability in Japanese cleanroom infrastructure represents the dominant structural risk. Distribution runs through authorized service depots tied to hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector yield improvements and software retrofit monetization create margin expansion headroom. Cost-down trajectories in semiconductor fabrication enable premium-tier volume scaling without price erosion.
For Market Incumbents: Acquire spectral reconstruction software assets to defend against pure-play AI vendors unbundling hardware replacement cycles. Siemens Healthineers and GE Healthcare should deepen captive supply of cadmium zinc telluride semiconductors through South Korean partnership structures. ISO 13485 certification investments across fragmented supplier footprints remain essential to EU MDR compliance timelines. For New Entrants and Emerging Players: Begin with iterative reconstruction algorithms deployable on Canon and GE installed bases in United States community hospitals. Cardiac imaging centers in North America represent the most penetrable white-space for dual-source architecture applications. Pursue GPO contract positioning through interoperability demonstrations with existing PACS archives rather than single-vendor ecosystem plays. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier energy-discriminating hardware specialists lacking photon-counting roadmaps. Long-term viability across the analysis window favors vendors with software recurring revenue above 40% of total sales. Watch FDA reimbursement coding decisions for spectral CT-specific CPT procedures as the critical inflection signal for hospital capital allocation priority.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Scale-Up | Cadmium zinc telluride yield improvements compress unit economics for academic medical center procurement. |
| AI-Enhanced Reconstruction Partnership | Third-party algorithm integration with Siemens and GE platforms opens retrofit revenue without hardware replacement. |
| EU MDR Clinical Validation Consortium | German university hospital framework agreements bundle longitudinal outcome studies with equipment procurement. |
| Reimbursement Strategy Development | CPT code advocacy for spectral-specific procedures determines hospital capital committee priority ranking. |
| Interoperability Certification Program | PACS integration standards from United States academic medical centers reduce vendor lock-in friction. |
Research Methodology
Coverage spans the United States, Germany, Japan, and South Korea, with primary inputs from each market cluster. The analysis combines structured interviews with hospital purchasing committee directors, biomedical engineers at academic medical centers, GPO contracts managers, and spectral CT vendor product strategists. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement records. Bottom-up scanner shipment tracking and top-down imaging equipment capex triangulation anchor volume estimates.
Rate-of-change decomposition separates hardware replacement cycle compression from software attach-rate expansion across the projection horizon. Segmentation dimensions modeled include detector technology tier, product type, end-user procurement authority structure, and clinical application maturity. CAGRs derive from installed base growth, upgrade penetration curves, and pricing trajectory assumptions. Industry-specific forecast inputs incorporate photon-counting detector yield improvement curves and EU MDR approval timeline distributions.
Several conditions sit outside the modeled scope, including tariff regime shifts on Japanese semiconductor exports and breakthrough non-CT imaging modalities displacing spectral protocols. Forecasts reflect documented assumptions around reimbursement coding finalization and cleanroom manufacturing capacity scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
C-Arms Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Digital Mammography Market