
 Non-Invasive Aesthetic Treatment Market | 2026-2036
Non-Invasive Aesthetic Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Aesthetic Treatment Market Intelligence
Market Context
South Korea is rewriting competitive dynamics in non-invasive aesthetics through its unmatched concentration of training institutions and device manufacturing clusters. AbbVie leverages its Allergan Aesthetics portfolio to dominate injectable neurotoxin and filler segments across North American dermatology practices. Galderma sustains R&D intensity in biostimulatory fillers, while Alma Lasers anchors geographic reach through direct sales subsidiaries in over ninety countries.
Technical Definition and Segment Structure
Non-invasive aesthetic treatment encompasses energy-based and injectable modalities that alter skin appearance or subcutaneous tissue without incision, typically operating at wavelengths between 532 nm and 10,600 nm or utilizing acoustic/mechanical energy below ablative thresholds. The primary commercial purpose centers on collagen remodeling, adipocyte reduction, or neuromuscular modulation for cosmetic enhancement with minimal recovery intervals. Injectable dermal fillers capture the deepest margin pools due to repeat purchase cycles and practitioner loyalty, while laser treatments compete on device utilization rates per clinic. RF technology for skin tightening represents the fastest-growing technology segment as combination protocols with microneedling expand addressable indications.
Regulatory Framework
FDA 510(k) clearances govern energy-based device market access in the United States, while the EU MDR imposes stricter clinical evidence requirements for aesthetic devices sold in European markets. China's NMPA maintains separate registration pathways that delay Western product launches by twelve to twenty-four months. Stakeholders must monitor evolving reimbursement classifications as some jurisdictions begin covering medically indicated scar revision and hair removal under expanded cosmetic-to-medical indication bridges.
Market Dynamics
Energy-based device manufacturers face margin compression as RF-microneedling combination systems commoditize faster than single-modality platforms, forcing R&D cycles to compress from thirty-six to eighteen months for competitive parity.
Growth Catalysts
- Preventative demographics:Med-spa chains in the United States report patients under thirty-five now constitute forty percent of first-time consults, expanding addressable lifetime value per client through earlier entry into maintenance protocols.
- FDA 510(k) pathway acceleration:Streamlined predicate device clearances for fractional laser systems have reduced average submission-to-clearance timelines, enabling faster commercialization of wavelength-optimized platforms for melanin-rich skin types.
- South Korean training infrastructure:Seoul's concentration of hands-on certification academies produces practitioner density that sustains procedure volume leadership and creates exportable clinical training standards.
Market Restraints
- Consumable cost concentration:Hyaluronic acid filler raw material supply clusters in Chinese fermentation facilities expose injectable manufacturers to input price volatility and geographic concentration risk.
- EU MDR clinical evidence burden:Stricter post-market surveillance requirements for energy-based devices sold in European markets demand expanded safety datasets that delay product launches by twelve to eighteen months.
- Non-ablative efficacy ceiling:Patient expectations for single-session results often exceed achievable outcomes from sub-threshold energy delivery, driving dissatisfaction and refund rates in fractional laser segments.
Strategic Opportunities
- India's nascent clinic infrastructure:Tier-two Indian cities present whitespace for device leasing models that lower capital barriers for dermatology practices entering aesthetic services.
- Biostimulatory filler convergence:Poly-L-lactic acid and calcium hydroxylapatite formulations combined with hyaluronic acid carriers address unmet demand for collagen induction with immediate volume correction.
- Telemedicine pre-screening protocols:Remote consultation platforms reduce no-show rates and optimize in-clinic utilization, particularly for time-intensive body contouring treatment series.
Industry Challenges
- Practitioner certification fragmentation:Inconsistent state-level licensing requirements for energy-based device operation in the United States create liability exposure and training standard gaps.
- Device utilization rate optimization:High capital intensity of multi-platform installations demands patient throughput modeling that conflicts with personalized treatment planning time requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Aesthetic Treatment Market |
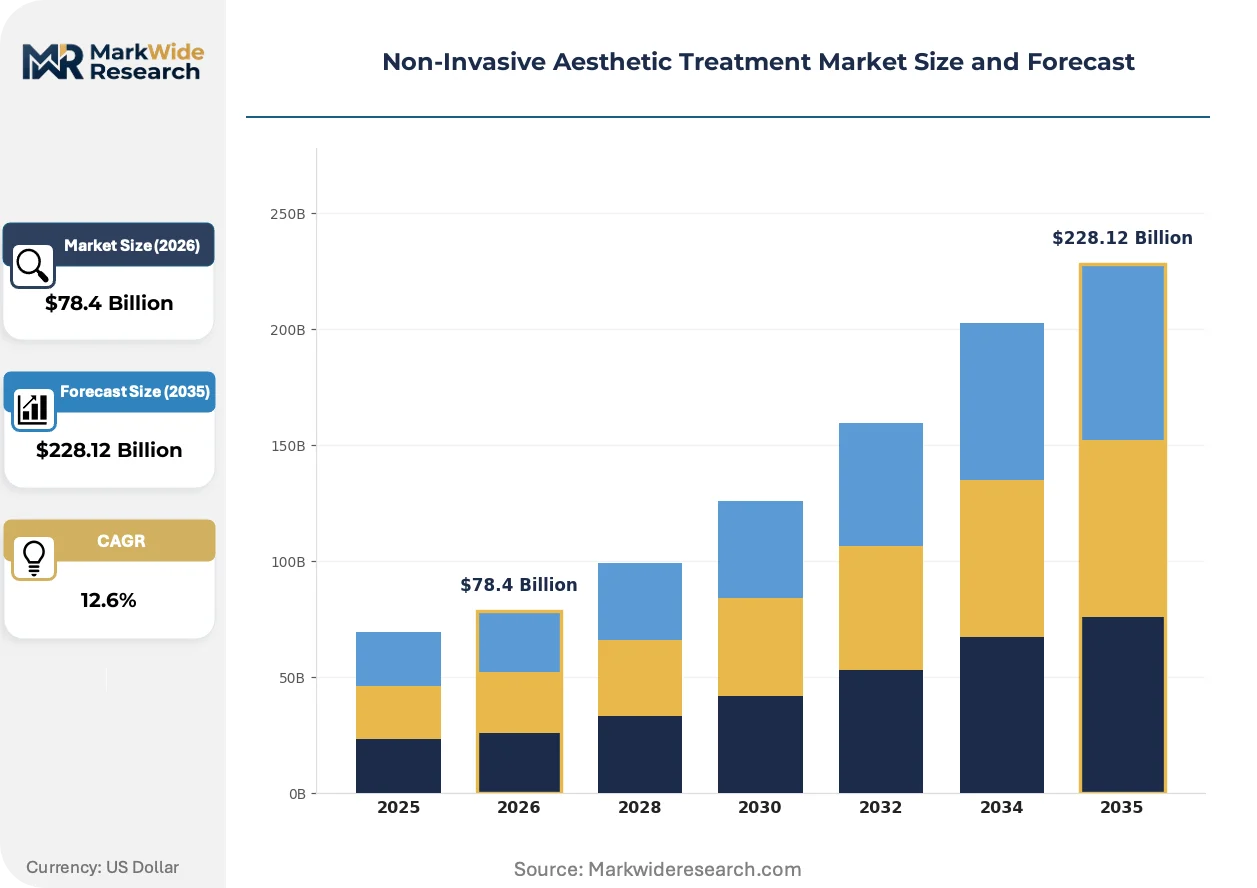
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $228.12 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Treatments, Injectable Dermal Fillers, Chemical Peels, Ultrasound Therapy Technology: RF Technology, Laser Technology, Microdermabrasion, Cryotherapy Application: Skin Tightening, Facial Rejuvenation, Hair Removal, Scar Treatment End User: Aesthetic Clinics, Dermatology Practices, Spas, Home Users |
| Companies Covered | AbbVie, Galderma, Merz Pharma, Hologic, Allergan Aesthetics, Alma Lasers, Cutera, Lumenis, Syneron Candela, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Aesthetic Treatment Market Strategic Shifts & Innovations
Convergence between acoustic energy and radiofrequency delivery systems is collapsing the distinction between standalone modalities, reshaping how clinics configure treatment rooms and amortize capital expenditure across indications.
Picosecond laser technology with 755 nm and 1064 nm wavelength switching is rendering obsolete nanosecond-domain devices for tattoo removal and benign pigmented lesion treatment. Dermatology practices in metropolitan United States markets are replacing legacy Q-switched platforms at replacement cycles compressed to twenty-four months. The structural consequence is collapsing resale values for first-generation picosecond systems and accelerated obsolescence risk for equipment financing portfolios.
China's NMPA has implemented separate registration pathways for aesthetic energy devices that mandate domestic clinical trials, creating regulatory friction for Western manufacturers. This policy construct forces parallel development tracks and localized evidence generation that extends time-to-revenue by eighteen to twenty-four months. Multinational device firms are responding through joint venture structures with domestic distributors to access NMPA clearance expertise and investigator networks.
Subscription-based consumable purchasing is displacing transactional filler ordering in high-volume North American med-spa chains. This procurement model locks in volume commitments that secure preferential unit pricing and priority allocation during supply constraints. The shift is most pronounced in California and Texas markets where chain consolidation has produced buyer concentration sufficient to negotiate enterprise terms with Allergan Aesthetics and Galderma direct sales organizations.
Non-Invasive Aesthetic Treatment Market Segmentation
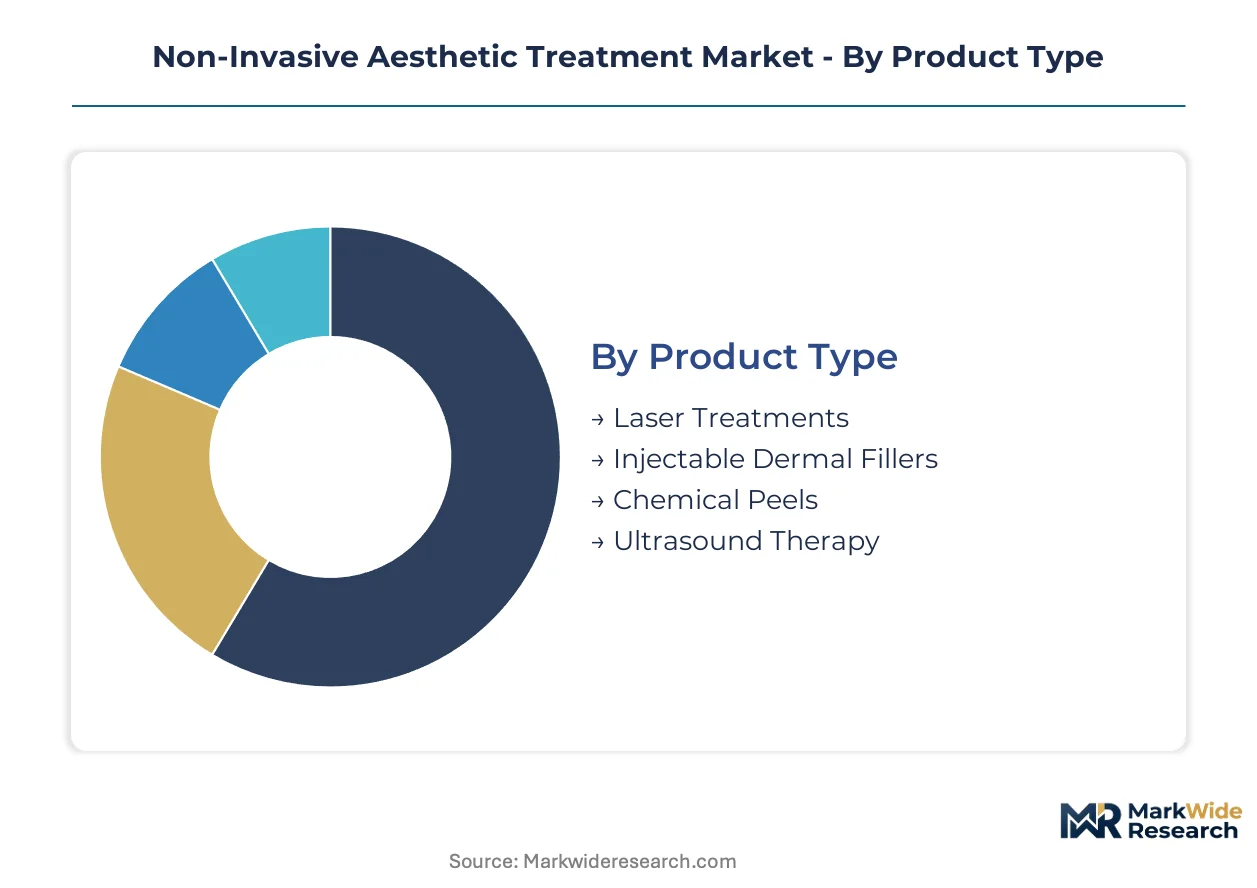
Non-invasive aesthetic treatments fragment across four distinct dimensions that determine capital deployment, regulatory pathway, and margin structure. Product type dictates consumable economics versus device utilization models. Technology selection shapes wavelength or energy platform R&D priorities. Application focus drives indication-specific clinical training investments. End user category determines sales channel configuration and pricing power.
Product Type:
Cost tier stratification separates capital-intensive platform purchases from recurring consumable revenue streams.
- Injectable Dermal Fillers:Hyaluronic acid, poly-L-lactic acid, and calcium hydroxylapatite formulations deliver immediate volume correction through subcutaneous injection. Repeat purchase cycles in South Korean and US dermatology practices sustain manufacturer loyalty programs and subscription procurement models.
- Laser Treatments:Energy-based platforms operating at 532 nm to 10,600 nm wavelengths address pigmentation, vascular lesions, and resurfacing through selective photothermolysis. Device utilization rates per clinic in metropolitan US markets determine financing viability and replacement cycle timing.
- Chemical Peels:Acid-based exfoliation solutions ranging from superficial alpha-hydroxy to deep phenol formulations. Med-spa chains favor superficial variants for throughput optimization.
- Ultrasound Therapy:Microfocused and high-intensity focused ultrasound systems targeting adipocyte disruption and collagen remodeling. Adoption concentrates in premium clinic tiers.
Injectable dermal fillers command the established base. The steepest expansion runs through laser treatments.
Technology:
Application specificity determines whether modalities compete as standalone platforms or converge into combination systems.
- RF Technology:Radiofrequency energy delivery at 0.3-40 MHz frequencies generates dermal heating for collagen contraction and neocollagenesis. Microneedling combination protocols in US aesthetic clinics are expanding addressable indications beyond monopolar and bipolar standalone systems.
- Laser Technology:Coherent light sources spanning ablative CO2 to non-ablative fractional erbium platforms. Picosecond-domain devices with 755 nm and 1064 nm wavelength switching are displacing nanosecond systems for tattoo removal in dermatology practices.
- Microdermabrasion:Mechanical exfoliation using aluminum oxide crystals or diamond-tipped abrasion. Spas deploy this entry-level modality to reduce patient acquisition costs.
- Cryotherapy:Controlled cooling applications for fat cell apoptosis and skin lesion treatment. Home-use devices are compressing professional procedure margins.
RF technology commands the established base. The steepest expansion runs through laser technology platform upgrades.
Application:
Customer lifetime value varies sharply between one-time corrective procedures and recurring maintenance protocols.
- Facial Rejuvenation:Comprehensive treatment protocols combining neuromodulators, fillers, and energy-based modalities to address rhytides, volume loss, and skin laxity. Preventative demographics in US med-spa chains under thirty-five are expanding addressable lifetime value through earlier maintenance entry.
- Skin Tightening:Non-surgical lifting procedures using ultrasound, RF, or infrared energy to stimulate collagen remodeling. Combination protocols with microneedling in South Korean clinics are setting clinical training standards for global export.
- Hair Removal:Laser and IPL-based permanent hair reduction across Fitzpatrick skin types I-VI. FDA 510(k) pathway acceleration for melanin-rich skin optimization is expanding addressable populations.
- Scar Treatment:Fractional laser and RF-microneedling protocols for acne, surgical, and traumatic scar revision. Some jurisdictions are beginning expanded reimbursement classification for medically indicated cases.
Facial rejuvenation commands the established base. The steepest expansion runs through skin tightening combination protocols.
End User:
Channel structure determines whether manufacturers deploy direct sales, distributor networks, or retail partnerships.
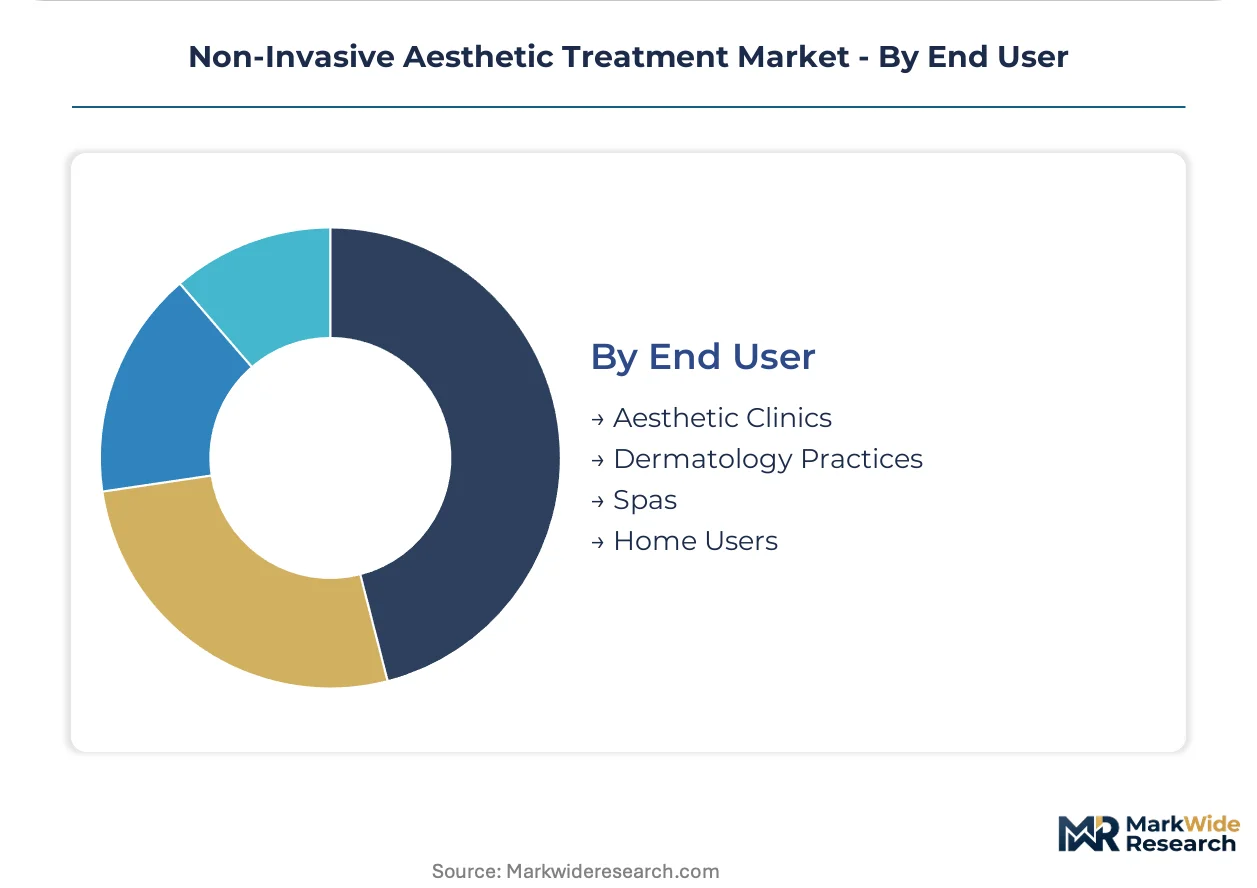
- Dermatology Practices:Board-certified dermatologists with procedural training privileges accessing full energy-based and injectable portfolios. AbbVie and Galderma direct sales organizations prioritize this channel for high-margin neurotoxin and biostimulatory filler distribution in North America.
- Aesthetic Clinics:Physician-supervised facilities specializing in cosmetic procedures with lower overhead than dermatology practices. Device leasing models in tier-two Indian cities are lowering capital barriers for market entry.
- Spas:Wellness-focused facilities limited to superficial modalities and skincare retail. Regulatory fragmentation across US state licensing requirements creates liability exposure.
- Home Users:Consumer-grade devices for low-intensity LED, microcurrent, and cooling applications. E-commerce direct-to-consumer channels are displacing professional procedure frequency for maintenance-minded patients.
Dermatology practices command the established base. The steepest expansion runs through aesthetic clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. South Korean patients pursue preventative maintenance protocols starting in their twenties. US demand clusters around corrective interventions in metropolitan dermatology practices. European markets emphasize evidence-based reimbursement pathways for medically indicated procedures.
United States
Med-spa chains in California and Texas now derive forty percent of first-time consults from patients under thirty-five, shifting lifetime value calculations toward earlier maintenance entry. FDA 510(k) clearances for energy-based devices have compressed submission-to-clearance timelines, accelerating wavelength-optimized platforms for melanin-rich skin types. Metropolitan dermatology practices in New York and Los Angeles anchor device utilization rate modeling for fractional laser financing viability.
South Korea
Clinic density per capita in Seoul sustains the world's highest procedure volume leadership through cultural normalization of maintenance aesthetics. MFDS registration pathways for novel energy devices operate with streamlined predicate approvals that shorten time-to-market for domestic manufacturers. The Gangnam district concentration of hands-on certification academies produces exportable clinical training standards now licensed across Southeast Asian markets.
China
Tier-one cities including Shanghai and Beijing demonstrate accelerating demand for combination RF-microneedling protocols among affluent demographics. NMPA mandates domestic clinical trials for aesthetic energy devices, forcing parallel development tracks that extend Western product launches by eighteen to twenty-four months. Domestic device manufacturers in the Yangtze River Delta are capturing share through joint venture structures with multinational distributors seeking NMPA clearance expertise.
Germany
Dermatology practices in Bavaria and North Rhine-Westphalia emphasize biostimulatory filler protocols with documented collagen induction outcomes. EU MDR imposes stricter post-market surveillance requirements that delay product launches by twelve to eighteen months relative to FDA pathways. The Baden-Württemberg medical technology cluster anchors precision manufacturing for RF and ultrasound platform components.
India
Tier-two cities including Pune and Hyderabad present whitespace for device leasing models that lower capital barriers for dermatology practices entering aesthetic services. CDSCO registration requirements for imported energy devices create regulatory friction that domestic assemblers exploit through localized kit production. The Maharashtra-Gujarat corridor concentrates med-spa chain expansion targeting upper-middle-class preventive demographics.
Non-Invasive Aesthetic Treatment Market Key Industry Players
Capability concentration sits with specialized energy-device manufacturers possessing wavelength optimization expertise; scale advantage sits with diversified pharmaceutical portfolios commanding injectable consumable loyalty. The market structures around three tiers: integrated aesthetic divisions of pharmaceutical conglomerates, standalone laser and RF platform specialists, and regional device distributors with localized regulatory capabilities. Dominant competitive moves include subscription-based consumable procurement contracts and direct sales subsidiary expansion into high-volume clinic markets.
Within the pharmaceutical-integrated tier, AbbVie and Galderma exemplify divergent strategic positioning. AbbVie leverages its Allergan Aesthetics portfolio to anchor neurotoxin and filler distribution across North American dermatology channels. Galderma occupies a position emphasizing biostimulatory filler R&D intensity and practitioner education investments. Among standalone device manufacturers, Alma Lasers represents the geographic reach archetype through direct sales subsidiaries spanning over ninety countries.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Merz Pharma |
| Hologic |
| Allergan Aesthetics |
| Alma Lasers |
| Cutera |
| Lumenis |
| Syneron Candela |
| Others |
Cost & Logistics Intelligence
Chinese fermentation facilities concentrate hyaluronic acid raw material supply, anchoring injectable filler manufacturing economics and exposing downstream formulators to input cost volatility that reshapes margin pool distribution toward device-based modalities.
Pricing Analysis
Long-term offtake contracts dominate high-volume filler procurement between med-spa chains and pharmaceutical suppliers, while spot purchasing persists for single-platform device acquisitions. Three-tier pricing structure across premium, standard, and economy levels separates biostimulatory formulations from basic hyaluronic acid fillers and entry-level RF devices. Pricing pressure stems from RF-microneedling combination systems commoditizing faster than anticipated, compressing hardware margins. Chain-affiliated clinics demonstrate lowest price sensitivity due to subscription-based consumable commitments, while independent aesthetic practices remain most exposed to device financing cost fluctuations.
Supply Chain Analysis
Contract manufacturing for laser and RF platform assembly concentrates in Germany, Israel, and South Korea, with Seoul-based foundries capturing increasing share of compact diode laser production. Device production draws from gallium arsenide wafers, precision optical components, and medical-grade aluminum housings. Single-source vulnerability runs through specialized crystal growth capacity for solid-state laser rods. Distribution runs through direct sales subsidiaries in high-volume markets and certified distributor networks in emerging geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including practitioner certification programs and preventive maintenance contracts are expanding faster than hardware sales, repositioning vendor economics toward recurring relationship value over transactional device placement.
For Market Incumbents: Entrench market position through backward integration into hyaluronic acid fermentation capacity and exclusive leasing arrangements for multi-platform installations. The threat of domestic Chinese device manufacturers capturing NMPA clearance advantages demands accelerated joint venture structures. Certification program standardization represents the critical lever for locking in practitioner loyalty across fragmented licensing jurisdictions. For New Entrants and Emerging Players: Tier-two Indian cities present the most penetrable whitespace for capital-light device leasing models targeting dermatology practices entering aesthetic services. Combination RF-microneedling protocols remain underserved in price-sensitive clinic tiers. Go-to-market execution should prioritize distributor partnerships with established CDSCO registration expertise over direct sales infrastructure buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aesthetic clinic rollups consolidating California and Texas markets. Long-term viability hinges on lifetime value per patient cohort rather than single-procedure economics. Acquisition targets should demonstrate proven subscription consumable conversion rates. Watch for FDA 510(k) clearance acceleration for melanin-rich skin optimization as inflection signal for wavelength-optimized platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Program Expansion | Creates recurring revenue attachment and locks in consumable purchasing loyalty across AbbVie and Galderma distribution channels. |
| Joint Venture with Domestic Distributor | Accelerates NMPA clearance timelines by leveraging local investigator networks and regulatory expertise in Shanghai and Beijing. |
| RF-Microneedling Combination Platform Launch | Addresses fastest-growing technology segment while collapsing standalone modality distinction in US aesthetic clinic configurations. |
| Subscription-Based Consumable Contracting | Mirrors enterprise procurement shift in California and Texas med-spa chains toward locked volume commitments with preferential pricing. |
| Device Leasing Model Deployment | Lowers capital barriers for tier-two Indian dermatology practices entering aesthetic services through Pune and Hyderabad corridor expansion. |
Research Approach
Initial hypotheses were tested against primary input from dermatology practice owners, medical device regulatory affairs specialists, med-spa chain procurement directors, and energy-based device R&D heads, then refined through secondary validation against FDA 510(k) clearance databases, MFDS registration filings, NMPA approval records, and hospital procurement contract disclosures. Bottom-up clinic survey data and top-down manufacturer shipment estimates were triangulated to reconcile volume figures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, technology platform, application indication, and end-user channel. CAGRs were derived from procedure volume growth trajectories and average selling price evolution assumptions. Industry-specific forecast inputs incorporated MFDS predicate approval velocity and NMPA domestic clinical trial mandates.
Practitioners should monitor regulatory pathway shifts, raw material input cost movements, and practitioner certification standardization progress for early signals of competitive repositioning. Quarterly review of FDA 510(k) submission volumes and med-spa chain consolidation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market