
 Phototherapy Lamps and Units for Aesthetic Medicine Market | 2026-2036
Phototherapy Lamps and Units for Aesthetic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Phototherapy Lamps and Units for Aesthetic Medicine Market Analytics
The direct-to-clinic distribution channel is narrowing as manufacturers consolidate relationships with dermatology chains and medical spa networks. Philips Healthcare leverages its clinical lighting heritage to sustain premium positioning in hospital-affiliated aesthetic centers. Herbert Waldmann GmbH & Co. KG anchors European supply through specialized phototherapy engineering, while The Daavlin Company competes aggressively in North American dermatology clinics with narrowband UVB systems.
Phototherapy lamps and units for aesthetic medicine are engineered light-emitting devices that deliver controlled wavelengths—typically 405–420 nm for blue light acne therapy or 590–1200 nm for skin rejuvenation—through LED, fluorescent, or laser sources to trigger photobiomodulation in targeted tissue. LED product types now dominate unit shipments due to thermal efficiency and wavelength precision, though laser segments retain the deepest margin pools in premium skin rejuvenation applications. Dermatology clinics represent the most concentrated end-user channel, while medical spas are expanding fastest as state-level scope-of-practice regulations liberalize across multiple jurisdictions.
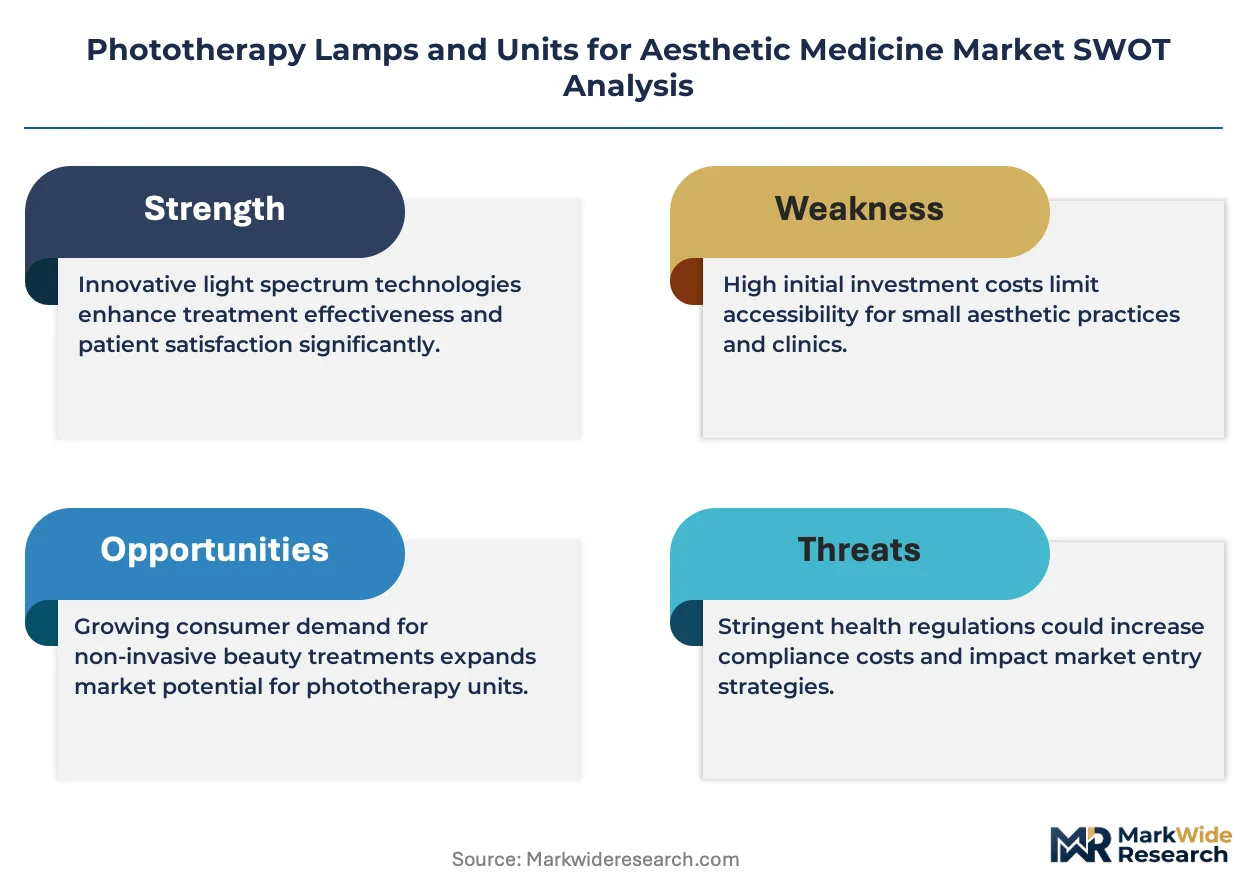
FDA 510(k) premarket notifications and the EU Medical Device Regulation (MDR) classification rules for active therapeutic devices are elevating clinical evidence burdens for new phototherapy entrants, which filters out smaller manufacturers and reinforces incumbent positions. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility requirements add compliance layers that shape R&D allocation across product development cycles. Stakeholders must monitor evolving MDR notified body capacity and FDA software-as-medical-device guidance for connected phototherapy units that integrate treatment logging and remote calibration.
Market Dynamics
LED wavelength precision is collapsing the performance gap between professional clinic systems and premium at-home devices, forcing incumbent manufacturers to defend margin pools through software-locked treatment protocols and subscription-based calibration services.
Growth Catalysts
- EU MDR Class IIa pathway elevation:Stricter clinical evidence requirements for active therapeutic devices filter out undercapitalized entrants, reinforcing established manufacturers with notified body relationships and ISO 13485 infrastructure.
- Medical spa scope liberalization:State-level regulatory expansions across multiple United States jurisdictions permit non-physician operators to administer LED phototherapy, opening new channel capacity beyond traditional dermatology clinics.
- Narrowband UVB engineering advances:German and South Korean suppliers achieve sub-nanometer wavelength stability in fluorescent tube systems, extending equipment lifespan and reducing clinic maintenance burdens.
Market Restraints
- Notified body capacity constraints:EU MDR implementation bottlenecks delay market entry timelines for new phototherapy entrants, concentrating 2024-2025 launch windows among pre-certified incumbents.
- GaN-on-Sapphire LED substrate costs:Blue light acne therapy modules depend on gallium nitride epitaxy supply concentrated in East Asian foundries, exposing manufacturers to input price volatility and allocation risk.
- Laser rejuvenation substitution pressure:Fractional CO2 and erbium systems retain superior collagen remodeling depth for severe photodamage cases, limiting LED penetration in premium anti-aging segments.
Strategic Opportunities
- Connected device integration:Phototherapy units with embedded treatment logging and cloud-based remote calibration create recurring revenue streams and lock-in effects for manufacturer service contracts.
- German aesthetic medicine infrastructure:Dense clinic networks and favorable reimbursement positioning for acne vulgaris treatment support premium equipment placement and replacement cycles.
- Blue-red combination protocol expansion:Dual-wavelength systems addressing both Cutibacterium acnes and inflammation simultaneously capture protocol standardization opportunities in United States dermatology residency programs.
Industry Challenges
- Biomedical optics engineering scarcity:Specialized expertise in tissue optics modeling and dosimetry validation commands premium compensation, constraining R&D team scaling for mid-tier manufacturers.
- FDA 510(k) predicate drift:Evolving software-as-medical-device guidance for connected phototherapy units creates documentation uncertainty, extending premarket notification preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phototherapy Lamps and Units for Aesthetic Medicine Market |
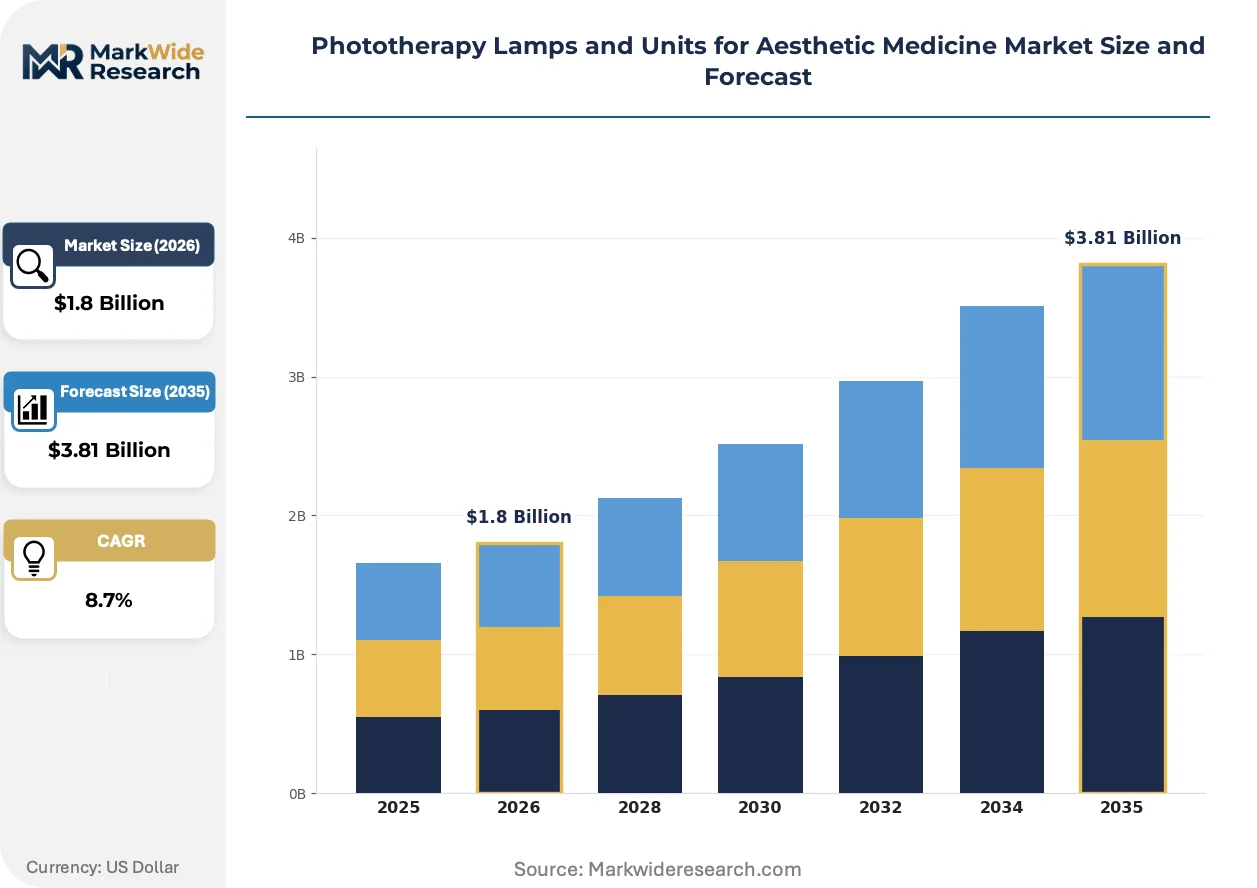
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Laser Application: Acne Treatment, Skin Rejuvenation, Psoriasis Therapy, Hair Growth Stimulation Technology: Intense Pulsed Light, Continuous Wave, Pulsed Wave, Multichannel End User: Dermatology Clinics, Medical Spas, Hospitals, Beauty Salons |
| Companies Covered | GE Healthcare, Philips Healthcare, Drägerwerk AG & Co. KGaA, Medtronic plc, Masimo Corporation, ATOM Medical Corporation, Natus Medical Incorporated, Herbert Waldmann GmbH & Co. KG, The Daavlin Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phototherapy Lamps and Units for Aesthetic Medicine Market Evolving Landscape
Wavelength-tunable LED arrays and AI-driven treatment personalization are compressing the traditional segmentation between professional and consumer phototherapy tiers, while regulatory frameworks struggle to classify hybrid device categories.
Multi-chip LED engines with independent wavelength control are collapsing the historical trade-off between treatment specificity and session throughput. Dermatology chains in the United States deploy these systems to sequence acne, redness, and rejuvenation protocols without equipment changeover. The technology is collapsing capital allocation patterns as single-unit flexibility replaces dedicated-device room configurations.
EU MDR technical documentation requirements for active therapeutic devices are elevating clinical evidence burdens beyond historical MEDDEV 2.7/1 precedents. Manufacturers must now submit prospective clinical investigations for novel wavelength combinations or energy density protocols. South Korean exporters targeting European markets face extended notified body queue times, redirecting 2024 launch priorities toward United States FDA 510(k) pathways.
Subscription-based equipment access models are displacing outright purchase arrangements in United States medical spa channels. Device-as-a-service contracts bundle hardware, maintenance, and consumable replenishment into per-treatment fees, transferring utilization risk from clinic operators to manufacturers. This shift concentrates most visibly in California and Texas markets where capital-light expansion strategies dominate new medical spa formation.
Phototherapy Lamps and Units for Aesthetic Medicine Market Segmentation
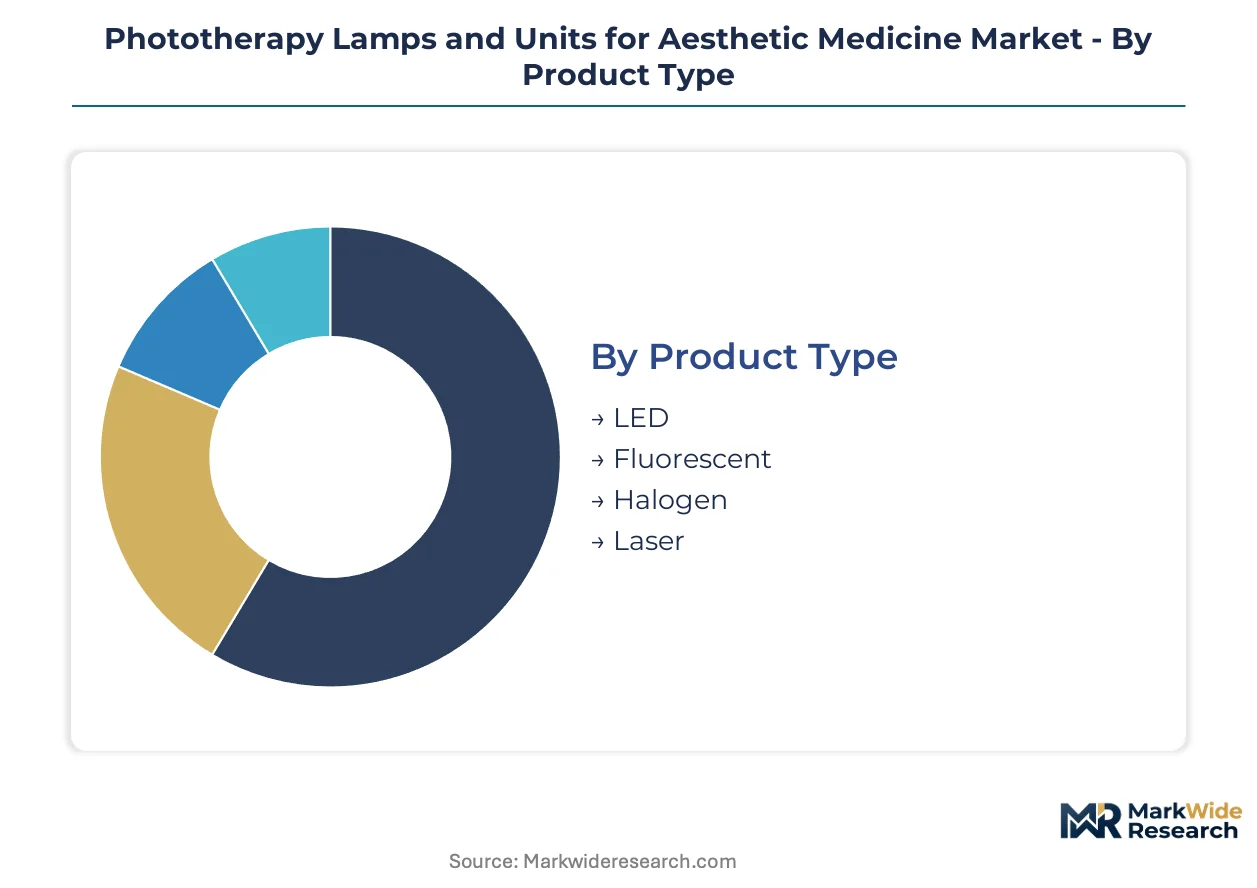
Segmentation in phototherapy equipment reveals how wavelength engineering, clinical setting requirements, and regulatory pathways fragment purchasing behavior across the aesthetic medicine supply chain. Understanding these divisions exposes where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Mature fluorescent and halogen systems coexist with emerging LED architectures that are collapsing the performance gap between professional and consumer tiers.
- LED:Solid-state arrays deliver precise wavelength control at 405–420 nm for acne therapy and 590–1200 nm for rejuvenation with minimal thermal load. Demand concentrates in United States dermatology chains seeking protocol flexibility through multi-chip engines. FDA software-as-medical-device guidance for connected units elevates compliance costs for new entrants.
- Fluorescent:Narrowband UVB tubes engineered by German and South Korean suppliers achieve sub-nanometer wavelength stability for psoriasis protocols. European clinic networks favor these systems for their extended service intervals and predictable maintenance schedules under EU MDR technical documentation requirements.
- Halogen:Broad-spectrum thermal sources retain niche placement in budget-conscious beauty salon channels where capital constraints limit LED migration.
- Laser:Coherent light systems command premium positioning in collagen remodeling applications where fractional CO2 and erbium wavelengths penetrate deeper than LED alternatives for severe photodamage cases.
LED handles the majority of throughput; laser is the fastest mover on share.
Application:
Cost tier stratification separates reimbursement-supported medical indications from elective aesthetic procedures with divergent equipment financing models.
- Acne Treatment:Blue light protocols at 405–420 nm target Cutibacterium acnes porphyrin excitation. United States dermatology residency programs are standardizing dual-wavelength blue-red systems that simultaneously address bacterial load and inflammation.
- Skin Rejuvenation:Near-infrared and red light photobiomodulation stimulates collagen synthesis and reduces erythema. Medical spas in California and Texas deploy subscription-based device access models to transfer utilization risk from operators to manufacturers.
- Psoriasis Therapy:Narrowband UVB at 311 nm remains the phototherapy gold standard with established reimbursement codes in German clinic networks.
- Hair Growth Stimulation:Low-level laser therapy at 650–655 nm targets androgenetic alopecia through mitochondrial cytochrome c oxidase activation.
Acne treatment commands the deepest installed base; skin rejuvenation is climbing the fastest.
Technology:
Volume concentration in pulsed architectures reflects their dominance in high-throughput clinic environments where session efficiency determines capital return.
- Intense Pulsed Light:Broadband filtered flashlamps deliver 500–1200 nm energy for hair removal and photorejuvenation through selective photothermolysis.
- Continuous Wave:Uninterrupted emission suits low-dose maintenance protocols in medical spa settings where treatment duration flexibility matters more than peak power density.
- Pulsed Wave:High-peak-power delivery with thermal relaxation periods enables aggressive collagen remodeling while minimizing epidermal damage.
- Multichannel:Independent wavelength control across multiple LED arrays permits sequential protocol execution without equipment changeover.
Pulsed wave systems anchor professional clinic throughput; multichannel configurations are gaining share fastest.
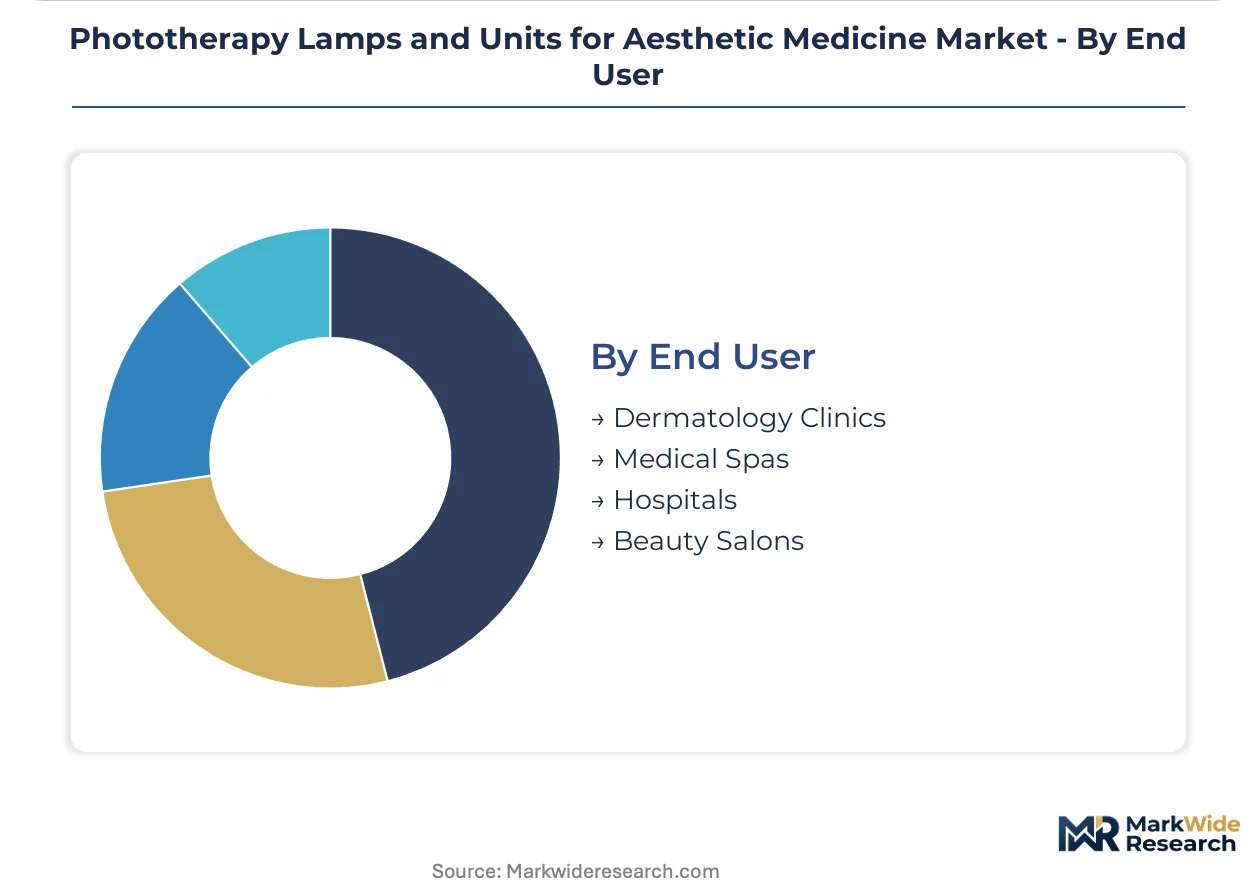
End User:
Customer type fragmentation maps directly to scope-of-practice regulatory variation across United States state jurisdictions and European national healthcare systems.
- Dermatology Clinics:Physician-supervised facilities concentrate demand for FDA 510(k)-cleared devices with robust clinical evidence packages. These sites prioritize wavelength precision and treatment logging capabilities for malpractice risk management.
- Medical Spas:Non-physician operator environments in Texas and Florida exploit liberalized state regulations to administer LED phototherapy. Capital-light expansion strategies favor device-as-a-service contracts bundling hardware, maintenance, and consumables.
- Hospitals:Hospital-affiliated aesthetic centers leverage group purchasing organization leverage to negotiate premium positioning from manufacturers with ISO 13485 infrastructure.
- Beauty Salons:Unregulated or lightly regulated channels in select jurisdictions drive residual demand for lower-cost halogen and entry-level LED systems.
Dermatology clinics handle the majority of throughput; medical spas are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy for acne vulgaris treatment in Germany and scope-of-practice liberalization across Texas and Florida are redirecting capital toward clinic infrastructure. FDA 510(k) clearance pathways and EU MDR Class IIa elevation are filtering market entry timelines unevenly across jurisdictions.
United States
Medical spa formation in Texas and California exploits state-level regulatory expansions permitting non-physician LED phototherapy administration. FDA software-as-medical-device guidance for connected treatment units extends premarket notification preparation cycles. The Dallas-Houston corridor concentrates device-as-a-service contract adoption, transferring utilization risk from clinic operators to manufacturers through bundled per-treatment fee structures.
Germany
Dense dermatology clinic networks in Bavaria and North Rhine-Westphalia sustain premium equipment replacement cycles through favorable statutory health insurance positioning for acne and psoriasis protocols. EU MDR technical documentation requirements for active therapeutic devices elevate clinical evidence burdens beyond historical MEDDEV 2.7/1 precedents. Herbert Waldmann GmbH & Co. KG anchors European supply through specialized phototherapy engineering capabilities concentrated in the Black Forest region.
South Korea
Seoul Capital Area aesthetic medicine clusters drive demand for multi-channel LED engines with independent wavelength control. MFDS medical device approval pathways for phototherapy equipment maintain alignment with international electromagnetic compatibility standards. Busan-Ulsan manufacturing corridors supply sub-nanometer wavelength stability components for narrowband UVB fluorescent systems exported to European clinic networks.
United Kingdom
Private dermatology chains in London and the Southeast prioritize FDA 510(k)-cleared devices with robust treatment logging capabilities for malpractice risk management. MHRA recognition of EU MDR certificates post-Brexit creates parallel conformity assessment pathways for phototherapy entrants. The Midlands region hosts NHS-affiliated aesthetic centers leveraging group purchasing organization leverage for ISO 13485-certified equipment procurement.
Phototherapy Lamps and Units for Aesthetic Medicine Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with established notified body relationships and clinical evidence infrastructure. Tiered competitive positioning separates heritage clinical lighting specialists, diversified medical technology conglomerates, and regional phototherapy engineering boutiques. Strategic moves concentrate on M&A absorption of wavelength-tunable LED array developers and exclusive distribution partnerships with dermatology chain networks.
Among diversified healthcare technology conglomerates, GE Healthcare and Philips Healthcare occupy positions leveraging hospital-affiliated aesthetic center procurement channels. Herbert Waldmann GmbH & Co. KG exemplifies the specialized phototherapy engineering archetype with European-centric supply relationships. The Daavlin Company represents North American narrowband UVB system competition focused on dermatology clinic penetration.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Drägerwerk AG & Co. KGaA |
| Medtronic plc |
| Masimo Corporation |
| ATOM Medical Corporation |
| Natus Medical Incorporated |
| Herbert Waldmann GmbH & Co. KG |
| The Daavlin Company |
| Others |
Value Network & Pricing Analysis
Busan-Ulsan corridor freight costs for GaN-on-sapphire substrates transmit directly into LED module pricing spreads, concentrating margin pressure on manufacturers lacking long-term foundry allocations while enabling premium positioning for ISO 13485-certified suppliers serving United States dermatology chains.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared systems and economy-tier salon equipment, with ISO 13485 and EU MDR Class IIa documentation commanding 40-60% markups over uncertified alternatives. Subscription-based device-as-a-service contracts now dominate medical spa channels in California and Texas, transferring utilization risk to manufacturers through per-treatment fee structures. Pricing pressure stems from GaN epitaxy supply concentration in East Asian foundries exposing mid-tier producers to allocation volatility. Dermatology clinics demonstrate lowest price sensitivity due to malpractice risk management requirements, while beauty salons in unregulated jurisdictions drive residual demand for halogen-based budget systems.
Supply Chain Analysis
GaN epitaxy wafers feed from Taiwan and South Korean foundries, with Seoul Capital Area packaging houses handling multi-chip LED engine assembly for wavelength-tunable arrays. Fluorescent tube phosphor coatings and narrowband UVB filters draw from German specialty chemical suppliers anchored in the Black Forest region. Single-source vulnerability concentrates in gallium nitride substrate supply, where three foundries control 80% of medical-grade epitaxy output. Distribution runs through direct-to-clinic relationships with dermatology chain procurement committees, bypassing traditional medical device distributors for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States dermatology chain procurement committees and German hospital group purchasing organizations, fragmenting negotiating leverage for smaller clinic operators and tilting contract terms toward multi-year exclusive supply arrangements with incumbent manufacturers.
For Market Incumbents: Insulate margin pools through backward integration into GaN epitaxy supply chains or captive wavelength-tuning software development, while locking dermatology chains into calibration service subscriptions that create switching costs against emerging LED array competitors. FDA software-as-medical-device guidance elevation presents a defensive moat when combined with treatment logging capabilities that address malpractice risk management requirements. For New Entrants and Emerging Players: Build out white-space positioning in medical spa channels where state-level scope liberalization permits non-physician LED administration, particularly Texas and Florida markets where capital-light device-as-a-service contracts displace outright purchase arrangements. Target narrowband UVB fluorescent system niches where German and South Korean incumbents face EU MDR notified body queue delays, enabling faster FDA 510(k) pathway execution for United States dermatology clinic penetration. For Investors and Strategic Acquirers: Wavelength-tunable LED array engineering boutiques with proprietary multi-chip control algorithms represent the highest-conviction acquisition archetype, given their scarcity value against biomedical optics engineering talent constraints. Long-term viability hinges on regulatory certification infrastructure durability across EU MDR and FDA 510(k) pathways, with inflection signaled by notified body capacity expansion or predicate device clearance acceleration for connected phototherapy units.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Accelerates European market access for active therapeutic devices through notified body relationships. |
| Multi-Channel LED Engine Development | Enables sequential acne-rejuvenation protocols without equipment changeover in dermatology chains. |
| Device-as-a-Service Contract Launch | Transfers utilization risk from Texas medical spa operators to manufacturers via per-treatment fees. |
| GaN Epitaxy Supply Agreement | Secures substrate allocation from Taiwan foundries against price volatility in blue light modules. |
| Software Companion Development | Addresses FDA software-as-medical-device guidance for connected treatment logging capabilities. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and phototherapy equipment customs records preceded structured interviews with dermatology clinic procurement managers, medical spa operators, biomedical optics engineers, and notified body auditors. Primary fieldwork validated wavelength engineering roadmaps and subscription contract adoption patterns against secondary sources including ISO 13485 certification registries and GPO contract databases. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions across product type and end-user segments.
Assumptions held fixed include EU MDR notified body capacity constraints and FDA software-as-medical-device guidance interpretation stability, while variables incorporated state-level medical spa scope-of-practice liberalization trajectories and GaN substrate supply allocation shifts. The analytical framework modeled volume and value across LED, fluorescent, halogen, and laser product types; acne treatment, skin rejuvenation, psoriasis therapy, and hair growth stimulation applications; and dermatology clinic, medical spa, hospital, and beauty salon end users. CAGRs derived from equipment replacement cycle analysis and protocol standardization adoption curves in United States dermatology residency programs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified healthcare conglomerates or sudden notified body capacity expansion would shift outcomes materially. Cross-checking against hospital procurement database trends and medical spa formation rates in Texas and California is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market