
 Global Tobacco Market | 2026-2036
Global Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tobacco Market Outlook
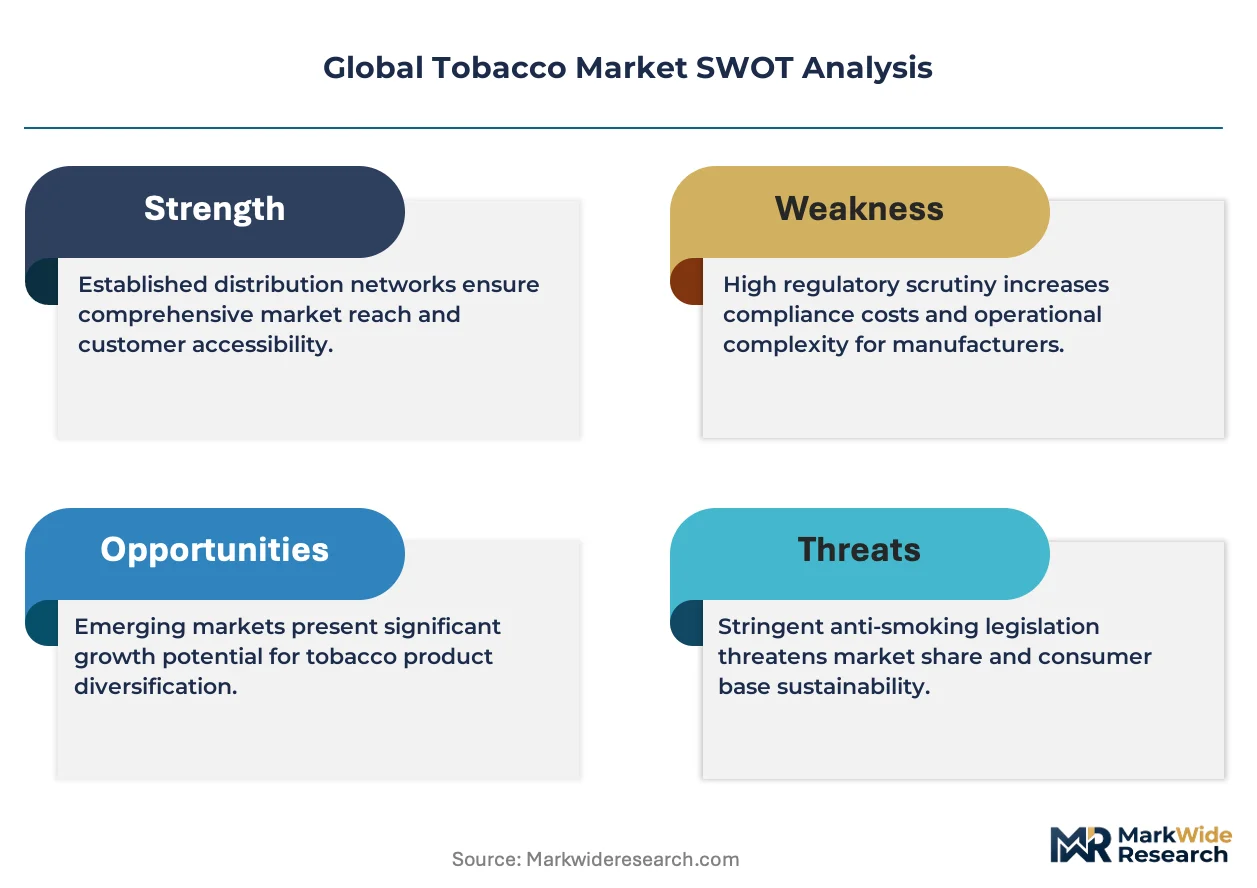
EU Tobacco Products Directive is shifting the cost-of-entry calculus for manufacturers seeking European market access, forcing reformulation investments and standardized packaging compliance. Philip Morris International leverages its IQOS heat-not-burn platform to differentiate from combustible portfolios. British American Tobacco sustains geographic diversification across Latin America, Africa, and Asia-Pacific. China National Tobacco Corporation anchors global volume through its domestic monopoly position.
Tobacco comprises cured and processed leaves of Nicotiana species, containing nicotine alkaloids typically measured at 1-3% dry weight, cultivated through controlled flue-curing or air-curing methods for use in smoked, heated, or oral delivery systems. Cigarettes occupy the dominant revenue position within product type segmentation, while smokeless tobacco represents the fastest-growing margin pool as oral nicotine pouches expand. Convenience stores control the highest traffic volume among sales channels, though online retail is gaining regulatory attention.
FDA in the United States, EMA through national competent authorities in Europe, and WHO Framework Convention on Tobacco Control collectively determine product authorization pathways, ingredient standards, and cross-border marketing restrictions. These frameworks compress commercial flexibility while creating compliance barriers that favor capital-intensive operators. Stakeholders must monitor evolving heat-not-burn classification decisions across multiple jurisdictions to anticipate tax treatment and channel access.
Market Dynamics
Heat-not-burn technology is compressing combustible volume while nicotine pouch formats are capturing oral-segment margin migration, forcing incumbents to rebalance portfolio allocation between legacy flue-cured products and reduced-risk alternatives.
Growth Catalysts
- Oral Nicotine Pouch Expansion:Smokeless formats bypass indoor air-quality restrictions in urban centers across Sweden and the United States, opening consumption occasions previously closed to combustibles.
- EU Tobacco Products Directive:Standardized packaging mandates and ingredient disclosure rules favor operators with scale to absorb compliance costs, consolidating shelf access for capital-intensive portfolios.
- China National Tobacco Corporation:State-controlled domestic production anchors global leaf procurement volume, stabilizing input costs for flue-cured varieties across Asia-Pacific supply chains.
Market Restraints
- Leaf Input Cost Volatility:Weather-induced yield variation in Brazilian and Zimbabwean growing regions creates margin pressure for manufacturers dependent on air-cured Burley varieties.
- FDA Premarket Authorization:Deeming rule requirements for novel products extend commercialization timelines, freezing revenue recognition for heat-not-burn submissions under review.
- Substitution by Pharmaceutical Nicotine:Prescription cessation therapies and over-the-counter gums compete for the same dependency-relief occasion, eroding trial rates among quit-intending consumers.
Strategic Opportunities
- India Smokeless Market:Gutka and khaini consumption patterns create infrastructure for pouch format conversion, with BIS standards providing regulatory scaffolding for quality differentiation.
- Carbon-Neutral Leaf Cultivation:Sustainability-linked financing and EU Green Deal alignment requirements incentivize investment in regenerative agriculture across Italian and Greek growing cooperatives.
- Direct-to-Consumer Channels:Age-verified e-commerce platforms circumvent traditional retail gatekeepers, capturing margin previously allocated to convenience store slotting fees.
Industry Challenges
- Flavor Chemist Talent Scarcity:Heat-not-burn aerosol engineering and reduced-toxicant formulation require cross-disciplinary expertise spanning organic chemistry and thermodynamics, with limited university pipeline output.
- Legacy IT Integration:Track-and-trace serialization mandates under WHO Framework Convention protocols force retrofit of decades-old manufacturing execution systems, disrupting batch-release workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tobacco Market |
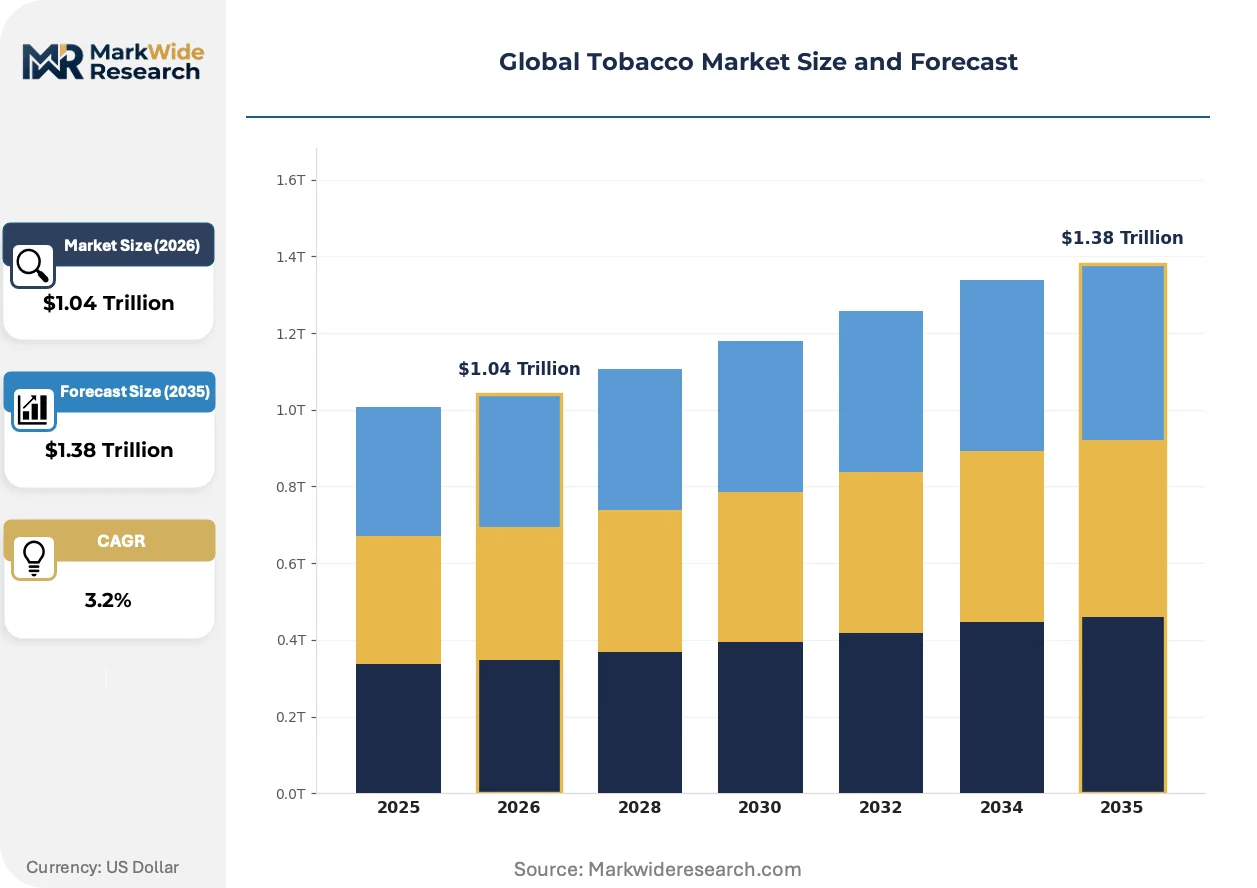
| Market Size in 2026 | $1.04 Trillion |
| Market Size in 2035 | $1.38 Trillion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Hookah, Smokeless Tobacco End User: Adult Consumers, Teenagers, Retailers, Distributors Sales Channel: Online Retail, Convenience Stores, Supermarkets, Specialty Shops Packaging Type: Hard Packs, Soft Packs, Blister Packs, Pouches |
| Companies Covered | Philip Morris International Inc., British American Tobacco plc, Altria Group, Inc., Japan Tobacco Inc., Imperial Brands plc, China National Tobacco Corporation, KT&G Corporation, ITC Limited, PT Hanjaya Mandala Sampoerna Tbk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tobacco Market Strategic Shifts
Product format diversification is fragmenting consumer loyalty while regulatory classification debates determine tax treatment and channel access for emerging nicotine delivery systems.
Heat-not-burn platforms are electrifying the competitive landscape by delivering nicotine through controlled thermal extraction rather than combustion. Adult smokers in Japan and South Korea have migrated rapidly from conventional cigarettes to blade-and-stick systems. This shift is compressing combustible volume in developed markets while opening premium pricing tiers previously unavailable to manufacturers.
EMA coordination through national competent authorities is tightening emissions testing protocols for novel tobacco products, requiring standardized toxicant reporting across EU member states. Manufacturers must now submit aerosol constituent data before market authorization, extending development cycles. Heat-not-burn portfolios face the steepest compliance burden as regulators debate whether to classify these products as tobacco or standalone nicotine systems.
Convenience store traffic erosion is accelerating as age-verified digital channels capture routine replenishment purchases previously executed at physical retail. Urban consumers in Germany and the United Kingdom now initiate subscription deliveries for heated-tobacco consumables. This behavioral shift is forcing slotting-fee renegotiation and inventory rebalancing across traditional wholesale networks.
Global Tobacco Market Segmentation
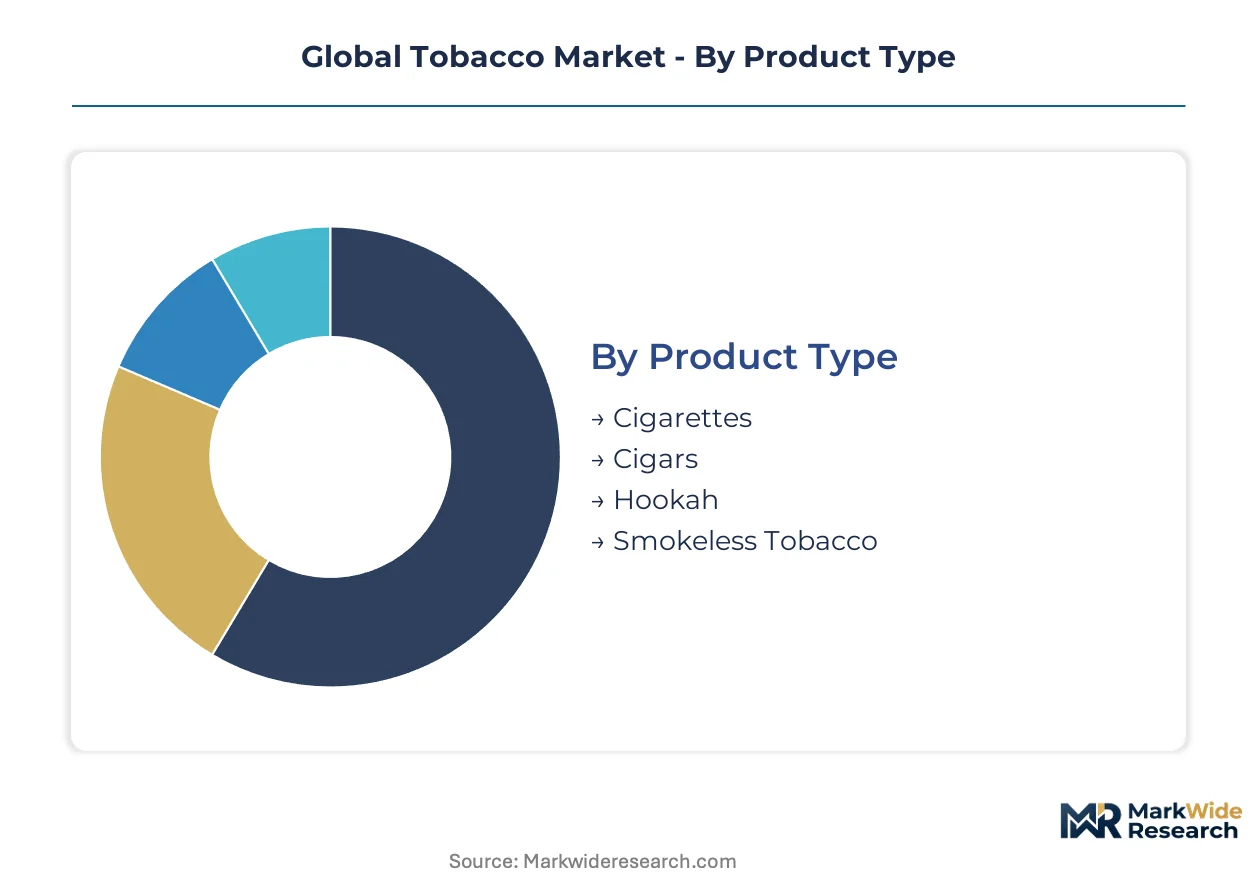
Tobacco market segmentation reveals divergent profit pools across combustion and non-combustion formats. Manufacturers allocate R&D capital based on channel-specific velocity and packaging compliance costs rather than aggregate volume alone.
Product Type:
Buyers in this category differentiate by ritual occasion and indoor consumption restrictions.
- Cigarettes:Flue-cured Virginia and Burley blends dominate, with filter ventilation engineering determining tar and nicotine delivery specifications. Demand concentrates in China and Indonesia where state-controlled pricing and informal distribution networks sustain volume; combustible taxes in Germany and France compress margin per stick.
- Smokeless Tobacco:Moist snuff and nicotine pouches bypass indoor air-quality regulations, enabling consumption in office and transit environments. Sweden and the United States anchor demand; pouch formats are displacing loose snuff as consumers prioritize discretion and reduced spit requirements.
- Cigars:Hand-rolled long-filler varieties command premium positioning through aged wrapper leaf and limited production batches. Dominican Republic and Nicaraguan provenance drives collector demand in Miami and Las Vegas retail corridors.
- Hookah:Flavored molasses-based shisha requires charcoal ignition apparatus and social consumption settings. Demand clusters in Middle Eastern diaspora communities across Dearborn, Michigan and Berlin's Neukölln district.
Cigarettes lead volumes today; smokeless tobacco is gaining share fastest.
End User:
Consumption patterns in this category split between dependency-driven replenishment and social trial behaviors.
- Adult Consumers:Legal-age smokers and oral nicotine users drive 95% of commercial volume through habitual purchase cycles. FDA and EMA age-verification mandates force channel friction that pouch formats partially circumvent through direct-to-subscription models.
- Retailers:Convenience store operators and tobacconists control shelf placement and visibility through slotting fee negotiations. Inventory turns in Tokyo's FamilyMart outlets and São Paulo's corner bodegas determine manufacturer promotional allocation.
- Distributors:Wholesale networks manage excise tax stamping and track-and-trace serialization compliance across state and national borders. Brazilian and South African distributors face highest working capital burdens due to complex duty structures.
- Teenagers:Regulatory frameworks universally prohibit commercial targeting; this segment appears in data only as policy failure metric rather than addressable market.
Adult consumers anchor revenue today; retailer consolidation is reshaping channel power fastest.
Sales Channel:
Channel selection in this category determines tax collection efficiency and age-verification rigor.
- Convenience Stores:High-frequency foot traffic and extended operating hours sustain cigarette carton replenishment. 7-Eleven Japan and OXXO Mexico capture routine purchases through location density and payment flexibility.
- Online Retail:Age-gated e-commerce platforms bypass traditional wholesale markups while requiring biometric or ID-scan verification. German and UK consumers increasingly subscribe to heated-tobacco consumables for home delivery.
- Supermarkets:Carrefour and Tesco hypermarkets leverage tobacco as traffic driver, though display restrictions in France and Australia compress visibility. Self-service checkout integration remains contested by regulators.
- Specialty Shops:Premium cigar lounges and hookah cafés provide experiential consumption environments with high per-visit spend. Dubai's cigar bars and Havana's state-run humidors anchor destination tourism revenue.
Convenience stores dominate transaction volume today; online retail is expanding most quickly.
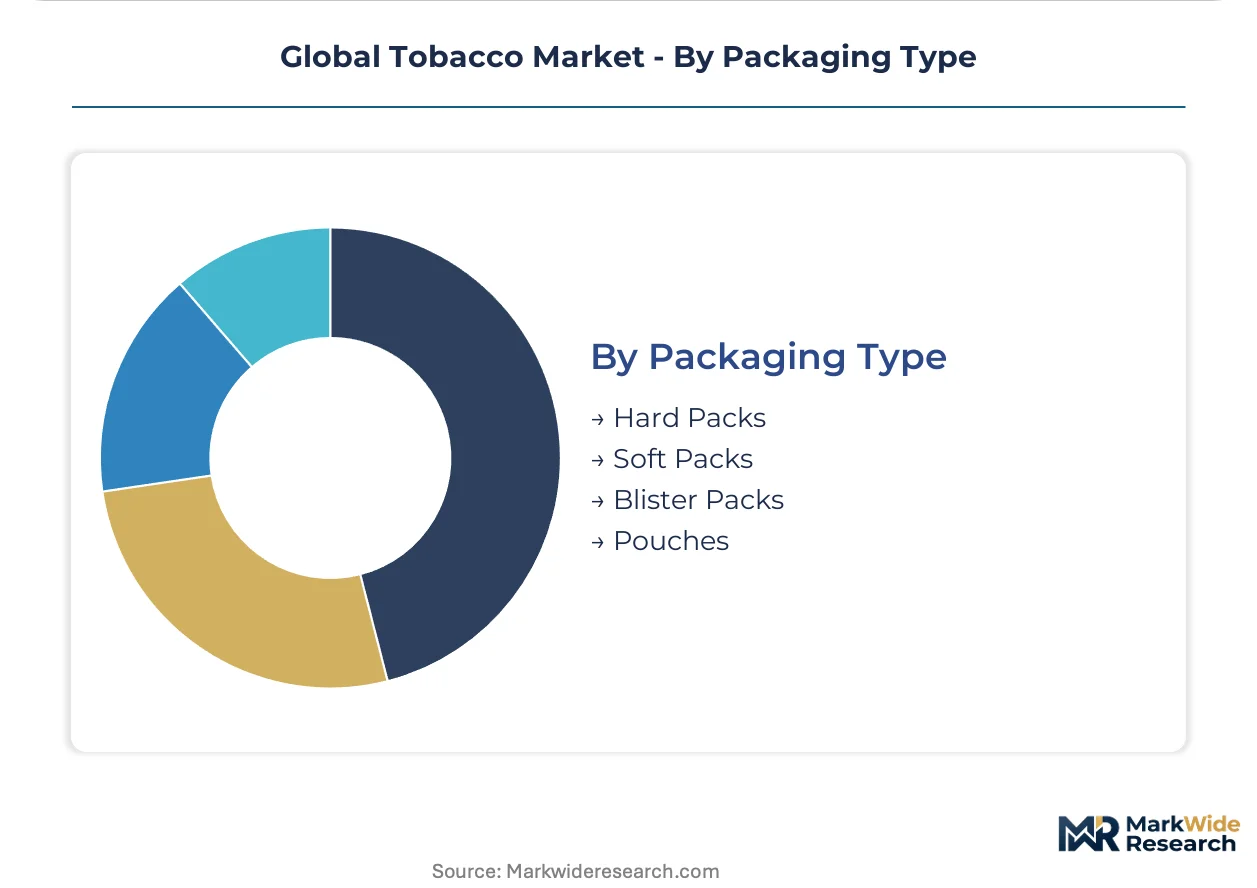
Packaging Type:
Packaging economics in this category balance protection, portability, and regulatory display mandates.
- Hard Packs:Rigid paperboard construction with foil inner lining preserves cigarette integrity through transport and storage. EU standardized packaging rules have flattened brand differentiation, forcing manufacturers to compete through tactile quality alone.
- Pouches:Flexible laminate sachets with resealable zippers contain moist snuff and nicotine pouches for pocket portability. Swedish Match and BAT pouch formats prioritize discrete consumption and reduced odor signature.
- Soft Packs:Collapsible paper wrapping minimizes material cost but offers limited crush protection. Demand persists in price-sensitive markets including Vietnam and Egypt where unit economics override durability concerns.
- Blister Packs:Thermoformed plastic cavities with foil lidding enable single-unit dosing for nicotine gum and lozenge formats. Pharmaceutical-grade packaging signals cessation intent rather than recreational use.
Hard packs lead manufactured unit volume today; pouch formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tobacco cultivation and manufacturing trace their modern industrial origins to the Jamestown colony in Virginia, where John Rolfe commercialized Nicotiana tabacum exports to Europe in 1612. This American foundation established the flue-curing techniques and plantation economics that spread to Brazil, Zimbabwe, and Indonesia over subsequent centuries.
United States
Adult smokers in the Southeast and Midwest sustain demand for combustibles and heated-tobacco alternatives. FDA premarket authorization requirements under the 2009 Family Smoking Prevention and Tobacco Control Act freeze commercialization timelines for novel nicotine products. Richmond, Virginia anchors Philip Morris USA's manufacturing campus and leaf procurement operations.
China
State-controlled production and domestic consumption patterns concentrate global cigarette volume within a single national market. China National Tobacco Corporation operates under SAMR oversight with standardized GB quality requirements for domestic distribution. Yunnan Province hosts the industry's largest flue-cured tobacco growing region, supplying processing facilities in Kunming.
Germany
Urban consumers in Berlin and Hamburg accelerate adoption of nicotine pouches and heated-tobacco systems to circumvent indoor smoking bans. EU Tobacco Products Directive mandates standardized packaging and emissions disclosure through EMA-coordinated national competent authorities. The Cologne-Düsseldorf corridor houses British American Tobacco's regional headquarters and distribution infrastructure.
Japan
Adult smokers migrated rapidly from combustibles to heat-not-blade systems following IQOS launch in 2014, compressing conventional cigarette volume. METI and PMDA regulate novel tobacco products under pharmaceutical-adjacent frameworks requiring toxicant reporting. Tokyo's convenience store density sustains the highest per-capita heated-tobacco consumable velocity globally.
Brazil
Air-cured Burley and dark-fired tobacco cultivation in Santa Cruz do Sul and Rio Grande do Sul supplies global leaf demand for premium cigarette blends. ANVISA oversees maximum residue limits and agricultural chemical approvals for domestic and export markets. The southern growing cooperatives face weather-induced yield volatility that propagates through Asia-Pacific manufacturing supply chains.
Global Tobacco Market Competitive Environment
The competitive structure tilts toward state-controlled and publicly traded incumbents with century-old brand equity and regulatory compliance infrastructure. Consolidation around capital-intensive operators favors those with heat-not-burn R&D platforms and smokeless format diversification. Three archetypes dominate: diversified multinationals with reduced-risk portfolios, state monopolies with domestic volume concentration, and regional specialists with niche oral nicotine positioning. Competitive moves center on portfolio rebalancing between combustible and non-combustible formats, plus direct-to-consumer channel development to circumvent traditional retail gatekeepers.
Among diversified multinationals, Philip Morris International Inc., British American Tobacco plc, and Altria Group, Inc. occupy positions exemplifying the capital-intensive archetype required for FDA and EMA compliance navigation. These publicly traded entities represent the tier capable of absorbing standardized packaging mandates and emissions testing investments. Philip Morris International anchors the heat-not-burn transition through its IQOS platform presence across Japanese and European markets. British American Tobacco sits within the geographic diversification archetype with operational footprints spanning Latin American, African, and Asia-Pacific jurisdictions. Altria Group exemplifies the domestic consolidation model through its US-focused combustible and oral nicotine portfolio concentration.
| Leading Market Players |
|---|
| Philip Morris International Inc. |
| British American Tobacco plc |
| Altria Group, Inc. |
| Japan Tobacco Inc. |
| Imperial Brands plc |
| China National Tobacco Corporation |
| KT&G Corporation |
| ITC Limited |
| PT Hanjaya Mandala Sampoerna Tbk |
| Others |
Value Chain & Pricing Dynamics
State-controlled procurement in China anchors global leaf pricing through volume commitments that stabilize flue-cured tobacco benchmarks. Manufacturers serving European and Japanese markets absorb premium compliance costs for emissions testing and standardized packaging, passing these through to heat-not-burn consumables.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IQOS blade systems from mid-tier heated-tobacco sticks and value cigarette brands. Price differentiation hinges on certification grade for reduced-risk claims and geographic delivery cost for air-cured Burley varieties. Cost compression in economy combustibles is intensifying because Brazilian weather volatility propagates through Asia-Pacific manufacturing. Price-sensitive buyers cluster in Southeast Asian informal markets; least sensitive buyers occupy Japanese and German urban centers seeking indoor-consumption alternatives.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam handle EU customs clearance and track-and-trace serialization for heated-tobacco imports. Geographic supply concentrates in China, Brazil, and Zimbabwe, with Yunnan Province flue-cured varieties and Santa Cruz do Sul air-cured Burley feeding global blending operations. Raw material dependencies include fertilizer-grade potassium nitrate, cigarette paper with controlled porosity, and laminate films for pouch packaging. Single-source vulnerability runs through China National Tobacco Corporation's domestic monopoly position. Distribution runs through duty-paid wholesale networks with excise stamping at national borders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as adult smokers in developed economies migrate toward premium heat-not-burn systems with toxicant-reduction credentials.
For Market Incumbents: To counter FDA premarket authorization delays freezing revenue recognition, accelerate parallel EMA submissions through national competent authorities and deepen backward integration into Italian and Greek carbon-neutral leaf cooperatives. Channel control through age-verified direct-to-subscription platforms reduces slotting-fee exposure to consolidating convenience retail. For New Entrants and Emerging Players: Oral nicotine pouch users in Indian urban centers present the most penetrable white-space target, with BIS quality standards providing regulatory scaffolding against unorganized gutka competitors. Pursue white-label manufacturing partnerships with existing pouch format specialists rather than greenfield capacity. For Investors and Strategic Acquirers: Diversified multinationals with heat-not-burn R&D platforms are the most active acquirers in this space, seeking smokeless format capabilities to rebalance combustible exposure. Long-term viability favors operators with reduced-risk portfolios achieving pharmaceutical-adjacent regulatory classification. Monitor EMA toxicant threshold decisions as the inflection signal for tax treatment and channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Not-Burn Portfolio Expansion | Philip Morris International's IQOS platform demonstrates premium pricing power in Japanese convenience retail. |
| Carbon-Neutral Leaf Sourcing | EU Green Deal alignment requirements incentivize regenerative agriculture investment across Greek growing cooperatives. |
| Direct-to-Consumer Channel Development | Age-verified subscription models capture margin previously allocated to 7-Eleven Japan slotting fees. |
| Oral Nicotine Pouch Format Diversification | Swedish Match and BAT pouch variants bypass indoor air-quality restrictions in German office environments. |
| Regulatory Compliance Infrastructure Buildout | FDA and EMA emissions testing investments consolidate shelf access for capital-intensive operators. |
Study Parameters
Multiple input streams — regulatory filing databases, customs trade records, and manufacturer production disclosures — were reconciled against primary fieldwork with leaf procurement directors, heat-not-burn platform engineers, and convenience store category buyers. Secondary validation drew from FDA premarket tobacco product application filings, EMA coordinated national competent authority decisions, WHO Framework Convention implementation reports, and China National Tobacco Corporation production statistics. Bottom-up volume modeling across product formats and sales channels was cross-checked against top-down macroeconomic consumption indicators.
Historical shipment data was cross-referenced against panel input from distribution executives to establish baseline volumes across the analysis window. Segmentation dimensions modeled include product type, packaging format, sales channel, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized volume trends adjusted for population demographics and excise tax elasticity. Industry-specific forecast inputs incorporated heat-not-burn adoption curves from Japanese market precedent and oral nicotine pouch velocity in Scandinavian markets.
Underlying measurement precision varies by segment; heat-not-burn and nicotine pouch categories carry tighter precision than traditional combustibles due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions regarding regulatory classification stability and excise tax treatment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Duty-Free Retailing Market
Others
Underwater Communication System Market
Others
Connected Wearable Patches Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Flexographic Printing Plate Market
Others
Billet Market
Others
Mexico Retail Market
Others
Running Apparel Market
Others
Dandelion Market
Others
Live IP Broadcast Equipment Market
Others
Global Platform Trolley Market
Others
India Smart Home Market
Others
Idaas Market
Others
Aboveground Storage Tanks Market
Others
Japan 3D Printing Construction Market
Others
Vo5g Market