
 Outsourced Software Testing Services Market | 2026-2036
Outsourced Software Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Software Testing Services Market Outlook
Modular bundling of functional, performance, and security testing into unified service contracts is hardening buyer expectations for comprehensive quality assurance partnerships. Accenture leverages its global delivery footprint to anchor large enterprise engagements across regulated industries. Capgemini differentiates through deep sector specialization in banking and telecommunications testing protocols. Tata Consultancy Services sustains competitive positioning with in-house automated testing frameworks that reduce cycle times for cloud migrations.
Outsourced software testing services encompass independent verification and validation of application functionality, performance thresholds, security postures, and user experience parameters executed by third-party specialists rather than internal development teams. These services employ scripted automation frameworks, load simulation environments, and penetration testing methodologies to detect defects before production deployment across web, mobile, and enterprise platforms. Functional testing and security testing command the largest revenue pools due to compliance mandates in healthcare and financial services, while cloud-based solutions and automated testing tools represent the fastest-expanding technology categories as enterprises accelerate DevOps adoption. Manual testing persists in usability and exploratory scenarios where human judgment evaluates interface intuitiveness, though its share of total effort continues declining relative to script-driven alternatives.
The FDA enforces software validation requirements under 21 CFR Part 820 for medical device applications, creating structural demand for independent testing documentation that outsourced providers supply. EMA's Medical Device Regulation and the EU AI Act impose conformity assessment obligations on AI-embedded software, expanding the addressable market for security and algorithmic bias testing services. Stakeholders must monitor evolving cybersecurity certification schemes and cross-border data governance rules that determine where testing infrastructure can reside and which audit trails satisfy multiple regulatory jurisdictions simultaneously.
Market Dynamics
DevOps pipeline acceleration is compressing testing cycles from weeks to hours, forcing outsourced providers to embed automation engineers directly into client sprint teams rather than operate as external gatekeepers.
Growth Catalysts
- EU AI Act conformity assessments:Healthcare and automotive OEMs now require algorithmic bias validation and security testing for AI-embedded software, expanding contracted testing scope beyond traditional functional verification.
- Cloud migration velocity:Enterprises shifting ERP and customer-facing applications to AWS, Azure, and GCP environments demand continuous compatibility and performance testing across hybrid infrastructure.
- India delivery cluster density:Bengaluru, Hyderabad, and Pune host concentrated engineering talent pools that enable 24-hour follow-the-sun testing cycles for North American and European clients.
Market Restraints
- Specialized automation engineer scarcity:Demand for Selenium, Cypress, and Playwright specialists exceeds supply in Tier-2 Indian cities, inflating wage premiums and attrition rates.
- Cross-border data residency mandates:Germany's BDSG and China's PIPL require testing environments to remain within national boundaries, fragmenting delivery architectures and duplicating infrastructure costs.
- Low-code platform substitution:Microsoft Power Apps and Salesforce Lightning include built-in automated testing modules that capture simpler validation workflows in-house.
Strategic Opportunities
- MedTech security certification gaps:FDA 21 CFR Part 820 and EU MDR cybersecurity requirements for connected devices create unmet demand for penetration testing and SBOM validation services.
- Generative AI test generation:Large language model-powered script creation converges with existing automation frameworks to reduce manual test case authoring effort by half.
- Embedded finance testing:Banking-as-a-Service APIs in retail and logistics platforms require specialized open banking protocol validation that generalist IT services cannot provide.
Industry Challenges
- Legacy mainframe integration complexity:Financial services clients require COBOL and AS/400 system connectivity testing that younger engineering workforces lack hands-on experience to execute.
- ISO 27001 and SOC 2 Type II audit fatigue:Continuous certification renewals consume 15-20% of operational bandwidth at mid-sized testing boutiques without dedicated compliance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Software Testing Services Market |
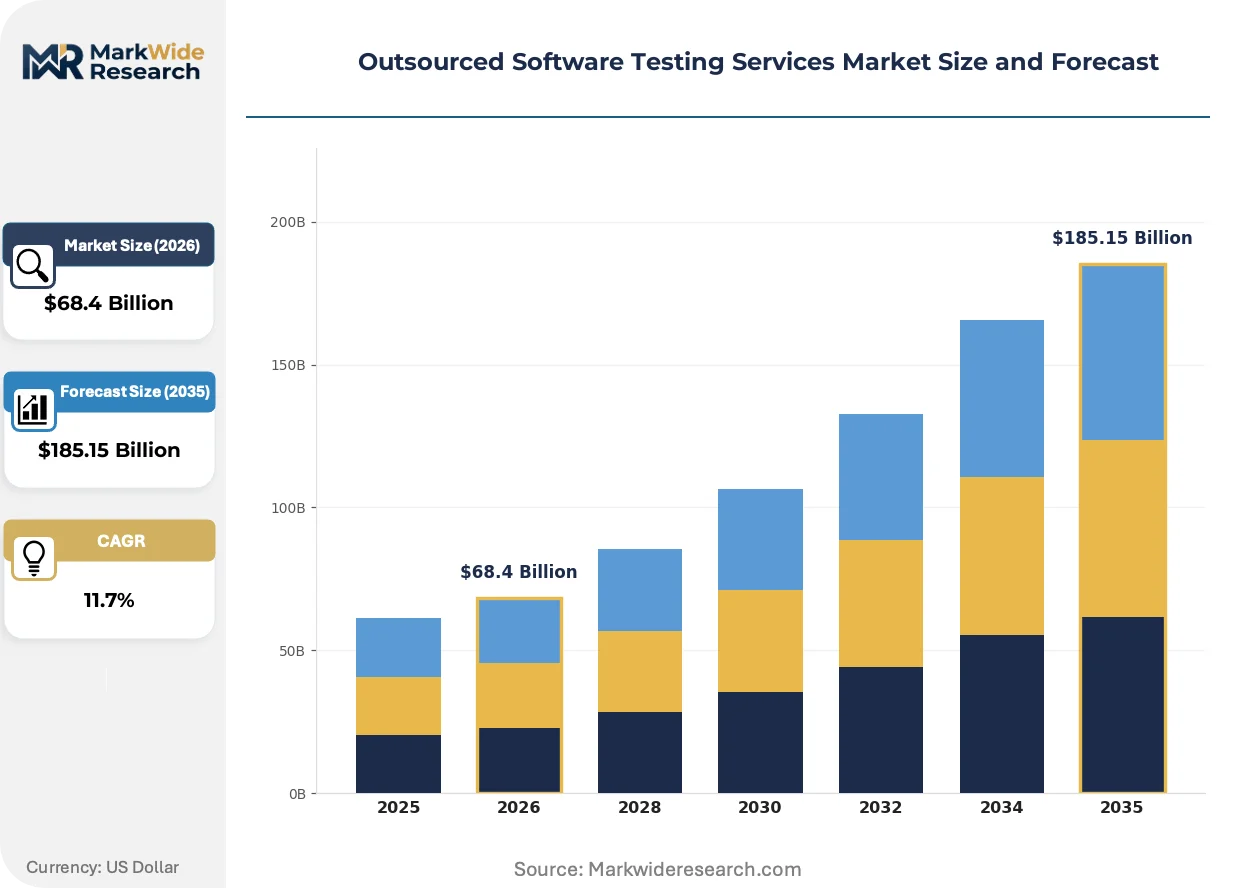
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Functional Testing, Performance Testing, Security Testing, Usability Testing Technology: Cloud-Based Solutions, Automated Testing Tools, Manual Testing, Mobile Testing End User: IT Companies, E-Commerce, Healthcare Providers, Telecommunication Delivery Model: Onshore, Offshore, Nearshore, Hybrid |
| Companies Covered | Accenture, Capgemini, Cognizant Technology Solutions, Tata Consultancy Services, Wipro, HCLTech, Qualitest, Cigniti Technologies, Tech Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Software Testing Services Market Strategic Shifts
Autonomous testing capabilities are redefining quality assurance economics by reducing human intervention in script maintenance and defect triage. Three developments are compressing delivery models and reshaping buyer expectations.
AI-powered self-healing test scripts is overtaking brittle locator-based automation in enterprise regression suites. E-commerce and fintech platforms with weekly release cadences now mandate tools that automatically adapt to UI changes without manual rework. This capability is compressing maintenance overhead from 40% of testing effort toward 15%, enabling providers to reallocate engineering resources toward exploratory and security testing.
EU AI Act risk classification requirements are mandating independent algorithmic audits for high-risk diagnostic and credit-scoring applications. Medical device manufacturers must document validation datasets and performance benchmarks before CE marking. German and French healthcare software vendors are responding by contracting specialized AI testing boutiques rather than generalist quality assurance firms.
Embedded quality engineering contracts are displacing transactional project-based testing engagements. Automotive and aerospace OEMs now require testing partners to assume outcome-based liability for production defects rather than time-and-material billing. This shift is most visible in Germany's industrial software sector, where suppliers absorb financial penalties for post-deployment failures detected in connected manufacturing systems.
Outsourced Software Testing Services Market Segmentation
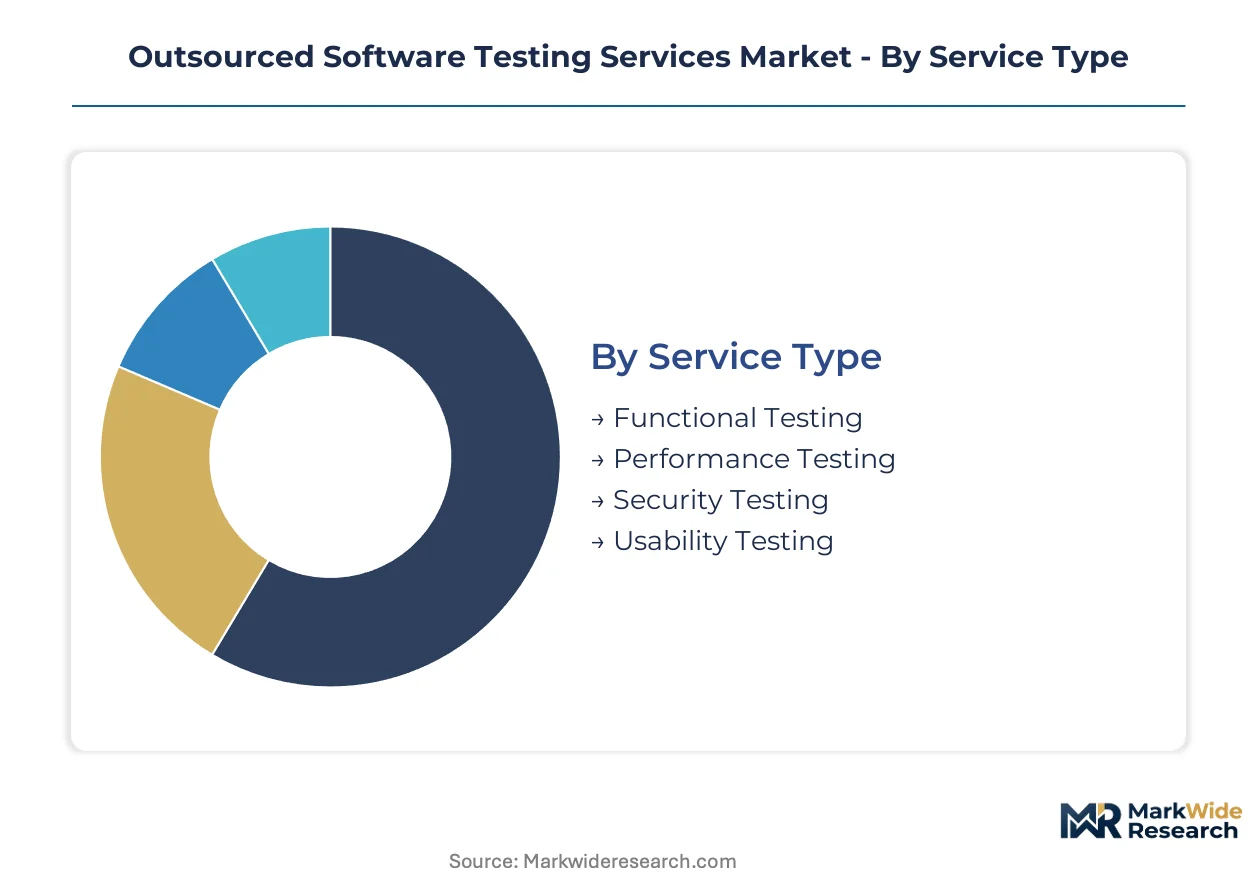
Testing service segmentation reveals how buyers prioritize validation depth against speed-to-market pressures. Technology choices increasingly dictate contract structures as automation maturity varies sharply across client IT estates.
Service Type:
Technical specification of validation scope determines staffing models and pricing architecture.
- Functional Testing:Script-based verification of business logic, API contracts, and data workflows across web and enterprise applications. Healthcare providers in the United States demand exhaustive EHR validation under FDA 21 CFR Part 820, creating structural demand for independent documentation that internal QA teams cannot self-certify.
- Security Testing:Penetration testing, vulnerability scanning, and SBOM validation for connected devices and cloud-native architectures. EU AI Act conformity assessments for high-risk diagnostic tools are expanding contracted scope beyond traditional defect detection into algorithmic bias verification and adversarial robustness checks.
- Performance Testing:Load simulation and stress validation for throughput thresholds under concurrent user spikes.
- Usability Testing:Human-centered evaluation of interface intuitiveness and accessibility compliance.
Mature deployment sits with Functional Testing. Newer deployment is concentrated in Security Testing.
Technology:
Cost tier alignment separates premium automation capabilities from commodity manual execution.
- Automated Testing Tools:Selenium, Cypress, and Playwright frameworks executing regression suites without human intervention. E-commerce platforms with weekly release cadences in India mandate self-healing scripts that adapt to UI changes automatically, compressing maintenance overhead toward 15% of total testing effort.
- Cloud-Based Solutions:Elastic test environment provisioning across AWS, Azure, and GCP infrastructure. North American enterprises accelerating DevOps adoption are displacing on-premise hardware investments with consumption-based models that scale validation capacity on demand.
- Manual Testing:Exploratory and usability validation requiring human judgment for interface intuitiveness.
- Mobile Testing:Device fragmentation management across iOS and Android form factors with OS version compatibility matrices.
Premium pricing attaches to Automated Testing Tools. Volume concentration flows through Cloud-Based Solutions.
End User:
Application complexity and regulatory exposure determine outsourcing penetration rates.
- Healthcare Providers:Electronic health record validation, connected medical device software verification, and clinical workflow testing. German and French healthcare software vendors are contracting specialized AI testing boutiques for EU MDR cybersecurity requirements rather than generalist quality assurance firms.
- IT Companies:Product engineering validation for SaaS platforms and enterprise software vendors.
- E-Commerce:Checkout flow verification, payment gateway integration testing, and cross-browser compatibility.
- Telecommunication:Network function virtualization testing and OSS/BSS system validation.
Regulatory intensity peaks with Healthcare Providers. Standardization maturity runs highest through IT Companies.
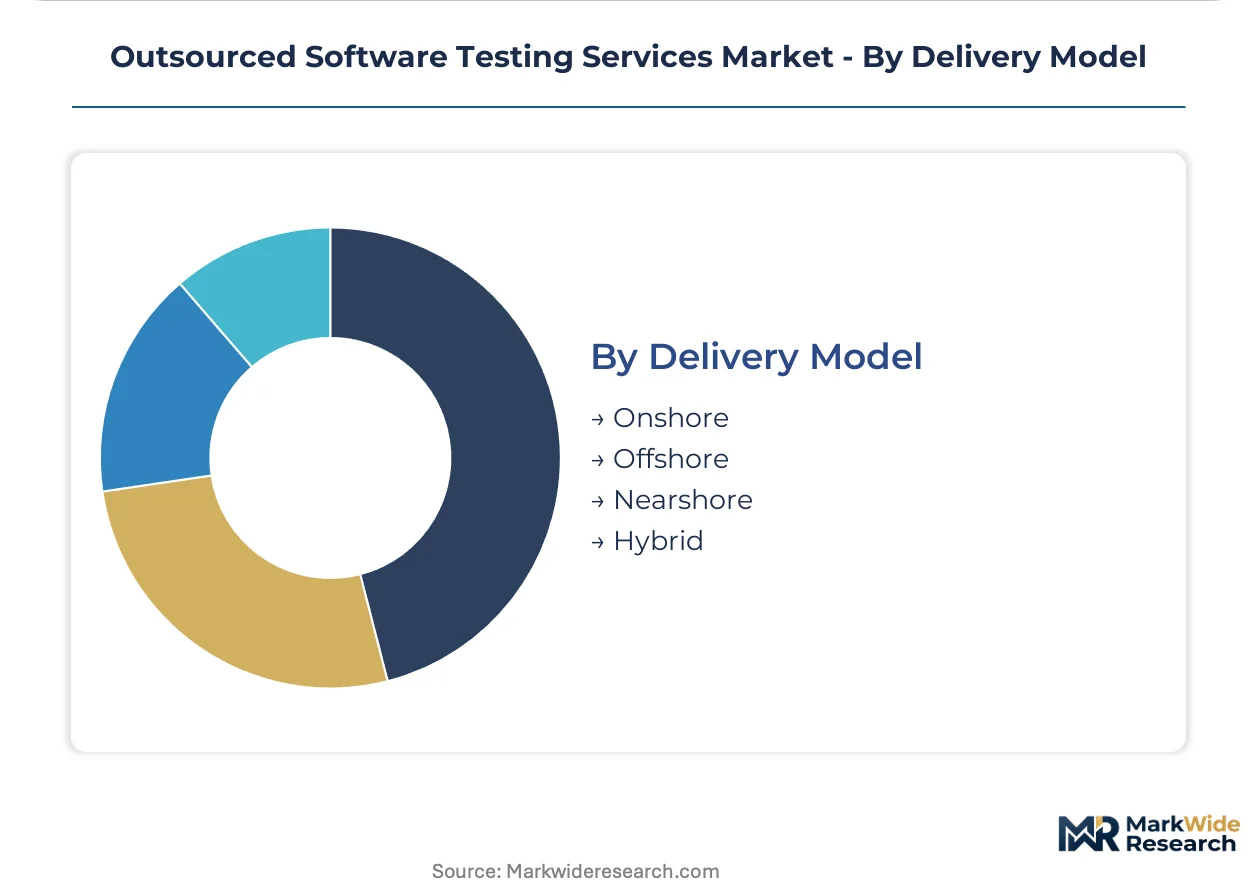
Delivery Model:
Geographic distribution of engineering talent shapes cost arbitrage and data residency compliance.
- Offshore:Concentrated delivery from Bengaluru, Hyderabad, and Pune enabling 24-hour follow-the-sun cycles for North American and European clients. India's Tier-2 cities face scarcity premiums for Selenium and Cypress specialists, inflating attrition rates above 25% annually.
- Hybrid:Blended onshore client presence with offshore execution centers, balancing sprint team embedding with cost efficiency. Germany's BDSG and China's PIPL are fragmenting architectures as clients mandate testing environments within national boundaries.
- Onshore:Domestic delivery for classified government contracts and financial services regulatory examinations.
- Nearshore:Regional proximity models for Latin American and Eastern European clients seeking timezone alignment.
Scale concentration favors Offshore. Compliance-sensitive workloads are migrating toward Hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme and Special Economic Zones have concentrated outsourced testing delivery in Bengaluru, Hyderabad, and Pune, creating tax-advantaged infrastructure that anchors global service provision for North American and European clients.
United States
FDA 21 CFR Part 820 validation requirements for medical device software and HIPAA security mandates for healthcare applications drive structural demand for independent testing documentation. The FDA's cybersecurity guidance for connected devices expands contracted scope into penetration testing and SBOM validation. Dallas and Austin host growing delivery centers serving domestic healthcare and financial services clients requiring onshore data residency.
Germany
EU AI Act conformity assessments for high-risk diagnostic tools and EU MDR cybersecurity requirements mandate algorithmic bias verification and adversarial robustness testing. Germany's BDSG data residency rules fragment delivery architectures by requiring testing environments within national boundaries. Munich and Berlin industrial software vendors contract specialized AI testing boutiques for connected manufacturing system validation.
India
STPI tax incentives and SEZ infrastructure concentrate 24-hour follow-the-sun testing cycles for North American and European clients across Bengaluru, Hyderabad, and Pune. Tier-2 cities face scarcity premiums for Selenium and Cypress specialists, inflating attrition rates above 25% annually. The concentrated engineering talent pools enable compressed delivery timelines for DevOps-integrated automation frameworks.
United Kingdom
Financial Conduct Authority open banking protocols and Prudential Regulation Authority operational resilience mandates drive specialized API and embedded finance testing demand. GDPR cross-border data governance rules determine audit trail requirements for multinational testing engagements. London's fintech cluster contracts outcome-based quality engineering partnerships with liability assumptions for production defects.
China
PIPL data localization requirements mandate testing environments remain within national boundaries, duplicating infrastructure costs for multinational providers. MIIT cybersecurity certification for connected devices and SAMR algorithmic governance for AI-embedded applications expand compliance scope. Shanghai and Shenzhen delivery centers serve domestic technology platforms requiring localized validation for cloud-native architectures.
Outsourced Software Testing Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. The vendor base organizes around three strategic archetypes: global IT services conglomerates with integrated testing divisions, dedicated quality engineering boutiques with sector-specific certifications, and mid-scale regional providers with cost-optimized delivery models. Dominant competitive moves include vertical capability acquisitions to fill AI testing gaps and outcome-based contract restructuring that shifts liability to service providers.
Within the global IT services tier, Accenture leverages its multi-industry delivery footprint to anchor large enterprise engagements, while Capgemini occupies a position emphasizing banking and telecommunications protocol specialization. Tata Consultancy Services exemplifies the automation-led archetype through proprietary framework development that compresses cloud migration cycle times. These three entities represent distinct competitive vectors: geographic reach, sector depth, and tooling differentiation.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Cognizant Technology Solutions |
| Tata Consultancy Services |
| Wipro |
| HCLTech |
| Qualitest |
| Cigniti Technologies |
| Tech Mahindra |
| Others |
Value Chain & Pricing Dynamics
Healthcare providers and automotive OEMs purchasing AI validation services operate under fixed-budget procurement frameworks that compress margins for non-specialized testing vendors. These buyers negotiate outcome-based contracts with penalty clauses for post-deployment defects, forcing providers to absorb quality assurance risk.
Pricing Analysis
Expedited delivery timelines command 30-40% premiums over standard project rates, while spot engagements for crisis remediation trade at the highest tier. Pricing stratifies across premium AI algorithmic audit tiers, standard functional regression suites, and economy manual validation packages. Cost compression in the manual testing tier is intensifying because low-code platforms internalize simpler workflows. Mid-sized healthcare providers exhibit the sharpest price sensitivity, whereas multinational pharmaceutical manufacturers prioritize certification pedigree over unit cost.
Supply Chain Analysis
Regional delivery hubs in Bengaluru, Hyderabad, and Pune anchor hub-and-spoke distribution of engineering talent to North American and European client sites. India, Poland, and Mexico constitute the primary geographic supply nodes for automated testing capacity. The talent pipeline draws from computer science graduate pools, proprietary framework licensing, and cloud infrastructure subscriptions. Single-source vulnerability concentrates in India's Tier-2 cities where Selenium and Cypress specialist scarcity inflates wage premiums. Distribution runs through hybrid onshore-offshore engagement models with embedded sprint team deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The outsourced software testing market functions as a cost-of-compliance arena where FDA 21 CFR Part 820 and EU AI Act documentation requirements erect formidable barriers to entry for uncertified competitors.
For Market Incumbents: Cement defensive positioning by acquiring specialized AI testing boutiques with EU MDR cybersecurity credentials, countering the threat of algorithmic audit pure-plays capturing high-margin healthcare contracts. Deepen backward integration into proprietary self-healing automation frameworks that reduce client dependency on open-source tooling. For New Entrants and Emerging Players: Launch via embedded quality engineering partnerships with German industrial software vendors seeking outcome-based liability transfer for connected manufacturing systems. Target the MedTech security certification gap where SBOM validation and penetration testing demand outstrips boutique supply. Prioritize go-to-market positioning around EU AI Act conformity assessment speed. For Investors and Strategic Acquirers: The window for entry favors quality engineering boutiques with vertical healthcare credentials and existing FDA submission documentation capabilities. Long-term viability hinges on automation framework IP ownership rather than staff-augmentment contracting. Watch for inflection when EU AI Act enforcement triggers mandatory third-party algorithmic audit procurement thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | EU MDR-certified boutiques command premium multiples from healthcare incumbents seeking algorithmic audit capabilities. |
| Platform Integration | Self-healing script frameworks embedded into client DevOps pipelines reduce maintenance overhead and deepen switching costs. |
| Geographic Expansion | Delivery centers in Germany and China satisfy BDSG and PIPL data residency mandates for compliance-sensitive contracts. |
| Strategic Partnership | Alliances with hyperscalers provide preferred cloud testing environment provisioning for enterprise cloud migration programs. |
| Product Launch | Generative AI-powered test case generation tools capture efficiency gains in manual scripting workflows. |
Study Parameters
Document review covered SEC filings from IT services conglomerates, EU regulatory guidance repositories, and FDA software validation guidance documents, complemented by interviews with CTOs at healthcare software vendors, quality engineering directors at automotive OEMs, procurement leads at hospital systems, and automation architects at cloud service providers. Secondary validation drew from DevOps toolchain adoption surveys, hyperscaler capex disclosures, and Indian IT industry association employment data. Bottom-up service line revenue estimates triangulated against top-down market sizing from regulatory mandate expansion projections.
Segment-level value outputs across the projection horizon reflect modeled deployment of automated testing tools, cloud-based solutions, manual testing, and mobile testing technologies by healthcare providers, IT companies, e-commerce platforms, and telecommunications operators. Organization size and vertical regulatory intensity served as cross-cutting segmentation dimensions. CAGRs derived from elasticity modeling of compliance mandate expansion rates against automation adoption curves, incorporating cloud migration velocity and AI-embedded software penetration as industry-specific demand drivers.
Regulatory enforcement timing, cloud infrastructure cost volatility, and generative AI capability maturation are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions regarding EU AI Act implementation schedules and FDA cybersecurity guidance finalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Note Taking App Market
Software & Services
Radio Propagation Software Market
Software & Services
Session Support Software Market
Software & Services
Sourcing Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Procurement Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Projector Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Media Planning Software Market
Software & Services
Employee Referral Software Market
Software & Services
Compositing Software Market