
 Fenoxanil Market | 2026-2036
Fenoxanil Market Size, Share, and Industry Trends Forecast 2026-2036
Fenoxanil Market Insights
The price-performance gap between premium formulated emulsions and commodity powder generics is hardening. BASF SE leverages its patented formulation technology to command premium positioning in liquid concentrates. Syngenta Group anchors its portfolio through integrated seed-and-crop-protection bundles across Asian rice belts. Sumitomo Chemical Co., Ltd. differentiates via proprietary adjuvant systems that improve rainfastness in tropical applications.
Fenoxanil is a carboxanilide fungicide that inhibits mitochondrial respiration by binding to cytochrome bc1 complex, with application rates typically ranging from 100 to 400 grams active ingredient per hectare for rice blast control. The compound functions primarily as a protective and curative treatment against Magnaporthe oryzae in cereal production systems. Liquid emulsions capture the dominant margin pool due to farmer preference for ready-to-apply convenience and reduced drift losses during aerial spraying. Agricultural Crops generate the largest volume base, while greenhouse applications represent the fastest-expanding segment as controlled-environment agriculture spreads. Farmers remain the core end-user constituency, though agricultural cooperatives in East Asia consolidate procurement to negotiate volume-based supply agreements.
EPA registration requirements under FIFRA govern product approval timelines and residue tolerance thresholds in the United States, while China's NMPA and GB standards mandate extensive field trial documentation before domestic manufacturing authorization. REACH compliance in Europe constrains formulation chemistry options and drives substitution toward lower-toxicity co-formulants. Stakeholders must monitor evolving maximum residue limits in import markets and align R&D pipelines with regulatory pre-approval data requirements.
Market Dynamics
Rice blast disease pressure across Southeast Asian deltas is tightening fenoxanil demand concentration, while China's NMPA registration pathway lengthens product entry timelines for new entrants.
Growth Catalysts
- Blast disease intensification:Vietnam's Mekong Delta and Thailand's Central Plains report escalating Magnaporthe oryzae pressure, forcing protective fungicide applications on irrigated rice acreage.
- NMPA pathway consolidation:China's tightened GB standards for novel agrochemicals favor incumbent registrants with established field trial dossiers, reducing competitive fragmentation.
- Aerial application expansion:Drone spraying adoption across Indonesian and Philippine rice belts accelerates liquid emulsion uptake due to drift reduction requirements.
Market Restraints
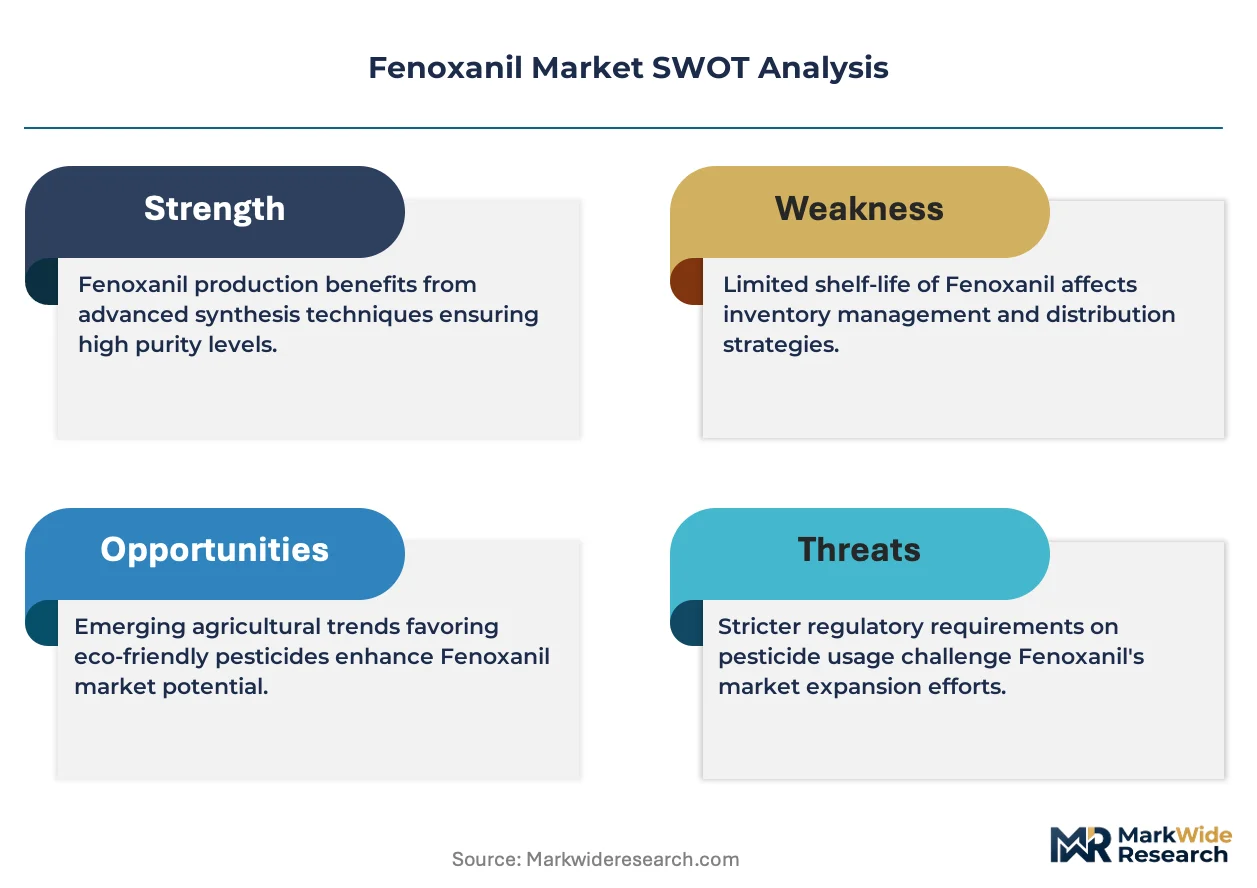
- Active ingredient cost volatility:Carboxanilide precursor supply concentrates among Chinese specialty chemical manufacturers, exposing formulators to input price swings.
- Residue tolerance compression:Import market MRL tightening—particularly EU EFSA reviews and Japan's positive list system—constrains application rate flexibility for export-oriented growers.
- Biological substitute emergence:Bacillus-based biofungicides gain traction in organic-certified rice operations, displacing synthetic protectants in premium export segments.
Strategic Opportunities
- Controlled-environment agriculture:Greenhouse tomato and pepper operations in Vietnam and China represent underpenetrated vectors for blast-protectant extension beyond field rice.
- Cooperative procurement consolidation:East Asian agricultural cooperatives are centralizing volume negotiations, creating channel leverage for long-term supply agreements.
- Dual carbon alignment:China's dual carbon goals incentivize low-drift, precision-application formulations that reduce environmental load per hectare treated.
Industry Challenges
- Formulation chemist scarcity:Rainfast adjuvant development for tropical high-humidity conditions requires specialized expertise concentrated among Japanese and European R&D centers.
- Registration timeline capital lockup:NMPA field trial requirements demand multi-year capital commitment before revenue realization, straining mid-tier development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fenoxanil Market |
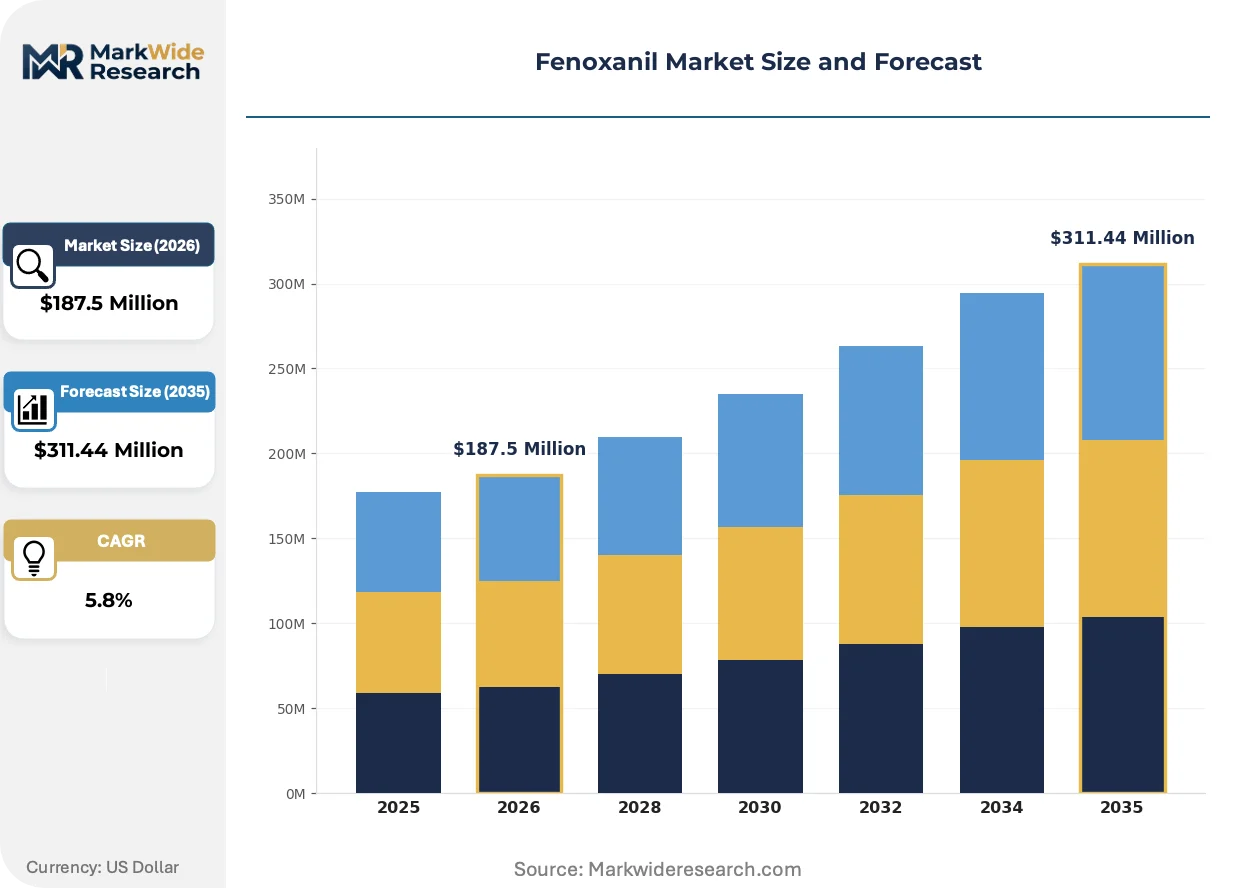
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powders, Liquids, Emulsions Application: Agricultural Crops, Ornamental Plants, Turf, Greenhouses End User: Farmers, Agricultural Cooperatives, Nurseries, Landscapers Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | BASF SE, Syngenta Group, Bayer Crop Science, Sumitomo Chemical Co., Ltd., Corteva Agriscience, FMC Corporation, UPL Limited, Adama Agricultural Solutions Ltd., Jiangsu Yangnong Chemical Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fenoxanil Market Trends and Innovations
Formulation chemistry and application technology are converging to address tropical environmental stressors, while regulatory data requirements reshape competitive entry economics.
Microencapsulation technology is unifying active ingredient protection with controlled-release kinetics for high-rainfall zones. Vietnamese and Thai aerial application contractors adopt these formulations to reduce re-spray frequency during monsoon peaks. The technology is compressing per-hectare labor costs while extending residual efficacy windows.
REACH compliance constraints in Europe are forcing substitution toward lower-toxicity co-formulants in export-bound products. ECHA substance evaluation timelines extend reformulation lead times by twelve to eighteen months for manufacturers serving EU import markets. Asian formulators with pre-validated alternative chemistries capture accelerated placement in residue-sensitive supply chains.
Farmer cooperatives in East Asia are consolidating procurement decisions through digital tender platforms that disaggregate traditional distributor networks. Volume aggregation enables direct manufacturer negotiation, compressing channel margins previously captured by provincial agrochemical wholesalers. This pattern is most visible in Vietnam's Mekong Delta and China's Hunan province rice belts.
Fenoxanil Market Segmentation
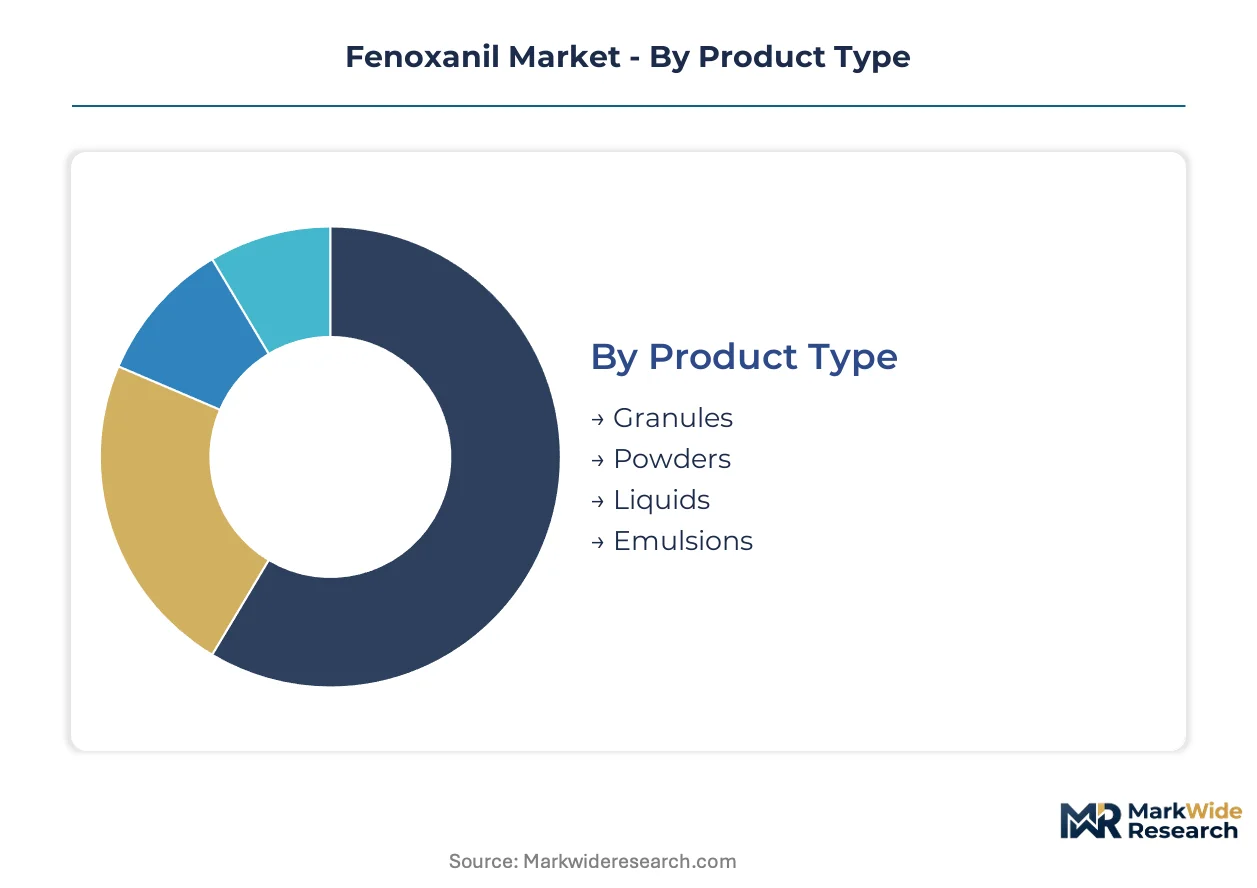
Fenoxanil formulation choices directly determine application economics, residue compliance, and labor efficiency across divergent rice cultivation systems. Segmentation reveals how product format, use case, and procurement channel intersect to shape vendor strategy and farmer purchasing behavior.
Product Type:
Cost tier differentiation separates commodity generics from precision-formulated premium products, with farmer cash flow and equipment access driving format selection.
- Liquids:Ready-to-apply concentrates eliminate mixing labor and reduce drift losses during aerial spraying in Vietnam's Mekong Delta. Drone contractors across Indonesian rice belts specify liquid formats to meet drift reduction mandates and compress re-spray frequency during monsoon peaks.
- Emulsions:Patented formulation technology from BASF SE and proprietary adjuvant systems from Sumitomo Chemical deliver superior rainfastness in tropical high-humidity conditions. Premium positioning captures the dominant margin pool as farmers prioritize residual efficacy over unit price.
- Granules:Slow-release matrix formulations suit manual broadcast applications on smallholder plots lacking mechanized spray equipment.
- Powders:Generic powder formulations serve price-sensitive procurement through agricultural cooperatives in China's Hunan province rice belts.
Liquids lead on scale; emulsions lead on momentum.
Application:
Volume concentration versus technology adoption speed splits the opportunity set between established field crops and emerging controlled-environment systems.
- Agricultural Crops:Irrigated rice acreage across Southeast Asian deltas generates the largest absolute volume base, with blast disease pressure from Magnaporthe oryzae forcing multiple protective applications per season.
- Greenhouses:Controlled-environment tomato and pepper operations in Vietnam and China represent underpenetrated vectors for blast-protectant extension beyond field rice, with precision dosing requirements favoring liquid concentrate uptake.
- Turf:Golf course and sports field maintenance in subtropical climates drives seasonal demand for curative blast treatments.
- Ornamental Plants:Nursery operations prioritize residue-sensitive formulations for export-bound flowering stock subject to EU EFSA and Japan positive list MRL scrutiny.
Agricultural Crops anchor volume; Greenhouses climb the fastest.
End User:
Procurement consolidation patterns reshape channel economics, with aggregation scale determining negotiation leverage and supply agreement structure.
- Farmers:Individual smallholders remain the core constituency across Southeast Asian rice belts, though their purchasing decisions increasingly flow through cooperative structures.
- Agricultural Cooperatives:East Asian cooperatives centralize volume negotiations through digital tender platforms, disaggregating traditional provincial wholesaler networks and compressing channel margins.
- Nurseries:Export-oriented ornamental producers demand pre-validated low-residue formulations to satisfy EU REACH compliance and Japan's positive list system.
- Landscapers:Commercial turf maintenance contractors prioritize application convenience and labor cost reduction over unit active ingredient price.
Farmers dominate headcount; Agricultural Cooperatives gain share fastest.
Distribution Channel:
Margin compression and disintermediation pressures are restructuring how formulated products reach end users across fragmented rural geographies.
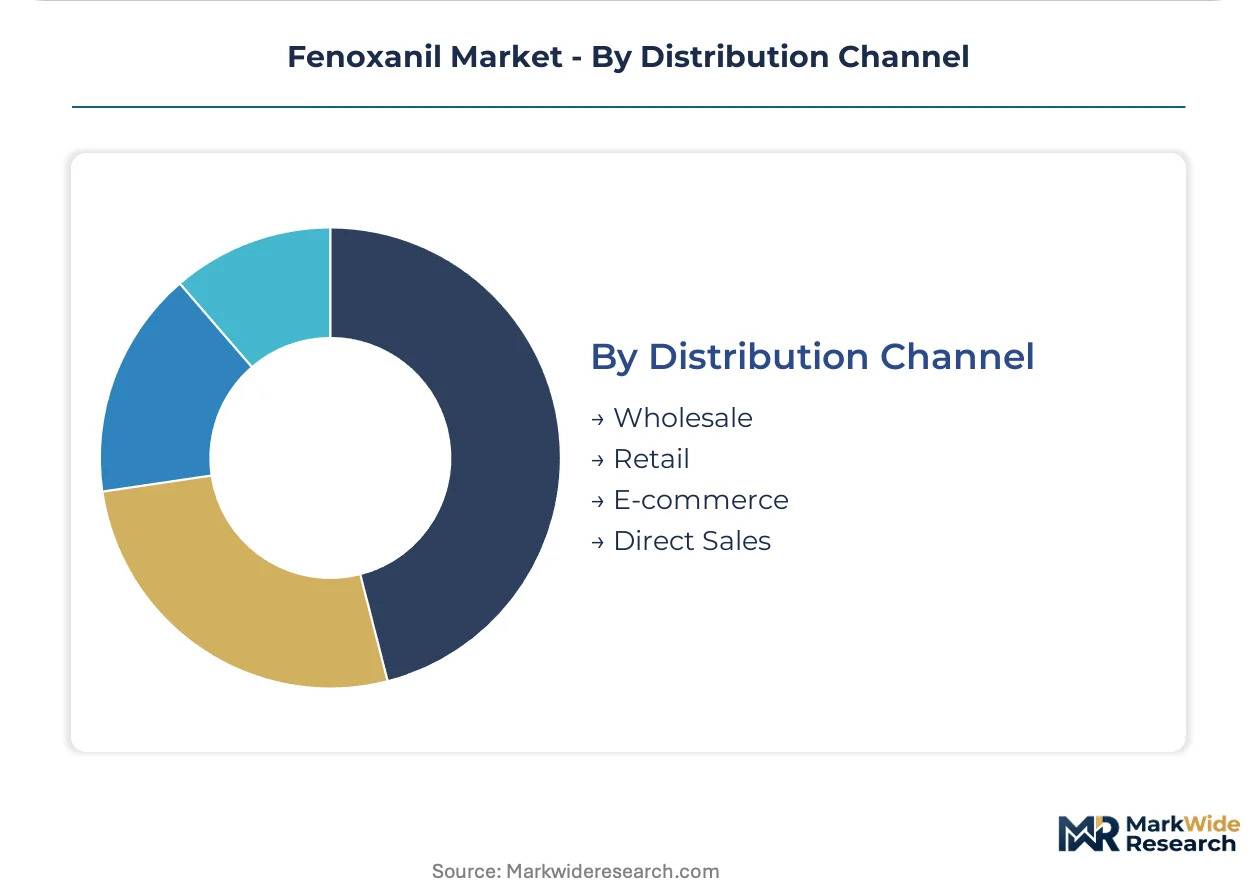
- Wholesale:Provincial agrochemical wholesalers retain relevance in remote rice belts lacking digital infrastructure, though cooperative procurement consolidation erodes their margin capture.
- Direct Sales:Manufacturers negotiate long-term supply agreements with centralized cooperative buyers, bypassing traditional distributor tiers to secure volume commitments.
- Retail:Local agro-input shops serve immediate-need purchases and small-lot buyers outside cooperative membership.
- E-commerce:Digital tender platforms enable transparent price discovery and volume aggregation, accelerating placement in residue-sensitive supply chains.
Wholesale retains reach; Direct Sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic expertise clusters in East Asian rice belts anchor regional fungicide demand, with formulation chemists concentrated in Japanese and European R&D centers supporting tropical application development.
China
Rice blast pressure across Hunan and Jiangsu provinces sustains protective fungicide volumes, while NMPA registration requirements under GB standards lengthen field trial documentation timelines. The Yangtze River Delta hosts domestic formulators scaling emulsion production for drone application contractors.
Vietnam
Magnaporthe oryzae intensification in the Mekong Delta forces multiple seasonal applications on irrigated acreage, with agricultural cooperatives centralizing procurement through digital tender platforms. Provincial wholesalers in Can Tho and An Giang face margin compression from direct manufacturer negotiations.
Thailand
Blast disease pressure across the Central Plains drives curative treatment demand, with the national agricultural regulator enforcing residue tolerance alignment with EU EFSA import standards. Bangkok-based distributors coordinate liquid concentrate supply for aerial spraying contractors.
Indonesia
Drone spraying adoption accelerates in Java and Sumatra rice belts, with drift reduction mandates favoring ready-to-apply liquid formats over powder generics. The Ministry of Agriculture coordinates with provincial extension services on application timing protocols.
Japan
Positive list system enforcement constrains residue thresholds for export-bound rice, with METI oversight of agrochemical manufacturing standards. Kyushu-based research stations develop rainfast adjuvant systems for tropical high-humidity deployment.
Fenoxanil Market Competitive Landscape
Top-tier vendors anchor premium formulation tiers, while commodity generic producers compete on unit price through agricultural cooperative channels. The vendor base stratifies across patented technology holders, integrated crop-protection bundlers, and regional formulators serving price-sensitive procurement. Three archetypes dominate: multinational agrochemical conglomerates with formulation IP, Asian chemical groups with backward integration into active ingredient supply, and cooperative-aligned distributors with channel control in fragmented rural geographies. Competitive moves concentrate on portfolio diversification beyond rice blast into greenhouse vegetables, and geographic expansion through NMPA registration consolidation in China.
Within the multinational tier, BASF SE and Syngenta Group exemplify premium positioning through proprietary formulation technology and integrated seed-and-crop-protection bundles respectively. Sumitomo Chemical Co., Ltd. occupies a specialist position via proprietary adjuvant systems. Among Asia-based chemical groups, Jiangsu Yangnong Chemical Group Co., Ltd. represents domestic manufacturing scale serving cooperative procurement consolidation.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer Crop Science |
| Sumitomo Chemical Co., Ltd. |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Adama Agricultural Solutions Ltd. |
| Jiangsu Yangnong Chemical Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into carboxanilide precursor production anchors pricing power for Chinese specialty chemical manufacturers, while formulators lacking captive supply face margin compression from input volatility. This integration pattern separates premium emulsion producers from commodity powder competitors across Southeast Asian rice belts.
Pricing Analysis
Bundled seed-and-crop-protection offerings from Syngenta Group command premium positioning against unbundled generic procurement through agricultural cooperatives. Three-tier pricing structure across premium emulsions, standard liquids, and economy powders reflects formulation complexity and rainfastness performance. Pricing pressure stems from biological substitute emergence in organic-certified segments. Smallholder farmers in Vietnam's Mekong Delta exhibit highest price sensitivity, while drone contractors prioritize application efficiency over unit cost.
Supply Chain Analysis
Carboxanilide active ingredient supply rests on Chinese specialty chemical manufacturers, with formulation capacity concentrated in Japan and Germany. Key inputs include aniline derivatives, chloroacetic acid intermediates, and proprietary adjuvant systems. Single-source vulnerability in precursor supply exposes formulators to input price swings during regulatory inspection periods. Distribution runs through provincial agrochemical wholesalers facing disintermediation from cooperative digital tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium formulation tiers as rainfastness performance separates price-setters from price-takers, with drone application adoption accelerating demand for drift-reduced liquid concentrates.
For Market Incumbents: Lock in cooperative procurement relationships through long-term supply agreements before digital tender platforms complete channel disintermediation. Deepen backward integration into adjuvant chemistry to defend formulation differentiation against generic entrants. Prioritize NMPA registration dossier completion to exploit China's tightened GB standards barrier. For New Entrants and Emerging Players: Digital tender platforms offer direct access to Vietnam's Mekong Delta cooperatives bypassing traditional provincial wholesaler networks. Target greenhouse vegetable operations in China and Vietnam as underpenetrated blast-protectant applications beyond field rice. Lead with microencapsulation technology to differentiate on re-spray frequency reduction during monsoon peaks. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with established NMPA registrations because China's lengthened field trial timelines create scarcity value in approved active ingredient portfolios. Acquisition targets include Vietnamese distributors with cooperative relationships and Japanese adjuvant specialists. Watch drone spraying penetration rates across Indonesian rice belts as inflection indicator for liquid emulsion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Deployment | Extends residual efficacy windows for Vietnamese aerial application contractors during monsoon peaks. |
| NMPA Registration Consolidation | Captures scarcity premium as China's GB standards lengthen approval timelines for competitors. |
| Cooperative Procurement Integration | Secures volume commitments through East Asian agricultural cooperative digital tender platforms. |
| Greenhouse Segment Extension | Diversifies revenue base into Vietnam and China controlled-environment tomato and pepper operations. |
| Adjuvant Chemistry Backward Integration | Protects rainfastness formulation differentiation from generic price competition in tropical markets. |
Research Methodology
Direct dialogue with formulation chemists, agricultural cooperative procurement managers, drone spraying contractors, and NMPA regulatory consultants grounded qualitative findings. Secondary validation drew from China NMPA registration databases, Vietnam Ministry of Agriculture extension reports, EU EFSA residue tolerance reviews, and Japanese METI manufacturing standards. Bottom-up volume estimates from country-level rice acreage and application rate assumptions triangulated against top-down agrochemical trade flow analysis.
Top-down market sizing anchored on rice cultivation statistics across Southeast Asian deltas, with bottom-up segmentation by formulation type, application method, and procurement channel. Modeled dimensions included product format, end-use crop system, and distribution channel structure. CAGRs derived from trend extrapolation of blast disease pressure indices and drone adoption curves across the analysis window. Industry-specific inputs incorporated NMPA approval timeline assumptions and EU MRL compression trajectories.
The model assumes a particular technology adoption path for precision application equipment; alternative pathways for biological fungicide substitution would alter the outlook. Forecasts reflect assumptions regarding regulatory timeline stability and cooperative procurement consolidation velocity. A small set of triggers—NMPA registration moratoria, EU EFSA MRL revisions, and Bacillus-based biofungicide efficacy breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Agricultural Enzymes Market
Others
India Home Automation Market
Others
Digital Audio Decoders Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Fibert Market
Others
Smart Plug Market
Others
Global Application Testing Services Market
Others
Global Car Wax Market
Others
Japan Smart Home Market
Others
Linseed Oil Market
Others
Global Snow Sports Apparel Market
Others
Saudi Arabia Laser Hair Removal Market
Others
North America Halal Food and Beverage Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Smart Home Technologies Market
Others
Cloud DVR Market