
 Automatic Barriers and Bollards Market | 2026-2036
Automatic Barriers and Bollards Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Barriers and Bollards Market Analytics
Aftermarket service revenue is reshaping margin distribution across the automatic barriers and bollards value chain. FAAC Group leverages its European installed base to sustain recurring maintenance contracts. Magnetic Autocontrol GmbH anchors its position through precision-engineered drive mechanisms for high-cycle applications. CAME Group competes on integrated access-control software that extends hardware utility into platform ecosystems.
Automatic barriers and bollards constitute electromechanical or hydraulic vehicle access-control systems, typically rated for impact resistance between 7.5 and 50 metric tons at specified velocities, designed to restrict, channel, or protect pedestrian and vehicular traffic at secured perimeters. Rising bollards dominate critical infrastructure deployments where shallow foundation constraints and retractable operation matter, while steel retains primacy in anti-ram specifications despite aluminum gaining share in corrosion-sensitive coastal installations. Solar power sources represent the fastest-expanding segment within off-grid and remote facility applications, though electric systems still occupy the bulk of urban parking and roadway installations.
The EU Machinery Directive and ISO IWA 14-1 establish baseline impact-performance and safety-interlock standards that manufacturers must satisfy for market access across European jurisdictions. The US Department of State and ASTM F2656 define crash-rating protocols that shape federal and municipal procurement specifications for anti-terrorism applications. Stakeholders must monitor evolving hostile-vehicle-mitigation guidelines and energy-efficiency mandates as these frameworks progressively tighten material, testing, and operational requirements.
Market Dynamics
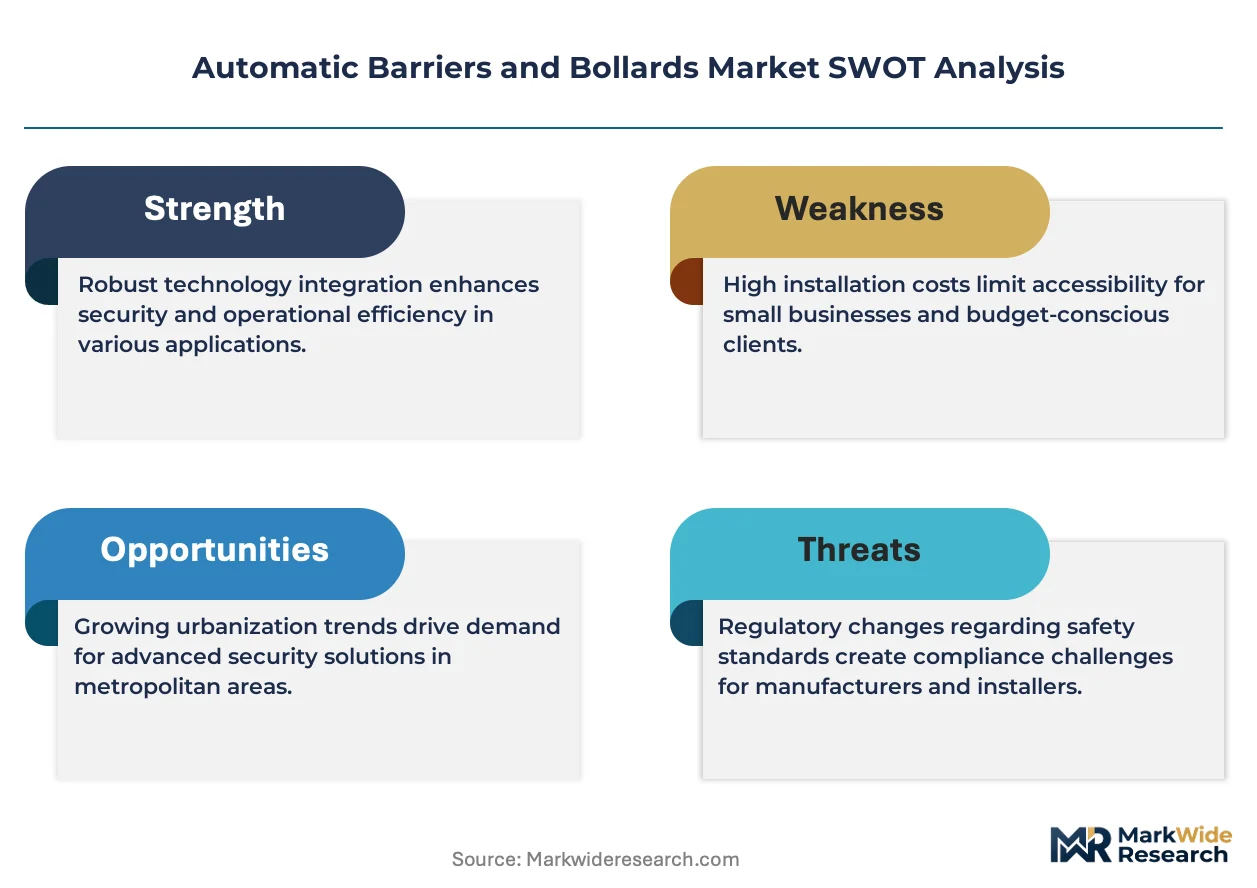
Critical infrastructure protection budgets are redirecting procurement specifications toward crash-rated bollard systems with integrated access-control software, compressing traditional hardware-only vendor margins.
Growth Catalysts
- EU Machinery Directive compliance mandates:Member states now require safety-interlock certification for all electromechanical barriers, forcing facility upgrades across Germany, France, and Italy.
- Airport perimeter hardening:Federal aviation security programs in the United States are expanding specifications for ASTM F2656-rated vehicle barriers at terminal approaches and cargo facilities.
- Solar-powered off-grid deployment:Remote energy infrastructure and mining operations are specifying photovoltaic bollard systems where grid connection proves uneconomical.
Market Restraints
- Steel price volatility:Anti-ram barrier manufacturers face margin pressure from fluctuating hot-rolled coil costs, which constitute 35-45% of finished product weight.
- Foundation engineering complexity:Shallow-bedrock sites in Scandinavia and Alpine regions require specialized geotechnical assessment, extending project timelines.
- Hydraulic fluid environmental regulations:REACH restrictions on mineral oil formulations are forcing reformulation of underground bollard actuation systems.
Strategic Opportunities
- India smart city infrastructure:Municipal corporations in Mumbai, Delhi, and Bangalore are tendering integrated parking barrier systems with license-plate recognition.
- Convergence of physical and cyber access control:Unified platforms combining bollard operation with visitor management software are penetrating corporate campus deployments.
- EU Green Deal retrofit incentives:Member state recovery funds are subsidizing energy-efficient barrier motor replacements in public parking structures.
Industry Challenges
- ISO IWA 14-1 certification timelines:Third-party crash-testing bottlenecks at accredited facilities are extending product launch cycles by 8-14 months.
- Legacy parking system integration:Facility managers struggle to synchronize new automatic barriers with existing pay-on-foot and PARCS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Barriers and Bollards Market |
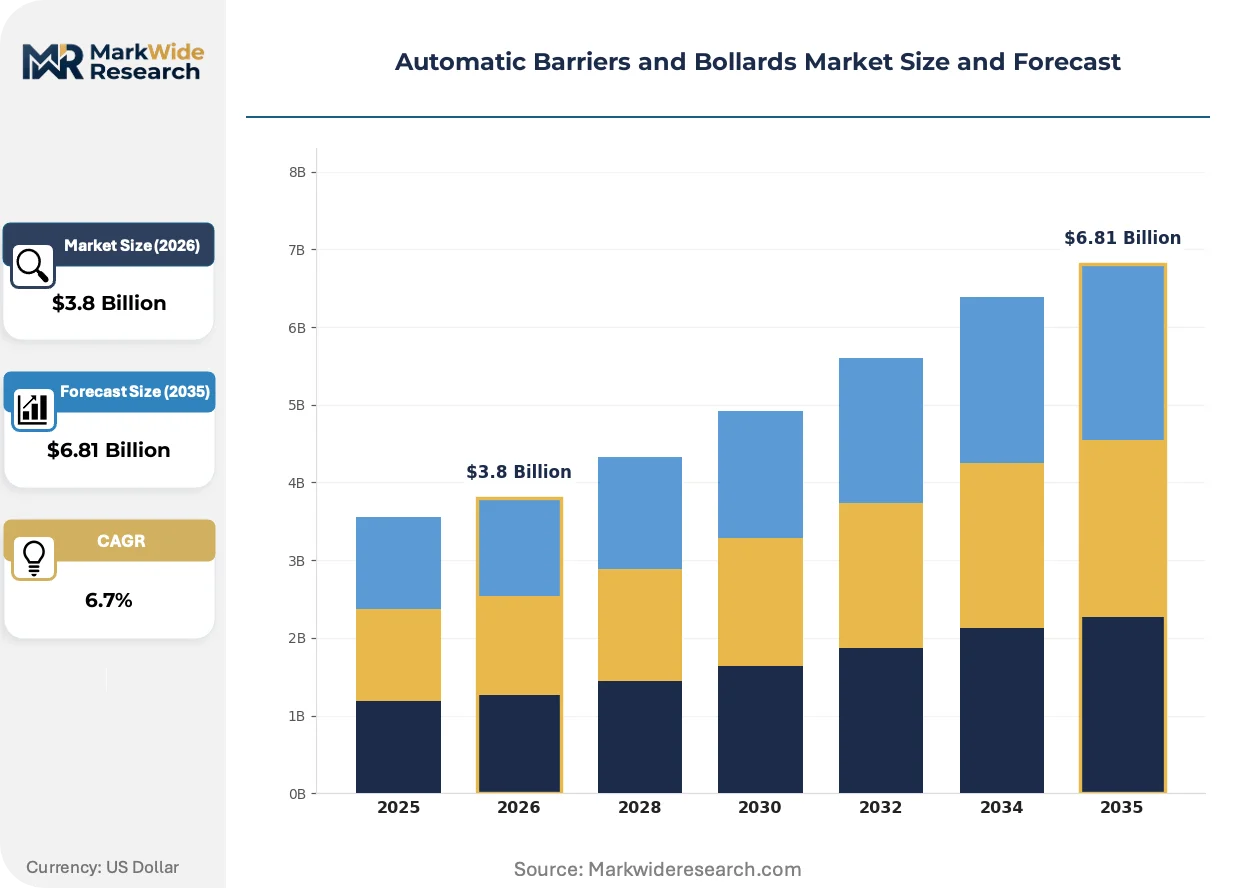
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Barriers, Retractable Bollards, Sliding Barriers, Rising Bollards Material: Steel, Aluminum, Plastic, Composite Installation Type: Pedestrian Zones, Parking Facilities, Roadways, Public Spaces Power Source: Electric, Hydraulic, Solar, Battery |
| Companies Covered | Automatic Systems, FAAC Group, ATG Access Ltd, Avon Barrier, Macs Automated Bollard Systems Ltd, CAME Group, Magnetic Autocontrol GmbH, Bollard Solutions, Houston Systems Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Barriers and Bollards Market Evolving Landscape
Electrification of actuation systems and embedded sensor networks are transforming barrier architectures from mechanical gates into data-generating perimeter nodes.
Brushless DC motor technology is collapsing maintenance intervals for high-cycle parking applications. Airport operators and commercial garage chains are specifying magnet-based drive systems rated for 2-3 million cycles. This shift is collapsing the traditional aftermarket service revenue model that depended on quarterly mechanical inspections.
The EU Machinery Directive 2006/42/EC as amended is mandating functional safety assessments for all new barrier installations. Manufacturers must now document failure-mode analyses and provide SIL-rated control systems. German and Dutch industrial safety inspectors are enforcing these provisions most stringently, rejecting non-compliant imports at port.
Buyers are unbundling hardware procurement from long-term service agreements. Municipal parking authorities now tender equipment and maintenance separately, pitting specialized service firms against original manufacturers. This pattern is most pronounced in French and Spanish urban markets where facility management has consolidated under specialized operators.
Automatic Barriers and Bollards Market Segmentation
Automatic barriers and bollards serve divergent operational requirements across critical infrastructure, commercial parking, and public realm applications. Each segmentation dimension reveals distinct procurement patterns driven by crash-rating mandates, foundation constraints, and energy access limitations.
Product Type:
Product selection hinges on operational frequency, impact-resistance requirements, and subsurface engineering constraints across deployment contexts.
- Rising Bollards:Electromechanical or hydraulic vertical-lift systems rated for 7.5 to 50 metric ton impact resistance at specified velocities. Demand concentrates in German critical infrastructure protection programs where shallow foundation constraints and retractable operation enable rapid threat response without permanent visual obstruction.
- Fixed Barriers:Static anti-ram installations including wedge barriers and cable-reinforced systems permanently embedded in foundations. Federal aviation security programs in the United States specify ASTM F2656-rated fixed barriers at airport cargo facilities and terminal approaches where continuous blocking is operationally acceptable.
- Retractable Bollards:Telescoping or folding designs permitting complete ground-level clearance. Municipal corporations in Mumbai and Delhi specify these for smart city pedestrianization schemes requiring flexible vehicle access.
- Sliding Barriers:Horizontal-movement gates for wide-entry applications. Commercial logistics hubs in France deploy these for high-cycle truck access where vertical bollard spacing proves insufficient.
Established volume favors fixed barriers; emerging adoption favors rising bollards.
Material:
Material selection balances impact-energy absorption, corrosion resistance, and total installed cost across climatic and threat environments.
- Steel:Hot-rolled and alloy formulations dominate anti-ram specifications. REACH restrictions on surface coating chemistries are forcing reformulation of corrosion protection systems for European installations.
- Aluminum:Marine-grade alloys gain share in coastal installations. Spanish and Portuguese port authorities specify aluminum bollards for salt-air environments where steel maintenance cycles prove uneconomical.
- Composite:Fiber-reinforced polymer systems for electromagnetic transparency and reduced weight. Remote mining operations in Australia specify these where helicopter transport limits deployment mass.
- Plastic:Polymer formulations for visual delineation and low-impact applications. Dutch cycling infrastructure programs deploy plastic bollards for lane separation where vehicle contact remains incidental.
Steel retains procurement dominance; aluminum climbs the fastest on corrosion-sensitive coastlines.
Installation Type:
Installation context determines foundation engineering, integration complexity, and operational duty cycles for system specification.
- Parking Facilities:High-cycle electromechanical barriers with license-plate recognition integration. French and Spanish urban markets unbundle equipment procurement from facility management contracts, pitting specialized operators against original manufacturers.
- Roadways:Heavy-duty crash-rated systems for arterial traffic management. German federal highway programs specify KBA-certified barriers for tunnel and bridge protection.
- Pedestrian Zones:Shallow-foundation retractable bollards with aesthetic cladding. Italian historic center revitalization programs demand bronze and stone finishes compatible with UNESCO heritage constraints.
- Public Spaces:Event-deployable and permanent hostile-vehicle-mitigation systems. UK counter-terrorism funding supports local authority procurement for Christmas markets and stadium approaches.
Parking facilities generate recurring service revenue; public spaces drive crash-rating specification upgrades.
Power Source:
Energy architecture selection responds to grid availability, maintenance access, and EU Green Deal efficiency mandates.
- Electric:Grid-connected brushless DC motor systems for urban parking and roadway applications. EU Machinery Directive safety-interlock mandates now require SIL-rated control documentation for all new installations.
- Solar:Photovoltaic-powered off-grid systems with battery storage. Remote energy infrastructure and mining operations in Western Australia specify these where grid connection exceeds project economics.
- Hydraulic:Underground fluid-power actuation for high-force rapid deployment. ECHA REACH restrictions on mineral oil formulations are forcing synthetic fluid adoption in Scandinavian cold-climate installations.
- Battery:Standalone electrochemical storage for temporary or backup operation. German critical infrastructure programs specify battery backup for grid-independent threat response capability.
Electric systems anchor urban volume; solar gains share fastest in remote resource extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany deploys rising bollards for critical infrastructure protection where shallow foundations enable rapid threat response. India prioritizes solar-powered systems for smart city pedestrianization schemes with unreliable grid access.
Germany
Federal critical infrastructure protection programs drive procurement of KBA-certified crash-rated barriers for tunnel and bridge protection. The EU Machinery Directive mandates SIL-rated safety-interlock documentation for all new electromechanical installations. Industrial concentration in Bavaria and North Rhine-Westphalia hosts precision-engineering clusters supplying drive mechanisms for high-cycle applications.
United States
Federal aviation security programs specify ASTM F2656-rated vehicle barriers at airport cargo facilities and terminal approaches. FAA procurement guidelines shape municipal and federal specifications for anti-terrorism perimeter hardening. California and Texas metropolitan areas concentrate deployment of integrated access-control systems for commercial parking structures.
India
Municipal corporations in Mumbai, Delhi, and Bangalore tender integrated parking barriers with license-plate recognition for smart city infrastructure. The Bureau of Indian Standards frames baseline safety requirements for electromechanical access control systems. Western port installations in Gujarat specify corrosion-resistant aluminum bollards for salt-air environments.
United Kingdom
Counter-terrorism funding supports local authority procurement of hostile-vehicle-mitigation systems for Christmas markets and stadium approaches. HSE guidelines intersect with EU Machinery Directive residual obligations for safety-interlock compliance. London and Southeast England concentrate demand for event-deployable bollard systems in heritage-sensitive public spaces.
Australia
Remote mining operations in Western Australia specify photovoltaic bollard systems where grid connection exceeds project economics. State-level work safety regulations govern hydraulic fluid specifications for underground actuation systems. Queensland coastal installations drive demand for marine-grade aluminum formulations in salt-air environments.
Automatic Barriers and Bollards Market Competitive Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with integrated access-control platforms. The vendor base stratifies across three tiers: European precision-drive manufacturers, diversified building-automation conglomerates, and regional installation-service providers. Two dominant competitive moves define current positioning: unbundling of hardware procurement from long-term maintenance contracts, and convergence of physical barriers with visitor-management software ecosystems.
Within the European specialist tier, FAAC Group and Magnetic Autocontrol GmbH exemplify contrasting archetypes—one leveraging installed-base scale for recurring service revenue, the other anchoring position through precision-engineered drive mechanisms. CAME Group occupies a position representing integrated platform competition, extending hardware utility into software ecosystems. These three entities collectively illustrate the market's structural tension between mechanical specialization and digital convergence.
| Leading Market Players |
|---|
| Automatic Systems |
| FAAC Group |
| ATG Access Ltd |
| Avon Barrier |
| Macs Automated Bollard Systems Ltd |
| CAME Group |
| Magnetic Autocontrol GmbH |
| Bollard Solutions |
| Houston Systems Private Limited |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors govern landed cost differentials for German precision-drive mechanisms, concentrating margin leverage with Bavarian engineering clusters while forcing price stratification between crash-certified and standard-grade barrier systems.
Pricing Analysis
Long-term offtake contracts dominate municipal parking authority procurement in France and Spain, where facility management operators unbundle hardware from service agreements. Price differentiation hinges on ISO IWA 14-1 certification tier and after-sales maintenance bundling. Cost compression in standard-grade electromechanical barriers intensifies as brushless DC motor commoditization collapses service revenue models. Corporate campus buyers exhibit lowest price sensitivity due to cyber-physical integration requirements, while Indian municipal corporations tender on pure equipment cost.
Supply Chain Analysis
Export-control restrictions on high-torque brushless motor controllers limit technology flows from Germany and Japan to non-allied jurisdictions. Manufacturing gravity centers on Germany, Italy, and China for electromechanical drive systems. Supply chains draw from hot-rolled steel coil, rare-earth permanent magnets, and SIL-rated control electronics. Single-source vulnerability concentrates in precision-machined gearbox housings from Bavarian suppliers. Distribution runs through specialized security integrators and OEM-direct channels for critical infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical access control is transitioning toward platform economics as visitor-management software ecosystems absorb barrier hardware into unified building-automation stacks, rewarding interoperability investments over standalone mechanical superiority.
For Market Incumbents: Entrench recurring revenue streams by captive control of aftermarket service networks before third-party facility management operators displace original manufacturer maintenance contracts. Prioritize backward integration into brushless DC motor production to defend margin position against commoditization pressure from Chinese drive suppliers. Accelerate SIL-rated control system certification to maintain port-of-entry compliance under EU Machinery Directive enforcement. For New Entrants and Emerging Players: Build out solar-powered off-grid bollard offerings for Western Australian mining operations and Indian smart city peripheries where grid economics favor photovoltaic architectures. Penetrate the retractable bollard segment for Italian historic center pedestrianization schemes requiring UNESCO-compatible aesthetic cladding. Pursue direct municipal tendering relationships bypassing established security integrator channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building-automation conglomerates seeking to divest non-core perimeter security divisions with stranded technology portfolios. Long-term viability favors precision-drive specialists with captive magnet supply and software-integration capabilities over pure-play hardware fabricators. Monitor FAA procurement guideline revisions as inflection signals for federal aviation security spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies bollard operation with CAME Group-style visitor management software ecosystems. |
| Certification Investment | Accelerates ISO IWA 14-1 crash-testing throughput to compress 8-14 month launch cycles. |
| Backward Integration | Captures brushless DC motor production to offset magnet cost volatility from Chinese suppliers. |
| Geographic Expansion | Targets Indian municipal tenders in Mumbai and Delhi for smart city parking integration. |
| Strategic Partnership | Links hardware procurement with long-term facility management contracts in French urban markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Machinery Directive enforcement records, ASTM F2656 crash-test databases, and municipal tender documentation from Mumbai, Delhi, and Bangalore. Interviews with critical infrastructure security directors, airport procurement officers, parking facility managers, and precision-drive manufacturing engineers informed demand-side validation. Trade flow data from German KBA certification registries and Indian BIS safety filings anchored supply-side triangulation. Bottom-up segment sizing cross-checked against top-down infrastructure spending forecasts.
Forecast inputs span product type segmentation across rising bollards, fixed barriers, and retractable systems; material grades from standard steel to marine aluminum; and power source architectures including electric, solar, hydraulic, and battery backup configurations. CAGRs were derived from regression analysis against critical infrastructure protection budget trajectories and aviation security program appropriations. The modeling period incorporates EU Green Deal retrofit incentive disbursement patterns and REACH hydraulic fluid reformulation compliance timelines.
Stress conditions across steel price volatility bands, third-party crash-testing queue durations, and solar component supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hostile-vehicle-mitigation guideline evolution and energy-efficiency mandate tightening. Cross-checking against FAA procurement bulletins and EU member state recovery fund allocation reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Shisha Tobacco Market
Others
Hardwood Market
Others
Hypermarket Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
South Asia Geosynthetics Market
Others
Coalescing Filter Market
Others
Badminton Apparel Market
Others
Hearables Market
Others
Exosome Technologies Market
Others
North America Forklift Truck Market
Others
Nyerereite Market
Others
North America Flexographic Printing Market
Others
Moveable Water Tap Market
Others
Global Digital Market
Others
5G Enabled Healthcare Services Market
Others
Edge Computing in Healthcare Market