
 UK Automotive LED Lighting Market | 2026-2036
UK Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive LED Lighting Market Insights
UK semiconductor packaging capacity for automotive-grade LEDs is decoupling from legacy European supply hubs as domestic foundries expand dedicated lines. HELLA GmbH & Co. KGaA (FORVIA) leverages its Redditch engineering center to sustain adaptive headlamp calibration services for British OEMs. Marelli Holdings Co., Ltd. anchors its European LED module assembly at its Crewe facility, while Valeo SE competes through its Manchester-based R&D lab specializing in matrix beam electronics.
UK automotive LED lighting encompasses solid-state illumination systems using gallium nitride emitters, aluminum-backed PCBs, and polycarbonate lenses engineered for vibration resistance and thermal management in vehicle applications. These assemblies deliver directional beams, signature daytime running patterns, and cabin ambiance control while drawing less current than halogen equivalents. Headlights dominate value capture given their complexity, though adaptive LED technology is expanding fastest as OEMs integrate camera-linked beam shaping. OEMs channel the majority of volume, while electric vehicle applications concentrate margin pools due to higher auxiliary lighting counts and premium positioning.
The UK's Vehicle Certification Agency enforces UN ECE Regulation 48 on light source installations, while the Department for Transport aligns domestic type approval with EU post-Brexit GB marking requirements. Euro NCAP protocols now weight adaptive driving beam performance in safety scoring, directly influencing OEM specification sheets. Stakeholders must track divergence between UK and EU automotive lighting standards as regulatory sovereignty reshapes homologation pathways.
Market Dynamics
British OEM specification sheets now weight adaptive driving beam performance heavily after Euro NCAP protocol changes, forcing rapid LED module redesign cycles across West Midlands engineering centers. This regulatory compression is restructuring supplier relationships and accelerating domestic packaging capacity investments.
Growth Catalysts
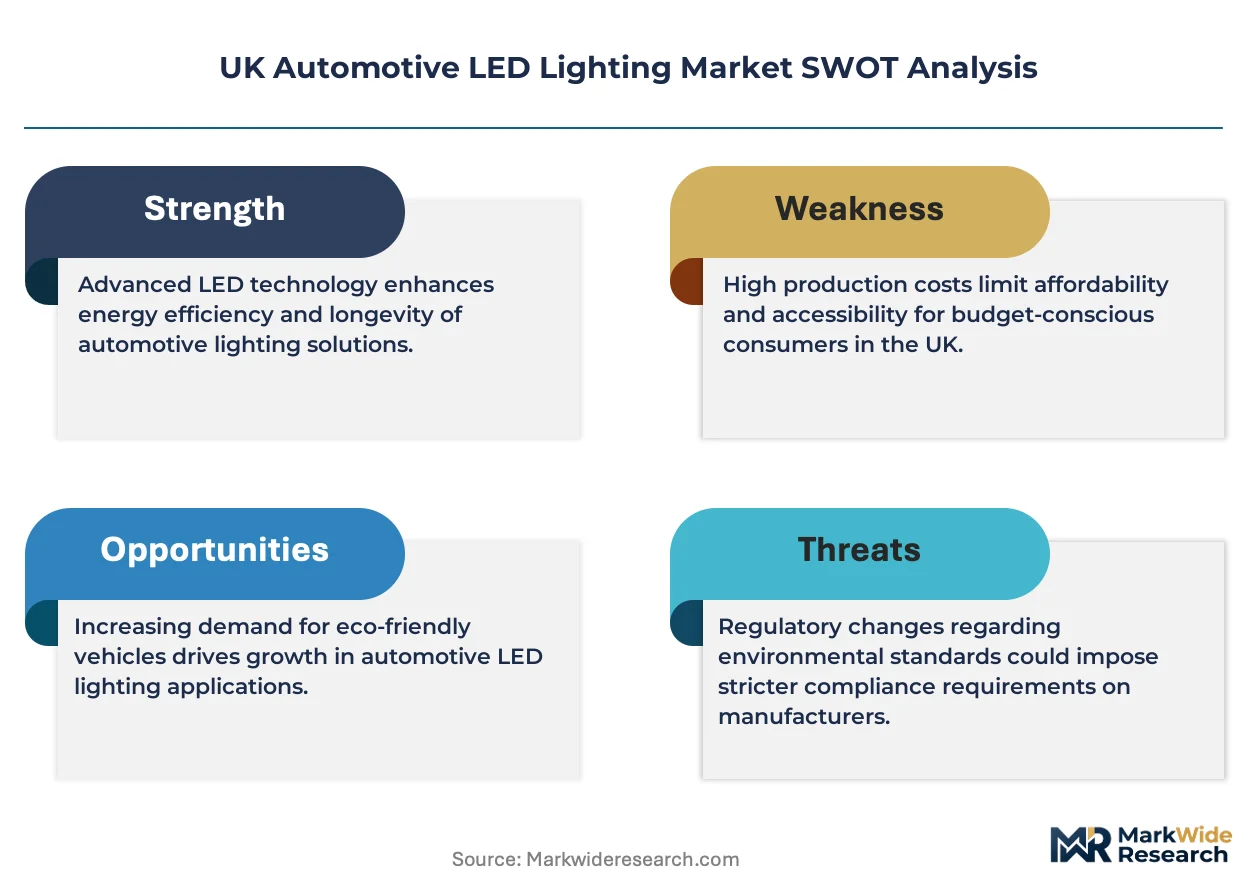
- Euro NCAP safety scoring:Weighted adaptive driving beam protocols now mandate camera-linked beam shaping in new vehicle platforms, pulling advanced LED assemblies into standard trim configurations.
- West Midlands automotive corridor:Concentrated OEM engineering activity around Birmingham and Coventry generates localized demand clusters for specialized calibration services.
- Gallium nitride emitters:These solid-state sources deliver superior thermal efficiency and directional control compared to legacy halogen architectures, reducing current draw in electric vehicle auxiliary circuits.
Market Restraints
- Semiconductor packaging concentration:Legacy European foundry dependence creates vulnerability in automotive-grade LED substrate supply, with limited domestic alternatives beyond emerging Redditch lines.
- Polycarbonate lens input volatility:Petrochemical feedstock fluctuations directly impact polycarbonate pricing for vibration-resistant lens housings, compressing module assembler margins.
- UN ECE Regulation 48 compliance friction:Post-Brexit divergence between UK type approval and EU homologation pathways forces dual certification investments for suppliers serving both markets.
Strategic Opportunities
- Scottish EV manufacturing:Underpenetrated assembly capacity in Scotland offers whitespace for LED module localization serving emerging electric vehicle platforms.
- Matrix beam electronics convergence:Integration of LiDAR sensor fusion with adaptive headlamp control creates premium positioning for R&D-intensive suppliers.
- GB marking regulatory tailwind:UK's sovereign type approval framework enables faster certification cycles for domestic innovators versus EU notification body queues.
Industry Challenges
- Adaptive calibration engineering talent:Scarce specialists in camera-linked beam pattern software create recruitment bottlenecks at West Midlands engineering centers.
- Legacy vehicle integration complexity:Retrofit LED compatibility with halogen-designed electrical architectures requires extensive harness modification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive LED Lighting Market |
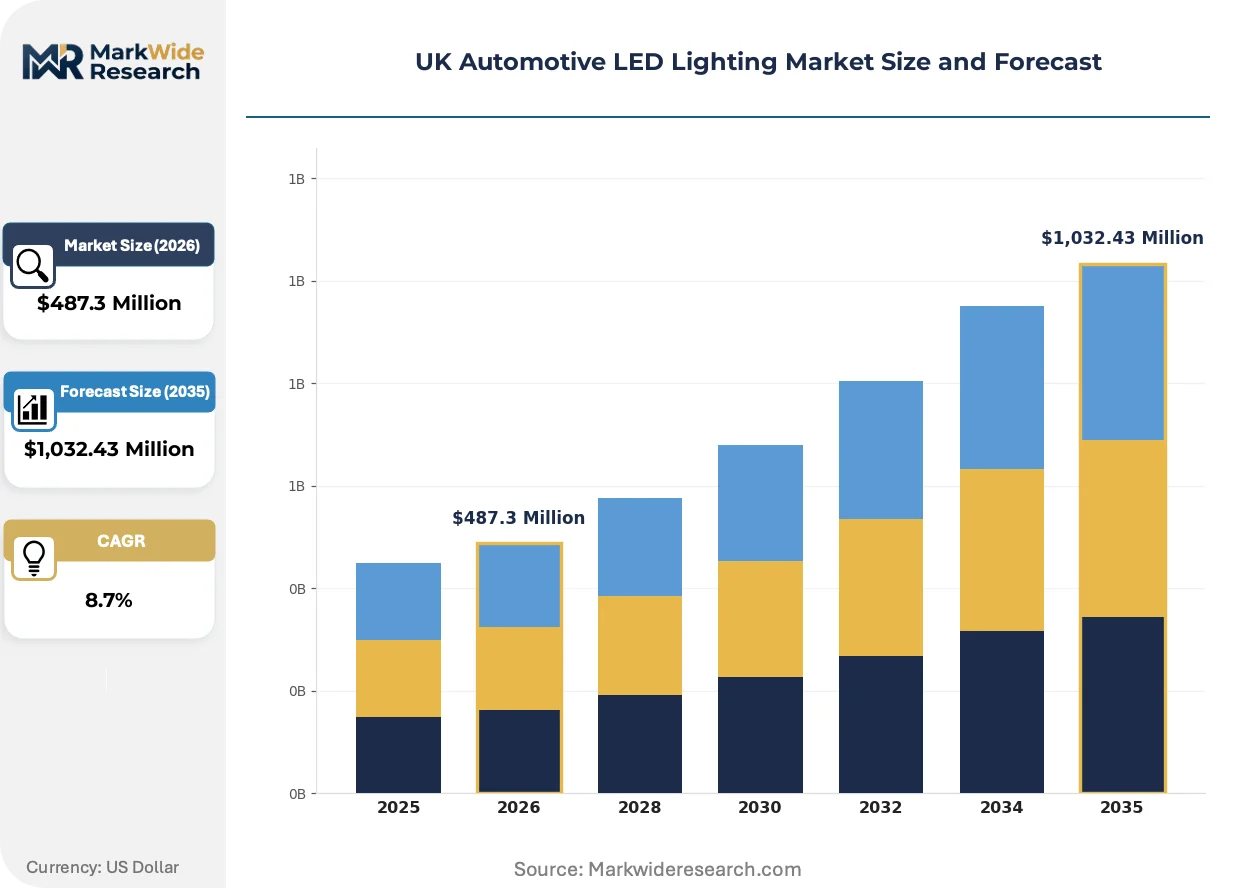
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Tail Lights, Fog Lights, Interior Lights End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Car Dealerships Technology: Standard LED, Smart LED, Adaptive LED, RGB LED Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | ams OSRAM AG, Hyundai Mobis, HELLA GmbH & Co. KGaA (FORVIA), GRUPO ANTOLIN IRAUSA, S.A., Stanley Electric Co., Ltd., Marelli Holdings Co., Ltd., Valeo SE, Lumileds Holding B.V., KOITO MANUFACTURING CO., LTD., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive LED Lighting Market Trends and Innovations
Digital light processing is actively restructuring how British OEMs specify headlamp architectures, shifting from static beam modules to software-defined illumination systems. This transformation compresses hardware differentiation while expanding firmware and calibration service value capture.
Matrix LED arrays with individually addressable pixels are overtaking conventional multi-chip designs in premium vehicle segments. JLR and Bentley specification teams now require pixel-level beam blanking to avoid dazzling oncoming traffic without mechanical shutter mechanisms. This capability is compressing supplier differentiation around semiconductor packaging precision rather than optical mechanical engineering.
The UK's Vehicle Certification Agency has tightened alignment between domestic GB marking requirements and evolving UN ECE beam pattern standards. This regulatory synchronization forces module suppliers to maintain dual technical file documentation for UK and EU market access. Aftermarket retrofit providers face the steepest compliance burden, with many redirecting volume toward OEM captive channels.
Fleet procurement managers at British leasing companies now specify adaptive LED performance as a residual value protection mechanism. This specification behavior is displacing traditional trim-level lighting hierarchies with safety-scoring-driven standardization. Electric vehicle fleet operators in England's commercial corridors show the most pronounced preference compression, bundling advanced lighting into base configurations to maximize Euro NCAP ratings.
UK Automotive LED Lighting Market Segmentation
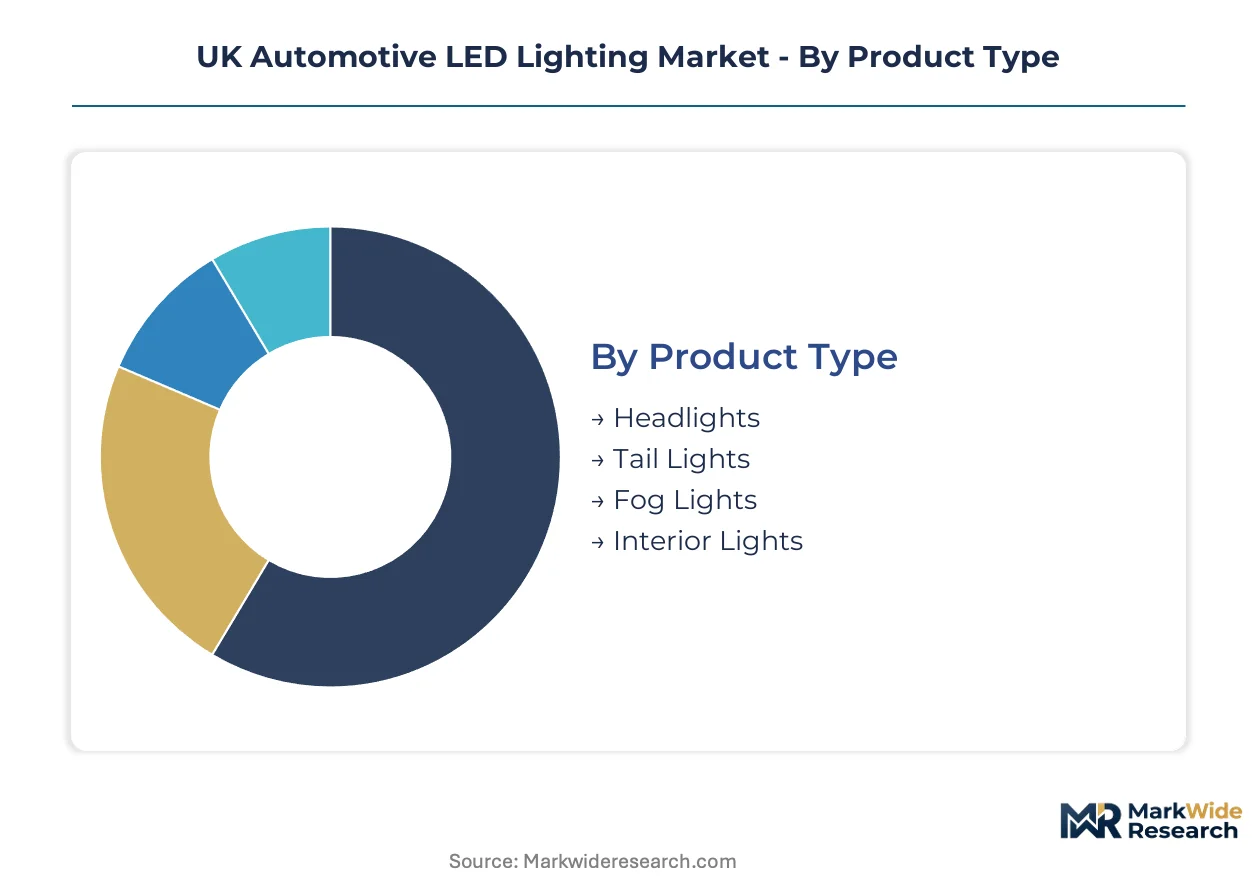
LED module suppliers in Britain must calibrate technical specifications, certification pathways, and service models to four distinct buyer archetypes. Each segmentation dimension reveals divergent margin structures and procurement rhythms across the West Midlands automotive corridor.
Product Type:
Cost tiers separate buyers seeking regulatory compliance from those pursuing premium positioning through advanced beam control.
- Headlights:Complex assemblies integrating gallium nitride emitters, aluminum-backed PCBs, and polycarbonate lenses for vibration resistance. Engineering centers in Birmingham and Coventry concentrate specification authority for adaptive beam modules as Euro NCAP protocols tighten.
- Tail Lights:Sequential signaling and signature daytime running patterns dominate design briefs. West Midlands OEMs source these modules through captive supplier relationships with shorter redesign cycles than headlamp programs.
- Fog Lights:Auxiliary beam modules for low-visibility conditions. Demand clusters around commercial vehicle configurations in England's logistics corridors.
- Interior Lights:Cabin ambiance systems with dimmable zones and color temperature control. Electric vehicle platforms specify higher auxiliary lighting counts, expanding module counts per vehicle.
Volume sits with Headlights; growth tilts toward Interior Lights.
End User:
Volume concentration and margin capture diverge sharply between captive supply relationships and independent distribution channels.
- OEMs:British vehicle manufacturers including JLR and Bentley specify pixel-level beam blanking and camera-linked calibration. These buyers command dedicated engineering resources and multi-year program commitments from Redditch and Crewe assembly facilities.
- Aftermarket Providers:Retrofit LED compatibility with halogen-designed electrical architectures requires extensive harness modification protocols. UN ECE Regulation 48 compliance friction limits viable participants serving both UK and EU markets.
- Vehicle Assemblers:Contract manufacturers building for multiple brands. Procurement emphasizes module standardization across platform variants to compress inventory carrying costs.
- Car Dealerships:Service bay upsell opportunities for premium trim lighting packages. Margins concentrate in software activation fees rather than hardware replacement.
Revenue concentrates with OEMs; aftermarket channels face steepest regulatory headwinds.
Technology:
Maturity curves and intellectual property intensity separate commodity emitters from firmware-dependent systems.
- Standard LED:Established gallium nitride architectures with fixed beam patterns. Price compression is accelerating as packaging capacity expands across European foundries.
- Smart LED:Networked illumination systems with vehicle-to-infrastructure communication protocols. Manchester-based R&D labs specialize in matrix beam electronics for this tier.
- Adaptive LED:Camera-linked beam shaping with pixel-level control. Euro NCAP safety scoring now mandates this capability in new vehicle platforms, pulling advanced assemblies into standard trim configurations.
- RGB LED:Multi-channel emitters enabling dynamic color temperature adjustment. Interior applications concentrate demand as electric vehicle platforms emphasize cabin differentiation.
Standard LED carries volume; Adaptive LED is climbing the fastest.
Application:
Electrification intensity and safety regulation exposure determine specification sophistication across vehicle categories.
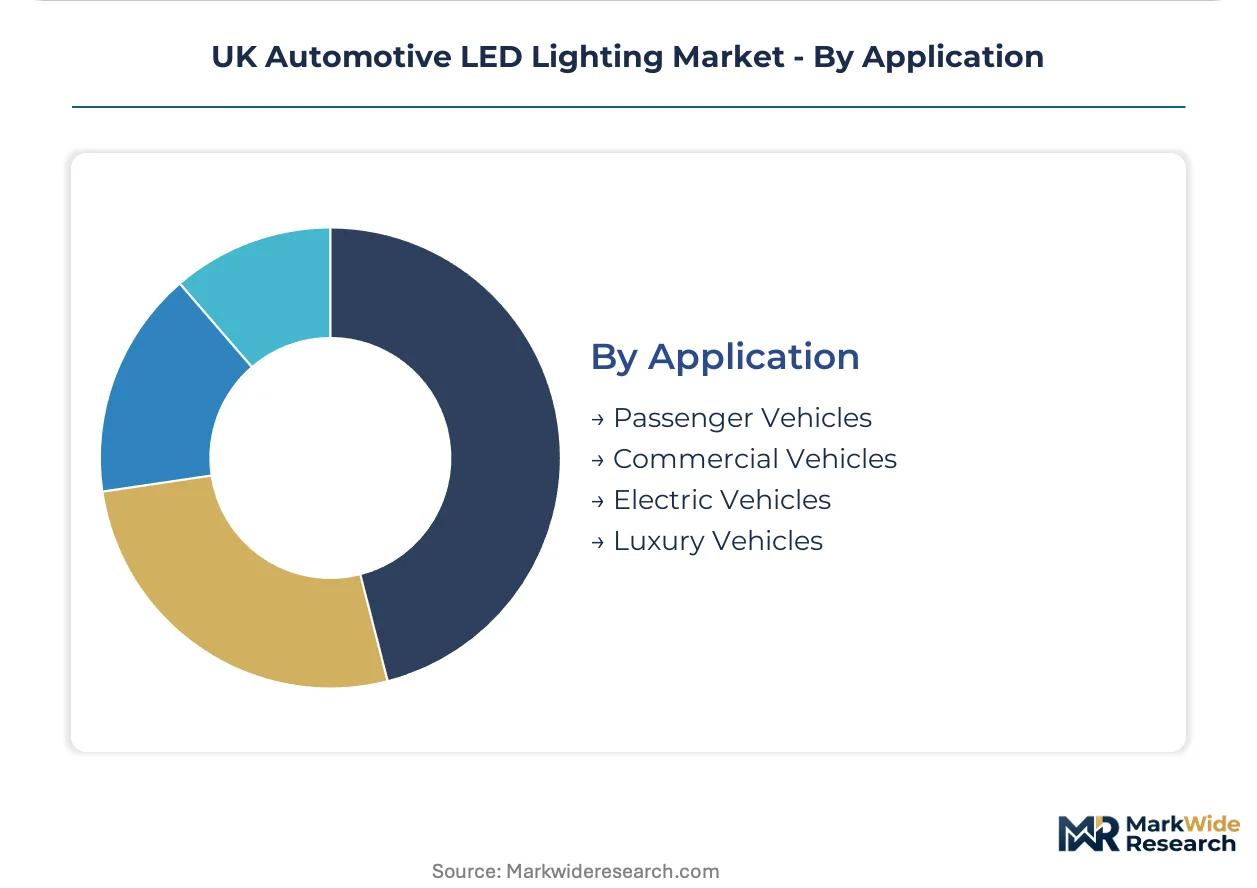
- Passenger Vehicles:Mass-market platforms with trim-level lighting hierarchies. Fleet procurement managers now specify adaptive LED performance as residual value protection.
- Commercial Vehicles:Durability-focused specifications emphasizing vibration resistance and thermal management. Logistics operators in England's commercial corridors prioritize reliability over beam sophistication.
- Electric Vehicles:Higher auxiliary lighting counts and premium positioning compress margin pools. Scottish EV manufacturing offers whitespace for LED module localization serving emerging platforms.
- Luxury Vehicles:Bentley and Rolls-Royce specification teams require matrix arrays with individually addressable pixels. Firmware and calibration service value capture exceeds hardware differentiation.
Passenger Vehicles anchor volume; Electric Vehicles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate supply from England's West Midlands foundry network anchors UK automotive LED manufacturing capacity. Domestic packaging lines at Redditch and Crewe facilities are decoupling from legacy European semiconductor hubs. Scotland's emerging EV assembly corridor presents whitespace for module localization.
England
OEM engineering centers in Birmingham and Coventry concentrate specification authority for adaptive beam modules. The Vehicle Certification Agency enforces UN ECE Regulation 48 on light source installations with GB marking requirements. Manchester-based R&D labs specialize in matrix beam electronics for camera-linked calibration services.
Scotland
Underpenetrated electric vehicle assembly capacity generates demand for localized LED module supply. Scottish government industrial strategy targets automotive component manufacturing investment. Glasgow-Edinburgh corridor development zones attract tier-one suppliers seeking proximity to emerging EV platforms.
Wales
Commercial vehicle configurations for England's logistics corridors drive auxiliary lighting demand. Welsh manufacturing zones emphasize durability-focused specifications with vibration resistance requirements. Cardiff-Newport industrial parks host module assemblers serving fleet procurement managers.
Northern Ireland
Post-Brexit regulatory alignment friction creates dual certification complexity for cross-border suppliers. Belfast engineering facilities support adaptive calibration software development. Derry-Londonderry manufacturing zones specialize in interior lighting systems for electric vehicle cabin differentiation.
Northwest England
Fleet leasing company procurement managers in Manchester specify adaptive LED performance for residual value protection. The Department for Transport coordinates domestic type approval with evolving beam pattern standards. Liverpool logistics hubs concentrate commercial vehicle retrofit demand for fog light modules.
UK Automotive LED Lighting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue firmware-defined illumination and calibration service expansion. The supplier base stratifies across semiconductor packaging specialists, module assemblers, and adaptive calibration engineering houses. Three archetypes dominate: integrated lighting system providers, component-focused emitters manufacturers, and software-centric beam control developers. Capacity expansion and strategic technology licensing represent the primary competitive vectors as Euro NCAP protocols compress redesign cycles.
Within the integrated lighting tier, HELLA GmbH & Co. KGaA (FORVIA) and Marelli Holdings Co., Ltd. exemplify module assembly concentration at British facilities. Valeo SE occupies a position among calibration-intensive developers with Manchester-based R&D investment. These three entities represent divergent strategic postures: German-originated captive supply relationships, Japanese-structured holding company manufacturing scale, and French-headquartered electronics convergence specialization.
| Leading Market Players |
|---|
| ams OSRAM AG |
| Hyundai Mobis |
| HELLA GmbH & Co. KGaA (FORVIA) |
| GRUPO ANTOLIN IRAUSA, S.A. |
| Stanley Electric Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Valeo SE |
| Lumileds Holding B.V. |
| KOITO MANUFACTURING CO., LTD. |
| Others |
Pricing and Supply Chain Analysis
Euro NCAP's weighted adaptive driving beam protocols gate both qualified supply and premium-tier pricing access, as only calibration-capable engineering houses capture standard-trim specification authority while commodity emitters face price compression. OEM procurement teams now bundle multi-year calibration service contracts with hardware modules, compressing pure component margins while expanding firmware-dependent revenue pools.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from unbundled commodity competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and adaptive beam complexity, with OEM captive channels commanding premium positioning. Price erosion runs through standard LED emitters as gallium nitride packaging capacity expands across European foundries. Fleet procurement managers show highest price sensitivity, while luxury vehicle specification teams prioritize pixel-level performance over unit cost.
Supply Chain Analysis
Gallium nitride substrate supply rests on Taiwanese and South Korean specialty semiconductor producers, with emerging domestic lines at Redditch and Crewe attempting partial decoupling. Polycarbonate lens feedstocks and aluminum-backed PCB materials complete the critical input matrix. Single-source vulnerability concentrates in automotive-grade LED packaging, where legacy European foundry dependence persists. Distribution runs through Tier 1 module assemblers serving West Midlands OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with upstream semiconductor packaging capacity and downstream calibration service networks representing the contested levers. Players pursuing captive gallium nitride foundry investments or adaptive beam software assets will capture specification authority.
For Market Incumbents: Acquire calibration engineering talent pools in the West Midlands corridor to defend against emerging software-centric beam control developers. Secure long-term gallium nitride substrate offtake agreements before domestic packaging lines reach scale. Reinforce relationships with JLR and Bentley specification teams through dedicated program engineering resources. For New Entrants and Emerging Players: Enter via Scotland's underpenetrated EV manufacturing corridor, where localized LED module supply lacks established Tier 1 presence. Target interior lighting applications for electric vehicle platforms, where higher auxiliary lighting counts expand addressable module counts per vehicle. Pursue direct partnerships with Glasgow-Edinburgh development zone operators to bypass entrenched West Midlands supply relationships. For Investors and Strategic Acquirers: Euro NCAP protocol changes mandating camera-linked beam shaping are the leading indicator that firmware-defined illumination systems will dominate value capture. Firms with Manchester-based matrix beam electronics R&D and established OEM calibration service contracts represent priority acquisition profiles. Watch for Scottish government industrial strategy funding announcements as inflection signals for EV component manufacturing localization.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Packaging Capacity Expansion | Domestic gallium nitride foundry lines at Redditch reduce European substrate dependence. |
| Adaptive Calibration Service Network Buildout | Camera-linked beam pattern software expertise concentrates in Birmingham and Coventry engineering centers. |
| Scottish EV Manufacturing Footprint Establishment | Glasgow-Edinburgh corridor development zones attract tier-one suppliers seeking platform proximity. |
| Matrix Beam Electronics R&D Investment | Manchester-based labs specialize in pixel-level control systems for premium OEM specifications. |
| GB Marking Regulatory Pathway Optimization | UK sovereign type approval enables faster certification cycles versus EU notification body queues. |
Research Methodology
Multi-period observation of Euro NCAP safety scoring protocol evolution and OEM specification sheet changes anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and Vehicle Certification Agency technical officers. Secondary validation drew from UN ECE Regulation 48 documentation, Department for Transport type approval records, and vehicle production databases. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework, with electric vehicle content per vehicle treated as a distinct modeling variable. CAGRs derived from fitted growth curves across the projection horizon, incorporating gallium nitride emitter cost trajectories and adaptive LED penetration assumptions by vehicle class. Regional production cluster data from England's West Midlands automotive corridor informed geographic allocation models.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polycarbonate feedstock volatility and post-Brexit regulatory divergence scenarios. Forecasts reflect documented assumptions regarding Euro NCAP protocol stability and domestic semiconductor packaging capacity expansion timelines. A small set of named triggers—Scottish EV platform announcements, UN ECE beam pattern standard revisions, and gallium nitride foundry commissioning dates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Semiconductor Gas Filters Market
Others
Global Multi-Access Edge Computing Market
Others
Europe Travel Retail Market
Others
Metal Ore Mining Market
Others
Industrial Air Purifiers Market
Others
North America Printed Signage Market
Others
Nyerereite Market
Others
PCB Laminate Market
Others
Europe Postal Services Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Global Drug Discovery Informatics Market
Others
AC Switchgear Market
Others
Germany 3D Printing Construction Market
Others
PC As a Service Market
Others
Europe Medical Simulation Market
Others
Reef Aquarium Market