
 Automated Testing Software Market | 2026-2036
Automated Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Testing Software Market Analysis
The capital-intensity divergence between cloud-native platform builders and legacy tool maintainers is bifurcating competitive dynamics across the sector. Tricentis leverages its enterprise-scale continuous testing platform to anchor long-term contracts with regulated industries. BrowserStack competes through extensive device-cloud infrastructure that sustains cross-browser validation at scale.
Automated testing software comprises code-driven frameworks that execute test scripts against applications without manual intervention, typically integrating assertion engines, orchestration layers, and reporting dashboards to validate functional correctness, performance thresholds, and security postures. Functional Testing occupies the largest revenue pool as enterprises maintain regression suites for legacy systems, while Security Testing captures accelerating interest from organizations addressing supply-chain code vulnerabilities. Cloud-Based deployment is displacing on-premise installations as CI/CD-native teams prioritize elastic execution environments over fixed infrastructure.
The EU AI Act and GDPR impose algorithmic accountability requirements that expand automated validation scope for European enterprises. The US FDA and NIST cybersecurity framework shape product standards for healthcare and federal software procurement respectively. ISO/IEC 25010 quality standards further codify test coverage expectations across regulated sectors. Stakeholders must decide whether to build proprietary validation stacks or embed third-party platforms before compliance deadlines harden procurement requirements.
Market Dynamics
Continuous compliance mandates from the EU AI Act and US FDA are compressing release cycles, forcing enterprises to embed validation directly into CI/CD pipelines rather than treating testing as a terminal gate.
Growth Catalysts
- EU AI Act algorithmic accountability:Enterprises serving European markets must automate bias detection and explainability verification, expanding validation scope beyond functional correctness into ethical AI governance.
- Healthcare software procurement:FDA cybersecurity guidance for medical devices mandates automated vulnerability scanning throughout the development lifecycle, pulling testing budgets forward.
- Shift-left security integration:Supply-chain code attacks disclosed through CISA advisories are accelerating SAST and DAST tool deployment within financial services CI/CD workflows.
Market Restraints
- Specialized talent scarcity:Shortages of engineers proficient in both test automation frameworks and domain-specific compliance requirements inflate implementation timelines and consulting dependency.
- Cloud infrastructure concentration:Execution environments cluster within hyperscaler data centers in Virginia, Frankfurt, and Singapore, creating latency and data sovereignty constraints for regulated workloads.
- Legacy system entrenchment:Mainframe and COBOL-dependent enterprises in banking and government lack API-native architectures, limiting automated test coverage to greenfield modules.
Strategic Opportunities
- India software testing services:Domestic IT services firms are building captive automation platforms to serve North American and European clients, capturing value from remote validation delivery.
- Edge computing validation:IoT firmware testing for industrial sensors and autonomous vehicle components requires new orchestration layers that execute tests against distributed hardware profiles.
- ISO/IEC 25010 certification demand:Quality standard compliance is becoming a procurement filter in healthcare and automotive supply chains, creating premium positioning for certified platform vendors.
Industry Challenges
- Test data management complexity:GDPR and HIPAA constraints on production data usage force synthetic data generation investments that slow pipeline velocity and raise infrastructure costs.
- Fragmented toolchain integration:Enterprises operate hybrid environments spanning Selenium, Cypress, Playwright, and proprietary platforms, multiplying maintenance overhead and skill requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Testing Software Market |
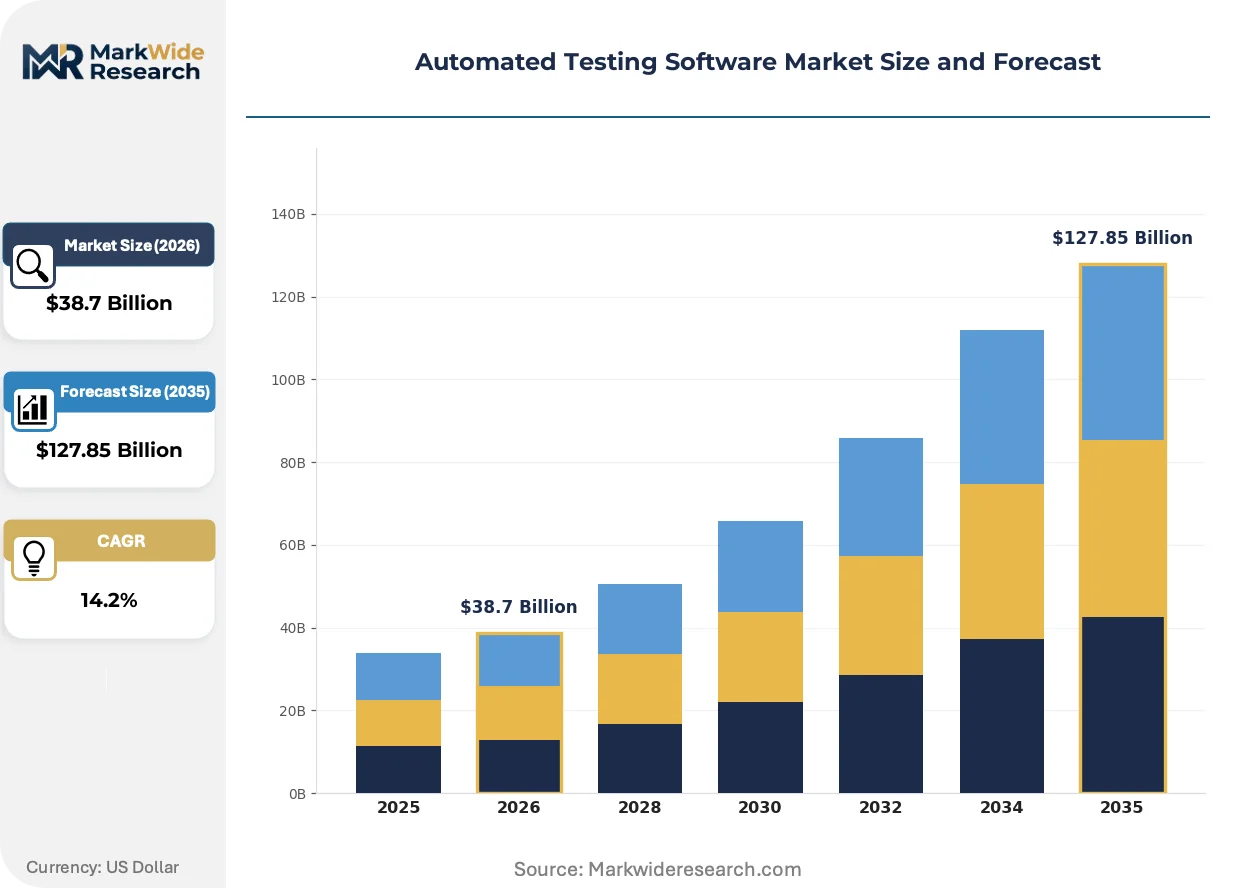
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Testing, Performance Testing, Security Testing, Load Testing Deployment: On-Premise, Cloud-Based, Hybrid, Open Source End User: IT Services, E-Commerce, Banking, Telecommunications Integration Level: CI/CD Pipelines, API Integration, Frameworks, Standalone |
| Companies Covered | Sauce Labs, Applitools, Tricentis, TestComplete, Katalon, SmartBear Software, BrowserStack, Leapwork, Micro Focus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Testing Software Market Emerging Trajectories
Agentic AI systems are rewriting how test cases are generated, executed, and maintained, collapsing the traditional boundary between manual test design and automated execution.
Self-healing test scripts powered by machine learning are displacing brittle locator-based automation that breaks with every UI change. E-commerce and SaaS teams in California and New York are deploying these capabilities to sustain daily release velocities without proportional tester headcount expansion. The structural consequence is compression of regression suite maintenance from dedicated engineering hours to algorithmic self-correction.
The EU AI Act's risk-based classification system is mandating continuous validation documentation for high-risk AI applications. European enterprises must maintain immutable audit trails of every test execution, model version, and deployment decision. Healthcare and financial services firms are responding by embedding compliance dashboards directly into testing platforms rather than extracting reports post-hoc.
Consumption-based pricing for test execution minutes is replacing perpetual license models among CI/CD-native teams. Platform vendors are unbundling storage, compute, and concurrency limits into metered services that align costs with actual pipeline activity. This shift is most visible among Series B and C software startups in Israel and Germany that prioritize cash-flow predictability over capital efficiency.
Automated Testing Software Market Segmentation
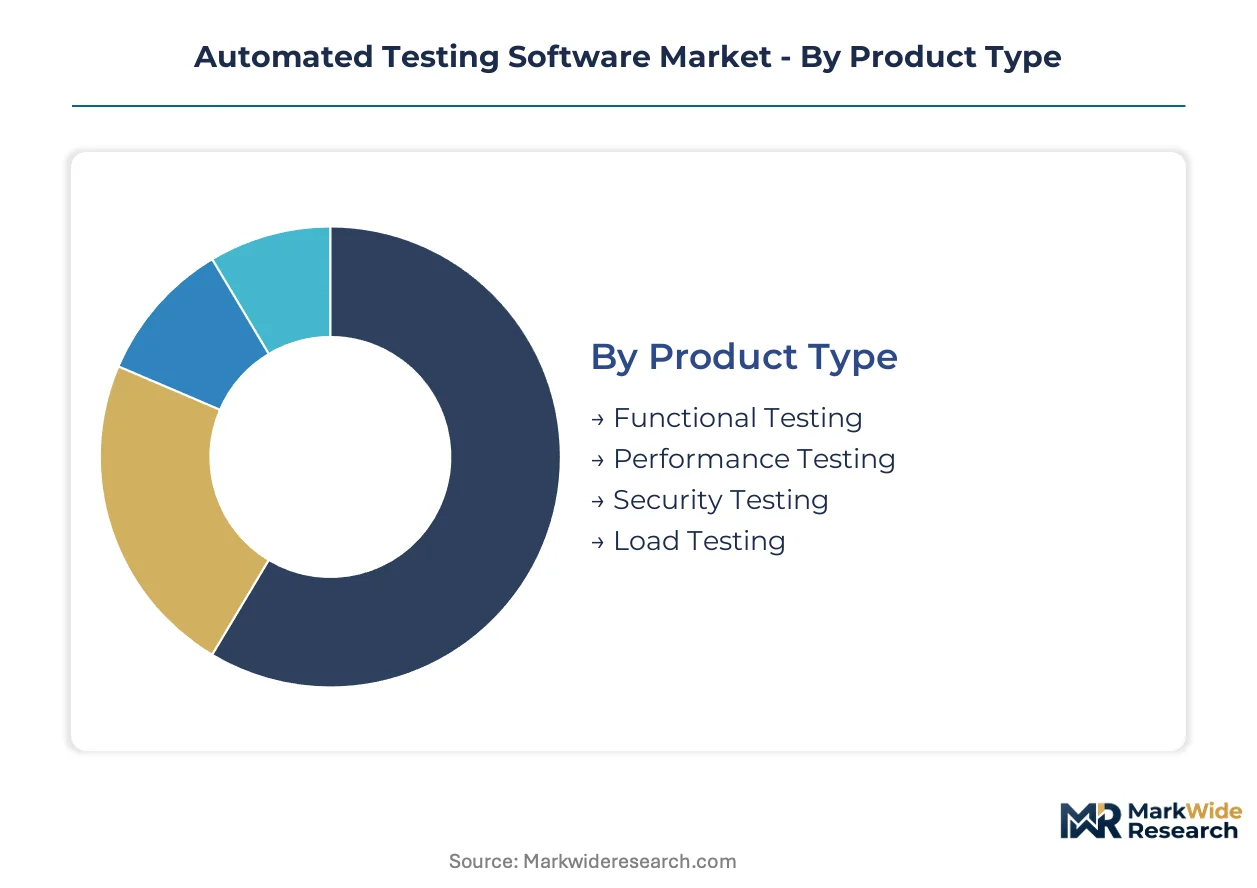
Automated testing software segments diverge sharply in their exposure to substitution by agentic AI and self-healing frameworks. Procurement patterns increasingly favor deployment modes and integration architectures that minimize manual test maintenance overhead.
Product Type:
Functional Testing faces the most acute substitution pressure from generative AI systems that autonomously generate and repair test scripts, while specialized testing categories retain defensive moats through compliance complexity.
- Functional Testing:Regression suites validate UI workflows, business logic, and data integrity across application releases. Banking IT departments in New York and California maintain extensive functional test libraries for legacy core systems, though self-healing automation is compressing maintenance labor.
- Security Testing:SAST, DAST, and dependency scanning tools probe codebases for vulnerabilities and supply-chain risks. Financial services firms subject to CISA advisories and SEC cybersecurity rules are embedding security validation directly into CI/CD gates, pulling budget from terminal-stage penetration testing.
- Performance Testing:Load, stress, and scalability validation ensures applications meet latency and throughput thresholds under production traffic patterns.
- Load Testing:Simulated concurrent user sessions identify bottlenecks in database queries, caching layers, and microservice orchestration.
Functional Testing retains volume leadership; Security Testing holds the steepest expansion curve.
Deployment:
Cost tier stratification separates enterprises paying premium rates for managed elasticity from organizations constraining spend through self-hosted or community alternatives.
- Cloud-Based:Metered execution environments scale compute and concurrency on demand, eliminating capital expenditure for test infrastructure. Israeli and German software startups favor consumption-based pricing that aligns costs with actual pipeline activity rather than perpetual licenses.
- On-Premise:Fixed hardware installations persist in defense, intelligence, and classified healthcare environments where data sovereignty requirements block external execution. FDA-regulated medical device manufacturers in Minnesota and Massachusetts maintain on-premise validation stacks for 21 CFR Part 11 compliance.
- Hybrid:Sensitive test data remains on-premise while compute-intensive execution bursts to cloud infrastructure.
- Open Source:Community-maintained frameworks eliminate licensing fees but require internal engineering investment for customization and support.
Cloud-Based deployment captures the majority of new contract value; Open Source maintains entrenched positions among cost-constrained development teams.
End User:
Application context determines whether testing investments prioritize release velocity, regulatory documentation, or operational resilience against failure costs.
- Banking:Core system modernization and open banking API validation drive substantial automation budgets. EU AI Act compliance requirements are forcing European banks to automate bias detection and explainability verification for algorithmic credit decisions.
- IT Services:Outsourced development shops build captive automation platforms to deliver validation as a bundled service. Indian IT services firms are constructing proprietary testing stacks to serve North American and European clients through remote delivery models.
- E-Commerce:Daily release cycles demand self-healing test scripts that sustain velocity without proportional tester headcount expansion.
- Telecommunications:Network function virtualization and 5G service orchestration require specialized test harnesses for distributed edge infrastructure.
Banking contributes the largest absolute spending; IT Services is climbing the fastest as vendors productize validation delivery.
Integration Level:
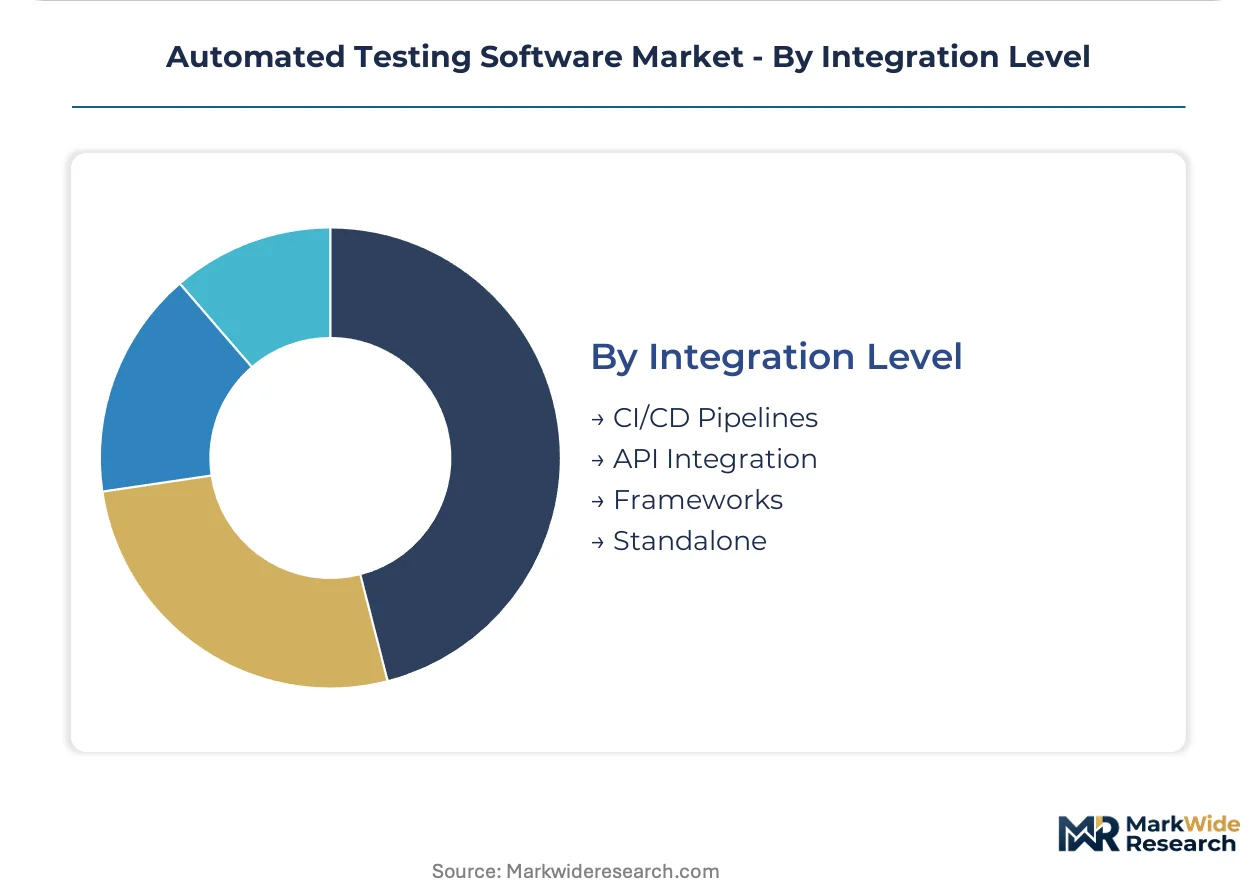
Architecture maturity separates teams embedding validation throughout development from those treating testing as a terminal quality gate.
- CI/CD Pipelines:Automated test execution triggers on every code commit, blocking merges that fail validation criteria. California and New York SaaS companies deploy pipeline-native testing to sustain multiple daily releases without regression escapes.
- API Integration:Headless test execution through REST and GraphQL endpoints enables validation of backend services independent of UI state. Microservices architectures in cloud-native enterprises depend on API-level testing to isolate service boundaries.
- Frameworks:Selenium, Cypress, and Playwright provide programmable foundations for custom test automation stacks.
- Standalone:Desktop applications execute tests through manual invocation without pipeline orchestration.
CI/CD Pipelines dominate new procurement decisions; Standalone installations persist only in legacy maintenance contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, absorbing premium rates for compliance-certified platforms, while Indian IT services firms and Southeast Asian startups operate under severe cost constraints that favor open-source frameworks and consumption-based pricing.
United States
Cloud-native enterprises in California and New York sustain the highest absolute spending on CI/CD-integrated testing platforms. FDA cybersecurity guidance for medical devices pulls validation budgets forward in Minnesota and Massachusetts. The FDA's 21 CFR Part 11 requirements anchor on-premise installations among medical device manufacturers in the Twin Cities corridor.
Germany
Automotive and industrial software suppliers in Bavaria and Baden-Württemberg automate validation for ISO/IEC 25010 compliance. The EU AI Act's risk-based classification system forces Munich-based enterprises to maintain immutable audit trails of every test execution. Stuttgart's automotive engineering clusters embed compliance dashboards directly into testing platforms.
India
Domestic IT services firms in Bengaluru and Hyderabad build captive automation platforms to serve North American and European clients through remote delivery models. The country's national software quality standards push enterprises toward continuous validation frameworks. Telangana's technology corridor concentrates vendor development centers for cross-browser and API testing tools.
United Kingdom
Financial services firms in London expand automated testing adoption to meet FCA operational resilience requirements and SEC cybersecurity rules affecting dual-listed entities. GDPR constraints on production data usage force synthetic data generation investments that raise infrastructure costs. The City's regulatory technology clusters integrate bias detection into algorithmic trading system validation.
Israel
Series B and C software startups in Tel Aviv prioritize consumption-based pricing for test execution minutes over perpetual licenses to preserve cash-flow predictability. The country's national cybersecurity authority advisories accelerate SAST and DAST deployment within CI/CD workflows. Herzliya's venture-backed SaaS companies deploy self-healing test scripts to sustain daily release velocities.
Automated Testing Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the automated testing software sector. Enterprise-scale continuous testing platforms anchor long-term contracts with regulated industries, while device-cloud infrastructure specialists compete through extensive cross-browser validation capabilities. The market structure separates consolidated platform vendors from fragmented point-solution providers. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and portfolio diversification into adjacent security testing categories.
Within the enterprise platform tier, Tricentis and BrowserStack exemplify divergent competitive positioning. Tricentis occupies a position among regulated-industry anchors through its continuous testing platform. BrowserStack sits within the infrastructure-intensive archetype, sustaining validation scale through device-cloud execution environments. Sauce Labs represents the CI/CD-native vector among California-based testing platform providers.
| Leading Market Players |
|---|
| Sauce Labs |
| Applitools |
| Tricentis |
| TestComplete |
| Katalon |
| SmartBear Software |
| BrowserStack |
| Leapwork |
| Micro Focus |
| Others |
Supply Flow & Price Mechanics
Consumption-based capacity reservation contracts lock in execution minute commitments for CI/CD-native teams while guaranteeing cloud infrastructure access at predictable unit economics. These arrangements tie pricing visibility directly to hyperscaler data center locations in Virginia, Frankfurt, and Singapore where execution environments concentrate.
Pricing Analysis
After-sales revenue from professional services and extended support contracts drives lifetime value for enterprise platform vendors. Subscription tiers stratify across premium compliance-certified platforms, standard cloud-based execution environments, and economy open-source alternatives. Cost compression in the economy tier intensifies as Indian IT services firms productize remote validation delivery. Early-stage software startups in Israel and Germany exhibit the highest price elasticity, while regulated healthcare and financial services buyers in Germany and Switzerland absorb premium rates without volume attrition.
Supply Chain Analysis
The United States and India anchor software development and testing services delivery respectively. Cloud compute infrastructure draws from hyperscaler facilities concentrated in Northern Virginia, Frankfurt, and Singapore. Synthetic data generation tooling and device-cloud hardware profiles rest on specialized component suppliers. Single-source vulnerability in hyperscaler concentration creates latency and data sovereignty exposure for regulated European and Asian workloads. Distribution runs through direct enterprise sales teams and channel partnerships with systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers proficient in both test automation frameworks and domain-specific compliance requirements remain scarce, compressing implementation timelines and inflating consulting dependency for enterprises attempting CI/CD-native transformation.
For Market Incumbents: Consolidate market position through backward integration into synthetic data generation capabilities and certification investment for ISO/IEC 25010 compliance. Self-healing test scripts powered by agentic AI threaten traditional functional testing margins, making compliance-certified platform positioning the priority defensive lever against commoditization. For New Entrants and Emerging Players: Anchor in edge computing validation for IoT firmware and autonomous vehicle components where orchestration layers for distributed hardware profiles remain underdeveloped. European automotive suppliers in Stuttgart and Munich present the most penetrable buyer segment given EU AI Act documentation requirements. Lead with consumption-based pricing to align with Series B and C startup procurement preferences. For Investors and Strategic Acquirers: Capital is best deployed toward CI/CD-native platform specialists with embedded compliance dashboard capabilities and proven hyperscaler partnership structures. Long-term viability hinges on defensible data moats from immutable audit trail architectures rather than execution infrastructure alone. Watch for FDA cybersecurity guidance expansion into medical device software as the inflection signal pulling validation budgets forward.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding compliance dashboards directly into testing platforms satisfies EU AI Act immutable audit trail requirements for Munich-based enterprises. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, and GCP anchor elastic execution environments for California SaaS companies sustaining daily release velocities. |
| Acquisition of Specialist Firm | Buying synthetic data generation capabilities addresses GDPR and HIPAA constraints that slow pipeline velocity for healthcare validation workflows. |
| Geographic Expansion | Captive automation platforms in Bengaluru and Hyderabad capture value from remote validation delivery to North American banking clients. |
| Product Launch | Self-healing test script offerings target e-commerce teams in New York seeking to sustain release velocity without proportional tester headcount expansion. |
Methodological Framework
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and compliance leads and secondary sources including SEC filings, hyperscaler capex disclosures, and CI/CD tooling adoption surveys anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing from regulatory filing analysis and enterprise software spending patterns.
Sensitivity analysis across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions shapes the analytical framework. CAGRs derive from regression analysis of historical adoption curves and forward projection of compliance mandate timelines. Test execution minute volumes and certification penetration rates serve as industry-specific forecast inputs throughout the modeling period.
Material uncertainties — regulatory deadline delays, hyperscaler concentration disruptions, and agentic AI substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance enforcement consistency and cloud migration velocity. Recalibration cycles align with material shifts in EU AI Act implementation guidance and FDA cybersecurity rule expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cricket Analysis Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Global ERP Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Output Management Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Office Productivity Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
North America Automotive Software Market
Software & Services
Stock Media Software Market
Software & Services
Global Janitorial Software Market
Software & Services
HR Tech Market
Software & Services
Client Virtualization Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market