
 Synthetic Natural Gas (SNG) Market | 2026-2036
Synthetic Natural Gas (SNG) Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Natural Gas (SNG) Market Analytics
The EU Green Deal is expanding the cost-of-entry calculus for fossil-derived gas alternatives across European industrial clusters. Sasol leverages its Fischer-Tropsch heritage to reposition coal gasification assets toward lower-carbon SNG pathways. Linde plc anchors large-scale methanation deployments through cryogenic hydrogen and carbon capture integration. Air Liquide competes on biomethane upgrading capacity, with membrane and pressure-swing adsorption systems operational across multiple EU member states.
Synthetic Natural Gas denotes methane-rich gas manufactured through thermochemical or biological conversion of coal, biomass, or hydrogen-carbon dioxide mixtures, typically achieving Wobbe index parity with conventional natural gas at 47.5-51.5 MJ/m³ for seamless grid injection. Its primary purpose is to decarbonize existing natural gas infrastructure without burner retrofit or pipeline replacement. SNG production from biomass gasification captures widening margin pools as EU renewable energy directives award guarantees of origin premiums, while coal gasification segments face structural compression under tightening emissions trading scheme carbon costs. Steam methane reforming paired with carbon capture dominates current capacity, though methanation routes using green hydrogen are accelerating fastest in project pipelines.
EMA's sustainability criteria for renewable fuels, REACH chemical safety protocols, and the EU F-Gas Regulation collectively shape product purity standards, grid interconnection rules, and equipment refrigerant choices across the SNG value chain. Germany's KBA and France's ANSM enforce end-use compliance for transport and industrial gas applications respectively. Stakeholders must monitor hydrogen blending limits in national gas grids and the pace of biomethane certificate standardization to align capital deployment with evolving offtake structures.
Market Dynamics
The EU Emissions Trading Scheme compresses margins on fossil-derived SNG while biomethane certificate premiums widen, forcing producers to reconfigure feedstock portfolios toward renewable gasification pathways.
Growth Catalysts
- Carbon Border Adjustment Mechanism:The EU CBAM phases in carbon cost parity for imported industrial goods, pushing German steel and chemical clusters toward certified renewable SNG to preserve export competitiveness.
- Biomethane upgrading:Membrane and pressure-swing adsorption systems achieve grid-quality methane purity at sub-10% energy loss, unlocking agricultural residue feedstocks previously excluded from pipeline injection.
- Industrial heat electrification limits:High-temperature process heat above 400°C remains technically challenging to electrify, preserving SNG's role in cement, glass, and ceramics manufacturing across the Netherlands and Belgium.
Market Restraints
- Green hydrogen cost structure:Electrolyzer capex and renewable electricity pricing render power-to-gas methanation routes economically marginal without sustained subsidy support in most EU member states.
- Biomass supply concentration:Agricultural residue collection networks cluster in Poland, Romania, and Baltic states, creating logistics bottlenecks for Western European upgrading facilities.
- F-Gas Regulation compliance:REACH chemical safety protocols and EU F-Gas restrictions on refrigerants in cryogenic separation units extend equipment procurement timelines by 12-18 months.
Strategic Opportunities
- Denmark's tariff architecture:Energinet's guaranteed grid access and priority dispatch for renewable gas upgrades create bankable offtake structures for first-mover biomethane-to-SNG projects.
- Hydrogen backbone repurposing:Existing natural gas transmission corridors in Germany and the Netherlands accept blended hydrogen-SNG mixtures, enabling incremental decarbonization without pipeline replacement.
- Guarantees of origin standardization:The EU's proposed harmonized biomethane certificate registry would cross-border trade premiums currently trapped in national verification silos.
Industry Challenges
- Process control engineering scarcity:Fischer-Tropsch and methanation plant operators face acute shortages of technicians trained in syngas ratio optimization and catalyst lifecycle management.
- Grid interconnection certification:France's ANSM and Germany's KBA maintain divergent purity specifications for industrial gas applications, forcing dual-track compliance testing for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Natural Gas (SNG) Market |
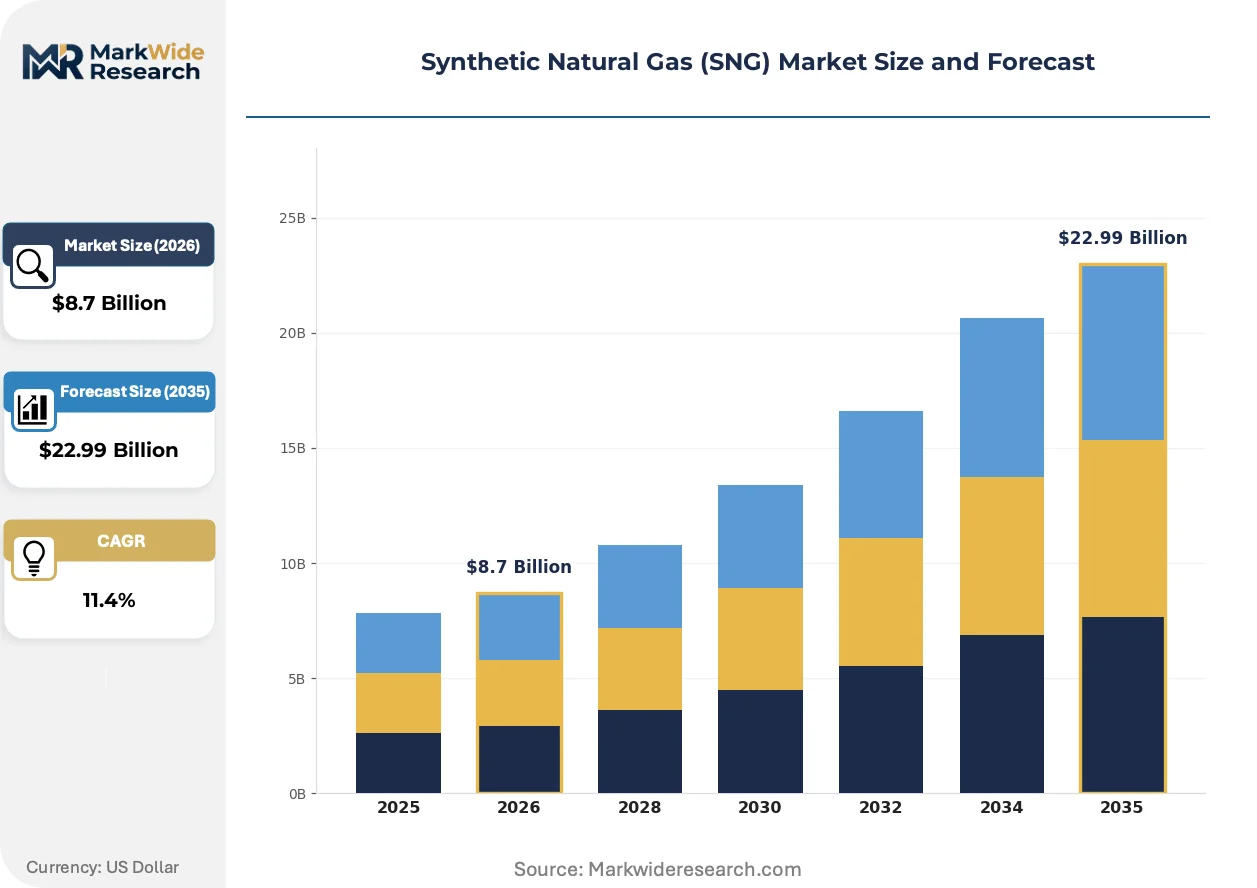
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: SNG Production, Biogas Upgrading, Coal Gasification, Biomass Gasification Technology: Steam Methane Reforming, Methanation, Fischer-Tropsch Synthesis, Pyrolysis End User: Power Generation, Industrial Heat, Residential Heating, Transportation Application: Heating, Electricity Generation, Fuel Supply, Feedstock |
| Companies Covered | Sasol, Linde plc, Air Liquide, Dakota Gasification Company, Siemens Energy AG, Air Products and Chemicals, Inc, Shell, TotalEnergies, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Natural Gas (SNG) Market Evolving Landscape
Biological methanation using archaea cultures is overtaking thermochemical routes in project pipelines, while regulatory pressure on embedded carbon intensifies feedstock traceability requirements across the value chain.
Biological methanation deploys hydrogenotrophic archaea to convert carbon dioxide and hydrogen directly to methane at ambient pressure, eliminating the energy-intensive compression stages of Sabatier reactors. Danish and Dutch pilot facilities demonstrate 85% conversion efficiency at sub-50 bar operating conditions. This biological pathway is overtaking thermochemical methanation in new project announcements due to 30-40% lower electricity intensity and compatibility with intermittent renewable hydrogen supply.
REACH chemical safety protocols now mandate full substance registration for catalyst precursors and process intermediates in SNG production, extending pre-construction authorization timelines. The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants forces cryogenic hydrogen liquefaction plants to adopt ammonia or magnetic-bearing turboexpanders. Upgrading equipment suppliers in Germany and France accelerate R&D partnerships to certify alternative refrigerant architectures before 2027 compliance deadlines.
Industrial offtake contracts now specify mass-balance certification rather than physical renewable gas delivery, enabling virtual trading of biomethane certificates separate from molecule flows. Chemical and food processing buyers in Belgium and the Netherlands lead this contractual evolution, unbundling price discovery from pipeline logistics. This certificate-driven procurement model concentrates liquidity in Denmark's Energinet registry and Germany's dena platform, marginalizing bilateral physical offtake negotiations.
Synthetic Natural Gas (SNG) Market Segmentation
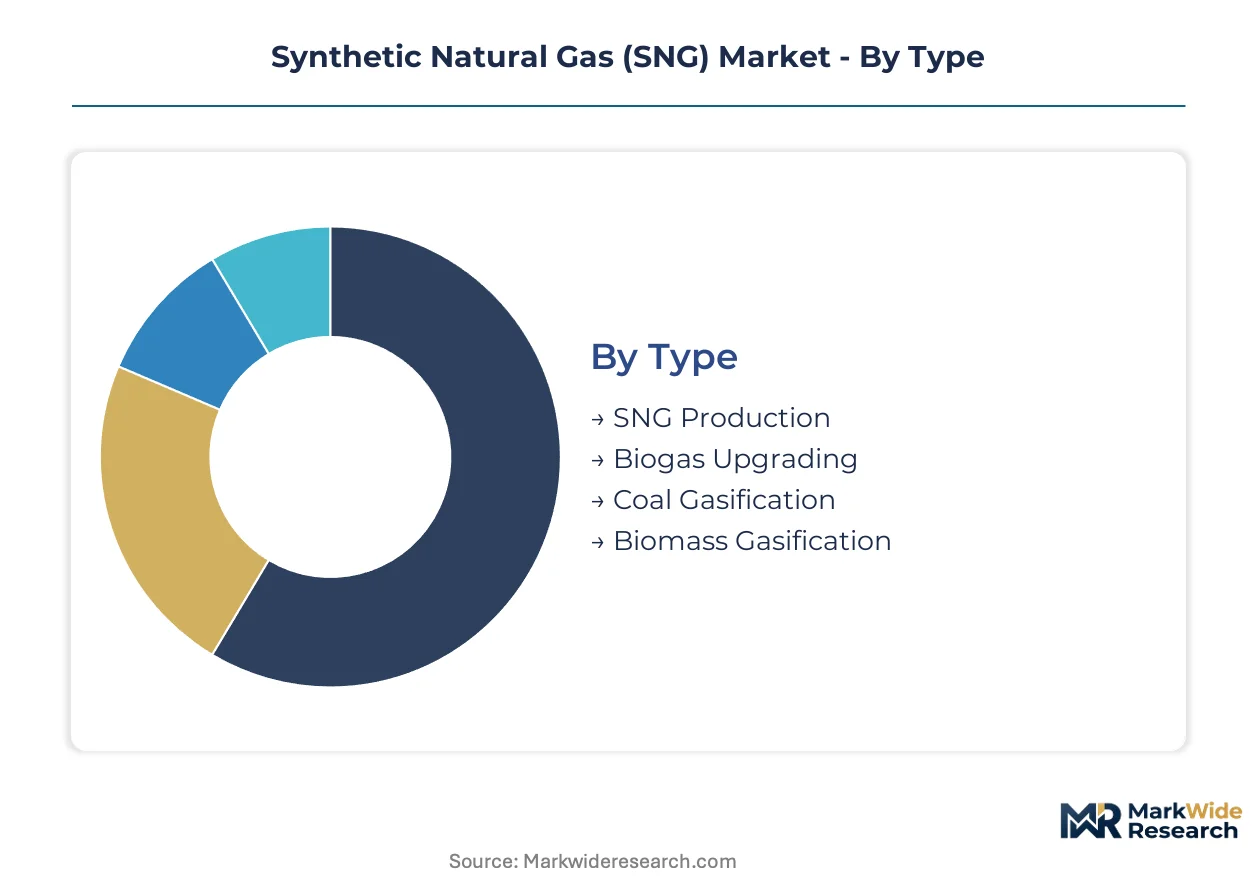
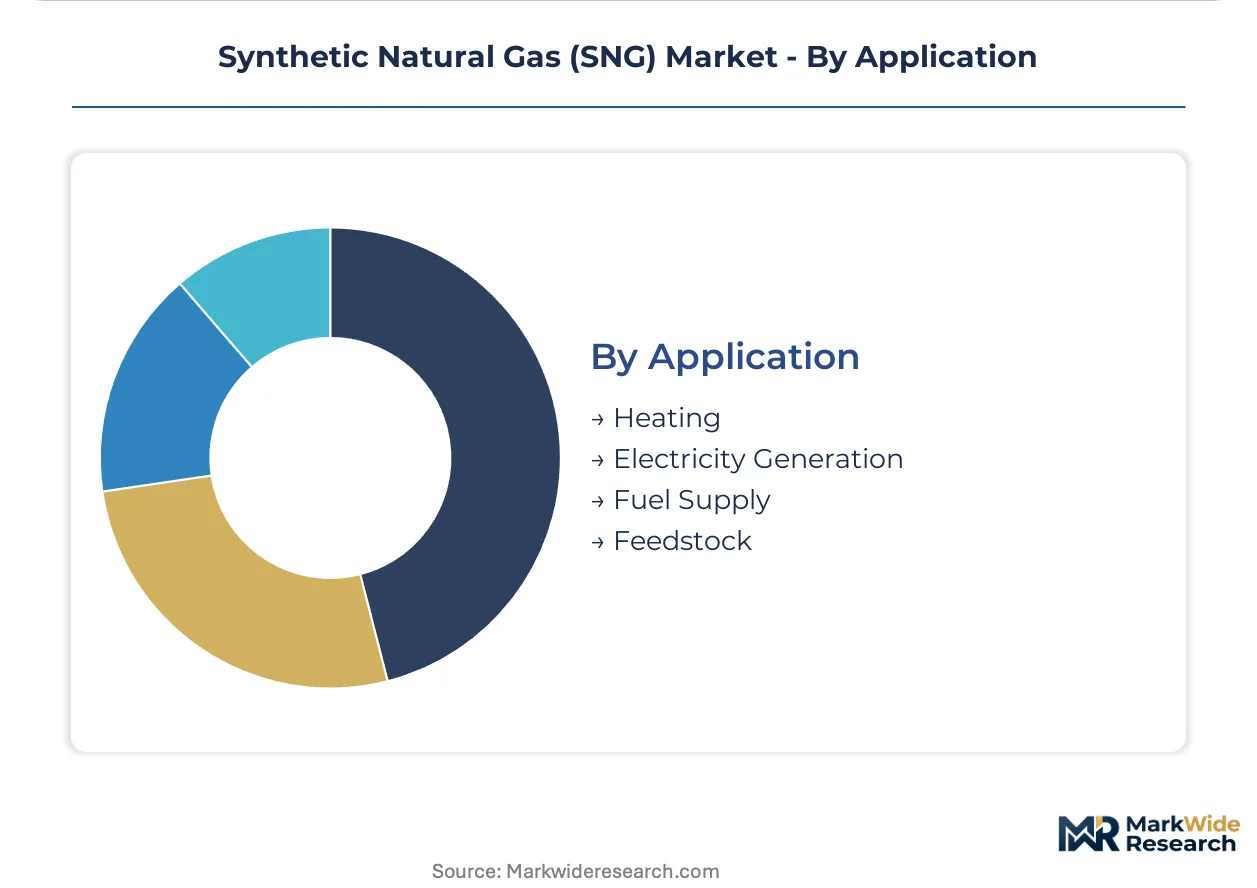
SNG market segmentation reveals divergent margin structures across production pathways and end-use applications. Producers must align feedstock access, technology choices, and offtake contracts to capture value in a market bifurcated between fossil-legacy assets and renewable gasification projects.
Type:
Volume concentrates in established fossil conversion routes, while premium margins accrue to renewable gasification pathways with guaranteed grid access.
- SNG Production:Thermochemical conversion of coal or biomass into methane-rich syngas achieves Wobbe index parity with pipeline natural gas. German industrial clusters in North Rhine-Westphalia anchor demand as carbon border adjustments tighten on imported steel and chemicals.
- Biogas Upgrading:Membrane and pressure-swing adsorption systems purify anaerobic digester output to grid-quality methane. Danish agricultural cooperatives leverage Energinet's priority dispatch tariffs to monetize manure and crop residue feedstocks through biomethane certificates.
- Coal Gasification:Sasol's Fischer-Tropsch heritage assets face structural margin compression under EU Emissions Trading Scheme carbon costs. South African and Polish facilities confront feedstock quality variability and rising compliance expenditures.
- Biomass Gasification:Wood pellet and agricultural residue conversion captures renewable energy directive premiums. Baltic states and Romania concentrate feedstock supply, creating logistics bottlenecks for Western European upgrading capacity.
Today's leader: SNG Production. Tomorrow's challenger: Biogas Upgrading.
Technology:
Cost tier stratification separates mature steam reforming from capital-intensive methanation and Fischer-Tropsch installations.
- Steam Methane Reforming:Dominates installed capacity through proven syngas generation from natural gas or coal. Dutch and Belgian chemical clusters pair reforming units with carbon capture to preserve export competitiveness under CBAM phase-in.
- Methanation:Sabatier reaction routes using green hydrogen and captured carbon dioxide command project pipeline attention. Danish pilot facilities demonstrate biological methanation at ambient pressure, cutting electricity intensity versus thermochemical alternatives.
- Fischer-Tropsch Synthesis:Legacy coal-to-liquids technology repurposed for SNG output faces catalyst precursor registration delays under REACH protocols. Sasol maintains operational expertise scarcity in syngas ratio optimization.
- Pyrolysis:Thermal decomposition of biomass or waste plastics yields syngas with elevated tar content requiring secondary conditioning. Limited commercial deployment outside demonstration scales in Germany and the Netherlands.
Methanation climbs the fastest as electrolyzer capex declines and renewable hydrogen supply firms.
End User:
Application-driven procurement splits between baseload power contracts and industrial heat offtake with stringent purity specifications.
- Power Generation:Grid-balancing capacity and combined-cycle gas turbine fuel demand concentrate in Germany and Denmark. Biomethane certificates enable virtual renewable procurement separate from physical molecule delivery.
- Industrial Heat:Cement, glass, and ceramics manufacturing above 400°C process temperatures preserves gas demand as electrification limits bite. Netherlands and Belgium lead high-temperature fuel switching contracts.
- Residential Heating:District heating network injection and distributed boiler fuel face hydrogen blending mandates in German building codes. France's ANSM maintains divergent purity specifications from Germany's KBA for cross-border suppliers.
- Transportation:Compressed natural gas vehicle fuel and maritime bunkering applications require sulfur and siloxane removal to protect engine systems. Limited infrastructure constrains scaling outside dedicated fleet deployments.
Industrial Heat commands current premium pricing. Power Generation offers steepest expansion trajectory under grid flexibility contracts.
Application:
Customer type differentiation separates commodity heating markets from specialized feedstock and fuel supply segments with certificate-linked premiums.
- Heating:Space and process heat applications dominate volumetric throughput. Dutch greenhouse operators anchor agricultural demand with combined heat and power integration.
- Electricity Generation:Peaking plant and grid stability services reward dispatchable renewable gas. Danish combined heat and power plants prioritize biomethane with guaranteed origin certification.
- Fuel Supply:Transport and marine bunkering segments require dedicated logistics infrastructure. Belgium's Antwerp-Rotterdam-Amsterdam corridor concentrates bunkering demand.
- Feedstock:Chemical synthesis and hydrogen carrier applications specify methane purity above standard grid injection thresholds. German chemical clusters lead power-to-X project announcements.
Heating retains volume leadership. Feedstock applications gain share fastest under chemical sector decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered large-scale coal gasification during the 20th century, leaving a legacy of syngas expertise now repurposed for renewable methane production. Industrial clusters in North Rhine-Westphalia and the Netherlands now anchor European SNG deployment as carbon border adjustments tighten.
Germany
Industrial heat users in cement and glass manufacturing drive SNG procurement as electrification limits persist above 400°C process temperatures. The KBA enforces divergent purity specifications for transport applications, forcing cross-border suppliers into dual-track compliance testing. North Rhine-Westphalia's chemical clusters anchor demand as carbon border adjustment mechanisms phase in on imported steel.
Netherlands
High-temperature fuel switching contracts concentrate in Rotterdam-Antwerp corridor ceramics and glass manufacturers. The national gas grid accepts blended hydrogen-SNG mixtures under building code mandates, enabling incremental pipeline decarbonization. Dutch greenhouse operators in Westland integrate combined heat and power with biomethane certificate procurement.
Denmark
Agricultural cooperatives leverage Energinet's guaranteed grid access and priority dispatch tariffs to monetize manure-derived biomethane. Danish pilot facilities demonstrate biological methanation at ambient pressure, cutting electricity intensity versus thermochemical alternatives. Combined heat and power plants in central Jutland prioritize guaranteed origin certification for grid flexibility contracts.
Belgium
Antwerp-Rotterdam-Amsterdam corridor bunkering demand concentrates transport fuel applications requiring sulfur and siloxane removal. Chemical sector decarbonization mandates drive power-to-X project announcements for feedstock-grade methane purity. Walloon industrial zones face hydrogen blending infrastructure gaps compared to Flemish grid access.
France
ANSM maintains divergent industrial gas purity specifications from Germany's KBA, fragmenting cross-border supplier compliance pathways. Île-de-France district heating networks trial biomethane injection as residential hydrogen blending mandates advance. Auvergne-Rhône-Alpes chemical clusters lag German counterparts in power-to-gas methanation deployment.
Synthetic Natural Gas (SNG) Market Competitive Landscape
The competitive structure tilts toward diversified industrial gas conglomerates with cryogenic and carbon capture integration capabilities. Tiering separates legacy coal gasification operators facing structural margin compression from renewable methanation specialists capturing certificate premiums. Three archetypes dominate: Fischer-Tropsch heritage asset holders, industrial gas majors with hydrogen liquefaction expertise, and biomethane upgrading technology providers. Capacity expansion into biological methanation and strategic partnerships for electrolyzer supply security represent the dominant competitive vectors.
Among Fischer-Tropsch heritage operators, Sasol occupies a position exemplifying coal gasification asset repurposing toward lower-carbon pathways. Linde plc and Air Liquide sit within the industrial gas major tier, representing cryogenic hydrogen and carbon capture integration archetypes respectively. These three companies anchor the competitive landscape as the EU Emissions Trading Scheme reshapes feedstock economics across production routes.
| Leading Market Players |
|---|
| Sasol |
| Linde plc |
| Air Liquide |
| Dakota Gasification Company |
| Siemens Energy AG |
| Air Products and Chemicals, Inc |
| Shell |
| TotalEnergies |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Biological methanation's emergence from Danish pilot facilities simultaneously compresses electricity costs and redraws feedstock procurement geography, as ambient-pressure archaea cultures eliminate energy-intensive compression stages while demanding distributed hydrogen supply nodes closer to renewable generation.
Pricing Analysis
The bundled-vs-unbundled service split separates physical molecule delivery from certificate-only procurement. Pricing stratifies across premium biomethane with guarantees of origin, standard grid-injection SNG, and economy-tier fossil-derived gas facing carbon cost compression. Price differentiation hinges on certification grade under EU renewable energy directives and volume scale in long-term offtake contracts. Margins are tightening in coal gasification routes as EU Emissions Trading Scheme costs accumulate, while agricultural cooperatives exhibit lowest price sensitivity due to priority dispatch tariff protection.
Supply Chain Analysis
Regional distribution centers for upgraded biomethane concentrate in Denmark, Germany, and the Netherlands, with hub-and-spoke patterns radiating from agricultural collection networks to grid injection points. Feedstock supply draws from Polish and Romanian agricultural residue clusters, while catalyst precursors and membrane systems rest on German and French equipment suppliers. Single-source vulnerability runs through Baltic states feedstock concentration for Western European upgrading capacity. Distribution runs through Energinet's guaranteed access tariffs and bilateral industrial offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Synthetic Natural Gas Market operates as a regulatory compounder where EU Green Deal carbon pricing milestones structurally elevate renewable gasification demand above fossil alternatives.
For Market Incumbents: Lock in biomethane certificate liquidity through registry partnerships before harmonized EU guarantees of origin standardization completes. Secure electrolyzer supply agreements to defend methanation project pipelines against green hydrogen cost volatility. Prioritize backward integration into agricultural residue collection networks to offset Baltic states logistics bottlenecks threatening Western European upgrading capacity. For New Entrants and Emerging Players: Biological methanation pilot facilities offer the most penetrable wedge, with Danish and Dutch demonstration projects proving 85% conversion efficiency at sub-50 bar conditions. Target agricultural cooperative offtake structures in Denmark's Energinet tariff architecture where guaranteed grid access de-risks first-mover capital deployment. Lead with technology licensing partnerships rather than asset-heavy construction to accelerate market entry. For Investors and Strategic Acquirers: Valuations sit cheapest among Fischer-Tropsch heritage operators facing structural margin compression under EU Emissions Trading Scheme carbon costs. Five-to-ten year viability favors industrial gas majors with cryogenic hydrogen integration capabilities and biomethane upgrading technology providers capturing certificate premiums. Monitor hydrogen blending limits in German building codes as the inflection signal for power-to-gas methanation project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Agricultural residue networks in Poland and Romania secure supply certainty for Western European upgrading facilities. |
| Biological Methanation Scale-Up | Danish pilot demonstrations at ambient pressure cut electricity intensity versus thermochemical Sabatier alternatives. |
| Certificate Registry Partnership | Energinet and dena platform liquidity concentration enables virtual trading separate from physical molecule delivery. |
| Electrolyzer Supply Security | Green hydrogen cost structure volatility threatens project economics without long-term equipment agreements. |
| Cross-Border Compliance Harmonization | France's ANSM and Germany's KBA divergent purity specifications fragment supplier certification pathways. |
Research Methodology
Direct dialogue with biomethane upgrading plant operators, Fischer-Tropsch facility engineers, agricultural cooperative managers, and grid interconnection regulators grounded qualitative findings in operational reality. Secondary validation drew from EIA energy statistics, IEA renewable gas reports, EU ETS carbon price databases, and national biomethane registry disclosures. Bottom-up project pipeline assessment and top-down regulatory scenario modeling were triangulated against stakeholder interview findings.
Bottom-up volume modeling tracked individual methanation and gasification project announcements across the projection horizon, while top-down analysis calibrated against EU renewable energy directive targets and carbon border adjustment mechanism phase-in schedules. Segmentation dimensions included production pathway type, technology maturity tier, end-use application heat requirements, and regional regulatory framework clusters. CAGRs were derived from capacity-weighted project pipeline analysis and policy-driven demand elasticity assumptions.
The model holds under sustained EU Emissions Trading Scheme carbon price elevation and renewable energy directive guarantee of origin premium structures; deviation in green hydrogen electrolyzer cost trajectories or agricultural residue supply logistics would shift capacity deployment timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Italy Chemical Logistics Market
Fuels
Compressed Natural Gas Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Wood Pellet Market
Fuels
City Gas Distribution Market
Fuels
Fuel Oil Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Multifuel Gas Turbine Market
Fuels
Liquefied Helium Tanks Market
Fuels
Electric Fuel Heater Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
India Retail Fuel Market
Fuels
North America Aviation Fuel Market
Fuels
Storage Tank Market
Fuels
United Kingdom Bunker Fuel Market