
 Aircraft Thrust Reverser Actuation Systems Market | 2026-2036
Aircraft Thrust Reverser Actuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Thrust Reverser Actuation Systems Market Analysis
Commercial aviation's narrowbody fleet renewal is restructuring procurement patterns across the supply chain. Triumph Group leverages its hydraulic actuator specialization to anchor positions on legacy and next-generation platforms. Parker Hannifin Corporation sustains broad portfolio coverage across electric and pneumatic architectures, while Safran SA differentiates through integrated landing gear and thrust management systems that tighten subsystem coupling.
Aircraft thrust reverser actuation systems are electromechanical or hydromechanical devices that translate flight deck or autobrake commands into physical deployment of cascade or bucket-type reverser translating sleeves, typically operating at system pressures between 3,000 and 5,000 psi and response times under 1.5 seconds to ensure rejected takeoff safety margins. Their primary purpose is to redirect engine fan airflow forward during landing rollout, decelerating aircraft without sole dependency on wheel brakes. Electric actuators now capture the fastest-growing product category as more electric aircraft architectures displace centralized hydraulic distribution, while commercial aviation dominates application demand though military aviation offers higher per-unit specification intensity and longer contract cycles. The OEM versus aftermarket split concentrates margin pools in MRO channels as fleet age profiles deepen across North America and Europe.
FAA airworthiness directives and EASA certification specifications jointly govern thrust reverser system reliability standards, with both agencies mandating redundant command paths and fail-safe stow provisions that elevate actuator design complexity. The EU Green Deal's trajectory for sustainable aviation fuels and emissions reductions indirectly pressures manufacturers to lighten actuation hardware and reduce hydraulic fluid volumes. Stakeholders must monitor whether China's CAAC adopts harmonized reliability standards or pursues indigenous certification pathways that fragment supplier qualification requirements.
Market Dynamics
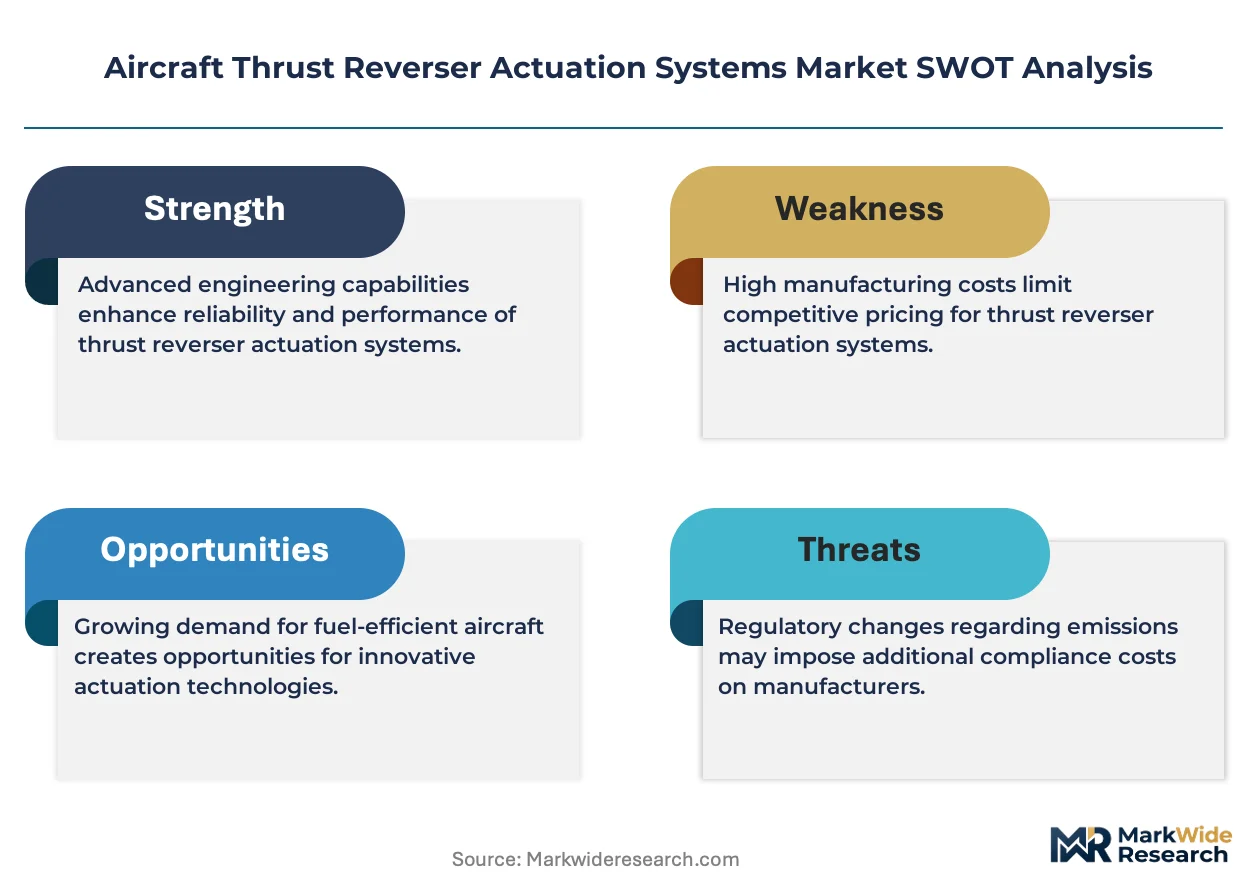
Electric actuator architectures are displacing centralized hydraulic distribution across narrowbody and widebody platforms, forcing suppliers to requalify component portfolios for distributed power architectures and higher-voltage electrical environments.
Growth Catalysts
- FAA Airworthiness Directives:Mandates on thrust reverser reliability and fail-safe stow provisions are elevating actuator design complexity and creating replacement demand across the installed fleet.
- Narrowbody Fleet Renewal:Airlines including Southwest and Ryanair are restructuring procurement patterns through multi-year fleet replacement programs that synchronize actuation system orders with airframe deliveries.
- More Electric Aircraft:Boeing and Airbus next-generation platforms are specifying electromechanical actuation to eliminate hydraulic distribution weight and maintenance burden.
Market Restraints
- Titanium and Superalloy Input Costs:Actuator housings and high-load components depend on aerospace-grade titanium and nickel superalloys subject to price volatility and Russian supply disruption.
- Supplier Concentration in Wichita and Toulouse Clusters:Tier-2 actuator assembly concentrates among a limited supplier base, creating single-source exposure for OEM qualification pathways.
- Hydraulic System Legacy Lock-In:Existing MRO infrastructure and technician certification pools slow displacement of proven hydromechanical architectures despite electric alternatives.
Strategic Opportunities
- India Defense Aviation:Indigenous fighter and transport programs under the country's defense procurement procedures are creating first-tier supplier qualification pathways for actuation specialists.
- EU Green Deal Trajectory:Emissions reduction mandates and sustainable aviation fuel compatibility requirements are pressuring manufacturers to lighten actuation hardware and reduce hydraulic fluid volumes.
- Predictive Maintenance Convergence:Integration of electromechanical actuators with aircraft health monitoring systems enables condition-based overhaul scheduling and unbundled service contracts.
Industry Challenges
- Electromechanical Certification Timelines:FAA and EASA qualification protocols for electric actuation in safety-critical deceleration systems extend development cycles and compress first-mover windows.
- Cross-Platform Software Verification:Common actuator control software deployed across multiple airframe types faces heightened scrutiny under DO-178C standards and variant-specific validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Thrust Reverser Actuation Systems Market |
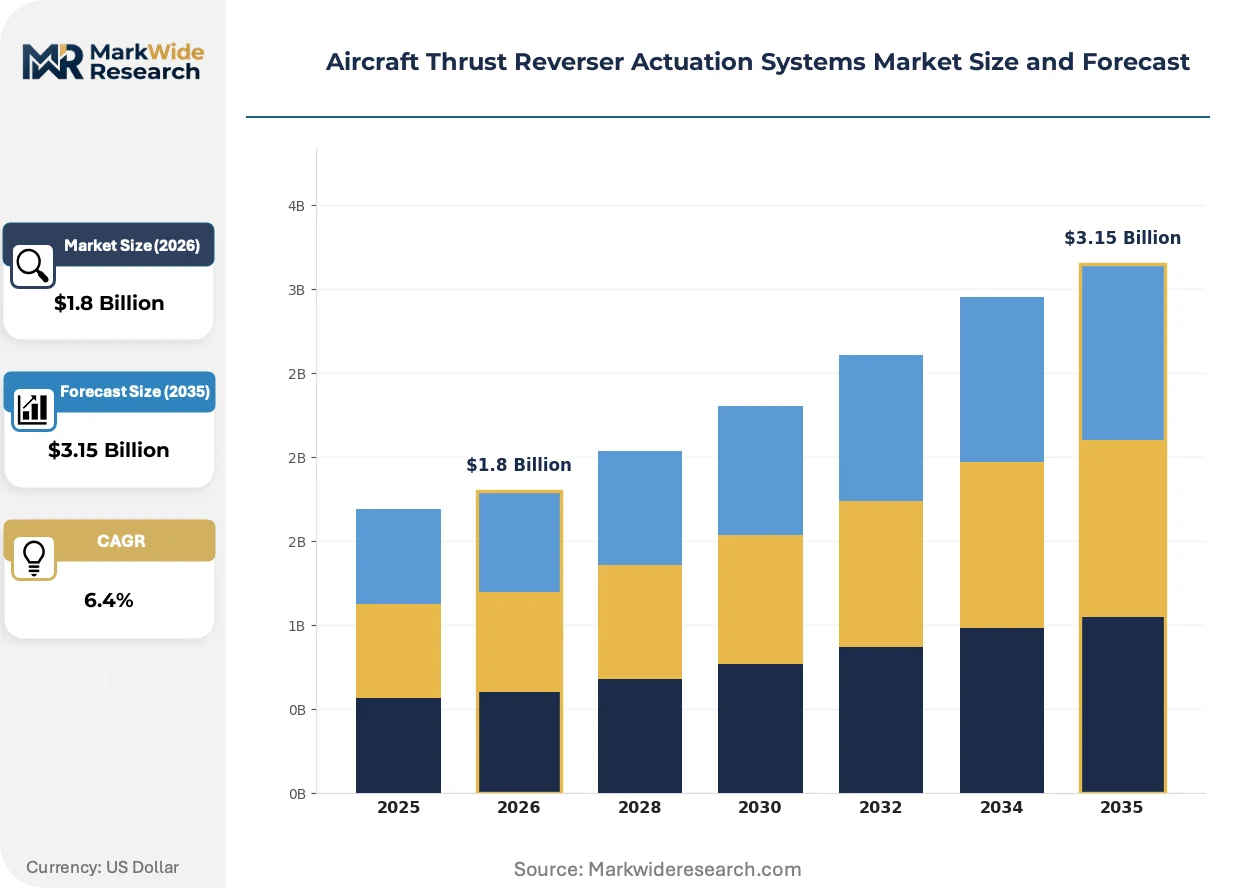
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electric Actuators, Pneumatic Actuators, Mechanical Systems Application: Commercial Aviation, Military Aviation, Business Jets, Rotorcraft Maneuver Mode: Single Acting, Double Acting, Variable Geometry, Fixed Geometry End User: OEMs, Maintenance, Repair & Overhaul, Airlines, Leasing Companies |
| Companies Covered | Triumph Group, Woodward Inc, Parker Hannifin Corporation, Collins Aerospace, Safran SA, Liebherr-Aerospace, Moog Inc, Singapore Technologies Engineering Ltd, Arkwin Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Thrust Reverser Actuation Systems Market Emerging Trajectories
Actuation system architectures are fragmenting across competing power modalities as electric, hydraulic, and hybrid configurations vie for platform-specific optimization. This technological divergence is compressing supplier development resources and fragmenting qualification pathways.
Distributed electromechanical actuation is decentralizing power distribution across the nacelle, replacing centralized hydraulic manifolds with localized motor-drive units. Boeing's 787 and Airbus A350 programs have validated this topology for spoiler and slat systems, and thrust reverser applications are following. The shift is decentralizing maintenance accountability from airframe hydraulic shops to nacelle-integrated LRU replacement protocols.
EASA Certification Specifications for Large Aeroplanes (CS-25) amendments on thrust reverser command path redundancy are tightening software and hardware verification requirements. The specifications now mandate dissimilar redundancy for electric command channels, forcing architectural redesigns. European OEMs and their supply chains are responding by segregating actuator control electronics across multiple hardware platforms.
Airline technical procurement teams are consolidating actuator sourcing decisions at the fleet level rather than deferring to individual MRO station preferences. This centralization is compressing regional supplier relationships and elevating OEM-direct contracting for integrated thrust management systems. The pattern is most visible among US network carriers with standardized narrowbody configurations.
Aircraft Thrust Reverser Actuation Systems Market Segmentation
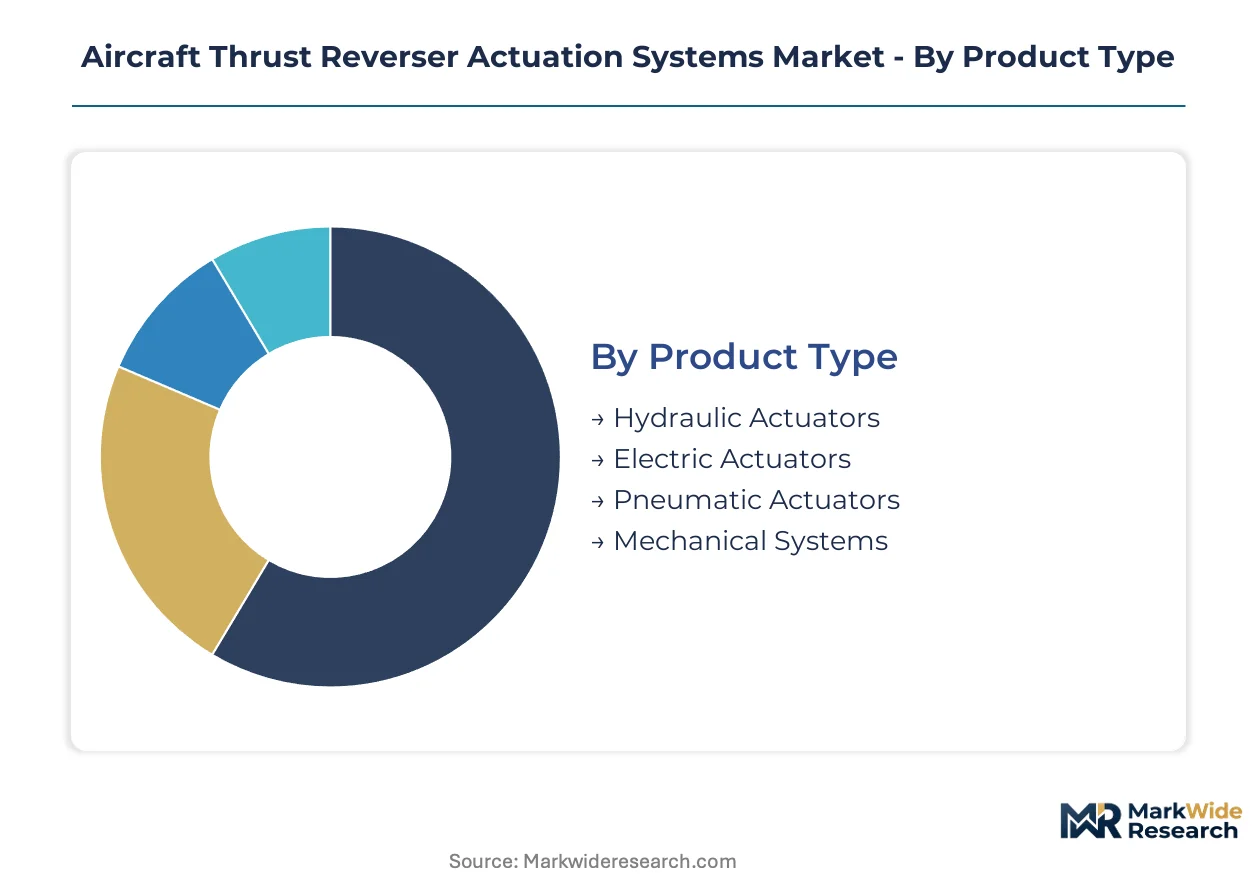
Thrust reverser actuation systems fragment across power modalities, airframe applications, and procurement channels. Each segmentation axis carries distinct margin profiles, certification burdens, and supplier qualification pathways that reshape competitive positioning.
Product Type:
Standardization dominates hydraulic architectures while electric systems demand platform-specific customization for voltage environments and thermal management.
- Hydraulic Actuators:These systems operate at pressures between 3,000 and 5,000 psi using centralized distribution manifolds. Demand concentrates in legacy narrowbody retrofits and MRO channels across the United States, constrained by technician certification pools and existing infrastructure investments.
- Electric Actuators:Motor-drive units replace hydraulic lines with localized electromechanical conversion. Boeing and Airbus next-generation platforms in Toulouse and Charleston are driving specification intensity, displacing centralized hydraulic distribution to reduce weight and maintenance burden.
- Pneumatic Actuators:Compressed air systems persist in regional turboprop applications where bleed air availability simplifies integration.
- Mechanical Systems:Cable-and-linkage architectures remain in select military transport platforms with redundant manual override requirements.
Most installed capacity flows through Hydraulic Actuators. Expansion is steepest in Electric Actuators.
Application:
Volume scales inversely with specification intensity across airframe categories, concentrating procurement leverage in high-unit commercial programs.
- Commercial Aviation:Narrowbody and widebody platforms generate the dominant unit demand. Fleet renewal programs at Southwest and Ryanair are synchronizing multi-year actuation orders with airframe delivery schedules, restructuring supplier contracting patterns.
- Military Aviation:Fighter and transport programs impose higher per-unit specification intensity with extended contract cycles. India's indigenous defense procurement procedures under the Ministry of Defence are creating first-tier supplier qualification pathways for actuation specialists.
- Business Jets:Low-volume, high-customization requirements characterize this segment with fragmented OEM procurement.
- Rotorcraft:Helicopter thrust management systems represent a distinct technical category with limited supplier overlap.
Commercial Aviation channels the majority of unit demand. Military Aviation delivers the steepest per-unit margin expansion.
Maneuver Mode:
Actuator kinematics divide between unidirectional simplicity and bidirectional control sophistication, with geometry flexibility determining platform compatibility breadth.
- Double Acting:Bidirectional force application enables precise positioning control for cascade-type reverser sleeves. Airbus A350 and Boeing 787 programs specify these architectures for variable deployment profiles during rejected takeoff scenarios.
- Variable Geometry:Adaptive sleeve positioning optimizes reverse thrust efficiency across landing weight and runway conditions. EASA CS-25 amendments on command path redundancy are elevating verification requirements for these electronically controlled systems.
- Single Acting:Spring-return stow mechanisms simplify fail-safe provisions in legacy bucket-type reverser installations.
- Fixed Geometry:Constant deployment angles persist in regional jet platforms with standardized landing performance envelopes.
Double Acting architectures anchor the installed fleet base. Variable Geometry systems are climbing the fastest as next-generation platforms proliferate.
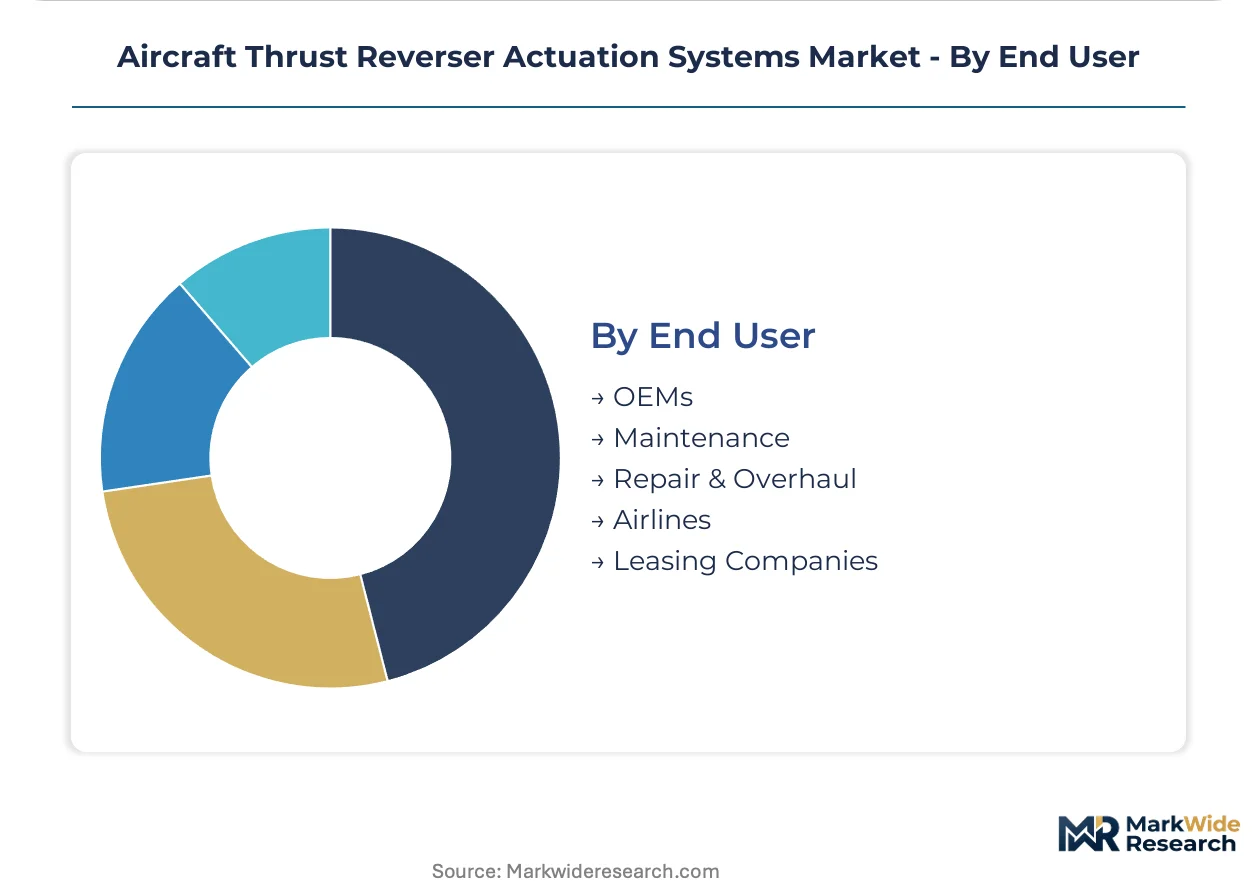
End User:
Procurement authority is migrating from distributed MRO stations toward centralized fleet-level technical teams, compressing regional supplier relationships.
- Maintenance, Repair & Overhaul:Post-warranty actuation system overhauls concentrate margin pools as North American and European fleet age profiles deepen. Predictive maintenance convergence with aircraft health monitoring is enabling condition-based scheduling and unbundled service contracts.
- OEMs:Airframe manufacturers specify actuation systems at platform design freeze, locking supplier positions for production runs spanning decades. Boeing's final assembly lines in Everett and Charleston anchor qualification pathways for integrated thrust management systems.
- Airlines:Technical procurement consolidation at US network carriers with standardized narrowbody configurations is elevating OEM-direct contracting.
- Leasing Companies:Residual value protection drives specification standardization across managed fleets.
MRO channels capture the dominant share of lifecycle value. OEM procurement is gaining share fastest as fleet renewal accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita's aerostructures corridor anchors the largest concentration of thrust reverser actuation manufacturing globally. FAA certification protocols and Boeing's final assembly footprint in Everett and Charleston drive supplier qualification intensity. Regional demand patterns diverge sharply between mature fleet replacement markets and emerging indigenous defense programs.
United States
Boeing's 737 MAX and 787 production lines in Renton and Charleston synchronize multi-year actuation orders with airframe delivery schedules. FAA airworthiness directives on thrust reverser reliability mandate redundant command paths that elevate design complexity for suppliers. Wichita's aerostructures cluster hosts Tier-2 actuator assembly operations with concentrated single-source exposure for OEM qualification pathways.
France
Airbus A350 and A320neo final assembly in Toulouse drives specification intensity for electromechanical architectures displacing hydraulic distribution. EASA CS-25 amendments mandate dissimilar redundancy for electric command channels, forcing architectural redesigns across European supply chains. The Toulouse-Blagnac aerospace cluster tightens subsystem coupling between landing gear and thrust management systems.
India
Indigenous fighter and transport programs under the Ministry of Defence's procurement procedures create first-tier supplier qualification pathways for actuation specialists. The country's national aviation regulator aligns reliability standards with FAA and EASA frameworks while permitting indigenous certification pathways. Bengaluru's defense aerospace corridor concentrates subsystem integration capabilities for domestic platform requirements.
Germany
Airbus wing assembly in Hamburg and Bremen anchors demand for cascade-type reverser sleeve actuation systems. EU Green Deal emissions reduction mandates pressure manufacturers to lighten actuation hardware and reduce hydraulic fluid volumes. The Hamburg metropolitan region hosts specialized MRO infrastructure for European fleet age profile deepening.
Japan
Mitsubishi Regional Jet and Boeing 787 workshare programs sustain precision actuator component demand. METI industrial policy supports aerospace supply chain localization for critical flight control subsystems. The Nagoya aerospace cluster concentrates Tier-3 machining capabilities for titanium and superalloy actuator housings.
Aircraft Thrust Reverser Actuation Systems Market Vendor Landscape
Portfolio diversification dominates the current landscape as suppliers requalify component architectures for distributed power systems. The market structure concentrates among integrated tier-one aerostructures suppliers and specialized motion control specialists. Three archetypes define competitive positioning: legacy hydraulic specialists pivoting toward electromechanical platforms, diversified industrial conglomerates with broad aerospace portfolios, and precision motion control pure-plays. M&A activity and strategic technology licensing agreements represent the dominant competitive vectors as firms secure positions on next-generation narrowbody and widebody programs.
Within the diversified industrial tier, Parker Hannifin Corporation and Safran SA exemplify broad portfolio coverage across competing power modalities. Triumph Group occupies a position representing legacy hydraulic specialization with established narrowbody platform positions. Moog Inc anchors the precision motion control archetype with electromechanical system capabilities. These three entities collectively illustrate the strategic tension between incumbent hydraulic infrastructure and accelerating electric architecture displacement across Boeing and Airbus supply chains.
| Leading Market Players |
|---|
| Triumph Group |
| Woodward Inc |
| Parker Hannifin Corporation |
| Collins Aerospace |
| Safran SA |
| Liebherr-Aerospace |
| Moog Inc |
| Singapore Technologies Engineering Ltd |
| Arkwin Industries Inc |
| Others |
Supply Flow & Price Mechanics
Titanium and nickel superalloy input costs cascade through actuator manufacturing tiers, compressing margins at hydraulic specialists while electric architecture suppliers command certification premiums from Boeing and Airbus procurement teams.
Pricing Analysis
Distributor margins on legacy hydraulic actuators are compressing as OEMs consolidate fleet-level sourcing decisions at Southwest and Ryanair. Three-tier pricing structure across fail-safe redundant, standard commercial, and regional jet tiers reflects EASA CS-25 amendment compliance burdens. Pricing pressure stems from Russian supply disruption in aerospace-grade titanium. MRO channels exhibit highest price sensitivity; integrated thrust management system suppliers show lowest.
Supply Chain Analysis
Workforce availability constraints in Wichita and Toulouse clusters are forcing Tier-2 actuator assemblers to extend qualification timelines. Manufacturing concentrates in the United States, France, and Germany. Supply chains draw from titanium sponge producers, precision forging operations, and high-voltage motor winding facilities. Single-source vulnerability permeates Boeing 737 MAX nacelle-integrated LRU protocols. Distribution runs through OEM-direct contracting and consolidated airline technical procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FAA airworthiness directives on thrust reverser reliability mandate redundant command paths that only certified suppliers can satisfy.
For Market Incumbents: Extend electric actuator qualification portfolios to secure positions on next-generation narrowbody platforms before development windows close. Lock in exclusive supplier agreements with Wichita aerostructures clusters to defend against emerging electromechanical pure-plays. Prioritize DO-178C software verification investment to meet EASA dissimilar redundancy mandates. For New Entrants and Emerging Players: Enter via India's Ministry of Defence indigenous fighter programs where first-tier supplier qualification pathways remain open to foreign actuation specialists. Target military aviation segments with higher per-unit specification intensity and extended contract cycles. Pursue technology licensing agreements with established Tier-2 assemblers to bypass certification timeline barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where hydraulic legacy lock-in meets electric architecture displacement across Boeing and Airbus supply chains. Five-to-ten year viability favors precision motion control pure-plays with electromechanical capabilities over undiversified hydraulic specialists. Watch for CAAC harmonization with FAA/EASA reliability standards as inflection signal for supplier qualification fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Certification Investment | DO-178C compliance opens Boeing 797 and Airbus A320neo successor programs to qualified suppliers. |
| Backward Integration into Titanium Forging | In-house superalloy component production insulates margins from Russian supply disruption volatility. |
| Predictive Maintenance Platform Integration | Aircraft health monitoring convergence enables condition-based overhaul contracts with US network carriers. |
| India Defense Procurement Qualification | Ministry of Defence indigenous programs create first-tier supplier pathways outside saturated commercial channels. |
| EU Green Deal Lightweighting R&D | Reduced hydraulic fluid volume architectures align with emissions mandates for European fleet operators. |
Methodological Framework
Bottom-up commercial aviation fleet modeling reconciled against top-down actuator supplier production tracking forms the analytical core of this study. Primary interviews with airframe platform engineers, MRO technical directors, airline procurement managers, and FAA certification specialists were validated against secondary sources including FAA airworthiness directive filings, EASA CS-25 amendment documentation, and Boeing Airbus delivery schedules. Trade data on titanium and superalloy inputs provided upstream cost calibration.
Historical trendline analysis across narrowbody and widebody delivery cycles established baseline penetration assumptions for hydraulic versus electric architectures. Segmentation modeling captured power modality, application intensity, maneuver geometry, and procurement channel dimensions. CAGRs were derived from installed fleet age profiles and replacement demand curves. Forecast inputs incorporated Boeing 737 MAX production ramp assumptions and Airbus A320neo backlog conversion rates.
Inputs from FAA certification databases and EASA safety publication archives were available through the study window; gaps in CAAC indigenous pathway documentation introduce uncertainty bands around China market penetration assumptions. Forecasts reflect documented assumptions on electric architecture displacement velocity and superalloy price normalization. Material deviation in CAAC harmonization decisions or Russian titanium export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aerospace Battery Technology Market