
 Aluminum Extrusion Lubricants Market | 2026-2036
Aluminum Extrusion Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Extrusion Lubricants Market Outlook
Synthetic ester formulations are restructuring cost structures across the aluminum extrusion lubricants sector as shops phase out chlorinated paraffin stocks. AMCOL Corporation leverages its bentonite-derived additive portfolio to anchor supply relationships with North American billet producers. CONDAT sustains formulation leadership in water-based systems through its European technical service network. Metalloid Corporation specializes in high-pressure metalworking chemistries that extend die life in continuous extrusion lines.
Aluminum extrusion lubricants are chemically engineered boundary films applied to billets, dies, and containers to reduce friction coefficients during high-temperature deformation, typically formulated with synthetic esters, graphite, or hexagonal boron nitride dispersed in aqueous or hydrocarbon carriers to withstand pressures exceeding 1,000 MPa and temperatures above 450°C. Oil-based lubricants still dominate legacy press installations across mature aerospace supply chains where equipment conversion costs stall substitution. Water-based systems represent the fastest-expanding product category as automotive end users enforce shop-floor volatile organic compound thresholds that disqualify solvent-based alternatives. Dry film boron nitride coatings command premium positioning in electronics-grade precision extrusion where surface contamination tolerances approach zero.
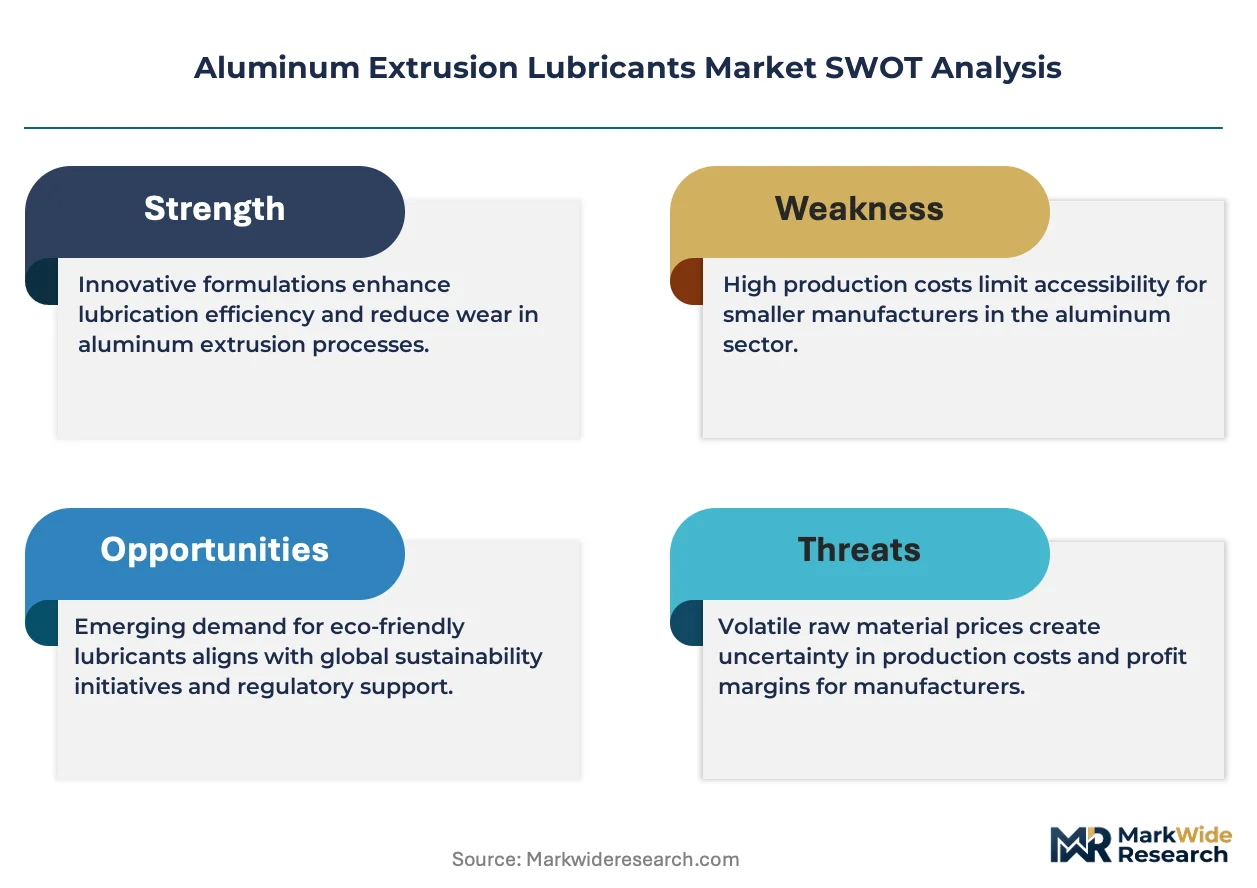
EPA enforcement under the Toxic Substances Control Act and REACH registration requirements in Europe are accelerating reformulation timelines, while China's Ministry of Ecology and Environment tightens emissions permits for metalworking fluid compounding facilities. The EU F-Gas Regulation and evolving state-level OSHA permissible exposure limits in California and Michigan are compressing allowable chemistries for chlorinated and sulfurized additives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Synthetic ester chemistry is displacing chlorinated paraffin stocks across aluminum extrusion facilities, forcing reformulation investments that compress legacy supplier margins while opening white space for boron nitride and aqueous system specialists.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany enforce volatile organic compound thresholds that redirect extrusion facility procurement toward water-based lubricant systems.
- REACH compliance deadlines:ECHA registration requirements accelerate phase-out schedules for sulfurized additives across European compounding operations.
- Hexagonal boron nitride dispersion advances:Electronics-grade precision extrusion in China's Yangtze River Delta cluster demands zero-contamination dry film coatings.
Market Restraints
- Petrochemical feedstock volatility:Synthetic ester base oil costs fluctuate with naphtha cracking margins, compressing blender profitability.
- Die conversion capex:Legacy oil-based press installations in aerospace supply chains require container and runout table modifications to handle aqueous chemistries.
- Chlorinated paraffin substitution timelines:EPA Toxic Substances Control Act enforcement creates stranded inventory risk for distributors holding legacy stocks.
Strategic Opportunities
- India extrusion capacity expansion:PLI scheme incentives for aluminum downstream processing create first-mover positioning for synthetic ester formulators.
- Closed-loop aqueous recycling:Water-based system providers capture recurring revenue through on-site fluid management contracts.
- Dual carbon goals alignment:China's Ministry of Ecology and Environment emissions permits favor low-carbon intensity lubricant production.
Industry Challenges
- Tribochemistry expertise scarcity:Formulators struggle to hire specialists who understand high-pressure metalworking fluid behavior above 450°C.
- Cross-border regulatory divergence:EU F-Gas Regulation and California OSHA permissible exposure limits create incompatible additive packages.
- Legacy equipment integration:Continuous extrusion lines require sequential die and container upgrades to accommodate new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Extrusion Lubricants Market |
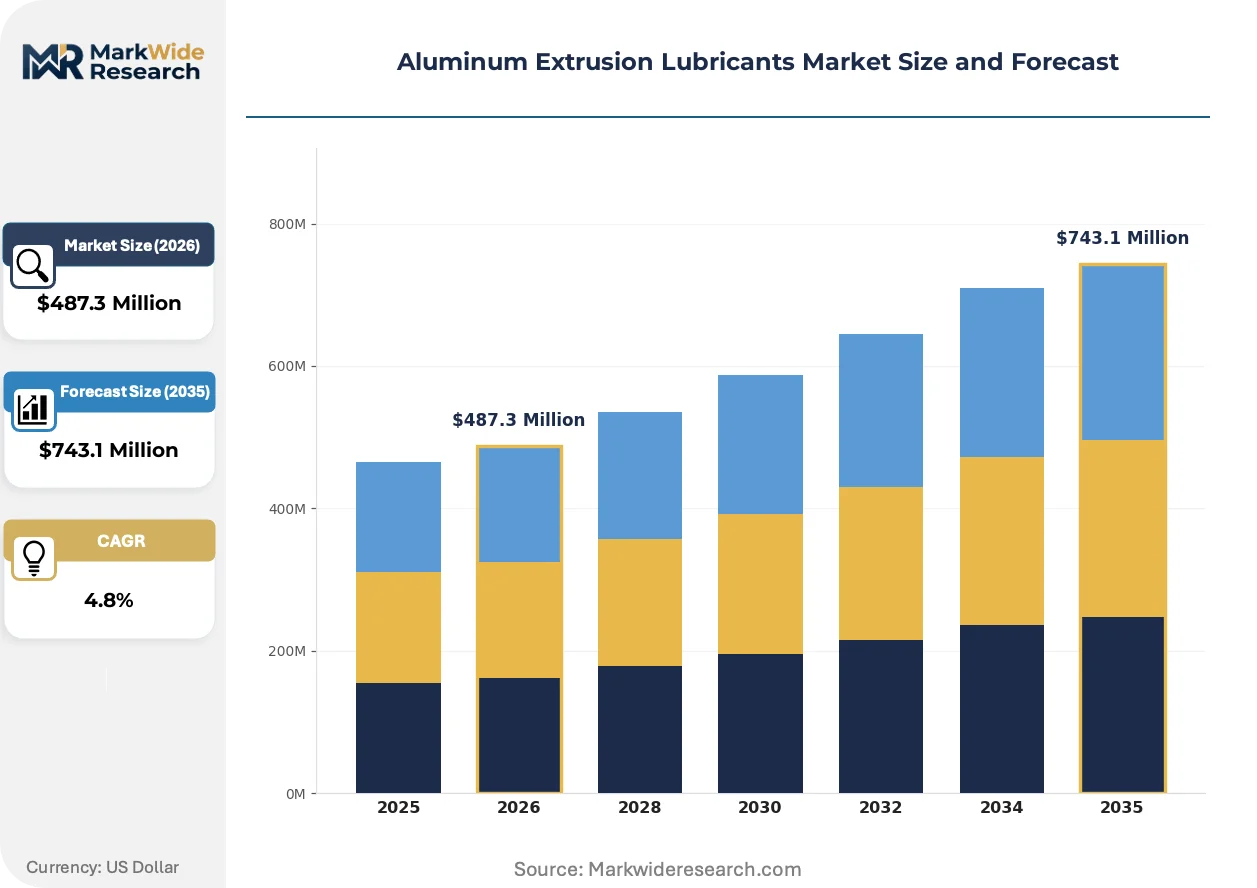
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Solvent-Based, Dry Film Application: Billet, Continuous Extrusion, Sheet Metal, Profiles End User: Aerospace, Automotive, Construction, Electronics Grade: Industrial, Food Grade, Marine, Specialty |
| Companies Covered | AMCOL Corporation, Metalloid Corporation, CONDAT, Sunbelt Lubricants, Chem Arrow Corporation, Kluber Lubrication, OEST Group, IKV Lubricants, Saint-Gobain Boron Nitride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Extrusion Lubricants Market Strategic Shifts
Boron nitride nanosheet dispersions are electrifying formulation possibilities while regulatory chemistry restrictions tighten and buyer procurement models compress supplier relationships.
Synthetic ester base stocks with tailored viscosity indices are electrifying high-pressure performance in continuous extrusion lines. Tier 1 automotive suppliers in Germany and Japan specify these chemistries for 6000-series aluminum profiles. The technology is electrifying competitive positioning by collapsing the performance gap between aqueous and oil-based systems.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing complete reformulation across European metalworking fluid blenders. The regulation eliminates cost-competitive legacy options for aerospace extruders. German extrusion clusters respond by accelerating water-based system validation timelines.
Direct procurement from compounders is consolidating distributor influence across North American billet producers. Large extruders bypass regional distributors to negotiate annual volume contracts with AMCOL and CONDAT technical service teams. This pattern concentrates most visibly in automotive supply chains where OEMs enforce supplier rationalization programs.
Aluminum Extrusion Lubricants Market Segmentation
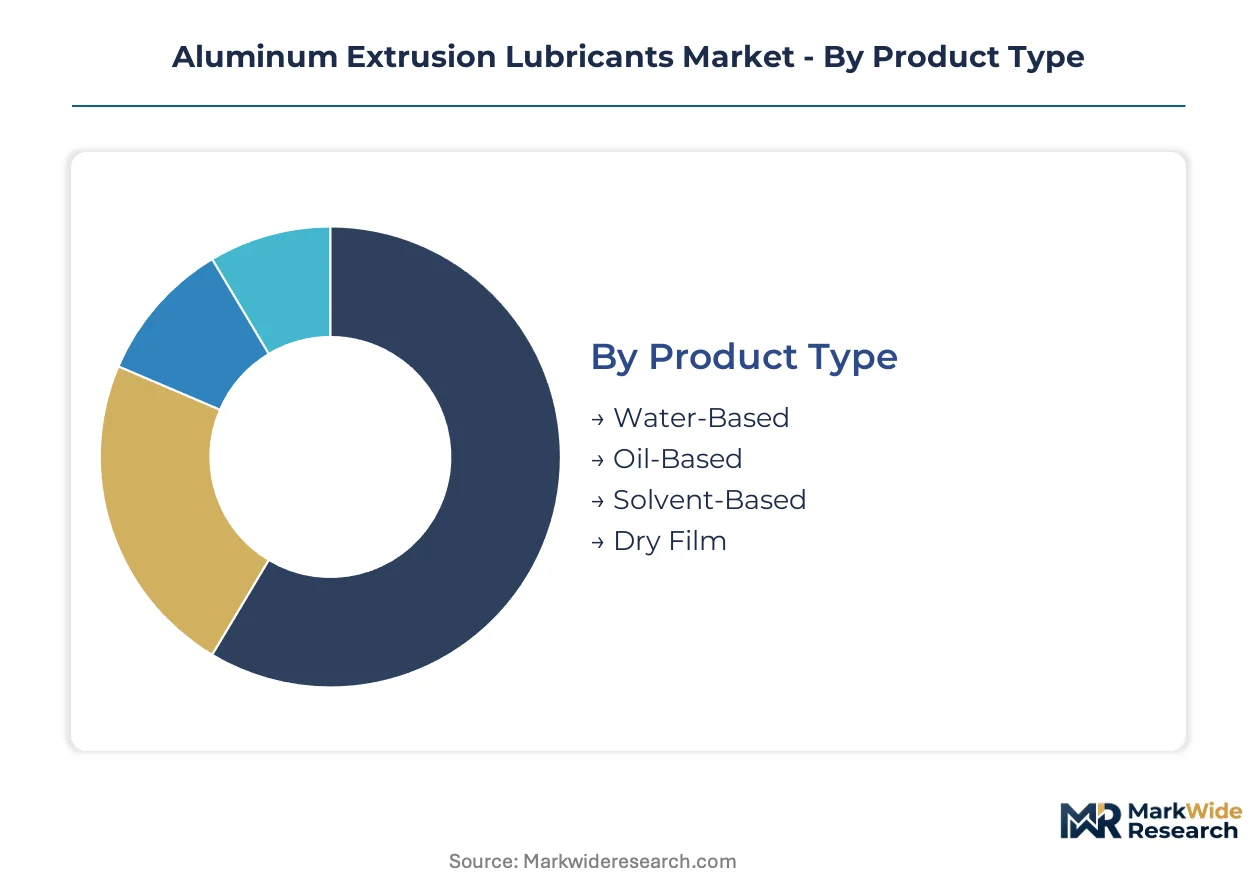
Formulation chemistry and application method dictate procurement specifications across aluminum extrusion facilities. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that suppliers must navigate.
Product Type:
Customization intensity spans from standardized commodity blends to precision-engineered dispersions requiring technical service support.
- Water-Based:Synthetic ester and boron nitride dispersions in aqueous carriers withstand temperatures above 450°C while meeting automotive VOC thresholds. Demand concentrates in Germany's automotive extrusion cluster where OEMs enforce shop-floor emissions limits.
- Oil-Based:Hydrocarbon carriers with chlorinated or sulfurized additive packages dominate legacy press installations. Aerospace supply chains in the US retain these chemistries where equipment conversion costs stall substitution timelines.
- Solvent-Based:Volatile organic compound carriers face accelerating phase-out under REACH Annex XVII and EPA Toxic Substances Control Act enforcement.
- Dry Film:Hexagonal boron nitride coatings command premium positioning for electronics-grade precision extrusion with zero surface contamination tolerance.
Leading the category by volume: Oil-Based. Expanding most quickly: Water-Based.
Application:
Process mechanics determine lubricant selection from high-pressure billet deformation to continuous profile output.
- Billet:Boundary films applied to cast aluminum logs reduce friction coefficients during initial container entry. Automotive suppliers in Japan specify synthetic ester formulations for 6000-series alloy processing.
- Continuous Extrusion:High-pressure metalworking chemistries extend die life in seamless tube and rod production lines. Metalloid Corporation specializes in these demanding tribochemical environments.
- Sheet Metal:Lower-pressure applications accommodate broader formulation latitude with reduced thermal stability requirements.
- Profiles:Architectural and structural extrusions utilize mid-tier aqueous systems where surface finish specifications are less stringent than electronics applications.
Dominant by installed base: Billet. Steepest technology shift: Continuous Extrusion.
End User:
Customer procurement maturity separates specification-driven buyers from price-sensitive commodity purchasers.
- Automotive:Tier 1 suppliers enforce volatile organic compound thresholds that redirect facility procurement toward water-based systems. Germany's lightweighting mandates accelerate validation timelines.
- Aerospace:Legacy oil-based chemistries persist where AS9100 quality systems and equipment amortization schedules resist chemistry conversion. US and French extruders maintain established supply relationships.
- Construction:Price-sensitive procurement accepts standard industrial grades with minimal technical service requirements.
- Electronics:Zero-contamination specifications drive boron nitride dry film adoption in China's Yangtze River Delta cluster.
Highest specification intensity: Electronics. Largest volume anchor: Automotive.
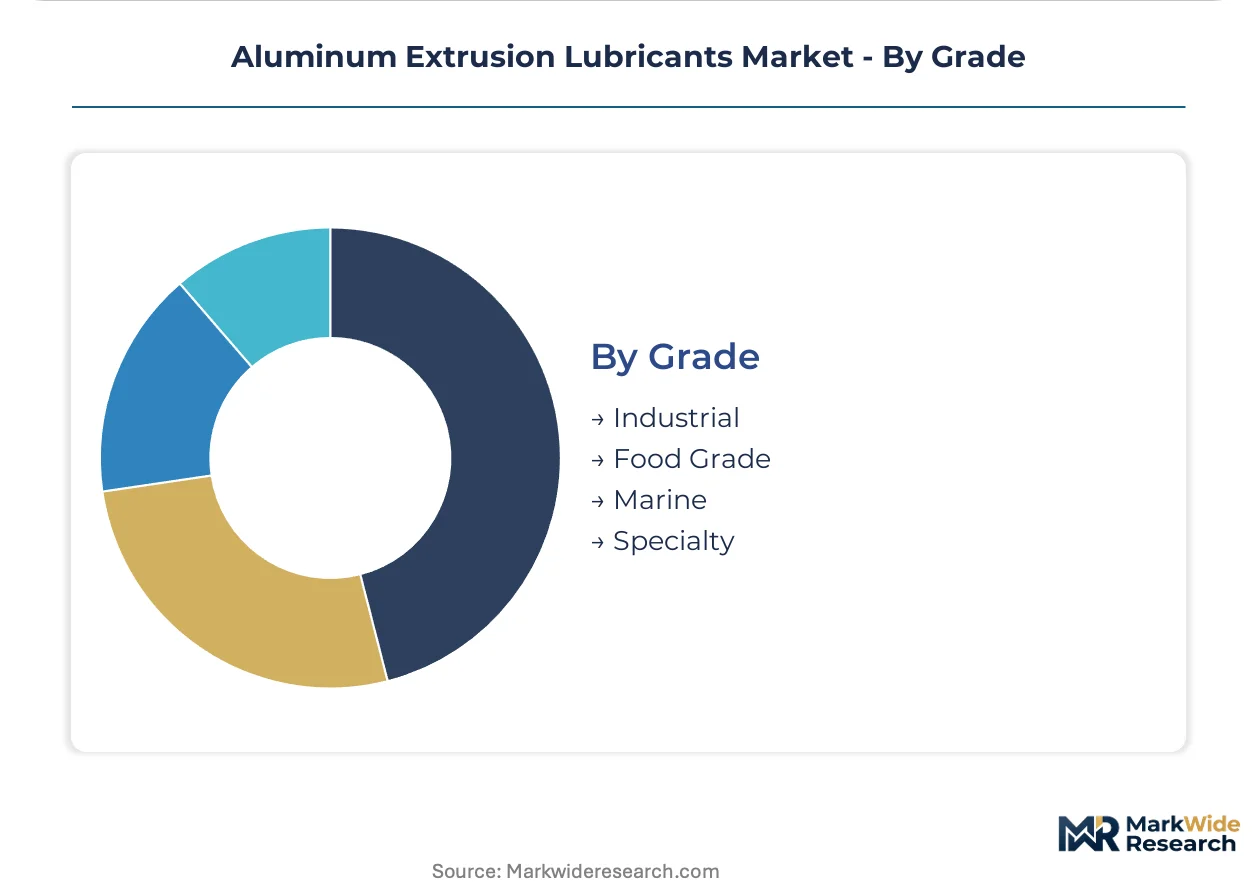
Grade:
Certification tier determines pricing architecture and regulatory compliance burden across formulation portfolios.
- Industrial:Standard metalworking fluid specifications serve general extrusion applications without specialized certifications. Construction and commodity profile producers drive baseline demand.
- Food Grade:NSF H1-registered chemistries serve aluminum extrusion for food processing equipment where incidental contact tolerance applies.
- Marine:Corrosion-resistant formulations address saltwater exposure requirements in offshore and coastal infrastructure applications.
- Specialty:Custom-engineered dispersions with tailored viscosity indices and extreme-pressure additive packages command formulation premiums.
Widest application base: Industrial. Margin expansion focus: Specialty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive lightweighting programs and electronics-grade precision requirements concentrate aluminum extrusion lubricant demand across three distinct manufacturing clusters. Germany's automotive supply chain, China's Yangtze River Delta electronics corridor, and the United States aerospace infrastructure each impose incompatible formulation specifications that fragment regional procurement patterns.
Germany
Tier 1 automotive suppliers enforce volatile organic compound thresholds that redirect facility procurement toward water-based synthetic ester systems. REACH Annex XVII restrictions on short-chain chlorinated paraffins accelerate reformulation timelines across Baden-Württemberg and Bavaria extrusion clusters. Stuttgart's automotive lightweighting engineering centers validate new aqueous chemistries for 6000-series aluminum profile production.
China
Electronics-grade precision extrusion in the Yangtze River Delta demands zero-contamination boron nitride dry film coatings for semiconductor thermal management applications. The Ministry of Ecology and Environment tightens emissions permits for metalworking fluid compounding facilities under dual carbon goals implementation. Jiangsu and Zhejiang provincial enforcement exceeds national baselines, redirecting formulation investments toward low-carbon intensity production.
United States
Legacy aerospace supply chains retain oil-based chlorinated paraffin chemistries where AS9100 quality systems and equipment amortization schedules resist chemistry conversion. EPA Toxic Substances Control Act enforcement creates stranded inventory risk for distributors holding legacy stocks. California and Michigan state-level OSHA permissible exposure limits compress allowable chemistries for sulfurized additives.
Japan
Automotive suppliers specify synthetic ester formulations with tailored viscosity indices for 6000-series alloy processing in continuous extrusion lines. METI industrial standards guide metalworking fluid performance specifications for high-pressure deformation applications. Nagoya's automotive component manufacturing cluster drives validation timelines for aqueous system adoption.
India
PLI scheme incentives for aluminum downstream processing create first-mover positioning opportunities for synthetic ester formulators entering extrusion capacity expansion projects. The Bureau of Indian Standards develops metalworking fluid specifications aligned with automotive export requirements. Gujarat and Maharashtra industrial corridors attract compounding facility investments serving domestic automotive OEMs.
Aluminum Extrusion Lubricants Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation-intensive applications favoring technical service relationships while commodity extrusion accepts distributor-mediated supply. The vendor base organizes around three strategic archetypes: bentonite-derived additive specialists, water-based system formulators with European service networks, and high-pressure metalworking chemistry experts. Competitive dynamics center on reformulation partnerships with billet producers and on-site fluid management contract structures.
Within the specialty additive tier, AMCOL Corporation and Saint-Gobain Boron Nitride occupy positions anchored by mineral-derived and ceramic dispersion expertise respectively. CONDAT sits within the European technical service archetype, while Metalloid Corporation exemplifies high-pressure metalworking chemistry specialization. These three companies represent distinct capability vectors that buyers evaluate against application-specific tribochemical requirements.
| Leading Market Players |
|---|
| AMCOL Corporation |
| Metalloid Corporation |
| CONDAT |
| Sunbelt Lubricants |
| Chem Arrow Corporation |
| Kluber Lubrication |
| OEST Group |
| IKV Lubricants |
| Saint-Gobain Boron Nitride |
| Others |
Value Chain & Pricing Dynamics
Tribochemistry expertise scarcity in Germany's Baden-Württemberg extrusion cluster widens labor-cost differentials between synthetic ester formulation specialists and commodity blenders, compressing mid-tier margins while premium boron nitride coatings capture pricing power.
Pricing Analysis
Volume concentration in oil-based legacy systems splits from margin capture in water-based synthetic ester and dry film boron nitride tiers. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade zero-contamination specifications from automotive VOC-compliant mid-tier and construction-grade commodity blends. Pricing pressure stems from naphtha-derived synthetic ester feedstock volatility squeezing blender profitability. Construction end-users exhibit highest price sensitivity, while electronics buyers accept premium positioning for contamination-free performance.
Supply Chain Analysis
Workforce availability constraints in Germany, China, and the United States shape compounding facility location decisions and technical service deployment. Synthetic ester base stocks, hexagonal boron nitride powder, and bentonite-derived additives constitute critical input dependencies. Single-source vulnerability concentrates in European chlorinated paraffin substitution timelines under REACH Annex XVII. Distribution runs through direct procurement relationships between large extruders and compounder technical service teams, bypassing traditional distributor networks in automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized tribochemistry formulation capacity operates as the binding constraint propping pricing power across premium lubricant tiers, with qualified chemist scarcity in high-pressure metalworking fluid design limiting rapid supply expansion.
For Market Incumbents: Anticipate REACH Annex XVII enforcement accelerating chlorinated paraffin phase-out timelines by securing backward integration into synthetic ester base oil production and anchoring technical service relationships with Yangtze River Delta electronics extruders before competitor entry.
For New Entrants and Emerging Players: India's PLI-scheme aluminum downstream processors represent an underserved buyer archetype with first-mover positioning available for synthetic ester formulators offering on-site fluid management contracts tied to capacity expansion timelines in Gujarat and Maharashtra corridors.
For Investors and Strategic Acquirers: The window for entry favors specialized boron nitride dispersion capability and aqueous system formulation expertise over commodity blending assets, with acquisition signals flashing when ECHA registration deadlines trigger forced divestiture of non-compliant legacy product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Production | AMCOL Corporation's bentonite-derived additive captive supply secures margin control against naphtha volatility. |
| Technical Service Network Expansion | CONDAT's European on-site fluid management contracts capture recurring revenue from automotive lightweighting programs. |
| REACH-Compliant Reformulation Partnership | Metalloid Corporation's high-pressure metalworking chemistry expertise extends die life for continuous extrusion line upgrades. |
| Electronics-Grade Dry Film Coating Scale-Up | Saint-Gobain Boron Nitride's nanosheet dispersion advances penetrate semiconductor thermal management applications. |
| Closed-Loop Aqueous Recycling Contracts | Water-based system providers lock in long-term supply relationships through on-site fluid regeneration infrastructure. |
Study Parameters
Independent corroboration across plant managers at German automotive extrusion facilities, procurement leads at Tier 1 aluminum billet producers, distribution channel partners serving North American aerospace supply chains, and technical R&D directors at synthetic ester compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data tracking lubricant additive imports, European Chemicals Agency REACH registration databases, SEC 10-K filings from specialty chemical manufacturers, and metalworking fluid industry association reports. Bottom-up demand modeling from end-use application volumes and top-down supply-side capacity assessments were cross-referenced for triangulation.
Comparable historical reference periods spanning pre-regulatory enforcement and post-implementation phases anchored the projection framework across the analysis window. Segmentation dimensions modeled include formulation chemistry type, application method, end-user industry procurement maturity, and grade certification tier. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting mandate compliance timelines and electronics-grade precision extrusion capacity expansion. Industry-specific forecast inputs encompass ECHA registration deadline schedules and China's Ministry of Ecology and Environment emissions permit tightening trajectories.
Revisions become necessary when REACH Annex XVII enforcement intensity exceeds baseline assumptions, China's dual carbon goals accelerate provincial emissions permit revocation, or synthetic ester feedstock cost volatility disrupts blender margin structures. Material deviation in named regulatory triggers or petrochemical input cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Power Steering Fluids Market
Lubricants
Neat Cutting Oil Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
North America Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Contact Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Philippines Lubricants Market