
 Tubatoxin Market | 2026-2036
Tubatoxin Market Size, Share, and Industry Trends Forecast 2026-2036
Tubatoxin Market Analysis
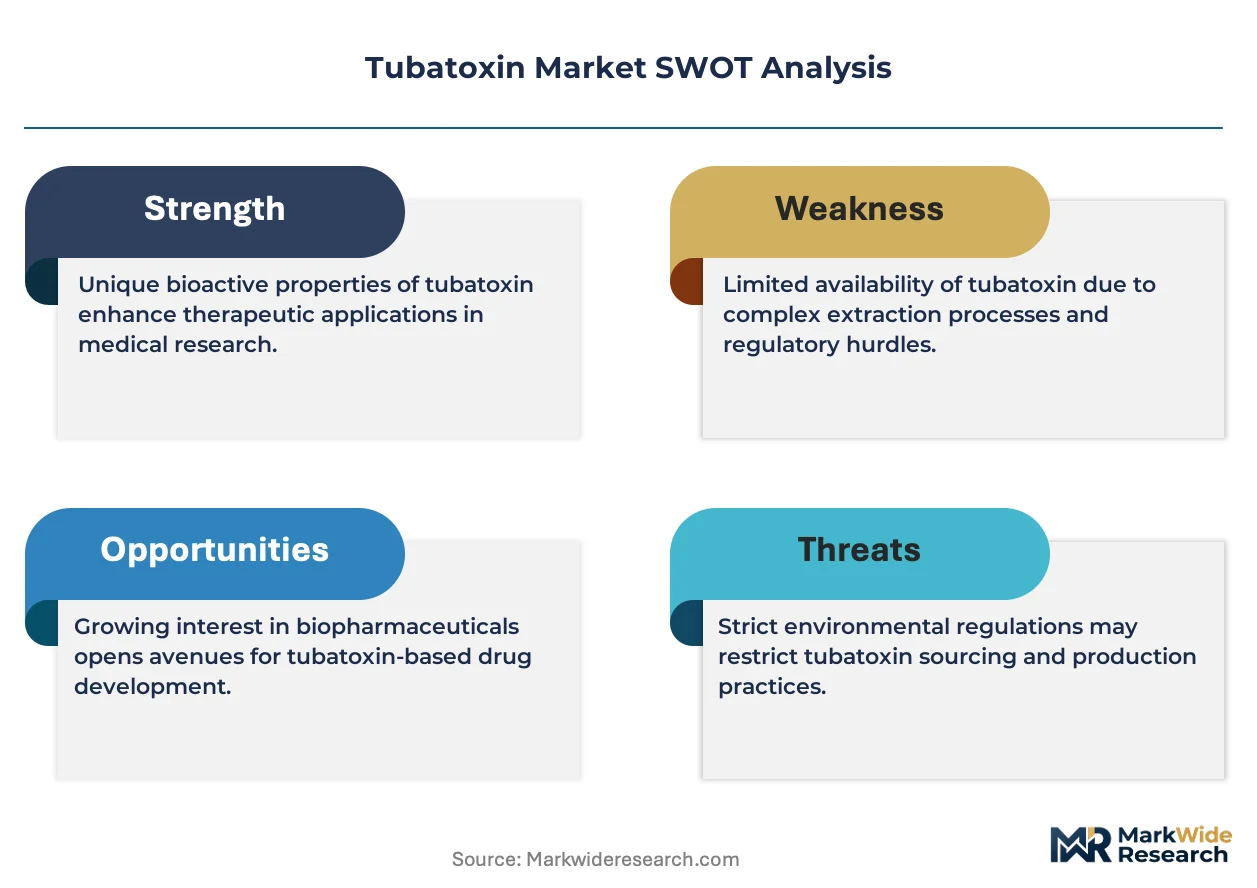
REACH registration requirements for hazardous botanical extracts is rebalancing capital deployment toward certified synthesis infrastructure. Wujiang Shuguang Chemical leverages captive pyrethrum supply chains to sustain cost advantages in raw material procurement. Zhejiang Rayfull Chemicals anchors its position through specialized extraction protocols that meet European import specifications. BASF competes on pharmaceutical-grade certification breadth, extending its regulatory dossier across multiple jurisdictions.
Tubatoxin denotes a naturally occurring neurotoxic compound derived from Derris and Lonchocarpus plant species, characterized by rotenone-class isoflavonoid structures that inhibit mitochondrial electron transport at complex I. Manufacturers employ solvent extraction followed by chromatographic purification to achieve pharmaceutical-grade purity thresholds above 98.5 percent for injectable formulations. Powder formulations dominate current volume due to stability advantages in cold-chain logistics and compounding flexibility for hospital pharmacies. Oncology applications represent the fastest-expanding demand pool as tubatoxin derivatives demonstrate targeted cytotoxicity in preclinical models. Research laboratories sustain premium pricing through small-batch, high-potency procurement for mechanism-of-action studies.
EPA toxicity evaluation frameworks classify tubatoxin under restricted-use pesticide designation, constraining agricultural applications while channeling supply toward pharmaceutical channels. EMA's MDR and FDA's active pharmaceutical ingredient guidance enforce batch-level impurity profiling that shapes manufacturer compliance spending. China's NMPA aligns with ICH Q3D elemental impurity standards, creating convergent quality benchmarks across export destinations. Stakeholders must monitor evolving neurotoxicity thresholds in occupational exposure limits, as regulatory stringency in manufacturing worker safety could reshape production geography.
Market Dynamics
Pharmaceutical-grade purification requirements are compressing the supplier base as REACH and FDA impurity standards force capital-intensive chromatography upgrades across extraction facilities.
Growth Catalysts
- Oncology pipeline expansion:Tubatoxin derivatives demonstrate targeted cytotoxicity in preclinical mitochondrial inhibition studies, pulling demand from research laboratories into formal drug development channels.
- EMA MDR alignment:Batch-level impurity profiling mandates in Europe are channeling supply toward certified manufacturers with established regulatory dossiers.
- Cold-chain stability:Powder formulation dominance in hospital pharmacy compounding sustains volume pull through distribution networks requiring minimal refrigeration infrastructure.
Market Restraints
- Pyrethrum input volatility:Captive supply chain dependence on Derris and Lonchocarpus cultivation concentrates geographic risk in tropical sourcing regions.
- EPA restricted-use designation:Pesticide classification constrains agricultural applications, limiting demand diversification and price floor support.
- Rotenone-class substitution:Synthetic mitochondrial complex I inhibitors from alternative chemical scaffolds threaten displacement in research applications.
Strategic Opportunities
- Neurology indication expansion:Neurodegenerative disease models leveraging tubatoxin's selective neuronal toxicity represent underexplored therapeutic white space.
- China NMPA export certification:ICH Q3D elemental impurity alignment creates convergent quality benchmarks enabling streamlined multi-jurisdiction market access.
- Continuous flow extraction:Chromatographic purification technology convergence with process analytical technology enables real-time quality verification reducing batch failure rates.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA active pharmaceutical ingredient guidance compliance requires 18-24 month validation cycles constraining working capital velocity.
- Occupational neurotoxicity protocols:Evolving manufacturing worker exposure limits in synthesis facilities necessitate ventilation and containment capex without immediate revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubatoxin Market |
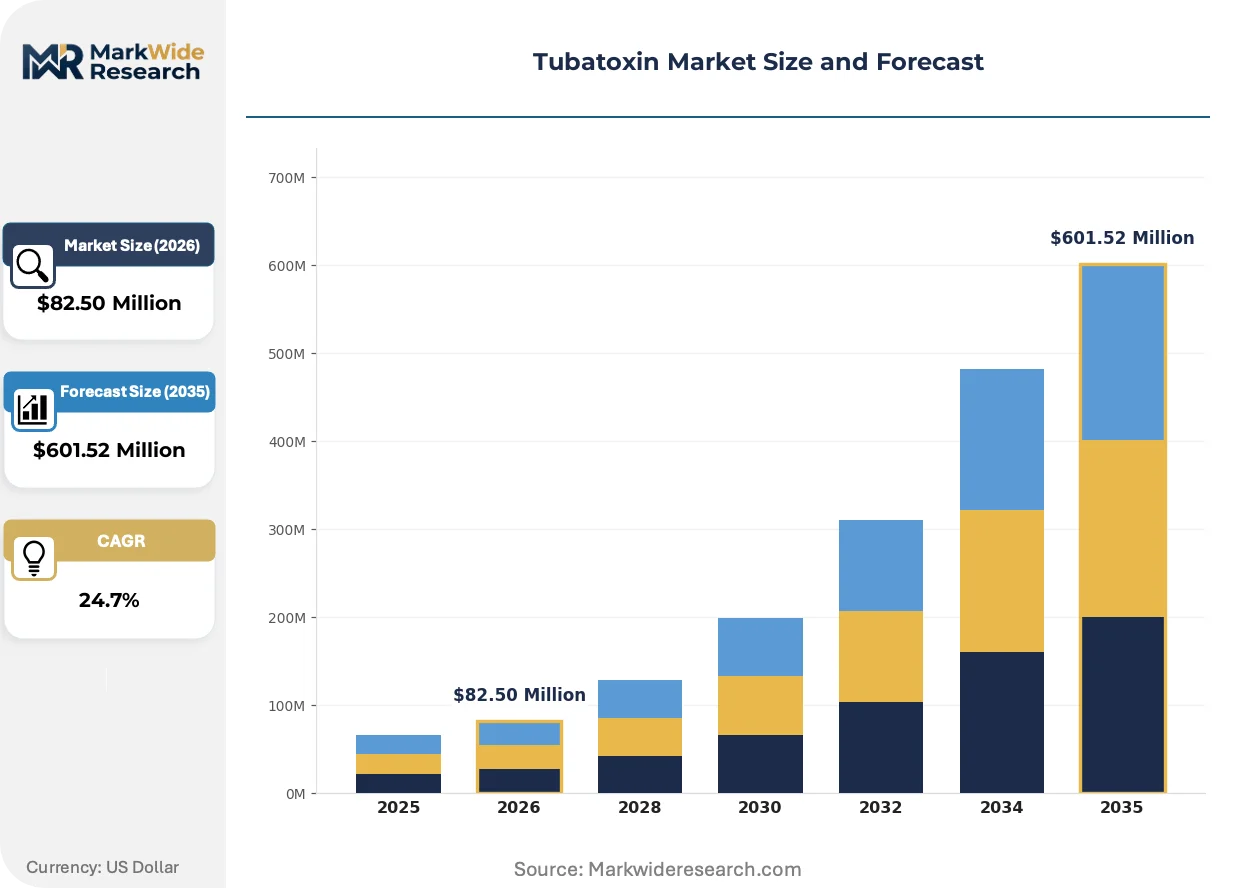
| Market Size in 2026 | $82.50 Million |
| Market Size in 2035 | $601.52 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Oral Solution, Powder, Gel Application: Treatment of Pain, Anesthesia, Neurology, Oncology End User: Hospitals, Clinics, Research Laboratories, Pharmacies Distribution Channel: Direct Sales, Online Pharmacy, Retail, Wholesalers |
| Companies Covered | Wujiang Shuguang Chemical Co. Ltd, Tokyo Chemical Industry Co., Ltd, Xi'an B-Thriving I/E Co., Ltd, Alfa Aesar, Zhejiang Rayfull Chemicals Co., Ltd, Ecompal SAC, BASF, Shandong Qiaochang Chemical, Shanghai Xinglu Chemical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubatoxin Market Emerging Trajectories
Modular purification architectures and convergent regulatory standards are compressing the gap between botanical extraction and pharmaceutical manufacturing, reshaping how suppliers validate quality and scale production.
Continuous chromatographic purification systems are modularizing production workflows across tubatoxin extraction facilities. Mid-scale pharmaceutical ingredient manufacturers adopt skid-mounted separation units to bypass fixed-asset commitment. This modularization enables capacity scaling in 12-month increments rather than 36-month facility construction cycles.
REACH registration requirements for hazardous botanical extracts are tightening purity verification protocols. ECHA substance evaluation deadlines force manufacturers to submit analytical method validation data for rotenone-class isoflavonoid quantification. European import specifications now require third-party certification of complex I inhibition potency, affecting suppliers without established European testing partnerships.
Research laboratory procurement is consolidating toward pre-qualified vendor lists with documented chain-of-custody protocols. Small-batch high-potency orders increasingly route through specialized chemical distributors rather than direct manufacturer relationships. This channel shift concentrates in North American academic medical centers where institutional review boards mandate supplier audit documentation.
Tubatoxin Market Segmentation
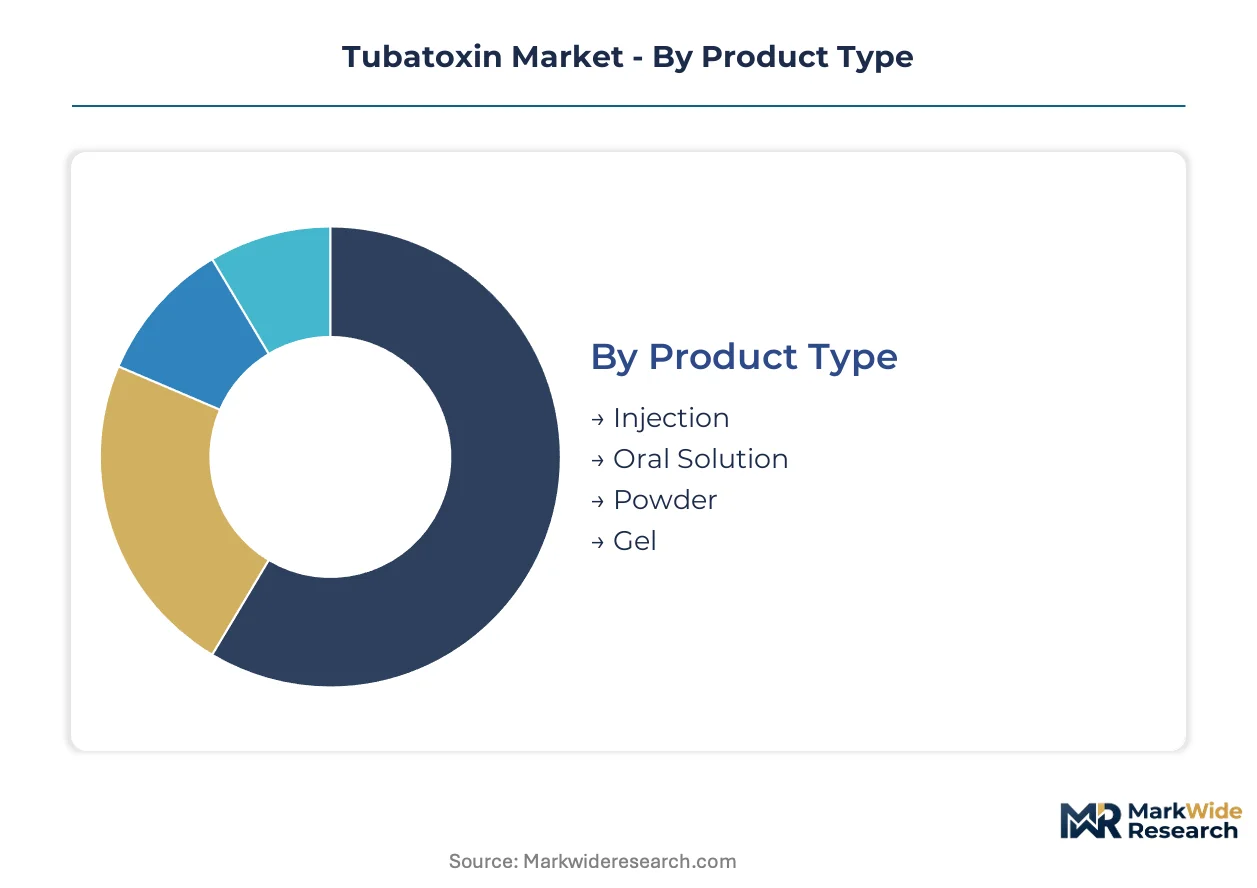
Tubatoxin formulation requirements diverge sharply across clinical settings, with oncology injectables demanding 98.5 percent purity thresholds while research laboratories prioritize batch-to-batch consistency over absolute potency. Understanding these segment-specific technical specifications enables manufacturers to align purification investments with revenue concentration points.
Product Type:
Hospital pharmacy procurement teams weight cold-chain logistics burden against compounding flexibility when selecting formulation formats.
- Powder:Lyophilized formulations achieve 24-month stability at controlled room temperature, eliminating refrigeration infrastructure requirements. Hospital pharmacies in India and Brazil concentrate procurement here due to unreliable cold-chain networks and compounding flexibility for individualized dosing.
- Injection:Sterile parenteral solutions require endotoxin testing below 0.25 EU/mL and compel manufacturers to maintain dedicated aseptic filling lines. Oncology departments at academic medical centers in the United States and Germany drive demand for this highest-certification tier.
- Oral Solution:Liquid formulations suit pediatric and geriatric populations where swallowing solid dosage forms presents compliance barriers.
- Gel:Topical delivery systems localize tubatoxin exposure for dermatological research applications and targeted pain management protocols.
Volume sits with Powder; growth tilts toward Injection.
Application:
Regulatory designation intensity varies across therapeutic areas, with oncology facing the steepest FDA active pharmaceutical ingredient validation requirements.
- Oncology:Mitochondrial complex I inhibition demonstrates selective cytotoxicity in preclinical tumor models. Pharmaceutical sponsors in Massachusetts and Basel advance tubatoxin derivatives through formal IND-enabling studies, pulling supply toward GMP-certified manufacturers with established Type II DMF filings.
- Neurology:Parkinson's disease research models leverage rotenone-class neurotoxicity to induce dopaminergic neuronal loss. Academic laboratories at University College London and Stanford University sustain premium pricing for mechanism-of-action studies requiring documented chain-of-custody protocols.
- Anesthesia:Local anesthetic adjunct applications exploit tubatoxin's sodium channel modulation properties in regional block procedures.
- Treatment of Pain:Chronic pain management protocols incorporate tubatoxin as an opioid-sparing alternative in multimodal analgesia regimens.
Revenue concentrates in Oncology; Neurology climbs the fastest.
End User:
Procurement sophistication tiers separate institutional buyers with dedicated quality assurance staff from smaller clinical operators.
- Research Laboratories:Small-batch high-potency orders require COA documentation with HPLC purity traces and NMR structural confirmation. North American academic medical centers increasingly mandate supplier audit documentation through institutional review board protocols.
- Hospitals:Integrated delivery networks negotiate formulary contracts based on total cost of ownership including compounding labor and waste reduction.
- Clinics:Outpatient settings prioritize single-dose packaging and simplified reconstitution procedures to minimize medication errors.
- Pharmacies:Community and specialty pharmacies serve as last-mile distributors for patient-specific prescriptions and investigator-initiated trials.
Research Laboratories command premium pricing; Hospitals drive procurement consolidation.
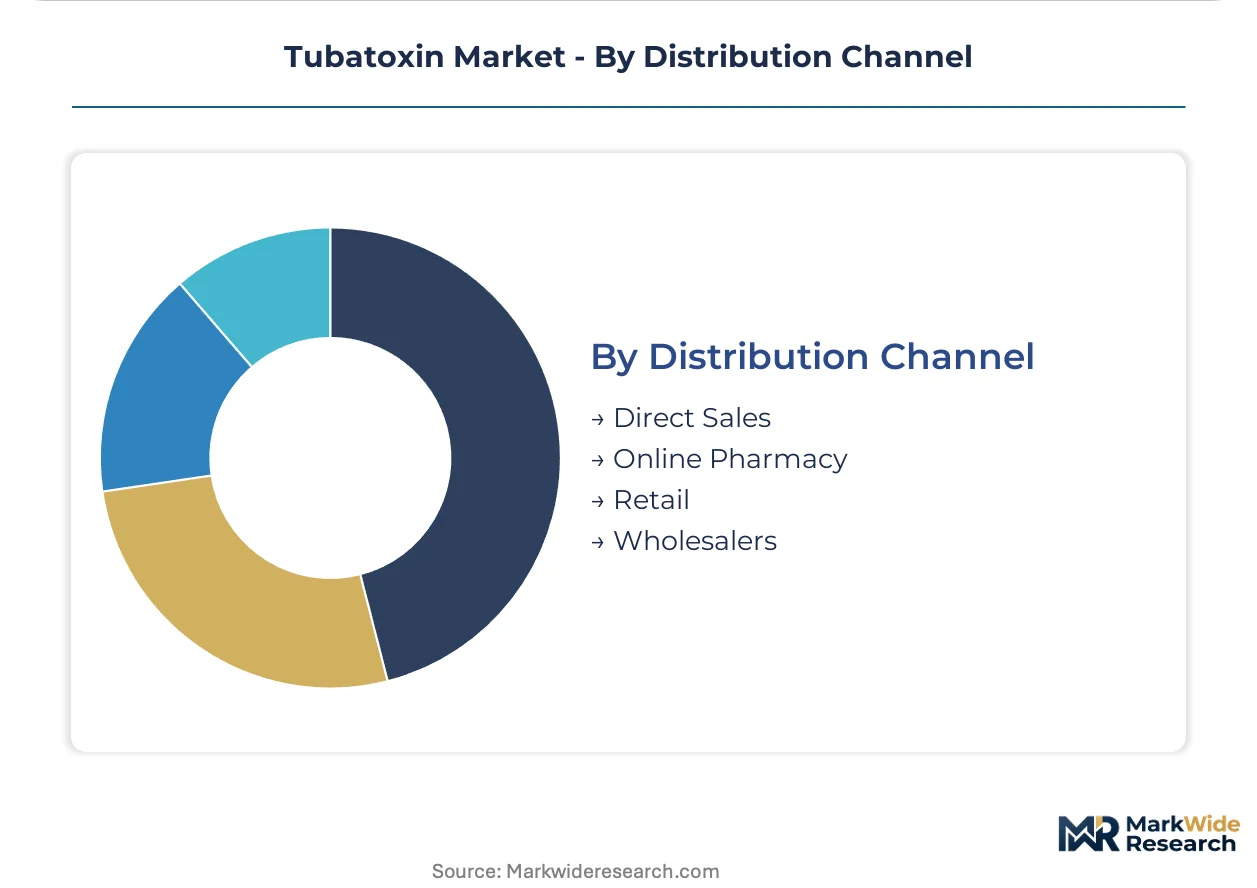
Distribution Channel:
Channel selection reflects buyer scale and regulatory documentation requirements rather than pure cost optimization.
- Direct Sales:Pharmaceutical manufacturers and contract research organizations negotiate master service agreements with tubatoxin suppliers for multi-year supply security. These relationships bypass distributor markups while imposing batch-level impurity profiling obligations on producers.
- Wholesalers:McKesson and AmerisourceBergen handle hospital system aggregation in the United States, leveraging existing cold-chain infrastructure for temperature-sensitive biologics.
- Online Pharmacy:E-commerce platforms serve research chemical procurement for smaller academic laboratories without established vendor relationships.
- Retail:Brick-and-mortar pharmacy chains participate marginally, primarily through specialty pharmacy subsidiaries focused on oncology supportive care.
Direct Sales capture pharmaceutical-grade volume; Wholesalers sustain hospital network penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu and Zhejiang provinces concentrate tubatoxin manufacturing capacity through preferential tax treatment and streamlined environmental permitting. These zones anchor raw material procurement networks extending into tropical cultivation regions.
China
Pharmaceutical-grade tubatoxin production clusters in Suzhou and Hangzhou industrial parks serve export markets through NMPA-certified facilities aligned with ICH Q3D standards. The dual carbon goals policy pressures solvent-intensive extraction operations toward energy-efficient process redesigns. Wujiang Shuguang Chemical and Zhejiang Rayfull Chemicals anchor regional supply chains with captive pyrethrum sourcing arrangements.
United States
Academic medical centers in Massachusetts and California drive research-grade procurement through institutional review board-mandated vendor qualification protocols. EPA restricted-use pesticide classification channels commercial supply toward pharmaceutical applications exclusively. FDA active pharmaceutical ingredient guidance enforces 18-24 month validation cycles that favor established manufacturers with Type II DMF filings.
Germany
EMA MDR batch-level impurity profiling requirements concentrate demand on certified suppliers with established European testing partnerships. REACH registration deadlines for hazardous botanical extracts force analytical method validation submissions to ECHA. BASF leverages its Ludwigshafen headquarters to maintain regulatory dossier breadth across multiple jurisdictions.
Japan
PMDA pharmaceutical-grade certification requirements sustain premium pricing for mitochondrial research applications at University of Tokyo and Kyoto University laboratories. METI industrial policy supports continuous flow extraction technology adoption through subsidized process analytical technology implementation. Tokyo Chemical Industry Co., Ltd. occupies a central position in research chemical distribution networks.
India
Hospital pharmacy compounding demand concentrates in Maharashtra and Karnataka states where cold-chain infrastructure limitations favor powder formulation procurement. CDSCO alignment with ICH Q3D standards enables streamlined export certification for European and North American markets. Domestic manufacturers invest in chromatographic purification upgrades to meet emerging impurity profiling mandates.
Tubatoxin Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated supply structure. Pharmaceutical-grade segments consolidate around manufacturers with multi-jurisdiction regulatory dossiers, while research-grade procurement fragments across regional distributors. Three archetypes dominate: integrated chemical conglomerates with broad certification portfolios, mid-scale specialists with geographic captive supply advantages, and research chemical distributors with institutional procurement relationships. Competitive moves center on chromatography capacity expansion and strategic partnerships with academic medical centers for vendor list pre-qualification.
Among Chinese manufacturers, Wujiang Shuguang Chemical Co. Ltd and Zhejiang Rayfull Chemicals Co., Ltd exemplify the mid-scale specialist archetype with regional supply chain integration. BASF represents the diversified conglomerate tier with pharmaceutical-grade certification breadth spanning European, North American, and Asian regulatory frameworks. These three anchors illustrate the competitive tension between geographic specialization and global regulatory coverage that shapes procurement decisions at research laboratories and pharmaceutical sponsors.
| Leading Market Players |
|---|
| Wujiang Shuguang Chemical Co. Ltd |
| Tokyo Chemical Industry Co., Ltd |
| Xi'an B-Thriving I/E Co., Ltd |
| Alfa Aesar |
| Zhejiang Rayfull Chemicals Co., Ltd |
| Ecompal SAC |
| BASF |
| Shandong Qiaochang Chemical |
| Shanghai Xinglu Chemical Technology |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-scale specialists in China's Jiangsu and Zhejiang provinces anchor supply-side discipline through captive pyrethrum cultivation networks, translating upstream control into pricing power over spot-market dependent competitors. Their multi-generational capital structures resist quarterly margin pressure, enabling patient investment in chromatographic purification capacity that certified buyers now require.
Pricing Analysis
Short lead-time premiums command 15-30 percent markups over standard delivery windows as pharmaceutical sponsors accelerate IND-enabling timelines. Contract-based long-term offtake agreements dominate GMP-certified tier procurement, while spot transactions concentrate in research-grade segments where batch-to-batch consistency matters less than immediate availability. Price differentiation hinges on FDA Type II DMF filing status and REACH registration completeness. Cost compression in standard-grade powder formulations is intensifying because Indian and Brazilian hospital pharmacies are consolidating procurement through integrated delivery networks. Research laboratories exhibit lowest price sensitivity due to institutional review board-mandated vendor qualification costs that dwarf per-gram differentials.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical sponsors in Massachusetts and Basel force buyers to qualify at least two GMP-certified manufacturers per tubatoxin derivative, fragmenting volume across Wujiang Shuguang Chemical, Zhejiang Rayfull Chemicals, and BASF's Ludwigshafen complex. Raw material dependence draws from Derris elliptica cultivation in Indonesia, Lonchocarpus utilis in Peru, and pyrethrum extraction byproducts in Kenya. Single-source vulnerability concentrates in tropical sourcing regions where climate volatility and land-use competition threaten cultivation consistency. Distribution runs through specialized chemical distributors for research-grade orders, while direct manufacturer relationships handle pharmaceutical-grade volume with dedicated aseptic filling line access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tubatoxin market is becoming a vertical-integration race as manufacturers pursue captive cultivation control to secure pyrethrum supply against input volatility and regulatory purity escalation.
For Market Incumbents: Hedge against rotenone-class synthetic displacement by deepening mitochondrial complex I inhibitor R&D partnerships with academic medical centers at Stanford and University College London. Secure backward integration into Indonesian and Peruvian cultivation zones before land-use competition from palm oil and soy tightens raw material access. FDA active pharmaceutical ingredient guidance compliance timelines represent the critical margin pressure point requiring working capital reserves. For New Entrants and Emerging Players: Enter via neurology indication white space where Parkinson's disease research models lack established supplier relationships and institutional review board protocols remain less stringent than oncology channels. Target Indian hospital pharmacy compounding demand where cold-chain infrastructure limitations favor powder formulation procurement and CDSCO alignment with ICH Q3D standards enables streamlined export certification. A specialized chemical distributor partnership with documented chain-of-custody protocols offers the fastest go-to-market path. For Investors and Strategic Acquirers: NMPA export certification announcements from mid-scale Chinese manufacturers are the leading indicator that multi-jurisdiction regulatory dossier breadth is achievable without BASF-scale infrastructure investment. Five-to-ten year viability hinges on continuous flow extraction technology adoption subsidized through Japan's METI industrial policy. Acquisition targets should display skid-mounted chromatographic purification capacity and pre-qualified vendor status at North American academic medical centers. Deviation in EPA neurotoxicity threshold revisions would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Extraction Adoption | Real-time quality verification through process analytical technology reduces batch failure rates at NMPA-certified facilities. |
| Captive Cultivation Integration | Upstream control over Derris and Lonchocarpus sourcing insulates against pyrethrum input volatility in tropical regions. |
| Multi-Jurisdiction Dossier Expansion | REACH, FDA, and ICH Q3D alignment enables streamlined market access across European, North American, and Asian regulatory clusters. |
| Academic Medical Center Partnership | Institutional review board pre-qualification secures premium research-grade procurement with documented chain-of-custody protocols. |
| Modular Purification Capacity Scaling | Skid-mounted chromatographic units bypass 36-month facility construction cycles for 12-month capacity increments. |
Methodological Framework
Document review covered FDA Type II DMF filings, EMA MDR batch-level impurity profiling submissions, and NMPA ICH Q3D alignment certifications, complemented by interviews with pharmaceutical manufacturing executives, regulatory affairs leads at GMP-certified facilities, hospital pharmacy procurement managers, and research chemical distribution channel partners. Secondary validation drew from customs trade data, SEC 10-K disclosures from diversified chemical conglomerates, and ECHA substance evaluation deadlines for hazardous botanical extracts. Bottom-up tubatoxin derivative demand modeling and top-down pharmaceutical-grade purification capacity assessment were triangulated against primary field intelligence.
Segmented outputs across the projection horizon reflect formulation type, therapeutic application, end-user procurement sophistication tier, and distribution channel structure. Analytical framework incorporated oncology pipeline advancement rates, neurology research funding trajectories, and cold-chain infrastructure development patterns by regional cluster. CAGRs were derived from regression analysis of historical pharmaceutical-grade certification timelines and projected research laboratory budget allocations. Forecast inputs included EPA restricted-use pesticide classification enforcement intensity and EMA MDR implementation pace across European import specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA neurotoxicity threshold revisions or sudden pyrethrum cultivation disruption in Indonesia and Peru. Deviation in China dual carbon goals policy enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Marine Hyaluronic Acid Market