
 Asia-Pacific UV Stabilizers Market | 2026-2036
Asia-Pacific UV Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific UV Stabilizers Market Outlook
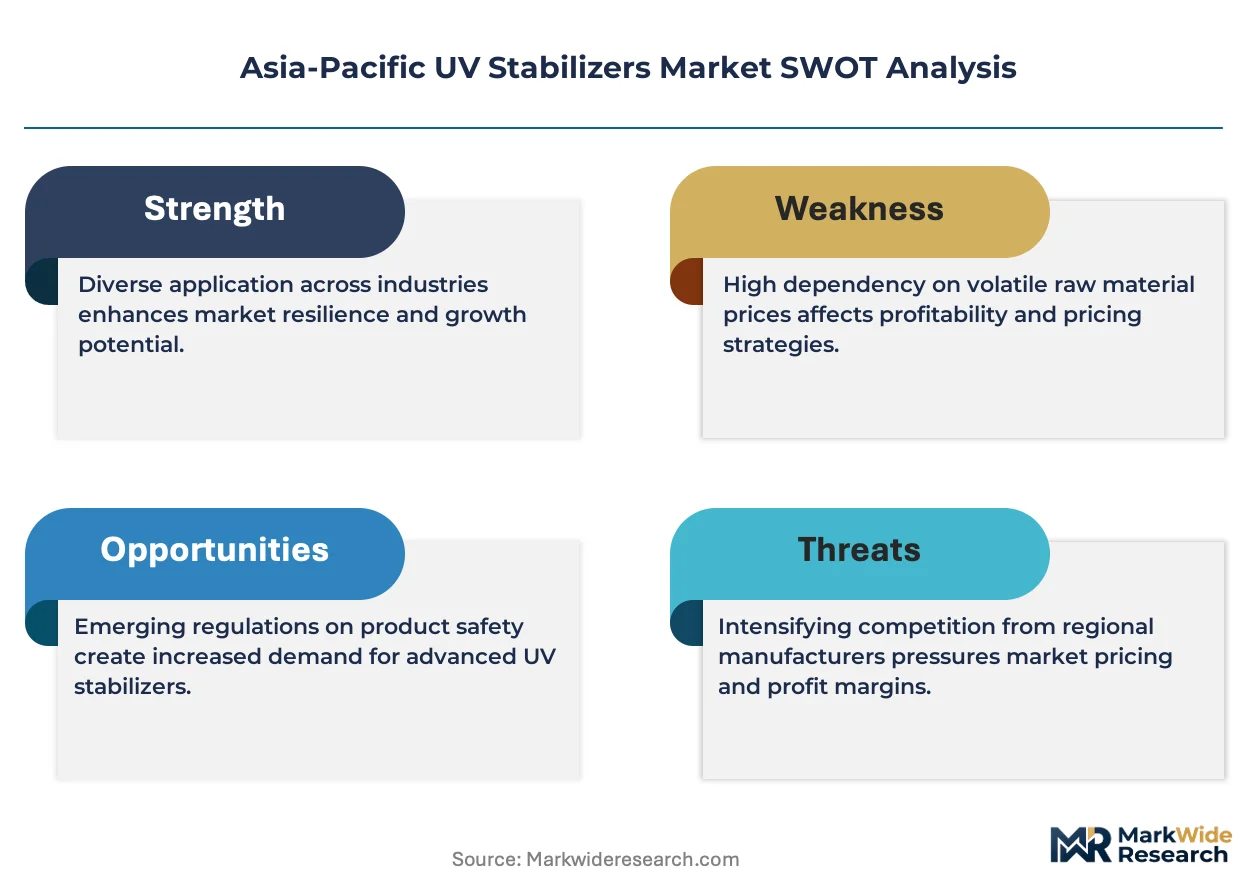
Capital-intensity divergence between integrated polymer additive producers and specialty chemical formulators is rotating competitive advantage toward backward-integrated manufacturers with captive hindered amine precursor supply. BASF SE leverages its Ludwigshafen-derived monomer base to sustain margin capture across the full stabilizer value chain. Rianlon Corporation anchors its position through Tianjin-based antioxidant-stabilizer integration, while SONGWON Industrial Co., Ltd. competes via dedicated light stabilizer R&D in South Korea.
UV stabilizers comprise organic molecules—predominantly hindered amine light stabilizers and benzotriazole derivatives—that interrupt photo-oxidative degradation pathways in polymers by scavenging free radicals or absorbing ultraviolet radiation in the 290–400 nm range. Their primary purpose extends service life of plastics, coatings, and textiles exposed to solar irradiance. Hindered amine light stabilizers dominate volume demand due to polyolefin film protection requirements, while benzotriazole stabilizers command premium positioning in automotive clearcoats where color retention standards are stringent. Liquid concentrates gain traction in automated dosing systems, though powder forms retain cost advantages in commodity compounding operations across China and India.
China's SAMR enforces GB standards governing additive migration limits in food-contact plastics, while Japan's METI oversees chemical substance screening under CSCL-aligned frameworks; both regulators elevate formulation transparency requirements for UV stabilizer suppliers. India's BIS certification mandates for polymer building products create additional compliance layers for imported additive packages. Buyers must monitor regulatory divergence between national chemical registries, as registration cost asymmetries favor domestic producers in China and compound market access complexity for regional formulators serving multi-country supply chains.
Market Dynamics
Backward integration into hindered amine monomer production is rotating competitive advantage toward polymer producers with captive precursor supply, compressing margins for standalone stabilizer formulators across East Asian automotive coating clusters.
Growth Catalysts
- China's GB standards on additive migration:SAMR-enforced limits in food-contact plastics are accelerating reformulation cycles among domestic compounders, creating pull for compliant UV stabilizer packages.
- Greenhouse film replacement cycles:Agricultural plastics in Shandong and Maharashtra require annual stabilizer replenishment, generating recurring volume demand for hindered amine light stabilizers.
- Automotive clearcoat specifications:Japanese OEM color retention standards are tightening benzotriazole specification requirements across Tier-1 coating suppliers in Aichi and Gyeonggi provinces.
Market Restraints
- Feedstock concentration in C4-C6 olefin supply:Hindered amine precursor availability clusters with Northeast Asian petrochemical complexes, exposing formulators to naphtha-cracker output volatility.
- REACH-equivalent registration asymmetries:China's MEE chemical substance inventory imposes disproportionate compliance burdens on imported additive packages versus domestic producers.
- Photocatalytic TiO2 substitution in packaging:Inorganic UV blockers are capturing share in opaque agricultural films where color stability requirements are secondary to cost minimization.
Strategic Opportunities
- India's BIS polymer building certification:Mandatory additive disclosure for construction-grade plastics creates first-mover advantage for pre-certified stabilizer suppliers in Gujarat and Maharashtra.
- Automated liquid dosing systems:Extrusion lines in Vietnam and Indonesia are converting from powder batching to metered concentrate injection, opening technical service partnerships.
- Japan's CSCL-aligned substance screening:METI's priority assessment list is accelerating demand for full formulation transparency from automotive coating formulators.
Industry Challenges
- Photochemistry specialization scarcity:Free-radical mechanism expertise required for stabilizer-application matching remains concentrated among senior formulators in South Korea and Japan.
- Multi-registry synchronization:Suppliers serving China-India-ASEAN supply chains must maintain parallel compliance documentation under divergent national chemical inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific UV Stabilizers Market |
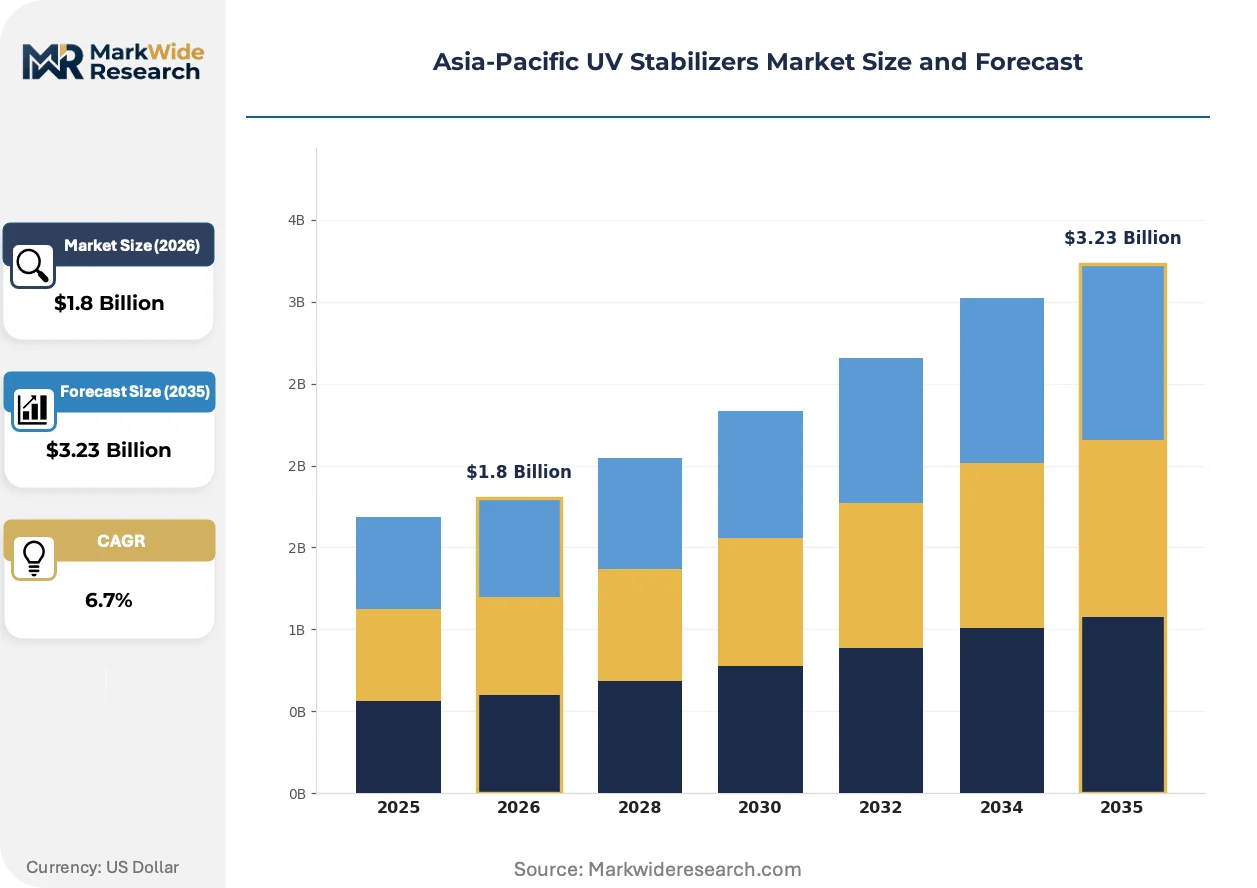
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Amine Light Stabilizers, Benzotriazole Stabilizers, UV Absorbers, Others End Use Industry: Plastics, Coatings, Textiles, Adhesives Form: Powders, Liquids, Granules, Concentrates Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BASF SE, Rianlon Corporation, Suqian Unitech Corp., Ltd., SONGWON Industrial Co., Ltd., ADEKA Corporation, Clariant AG, Everlight Chemical Industrial Corporation, SABO S.p.A., Baoding Lucky Chemical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific UV Stabilizers Market Strategic Shifts
Reactive UV stabilizers with polymer-bound functionality are disrupting conventional additive leaching models, while regulatory pressure on migration limits accelerates molecular architecture innovation across Asia-Pacific formulators.
Polymeric hindered amine light stabilizers with covalent backbone attachment are decomposing the traditional trade-off between stabilizer permanence and processing compatibility. Japanese automotive coating formulators in Kansai and Chubu regions are specifying these grades for 10-year weathering warranties. The technology is decomposing volume-based pricing models as performance-per-dose metrics replace kilogram contracting.
China's SAMR GB standards on additive migration in food-contact plastics are forcing reformulation of legacy benzotriazole packages toward higher molecular weight derivatives. Domestic compounders in Zhejiang and Guangdong are accelerating qualification timelines to avoid import substitution penalties. Agricultural film producers face the steepest compliance gradients due to high surface-area-to-volume ratios in greenhouse applications.
Specification consolidation among ASEAN packaging converters is compressing supplier rosters from multi-source to dual-source contracting. Vietnamese and Thai extrusion houses are consolidating procurement through regional master distributor agreements rather than direct mill relationships. This pattern is most visible in Ho Chi Minh City and Bangkok corridor operations serving export-oriented horticultural film demand.
Asia-Pacific UV Stabilizers Market Segmentation
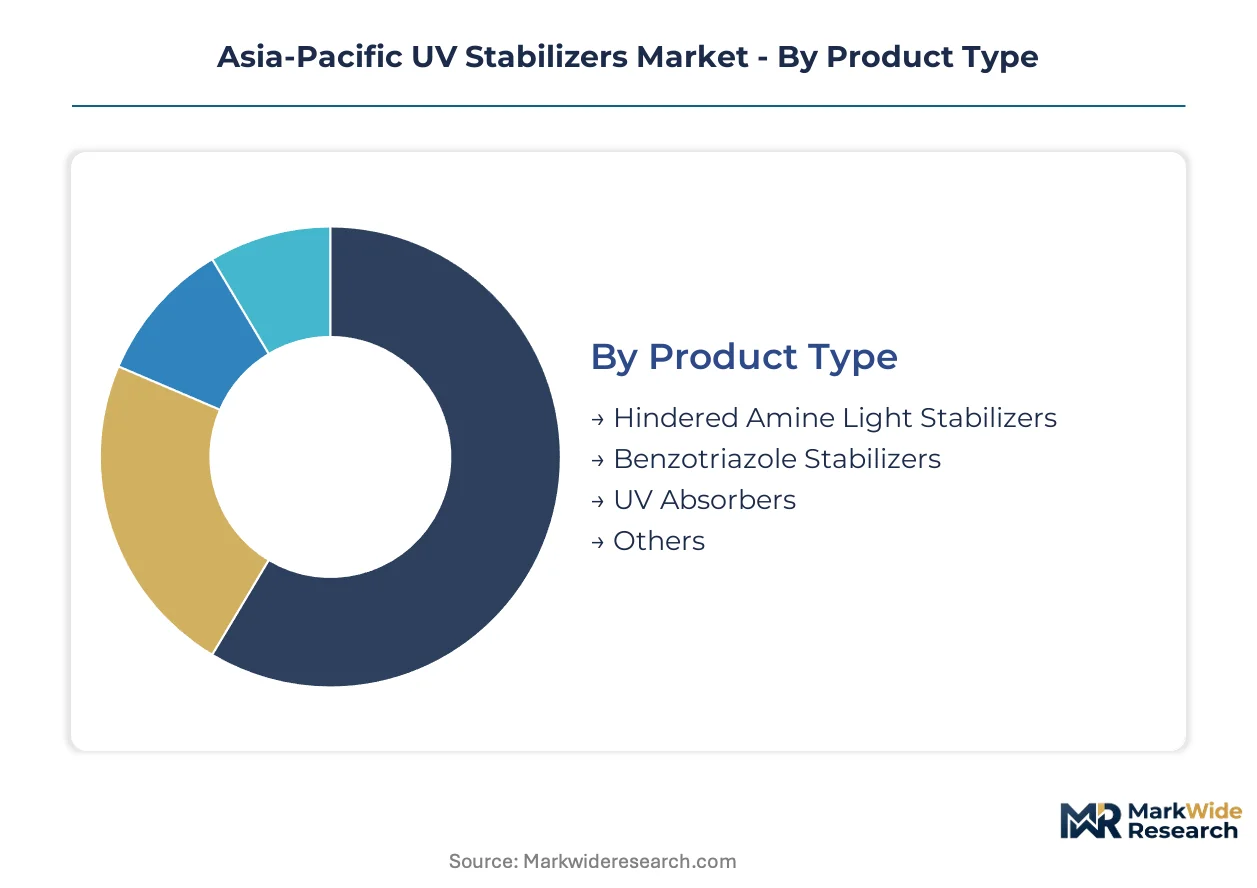
UV stabilizer segmentation across the Asia-Pacific region reflects divergent compliance burdens under China's GB standards, Japan's METI frameworks, and India's BIS mandates. Formulators must architect product portfolios that navigate these regulatory fault lines while serving distinct end-use performance requirements.
Product Type:
China's SAMR enforces differential migration limits that favor higher molecular weight architectures, while Japan's automotive coating specifications privilege benzotriazole derivatives with superior color retention profiles.
- Hindered Amine Light Stabilizers:These cyclic amine compounds scavenge free radicals through a regenerative mechanism that sustains polyolefin protection over extended UV exposure cycles. Demand concentrates in Shandong and Maharashtra agricultural film corridors where annual greenhouse plastic replacement generates recurring volume. China's GB 31604.30 standard on additive migration in food-contact applications is accelerating qualification of polymeric HALS grades among Zhejiang compounders.
- Benzotriazole Stabilizers:These aromatic heterocycles absorb ultraviolet radiation in the 290-350 nm range through intramolecular proton transfer, delivering color stability critical to automotive clearcoat specifications. Japanese OEM requirements in Aichi and Gyeonggi provinces are tightening specification tolerances for 10-year weathering warranties. METI's substance screening protocols under CSCL-aligned frameworks are forcing disclosure of residual monomer content in coating formulations.
- UV Absorbers:Benzophenone and triazine derivatives compete on cost in commodity packaging applications across Vietnam and Indonesia.
- Others:Nickel quenchers and hindered phenol synergists serve niche textile and adhesive stabilization requirements in South Korea and Taiwan.
Established volume favors hindered amine light stabilizers; emerging adoption favors benzotriazole derivatives as automotive coating specifications tighten.
End Use Industry:
Cost tier differentiation separates commodity polyolefin protection from premium coating specifications, with regulatory intensity scaling from agricultural films through automotive clearcoats.
- Plastics:Polyolefin films, injection-molded components, and extruded profiles constitute the dominant consumption base across China and India. Agricultural greenhouse applications in Shandong and Maharashtra drive hindered amine replenishment cycles with annual stabilizer dosing requirements. BIS certification for polymer building products in Gujarat and Maharashtra is creating compliance premiums for pre-qualified additive packages.
- Coatings:Automotive OEM clearcoats, industrial maintenance finishes, and wood coatings demand benzotriazole and triazine absorbers with stringent color retention metrics. Japanese formulators in Kansai and Chubu regions are specifying reactive stabilizer grades for 10-year weathering performance. METI's priority assessment list is accelerating full formulation disclosure requirements among Tier-1 suppliers.
- Textiles:Synthetic fiber stabilization for outdoor fabrics and automotive interiors relies on benzotriazole derivatives with low volatility profiles.
- Adhesives:Pressure-sensitive and structural adhesive formulations require UV protection for transparent bonding applications in electronics assembly across South Korea and Taiwan.
Volume concentration sits with plastics; margin expansion concentrates in coatings as automotive specifications escalate.
Form:
Customer type segmentation separates automated extrusion operations from batch compounding facilities, with dosing technology driving form selection across ASEAN packaging corridors.
- Powders:Free-flowing crystalline stabilizers retain cost advantages in commodity compounding operations across China and India where manual batching persists. High surface-area-to-volume ratios in agricultural films favor powder dispersion efficiency. Zhejiang and Guangdong compounders maintain powder-dominant procurement for legacy extrusion assets.
- Liquids:Metered concentrate injection systems are converting extrusion lines in Vietnam and Indonesia from powder batching to automated dosing. Technical service partnerships with equipment suppliers are opening specification control for formulators with liquid formulation expertise. Ho Chi Minh City and Bangkok corridor operations serving export horticultural film demand are leading this transition.
- Granules:Dust-free handling characteristics serve medium-volume compounders in Thailand and Malaysia with semi-automated feeding systems.
- Concentrates:High-loading masterbatches enable precise dosing control for multi-layer film structures in Japanese and South Korean packaging operations.
Processing legacy favors powders; automation investment favors liquids as ASEAN extrusion capacity modernizes.
Distribution Channel:
Supply concentration patterns favor direct mill relationships for volume accounts while specification complexity drives distributor intermediation for mid-tier compounders.
- Direct Sales:Integrated polymer producers and Tier-1 coating formulators in China, Japan, and South Korea negotiate direct supply agreements with captive technical service support. BASF SE and Rianlon Corporation maintain direct channels for automotive coating specifications requiring formulation co-development. Annual contracting volumes in East Asian automotive clusters justify dedicated account engineering resources.
- Distributors:Regional master distributor agreements are consolidating procurement for Vietnamese and Thai extrusion houses previously sourcing through multi-source mill relationships. Specification consolidation among ASEAN packaging converters is compressing supplier rosters and elevating distributor technical capabilities. Bangkok and Ho Chi Minh City distribution hubs are capturing specification influence in horticultural film supply chains.
- Online Sales:Digital procurement platforms serve small-batch compounders and research-scale buyers in India and Southeast Asia with standardized product grades.
- Retail:Limited counter sales support maintenance and repair coating applications through specialty chemical distributors in Australia and New Zealand.
Volume gravity centers on direct sales; market access expansion favors distributor consolidation across ASEAN emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan and South Korea sits 15-25% above Chinese benchmarks, reflecting tighter automotive coating specifications and fuller formulation disclosure requirements under METI frameworks.
China
Shandong and Zhejiang agricultural film corridors drive recurring hindered amine demand through annual greenhouse plastic replacement cycles. SAMR's GB 31604.30 standard on additive migration in food-contact plastics forces compounders toward higher molecular weight stabilizer architectures. Tianjin-based antioxidant-stabilizer integration anchors backward-integrated supply for domestic automotive coating formulators.
Japan
Kansai and Chubu automotive coating clusters specify reactive stabilizer grades for 10-year weathering warranties on OEM clearcoats. METI's priority assessment list under CSCL-aligned frameworks accelerates full formulation disclosure requirements from Tier-1 suppliers. Aichi prefecture concentration of Japanese OEM technical centers tightens benzotriazole specification tolerances beyond regional norms.
India
Maharashtra and Gujarat agricultural plastics consumption generates annual stabilizer replenishment demand comparable to Chinese Shandong volumes. BIS certification mandates for polymer building products create compliance premiums for pre-qualified additive packages. Mumbai-Pune industrial corridor compounders face steepest reformulation gradients as food-contact migration limits tighten.
South Korea
Gyeonggi province automotive coating operations align with Japanese OEM color retention standards for benzotriazole derivatives. Dedicated light stabilizer R&D concentration in domestic chemical parks sustains photochemistry specialization scarce elsewhere in Asia-Pacific. Busan-Ulsan petrochemical complex proximity secures captive hindered amine precursor supply for integrated producers.
Vietnam
Ho Chi Minh City corridor extrusion houses convert from powder batching to automated liquid dosing systems for export horticultural film production. Regional master distributor agreements consolidate procurement previously fragmented across multi-source mill relationships. Technical service partnerships with equipment suppliers open specification control for formulators with liquid formulation expertise.
Asia-Pacific UV Stabilizers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated polymer producers commanding margin capture through captive precursor supply while specialty formulators compete on application-specific performance. The market structure splits between backward-integrated manufacturers with in-house hindered amine production and standalone stabilizer compounders dependent on merchant monomer supply. Three archetypes dominate: Ludwigshafen-style integrated chemical giants, Tianjin-anchored Chinese additive specialists, and South Korean R&D-focused light stabilizer houses. Competitive moves concentrate on upstream control over hindered amine precursors and technical service partnerships for automated dosing system conversions.
Among the integrated chemical majors, BASF SE exemplifies the captive monomer base archetype, while Rianlon Corporation occupies a position within the Chinese antioxidant-stabilizer integration tier. SONGWON Industrial Co., Ltd. sits within the dedicated light stabilizer specialization segment that South Korea has cultivated. These three represent the structural fault lines of the market: European-headquartered multinationals with full value chain control, Chinese domestic champions with backward-integrated regional supply, and Korean specialists with concentrated R&D depth in photochemistry applications.
| Leading Market Players |
|---|
| BASF SE |
| Rianlon Corporation |
| Suqian Unitech Corp., Ltd. |
| SONGWON Industrial Co., Ltd. |
| ADEKA Corporation |
| Clariant AG |
| Everlight Chemical Industrial Corporation |
| SABO S.p.A. |
| Baoding Lucky Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Photocatalytic TiO2 displacement of organic UV stabilizers in opaque agricultural films simultaneously redistributes supply geography toward inorganic pigment producers and compresses pricing power for hindered amine formulators serving cost-minimized greenhouse applications in Shandong and Maharashtra.
Pricing Analysis
Configured-to-order pricing for automotive-grade benzotriazole derivatives commands a 15-25% premium over standard hindered amine packages in commodity polyolefin applications. Three-tier pricing structure across premium, standard, and economy levels separates Japanese OEM-certified grades from BIS-compliant building products and unbranded agricultural film additives. Pricing pressure stems from naphtha-cracker output volatility in Northeast Asian petrochemical complexes, squeezing margins for standalone formulators without captive precursor supply. Tier-1 coating compounders in Aichi and Gyeonggi provinces exhibit lowest price sensitivity due to warranty-linked specification lock-in, while Vietnamese packaging converters show highest sensitivity as they consolidate procurement through regional master distributors.
Supply Chain Analysis
China and South Korea anchor hindered amine light stabilizer production through integrated petrochemical complexes in Tianjin and Busan-Ulsan. Feedstock supply draws from C4-C6 olefin streams tethered to regional naphtha crackers, with benzotriazole precursor availability concentrated among Japanese and South Korean specialty chemical houses. Single-source vulnerability runs through Northeast Asian monomer supply, exposing formulators to cracker turnaround schedules and olefin allocation priorities. Distribution runs through direct mill relationships for East Asian automotive coating clusters and regional master distributor agreements for ASEAN packaging converters in Ho Chi Minh City and Bangkok corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against inorganic UV blockers capturing share in cost-driven agricultural segments, requiring strategic repositioning toward specification-protected automotive and food-contact applications where organic stabilizers retain irreplaceable performance advantages.
For Market Incumbents: Fortify captive supply of hindered amine precursors through backward integration into C4-C6 olefin derivatives or long-term offtake agreements with Northeast Asian petrochemical complexes. Accelerate qualification of polymeric HALS grades under China's GB 31604.30 standard to preempt domestic competitors in Zhejiang food-contact compounding. Technical service partnerships for automated liquid dosing system conversions in Vietnam and Indonesia secure specification control as ASEAN extrusion capacity modernizes. For New Entrants and Emerging Players: Differentiate on liquid concentrate formulation expertise for metered injection systems converting Vietnamese and Indonesian extrusion lines from powder batching. Target India's BIS pre-certification gap for polymer building products in Gujarat and Maharashtra, where mandatory additive disclosure creates first-mover premiums for compliant suppliers. Partner with equipment OEMs to bundle stabilizer supply with dosing system technical service, capturing procurement consolidation among ASEAN master distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese antioxidant-stabilizer integrators seeking geographic expansion into Southeast Asian distribution networks. Long-term viability hinges on exposure to automotive coating specifications with 10-year weathering warranties and food-contact compliance regimes tightening migration limits. Watch for inflection in Japanese METI priority assessment list expansions, which would accelerate full formulation disclosure requirements and favor incumbents with established transparency protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hindered Amine Precursors | Captive C4-C6 olefin supply from Tianjin and Busan-Ulsan complexes insulates margin capture from naphtha-cracker volatility. |
| Polymeric HALS Grade Qualification | GB 31604.30 compliance for food-contact applications in Zhejiang and Guangdong secures replacement demand from legacy benzotriazole reformulation. |
| Automated Liquid Dosing Technical Partnerships | Ho Chi Minh City and Bangkok corridor conversions from powder batching open specification control for concentrate formulators. |
| BIS Pre-Certification for Building Products | Mandatory additive disclosure in Gujarat and Maharashtra creates compliance premiums ahead of import substitution penalties. |
| Reactive Stabilizer R&D Investment | Polymer-bound functionality for 10-year automotive warranties in Kansai and Chubu decomposes volume-based contracting models. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC and Cefic additive industry reports, SAMR GB standard filings, and METI substance screening disclosures. Primary interviews engaged technical R&D directors at integrated stabilizer producers, procurement leads at Tier-1 automotive coating formulators, distribution channel partners in ASEAN master distributor networks, and plant managers at agricultural film extrusion operations in Shandong and Maharashtra. Bottom-up demand modeling triangulates against top-down petrochemical capacity assessments across the analysis window.
Segmentation dimensions modeled include stabilizer chemistry type, end-use industry performance tier, physical form for processing compatibility, and regional regulatory compliance cluster. CAGRs derive from production capacity expansion schedules, replacement cycle frequencies in greenhouse applications, and automotive OEM specification evolution across the projection horizon. Industry-specific inputs incorporate hindered amine precursor availability from naphtha-cracker yields and benzotriazole derivative qualification timelines under METI frameworks.
Forecasts assume regulatory continuity in China's SAMR GB standards, Japan's METI CSCL-aligned screening, and India's BIS certification regimes; material policy shifts would require re-modeling. Specific risks include REACH-equivalent registration asymmetries favoring domestic Chinese producers, photocatalytic TiO2 substitution acceleration in commodity films, and feedstock concentration exposing margin compression during olefin supply disruptions. Recalibration cycles align with material shifts in automotive warranty specifications, migration limit tightenings, and ASEAN extrusion automation adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Mandelic Acid Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Washable Marker Market