
 Specialty Chemicals Market | 2026-2036
Specialty Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Chemicals Market Intelligence
ISO 14001 environmental management certification is unwinding the competitive landscape for smaller formulators lacking audit resources. BASF SE leverages integrated production complexes across Ludwigshafen and Antwerp to sustain margin capture from captive intermediates. Evonik Industries AG anchors its position through high-purity silica and specialty additives for semiconductor clients. Croda International Plc differentiates via bio-based surfactant platforms that navigate tightening biodegradability thresholds in personal care applications.
Specialty chemicals comprise high-value, low-volume formulations engineered for specific performance criteria such as purity levels exceeding 99.99 percent, controlled particle size distributions, or tailored rheological profiles. These substances serve as enabling inputs where standard commodity chemicals fail to meet exacting functional requirements in end-processes. Electronic chemicals command premium pricing as semiconductor nodes shrink below three nanometers and contamination tolerances tighten. Construction chemicals face margin compression from commoditized concrete admixtures while flavors and fragrances extract value from proprietary encapsulation technologies and natural extraction methods.
REACH registration dossiers and the EU Green Deal's chemical sustainability targets force reformulation investments across European suppliers. EPA Toxic Substances Control Act Section 5 premanufacture notifications delay new chemical introductions in the United States. China's MEE environmental inspections and GB standards for hazardous chemical storage reshape plant siting decisions and capital allocation. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional specialization delivers superior compliance economics.
Market Dynamics
Semiconductor node shrinkage below three nanometers is compressing contamination tolerances and forcing specialty chemical suppliers to retool purification infrastructure at unprecedented capital intensity.
Growth Catalysts
- Electronic-grade purity mandates:Chip fabrication at sub-3nm nodes requires contamination thresholds below parts-per-trillion, pulling investment into advanced filtration and synthesis infrastructure.
- REACH registration deadlines:ECHA dossier requirements for existing substances are accelerating reformulation cycles and opening market share for compliant suppliers.
- China domestic chip capacity:Wafer fab construction in Shanghai, Beijing, and Hefei is concentrating demand for photoresists, etchants, and CMP slurries.
Market Restraints
- Fluorinated feedstock volatility:PFAS precursor availability constrains production of high-performance polymers and surfactants as environmental litigation accumulates in US federal courts.
- German production cluster dependency:Ludwigshafen and Antwerp complexes account for disproportionate European intermediate supply, creating geographic concentration risk.
- EPA Section 5 review timelines:Premanufacture notification delays for novel chemical entities extend commercialization cycles by 18-24 months.
Strategic Opportunities
- India specialty chemical manufacturing:PLI scheme incentives and CDSCO regulatory streamlining are attracting formulation investments for pharmaceutical intermediates and agrochemical actives.
- Bio-based surfactant platforms:EU Green Deal biodegradability thresholds favor renewable feedstock substitution in personal care and home care applications.
- AI-assisted molecular design:Convergence of computational chemistry and machine learning is compressing R&D cycles for custom performance molecules.
Industry Challenges
- Analytical chemist scarcity:Expertise in ICP-MS and GC-MS for parts-per-trillion detection is concentrated among retiring specialists in Germany and Japan.
- ISO 14001 audit resource constraints:Smaller formulators lack capital for environmental management certification, excluding them from tier-one supplier pools.
- Legacy ERP integration friction:Batch record digitization for FDA 21 CFR Part 11 compliance conflicts with decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Chemicals Market |
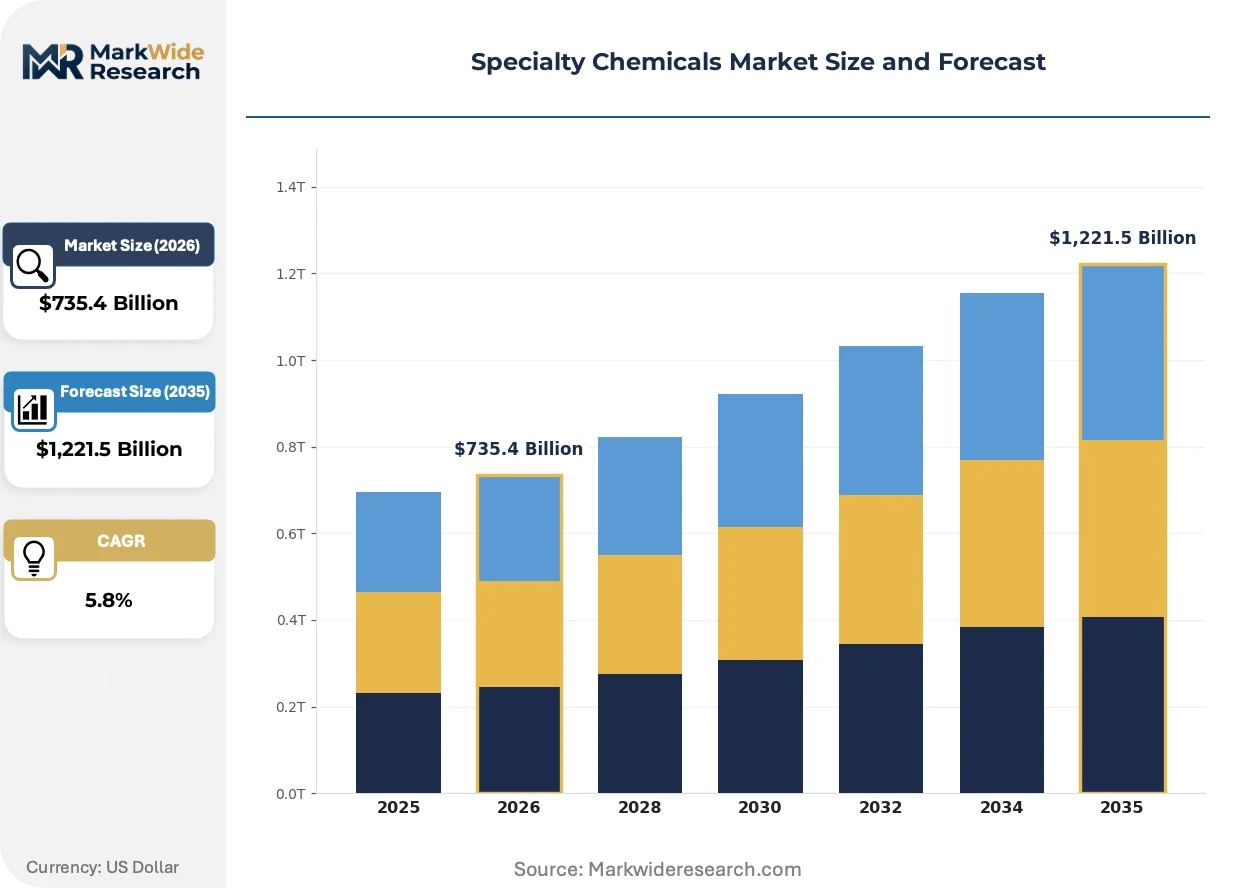
| Market Size in 2026 | $735.4 Billion |
| Market Size in 2035 | $1,221.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agrochemicals, Electronic Chemicals, Construction Chemicals, Flavors & Fragrances, Water Treatment Chemicals Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade, Textile Grade Application: Crop Protection, Semiconductor Manufacturing, Building Material Enhancement, Personal Care Products, Pulp & Paper Processing Packaging Type: Drums, Bulk Bags, Fiber Drums, Intermediate Bulk Containers, Bottles |
| Companies Covered | Clariant AG, Huntsman Corporation, BASF SE, Covestro AG, Croda International Plc, Solvay S.A., Akzo Nobel N.V., Arkema Group, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Chemicals Market Strategic Shifts & Innovations
Process intensification and closed-loop manufacturing are redefining asset productivity benchmarks while regulatory chemistry is forcing molecular architecture redesign across multiple end-use verticals.
Continuous flow reactor technology is displacing traditional batch synthesis in pharmaceutical intermediate manufacturing. Merck KGaA and Lonza have operationalized micro-reactor platforms for hazardous nitrations and oxidations. This shift is displacing capital-heavy stirred-tank infrastructure and enabling on-site modular production near end-use facilities.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption while constraining legacy HFC blowing agents in polyurethane foam applications. German chemical parks face stranded asset risk in fluorinated gas production lines. Formulators are responding with hydrocarbon and CO2 alternative investments, particularly in construction insulation segments.
Direct procurement relationships between semiconductor fabs and chemical suppliers are consolidating vendor bases and compressing distributor margins. Tokyo Electron and ASML equipment specifications now require supplier qualification at the molecular level rather than distributor level. This pattern is most visible in South Korea and Taiwan, where Samsung and TSMC procurement teams have reduced qualified chemical suppliers by 40 percent since 2020.
Specialty Chemicals Market Segmentation
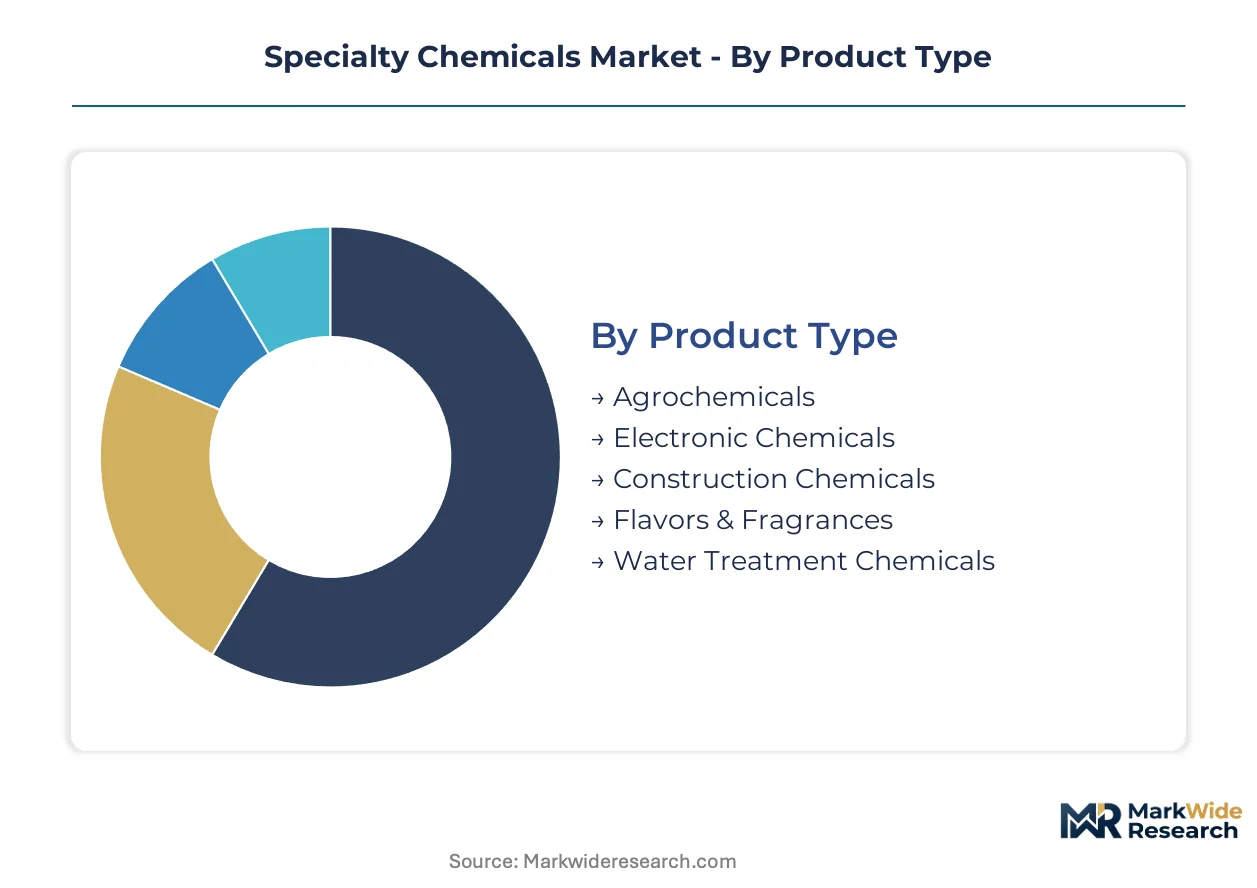
Segmentation in specialty chemicals reveals where formulation complexity commands premium capture versus where commoditization erodes returns. Product type and grade classifications determine regulatory burden and capital intensity, while application and packaging choices reflect supply chain proximity requirements and contamination risk management.
Product Type:
Substitution pressure from bio-based alternatives and process intensification technologies is reshaping competitive boundaries across all five product categories.
- Agrochemicals:Formulations encompass herbicides, insecticides, fungicides, and plant growth regulators engineered for targeted crop protection. Demand concentrates in Brazil and India as soybean and cotton acreage expands, though biological pesticide substitution is compressing synthetic active ingredient pricing in European markets under EU Green Deal Farm to Fork targets.
- Electronic Chemicals:Ultra-high purity acids, solvents, photoresists, and CMP slurries serve semiconductor fabrication nodes below three nanometers. Wafer fab construction in Shanghai, Hefei, and Beijing is pulling disproportionate volume growth as China pursues domestic chip self-sufficiency amid export control tightening.
- Construction Chemicals:Concrete admixtures, waterproofing compounds, and repair mortars modify building material performance.
- Flavors & Fragrances:Proprietary encapsulation technologies and natural extraction methods deliver olfactory and gustatory performance.
- Water Treatment Chemicals:Coagulants, flocculants, and biocides manage industrial and municipal water quality.
Electronic chemicals retain volume leadership; agrochemicals hold the steepest expansion curve as biological integration and precision agriculture reshape formulation requirements.
Grade:
Cost tier stratification separates qualification-intensive grades serving regulated end-uses from specification-flexible industrial formulations.
- Pharmaceutical Grade:Purity specifications exceeding 99.9 percent with comprehensive impurity profiling satisfy FDA and EMA drug master file requirements. CDSCO regulatory streamlining in India is attracting API intermediate investment, while USP and EP compliance costs exclude smaller manufacturers from generic drug supplier pools.
- Electronic Grade:Contamination thresholds below parts-per-trillion for metals and ions enable sub-three nanometer semiconductor processing. ICP-MS analytical capability scarcity in Germany and Japan is constraining supplier qualification for advanced node fabs in Taiwan and South Korea.
- Food Grade:FSSAI, FDA, and EFSA compliance for direct and indirect food contact applications.
- Industrial Grade:Performance-adequate specifications for manufacturing processes without human exposure pathways.
- Cosmetic Grade:EU Cosmetics Regulation and MoCRA compliance for personal care actives and preservatives.
Industrial grade retains volume leadership; electronic grade is gaining share fastest as semiconductor fabrication capacity concentrates in East Asia.
Application:
Customer type fragmentation separates specification-driven OEM procurement from price-sensitive distributor channels across end-use verticals.
- Semiconductor Manufacturing:Direct fab-supplier relationships now require molecular-level qualification rather than distributor certification. TSMC and Samsung procurement teams have consolidated qualified chemical suppliers by 40 percent since 2020, compressing margins for intermediaries while rewarding integrated producers with captive ultra-purification infrastructure.
- Crop Protection:Formulation services and active ingredient supply to agricultural input distributors and direct-to-farm channels.
- Building Material Enhancement:Ready-mix concrete producers and construction contractors specify admixture performance.
- Personal Care Products:Multinational beauty brands and contract manufacturers demand bio-based surfactant platforms meeting EU Green Deal biodegradability thresholds.
- Pulp & Paper Processing:Bleaching chemicals, sizing agents, and process aids for integrated mills.
Crop protection retains volume leadership; semiconductor manufacturing holds the steepest expansion curve as node shrinkage intensifies purity requirements.
Packaging Type:
Supply concentration in hazardous chemical logistics favors regional packaging specialists with MEE and GB standards compliance for Chinese distribution.
- Intermediate Bulk Containers:Stainless steel and composite IBCs enable closed-loop solvent return systems for pharmaceutical and electronics manufacturers. German chemical parks leverage IBC fleets for just-in-time delivery to Ludwigshafen and Antwerp production complexes, reducing drum waste disposal costs.
- Bulk Bags:Flexible intermediate bulk containers handle powdered construction chemicals and water treatment polymers.
- Drums:Steel and plastic drums remain standard for liquid specialty chemicals across industrial applications.
- Fiber Drums:Lightweight corrugated containers serve solid and granular formulations with lower hazard classification.
- Bottles:Laboratory-scale and sampling quantities for analytical and R&D applications.
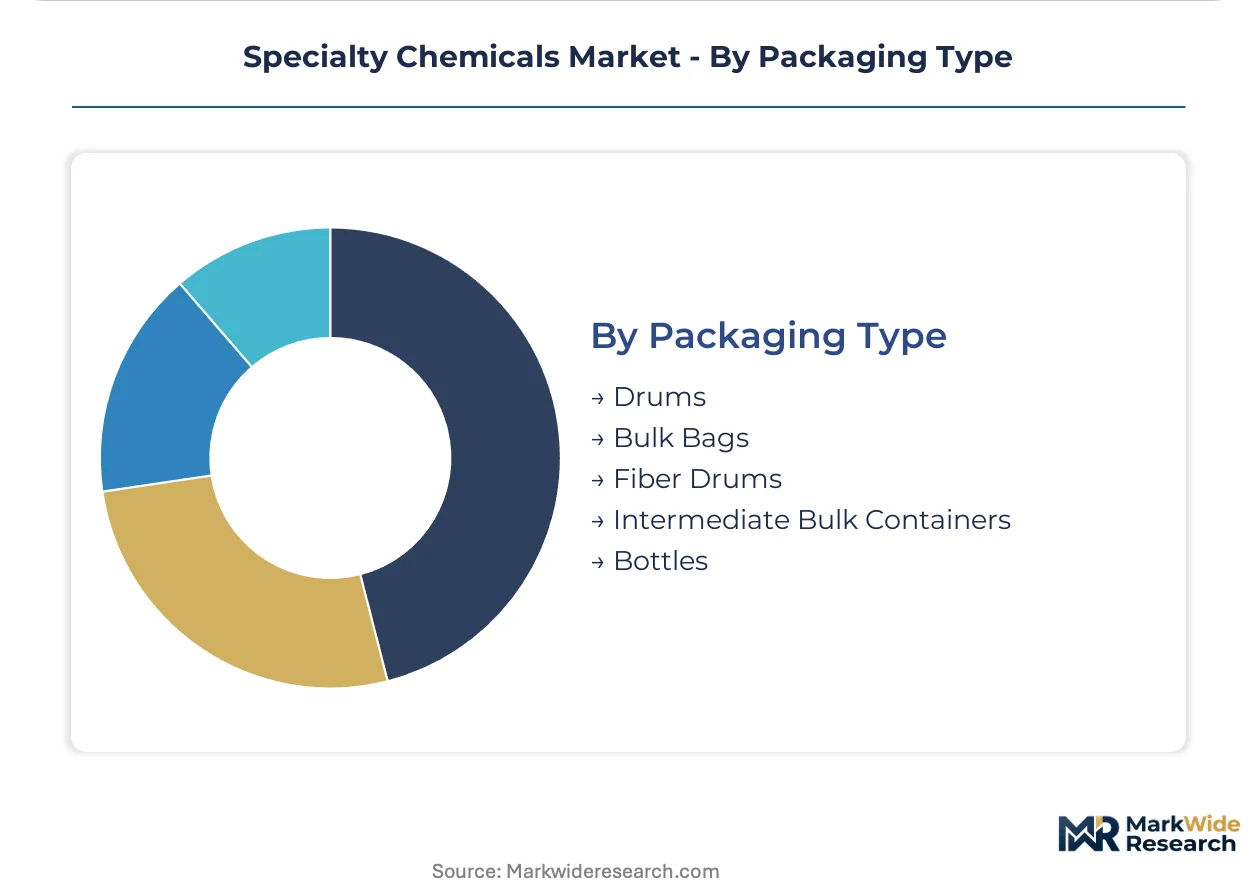
Drums retain volume leadership; intermediate bulk containers are climbing the fastest as closed-loop sustainability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE environmental inspections and GB standards for hazardous chemical storage are redirecting capital toward compliant manufacturing zones. Germany's REACH implementation tightens formulation requirements for European suppliers. India's PLI scheme incentives attract pharmaceutical intermediate investments.
China
Wafer fab construction in Shanghai, Hefei, and Beijing concentrates demand for photoresists, etchants, and CMP slurries. MEE environmental inspections enforce GB standards for hazardous chemical storage and reshape plant siting decisions. Yangtze River Delta chemical parks absorb disproportionate investment as domestic chip fabrication capacity expands.
Germany
Ludwigshafen and Antwerp production complexes sustain European intermediate supply through integrated manufacturing infrastructure. REACH registration dossiers and ECHA compliance requirements accelerate reformulation cycles for existing substances. BASF SE leverages captive production complexes to maintain margin capture from internal intermediate supply.
United States
EPA Toxic Substances Control Act Section 5 premanufacture notifications delay new chemical introductions by 18-24 months. Semiconductor manufacturing clusters in Arizona, Texas, and Oregon drive electronic-grade purity demand for sub-3nm node processing. PFAS precursor litigation in federal courts constrains fluorinated feedstock availability for high-performance polymer production.
India
CDSCO regulatory streamlining and PLI scheme incentives attract formulation investments for pharmaceutical intermediates and agrochemical actives. Maharashtra and Gujarat chemical corridors expand capacity for API intermediate manufacturing. Domestic crop protection demand concentrates in soybean and cotton-growing states as precision agriculture adoption accelerates.
Japan
ICP-MS and GC-MS analytical expertise for parts-per-trillion detection concentrates among retiring specialists in Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic semiconductor material supply chain security. Kyushu and Tohoku regions host specialized purification infrastructure serving Taiwan and South Korean fab customers.
Specialty Chemicals Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The vendor base organizes around three tiers: integrated majors with captive intermediate supply, regional formulators with application expertise, and niche specialists with analytical certification. Strategic archetypes include purification infrastructure owners, bio-based platform developers, and semiconductor-qualified suppliers. Competitive moves center on M&A for analytical capabilities and capacity expansion near Asian fab clusters.
Within the integrated major tier, BASF SE and Evonik Industries AG exemplify European producers with Ludwigshafen and Antwerp production complex advantages. Croda International Plc occupies a position among UK-based specialists with bio-based surfactant platform differentiation. Arkema Group represents French chemical producers navigating EU F-Gas Regulation phase-down requirements.
| Leading Market Players |
|---|
| Clariant AG |
| Huntsman Corporation |
| BASF SE |
| Covestro AG |
| Croda International Plc |
| Solvay S.A. |
| Akzo Nobel N.V. |
| Arkema Group |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for electronic-grade solvents concentrate pricing power with German and Japanese producers holding captive purification infrastructure, while buyers in Taiwan and South Korea absorb transport premiums to secure sub-parts-per-trillion contamination thresholds.
Pricing Analysis
Certification level creates the primary spread, with electronic-grade purity commanding substantial premiums over industrial formulations as semiconductor fabs qualify suppliers at the molecular level. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity threshold and analytical documentation depth. Cost compression in construction chemicals intensifies as commoditized concrete admixtures face oversupply, while pharmaceutical-grade intermediates resist pricing pressure due to FDA and EMA compliance barriers. Distributor channels exhibit highest price sensitivity as direct fab-supplier relationships eliminate intermediary margins.
Supply Chain Analysis
Just-in-time delivery preferences dominate semiconductor chemical procurement, with IBC fleet systems enabling closed-loop returns from Taiwanese and South Korean fabs to German chemical parks. Supply concentrates in Germany, Japan, and China for high-purity intermediates, drawing from fluorinated feedstocks, rare earth catalysts, and bio-based surfactant platforms. Single-source vulnerability runs through PFAS precursor availability as US environmental litigation constrains legacy polymer production. Distribution runs through qualified direct supplier relationships rather than distributor networks for electronic-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ICP-MS and GC-MS analytical expertise for parts-per-trillion detection concentrates competitive advantage with aging specialist workforces in Tokyo and Osaka metropolitan areas, forcing acquisition premiums for certified laboratories.
For Market Incumbents: Secure captive ultra-purification infrastructure through backward integration into filtration membrane production, insulating margin capture from fluorinated feedstock volatility. Acquire analytical laboratories in Kyushu and Tohoku regions to lock in retiring Japanese ICP-MS specialists before qualification bottlenecks constrain TSMC and Samsung supplier pools. For New Entrants and Emerging Players: Lead with bio-based surfactant platforms targeting EU Green Deal biodegradability thresholds in personal care applications, where Croda's incumbent position leaves mid-tier pricing exposed. Establish modular micro-reactor production near Maharashtra and Gujarat pharmaceutical corridors to exploit CDSCO regulatory streamlining and PLI scheme incentives for API intermediates. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct fab-supplier qualification requirements are compressing distributor margins and rewarding integrated producers with molecular-level certification capabilities. Target acquisition archetypes include regional formulators with ISO 14001 compliance and captive analytical infrastructure. Watch for inflection when EPA Section 5 review timelines compress below twelve months, signaling regulatory streamlining that would accelerate novel chemical commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purification Infrastructure | Captive filtration membrane production insulates margin capture from fluorinated feedstock constraints in Ludwigshafen complexes. |
| Acquisition of Analytical Laboratories | ICP-MS capability scarcity in Germany and Japan commands premium valuations as semiconductor node shrinkage intensifies. |
| Modular Micro-Reactor Deployment | Continuous flow platforms near Indian pharmaceutical corridors exploit CDSCO streamlining and reduce batch synthesis capital intensity. |
| Bio-Based Surfactant Platform Development | EU Green Deal biodegradability thresholds favor renewable feedstock substitution in personal care and home care segments. |
| Long-Term Supply Agreements with Fab Clusters | Direct qualification with TSMC and Samsung procurement teams locks out distributor intermediaries and secures volume commitments. |
Research Approach
A spread of perspectives from plant managers at German chemical parks, procurement leads at Taiwanese semiconductor fabs, distribution channel partners in Indian pharmaceutical corridors, and technical R&D directors at European surfactant formulators converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and MEE environmental inspection records. Bottom-up capacity assessments and top-down demand modeling triangulated volume and value estimates across the projection horizon.
Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub, with analytical frameworks tracking substitution dynamics between synthetic and bio-based platforms throughout the forecast period. CAGRs derived from capacity expansion pipelines, regulatory compliance cost trajectories, and customer procurement consolidation patterns. Forecast inputs incorporated REACH registration timelines, EPA Section 5 review velocity, and China domestic chip fabrication capacity buildouts.
Underlying assumptions cover sustained semiconductor node shrinkage below three nanometers and continued PFAS precursor availability constraints, with deviation risk concentrated in EPA regulatory acceleration or China MEE enforcement intensity. Revision becomes warranted when direct fab-supplier qualification thresholds relax or bio-based surfactant cost parity with petroleum-derived alternatives crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Bio-Ketones Market