
 Stable Isotopes Market | 2026-2036
Stable Isotopes Market Size, Share, and Industry Trends Forecast 2026-2036
Stable Isotopes Market Analytics
A capital-intensity divergence between centrifuge enrichment specialists and chemical exchange processors is unwinding competitive dynamics in stable isotope supply. Cambridge Isotope Laboratories leverages vertical integration across deuterium gas and labeled compound production to sustain margin capture from raw feedstock to finished reagent. Merck KGaA anchors European pharmaceutical demand through controlled distribution of pharmaceutical-grade isotopes to GMP-certified formulation sites. URENCO Limited dominates industrial-scale enrichment capacity, operating gaseous centrifuge cascades that supply baseline feedstock to downstream labelers.
Stable isotopes are variants of chemical elements with identical proton counts but differing neutron numbers, typically enriched through gaseous centrifugation or cryogenic distillation to isotopic purities exceeding 99 percent for analytical and therapeutic applications. Carbon-13 leads pharmaceutical tracer applications due to its role in metabolic imaging and drug metabolism studies, while deuterium commands premium positioning in heavy drug synthesis where kinetic isotope effects modify therapeutic half-lives. Mass spectrometry instrumentation anchors analytical demand, though NMR spectroscopy is displacing older methods in structural biology workflows at major research institutes.
The FDA enforces Current Good Manufacturing Practice standards for isotope-containing radiopharmaceuticals, while the EPA monitors environmental release thresholds for enrichment facilities under Clean Air Act provisions; both frameworks elevate compliance costs for new market entrants. ISO 17025 accreditation requirements for analytical laboratories shape procurement specifications, directing volume toward certified suppliers. Stakeholders must monitor emerging national security export controls on dual-use enrichment technology, as these restrictions threaten to fragment long-established supply relationships between producers and international research consumers.
Market Dynamics
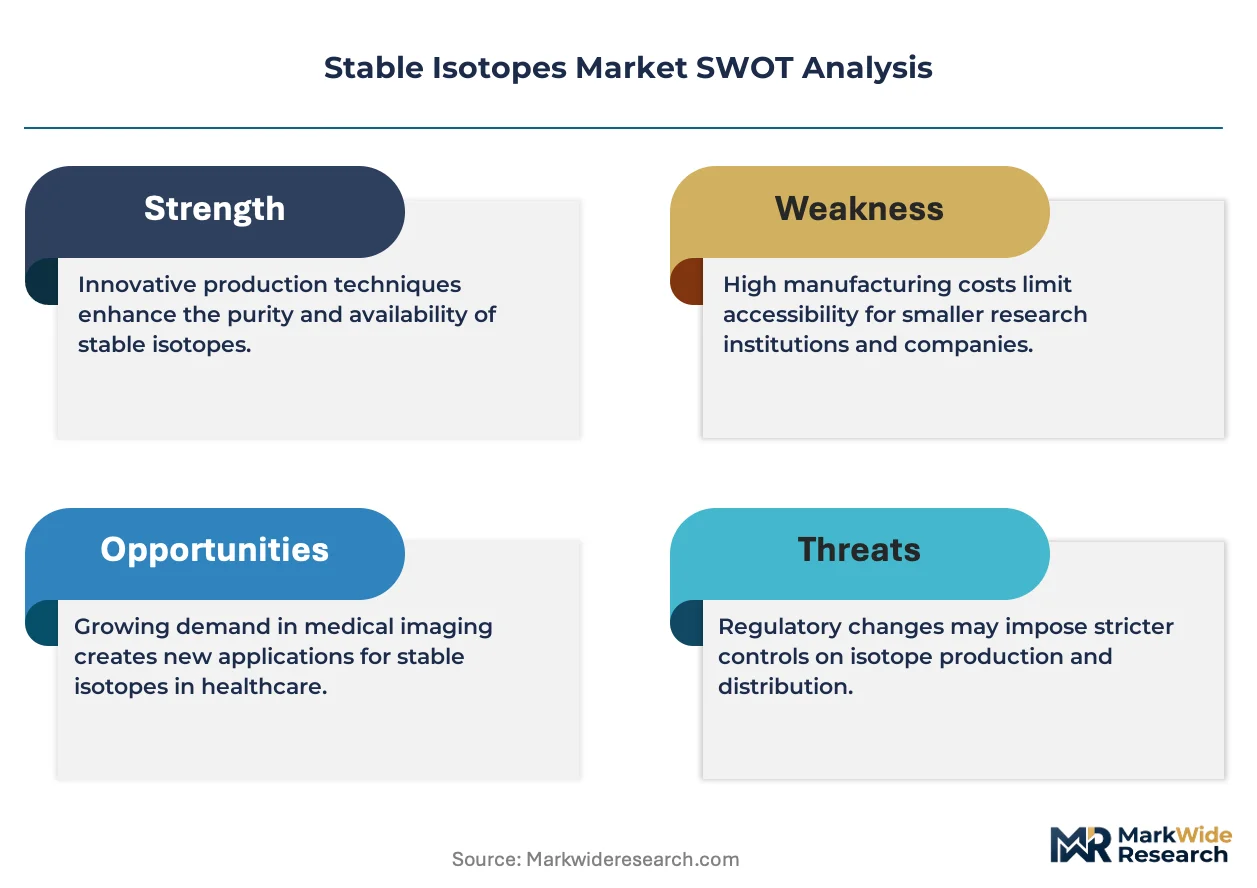
Centrifuge enrichment capacity concentration among a handful of state-linked operators is constraining feedstock availability for downstream compound manufacturers, forcing labelers to secure long-term offtake agreements or invest in captive distillation assets.
Growth Catalysts
- Pharmaceutical tracer expansion:Metabolic imaging protocols at US academic medical centers are proliferating carbon-13 labeled substrates for real-time drug metabolism visualization.
- EMA's tightened GMP Annex 1:Sterile manufacturing guidelines for isotope-containing injectables are mandating higher purity grades, pulling demand toward certified pharmaceutical-grade suppliers.
- Heavy drug synthesis:Deuterium substitution in small-molecule therapeutics is extending half-lives through kinetic isotope effects, attracting investment from specialty API manufacturers.
Market Restraints
- Feedstock concentration risk:Gaseous centrifuge capacity clusters in a narrow set of national enrichment facilities, exposing compound manufacturers to geopolitical supply disruptions.
- Energy input volatility:Cryogenic distillation of deuterium from hydrogen feedstock consumes substantial electricity, compressing margins when regional power tariffs spike.
- Substitution by fluorine-18:Positron emission tomography tracers using short-lived radioisotopes are capturing certain metabolic imaging applications previously served by carbon-13.
Strategic Opportunities
- India's pharmaceutical manufacturing:CDSCO's streamlined API approval pathways are attracting isotope labeling investments for export-oriented generic drug production.
- Laser isotope separation convergence:Emerging atomic vapor laser enrichment technology promises lower energy intensity than centrifuge cascades for niche isotope production.
- Direct-to-laboratory distribution:E-commerce platforms specializing in research reagents are disintermediating traditional distributor networks for analytical-grade isotopes.
Industry Challenges
- Mass spectrometry technician scarcity:Analytical laboratories face recruitment gaps for operators capable of maintaining isotope ratio instrumentation at ISO 17025 standards.
- GMP certification timelines:FDA pre-approval inspections for isotope-containing radiopharmaceuticals extend facility qualification periods by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stable Isotopes Market |
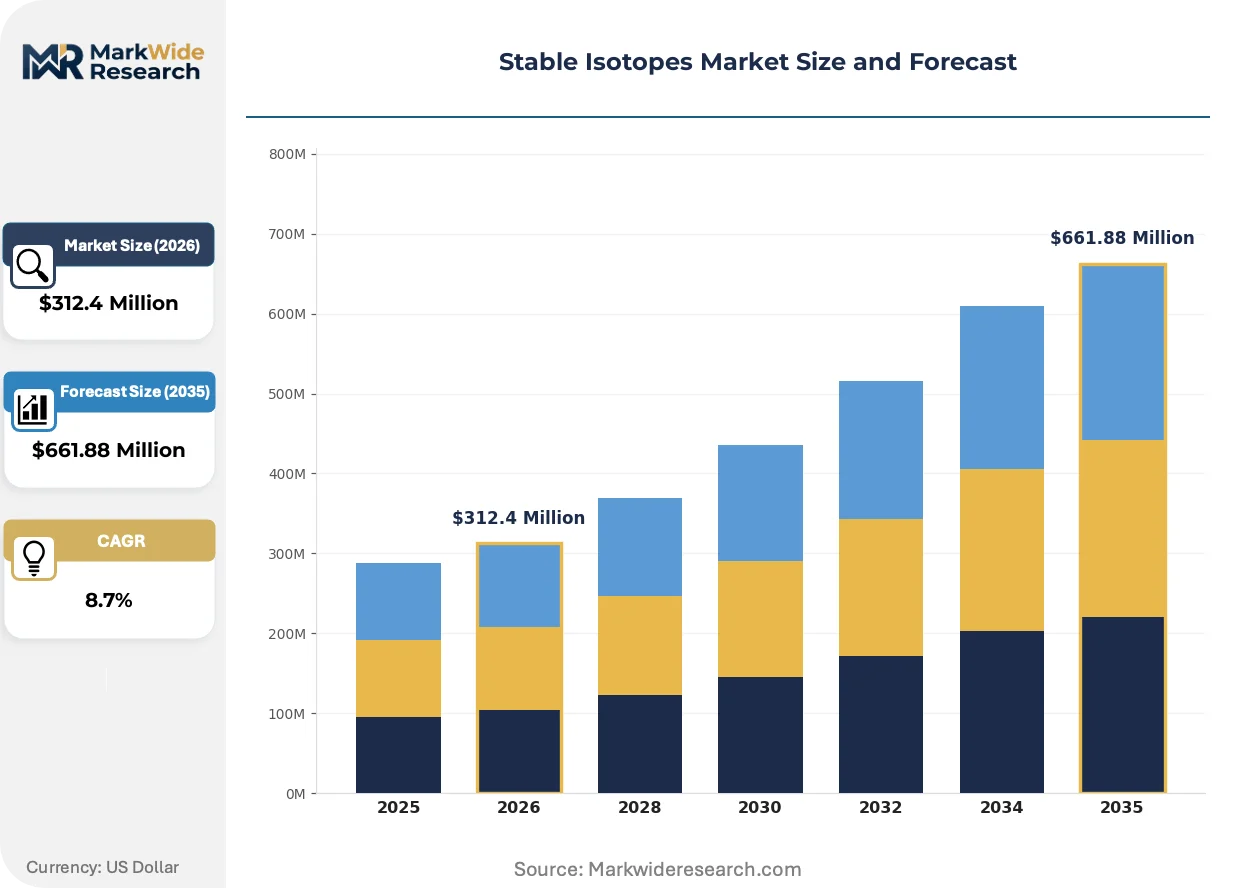
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon-13, Oxygen-18, Nitrogen-15, Deuterium End User: Healthcare, Research Institutes, Environmental Agencies, Pharmaceutical Application: Clinical Diagnostics, Environmental Monitoring, Agriculture Testing, Nuclear Medicine Technology: Mass Spectrometry, NMR Spectroscopy, Accelerator Mass Spectrometry, Gamma Spectroscopy |
| Companies Covered | Cambridge Isotope Laboratories, Inc., Merck KGaA, PerkinElmer, Inc., JSC Isotope, Trace Sciences International, Medical Isotopes, Inc., Omicron Biochemicals, Inc., URENCO Limited, IsoSciences, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stable Isotopes Market Evolving Landscape
Workflow automation and spectroscopic platform convergence are compressing analytical turnaround times while elevating data reproducibility standards across pharmaceutical and environmental testing verticals.
High-field NMR spectrometers equipped with cryogenically cooled probes are supplanting traditional magnetic sector mass spectrometers in structural biology departments at German and Swiss research institutes. Protein crystallography groups at Max Planck facilities are adopting these systems for real-time isotope-edited resonance assignment. The shift is compressing instrument replacement cycles from seven years toward four-year refresh schedules.
REACH authorization requirements for deuterated solvent imports into the European Union are tightening substance volume tracking and safety documentation obligations for laboratory chemical suppliers. Compound distributors must now submit extended safety data sheets for isotope-labeled reagents above specified tonnage thresholds. German formulation sites are consolidating procurement through REACH-authorized importers to minimize compliance overhead.
Consolidated procurement consortia at US national laboratories are displacing individual investigator purchasing for stable isotope feedstocks. Oak Ridge and Argonne facilities now coordinate bulk deuterium and carbon-13 acquisitions through centralized supply contracts. This concentration is visible across Department of Energy-funded research programs, where standardized specifications reduce vendor qualification burdens.
Stable Isotopes Market Segmentation
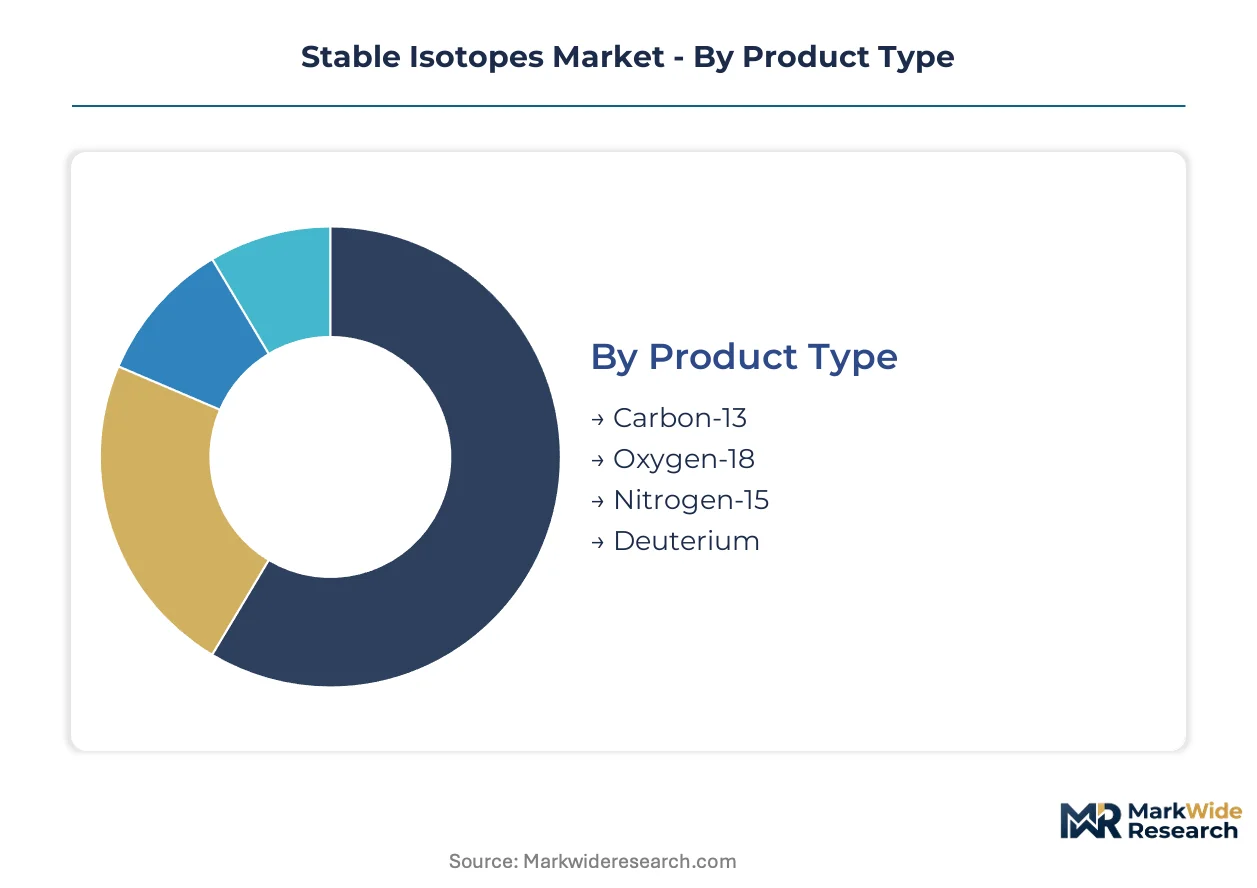
Stable isotope procurement specifications diverge sharply across end-use verticals, with pharmaceutical-grade purity thresholds and analytical-grade tolerances creating distinct commercial tiers. Regulatory frameworks from FDA, EMA, and CDSCO enforce grade-specific certifications that reshape supplier qualification requirements and pricing structures.
Product Type:
FDA's GMP standards for radiopharmaceuticals and EMA's Annex 1 sterile manufacturing guidelines enforce divergent purity specifications across isotope categories, fragmenting supplier certification pathways.
- Carbon-13:Enriched to isotopic purities exceeding 99 percent through cryogenic distillation of carbon monoxide feedstock. US academic medical centers concentrate demand for metabolic imaging substrates where real-time drug metabolism visualization protocols are proliferating.
- Deuterium:Separated from hydrogen via gaseous centrifugation or electrolysis with substantial electricity inputs. Specialty API manufacturers in heavy drug synthesis programs command premium positioning where kinetic isotope effects extend therapeutic half-lives.
- Oxygen-18:Produced through water distillation for PET precursor chemistry and paleoclimate research applications.
- Nitrogen-15:Enriched via chemical exchange for agricultural tracer studies and protein metabolic research.
Carbon-13 handles the majority of throughput; deuterium is the fastest mover on share.
End User:
Procurement scale and specification stringency separate institutional buyers, with national laboratory consortia consolidating volume while pharmaceutical manufacturers drive purity premiums.
- Pharmaceutical:GMP-certified formulation sites demand pharmaceutical-grade isotopes with full batch documentation for radiopharmaceutical production. CDSCO's streamlined API approval pathways in India are attracting labeling investments for export-oriented generic drug manufacturing.
- Research Institutes:Max Planck facilities and Swiss structural biology departments are displacing mass spectrometry with high-field NMR spectrometers for isotope-edited resonance assignment. Oak Ridge and Argonne national laboratories coordinate bulk acquisitions through centralized supply contracts.
- Healthcare:Academic medical centers procure carbon-13 labeled substrates for clinical diagnostic protocols.
- Environmental Agencies:EPA-monitored facilities track isotope release thresholds under Clean Air Act provisions for enrichment oversight.
Research institutes handle the majority of throughput; pharmaceutical is expanding most quickly.
Application:
Instrument platform compatibility and regulatory submission requirements segment demand, with clinical applications facing extended FDA pre-approval inspection timelines.
- Clinical Diagnostics:Carbon-13 breath tests and metabolic imaging substrates require FDA-validated manufacturing processes with twelve-to-eighteen-month facility qualification periods. US academic medical centers are proliferating real-time visualization protocols.
- Nuclear Medicine:Radiopharmaceutical production demands isotopic purities meeting USP monograph specifications with full chain-of-custody documentation. EMA's tightened GMP Annex 1 mandates higher purity grades for sterile injectables.
- Environmental Monitoring:Isotope hydrology and contaminant tracing applications anchor demand at EPA-regulated facilities.
- Agriculture Testing:Nitrogen-15 and carbon-13 tracers support fertilizer efficiency and soil carbon sequestration studies.
Clinical diagnostics handles the majority of throughput; nuclear medicine is climbing the fastest.
Technology:
Detection sensitivity and sample throughput requirements drive platform selection, with cryogenic probe advances compressing NMR replacement cycles.
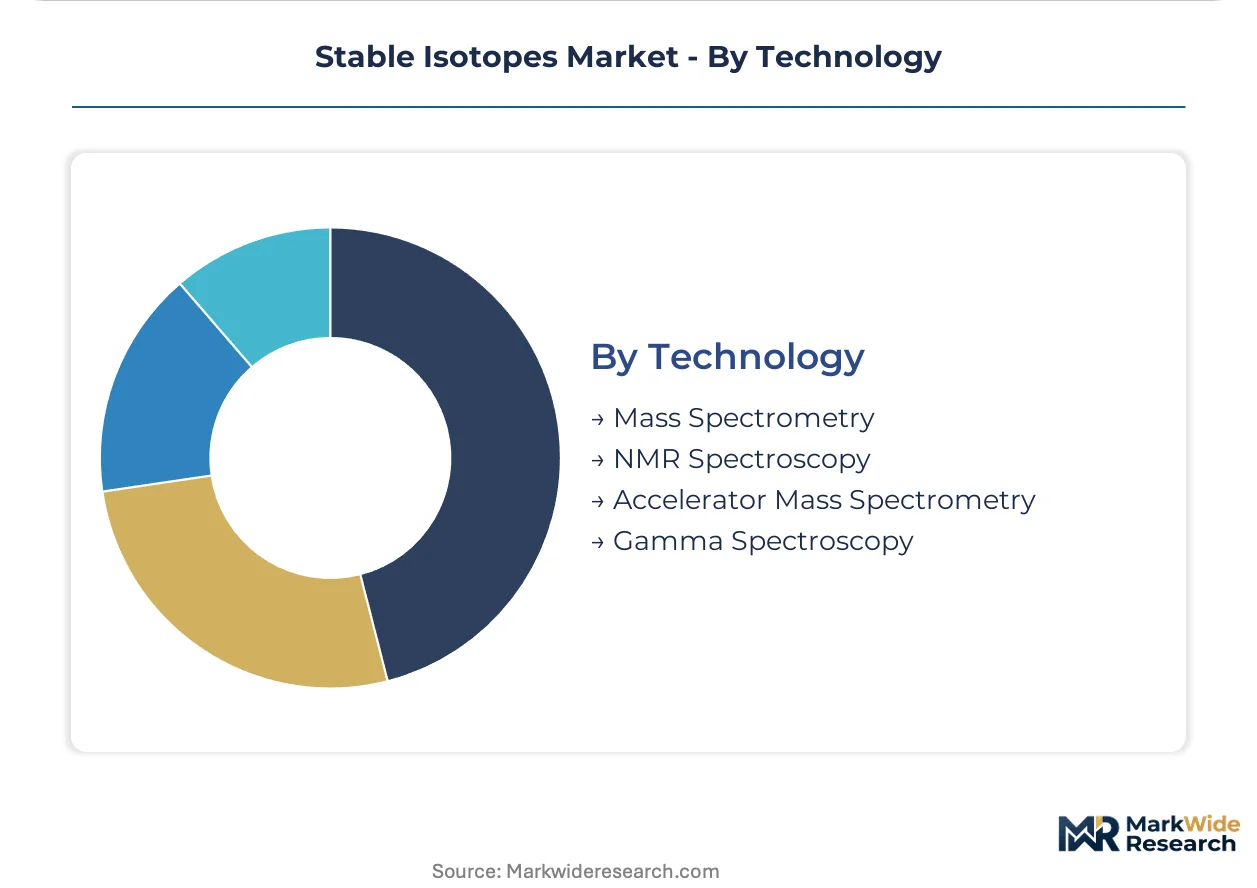
- NMR Spectroscopy:High-field systems equipped with cryogenically cooled probes are supplanting magnetic sector mass spectrometers at German and Swiss research institutes. Protein crystallography groups are adopting four-year refresh schedules versus seven-year replacement cycles.
- Mass Spectrometry:Isotope ratio instrumentation anchors analytical demand across environmental and pharmaceutical testing verticals. ISO 17025 accreditation requirements shape procurement specifications toward certified suppliers.
- Accelerator Mass Spectrometry:Ultra-trace detection capabilities serve radiocarbon dating and geochronology applications.
- Gamma Spectroscopy:Nuclear medicine quality control and environmental monitoring deploy scintillation detector arrays.
Mass spectrometry handles the majority of throughput; NMR spectroscopy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Academic buyers in the United States absorb premium pricing for GMP-certified isotopes, while Indian pharmaceutical manufacturers prioritize cost efficiency in bulk deuterium procurement.
United States
Oak Ridge National Laboratory and Argonne National Laboratory coordinate consolidated procurement contracts for carbon-13 and deuterium feedstocks. FDA pre-approval inspection timelines for isotope-containing radiopharmaceuticals extend facility qualification periods by twelve to eighteen months. Greater Boston's academic medical centers proliferate real-time metabolic imaging protocols using carbon-13 labeled substrates.
Germany
Max Planck Institute protein crystallography groups displace mass spectrometry with high-field NMR spectrometers for isotope-edited resonance assignment. REACH authorization requirements tighten substance volume tracking for deuterated solvent imports above specified tonnage thresholds. Bavarian formulation sites consolidate procurement through REACH-authorized importers to minimize compliance overhead.
India
Export-oriented generic drug manufacturers attract isotope labeling investments for heavy drug synthesis programs. CDSCO streamlines API approval pathways, reducing regulatory friction for pharmaceutical-grade isotope integration. Gujarat and Maharashtra pharmaceutical clusters expand tracer compound production for international contract research organizations.
Switzerland
Swissmedic enforces stringent GMP standards for radiopharmaceutical manufacturing, elevating purity requirements for clinical-grade isotopes. Basel-area pharmaceutical formulation sites demand full batch documentation and chain-of-custody certification. Swiss structural biology departments compress NMR instrument replacement cycles from seven years toward four-year refresh schedules.
Japan
PMDA oversight of isotope-containing therapeutics mandates rigorous manufacturing process validation for metabolic imaging agents. METI programs support domestic enrichment capacity for strategic isotope independence. Kanto region research institutes anchor analytical demand for nitrogen-15 in agricultural tracer studies.
Stable Isotopes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in stable isotope supply. State-linked enrichment operators control gaseous centrifuge capacity, constraining feedstock availability for downstream compound manufacturers. Three archetypes dominate: vertically integrated feedstock-to-reagent producers, pharmaceutical-grade certification specialists, and industrial-scale baseline feedstock suppliers. Competitive moves concentrate on long-term offtake agreements and captive distillation asset investments.
Within the integrated tier, Cambridge Isotope Laboratories exemplifies backward integration across deuterium gas and labeled compound production. Merck KGaA anchors European pharmaceutical demand through controlled distribution to GMP-certified formulation sites. URENCO Limited occupies a position as the dominant industrial-scale enrichment capacity operator, supplying baseline feedstock to downstream labelers through gaseous centrifuge cascades.
| Leading Market Players |
|---|
| Cambridge Isotope Laboratories, Inc. |
| Merck KGaA |
| PerkinElmer, Inc. |
| JSC Isotope |
| Trace Sciences International |
| Medical Isotopes, Inc. |
| Omicron Biochemicals, Inc. |
| URENCO Limited |
| IsoSciences, LLC |
| Others |
Value Network & Pricing Analysis
Gaseous centrifuge cascade utilization rates above 85 percent at URENCO Limited and state-linked enrichment facilities create substantial scale economies that compress unit economics for baseline deuterium and carbon-13 feedstock. This concentration of industrial-scale capacity in the United States, Germany, and Russia establishes asymmetric pricing power where downstream compound manufacturers face take-it-or-leave-it contract terms or must invest in captive cryogenic distillation assets. Academic medical centers and national laboratory consortia absorb premium pricing for pharmaceutical-grade isotopes with full GMP documentation, while Indian generic API manufacturers prioritize cost efficiency in bulk deuterium procurement.
Pricing Analysis
After-sales service contracts for isotope ratio instrumentation calibration and maintenance drive lifetime value capture for analytical-grade suppliers. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and industrial-grade levels segments buyers by certification stringency, with FDA-validated batches commanding substantial premiums over ISO 17025-certified analytical lots. Cost compression in industrial-grade deuterium is intensifying because Indian and Chinese pharmaceutical clusters are negotiating volume-based contract structures. Research institutes exhibit lowest price sensitivity due to grant-funded procurement, while export-oriented generic manufacturers in Gujarat and Maharashtra demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpiling preferences dominate among US national laboratories and European pharmaceutical formulation sites, insulating against enrichment facility maintenance shutdowns and geopolitical supply disruptions. Feedstock supply concentrates in the United States, Germany, and Russia, with cryogenic distillation of carbon monoxide and electrolytic hydrogen separation drawing from natural gas and heavy water reactor sources. Single-source vulnerability runs through URENCO's dominance in industrial-scale centrifuge capacity. Distribution runs through controlled distributor networks for pharmaceutical-grade isotopes, while direct-to-laboratory e-commerce platforms are disintermediating analytical-grade channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser isotope separation convergence promises to disrupt gaseous centrifuge economics, while FDA and EMA tightening of GMP standards for radiopharmaceuticals accelerates certification requirements across the supply base.
For Market Incumbents: Consolidate long-term offtake agreements with national laboratory consortia before laser enrichment technology reaches commercial scale. Cambridge Isotope Laboratories and Merck KGaA should deepen backward integration into cryogenic distillation assets to defend margin capture against feedstock price volatility. EMA's tightened Annex 1 sterile manufacturing guidelines threaten to disqualify uncertified suppliers, making GMP investment the priority defensive lever.
For New Entrants and Emerging Players: Differentiate on laser isotope separation technology to exploit energy intensity advantages over centrifuge cascades for niche isotope production. India's CDSCO-streamlined API approval pathways offer the most penetrable geography for pharmaceutical-grade labeling investments. A direct-to-laboratory e-commerce go-to-market angle bypasses entrenched distributor relationships in analytical-grade segments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade certification specialists with locked GMP supply contracts to formulation sites. Long-term viability across the analysis window favors vertically integrated producers with captive enrichment capacity rather than downstream-only compound labelers. The signal to watch is CDSCO approval velocity for tracer compound programs, as acceleration would validate Indian manufacturing cluster expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Oak Ridge and Argonne consortia lock in multi-year deuterium and carbon-13 volumes. |
| Backward Integration | Cambridge Isotope Laboratories controls cryogenic distillation from heavy water reactor feedstock. |
| GMP Certification Investment | EMA Annex 1 compliance opens sterile injectable radiopharmaceutical supply to European formulation sites. |
| Technology Licensing | Laser isotope separation patents enable lower-energy niche production outside centrifuge dominance. |
| Geographic Expansion | Gujarat and Maharashtra clusters leverage CDSCO pathways for export-oriented tracer production. |
Research Methodology
The analysis maps centrifuge enrichment, chemical exchange processing, and laser separation sub-sectors, each validated through enrichment facility operators, pharmaceutical formulation site procurement leads, and academic laboratory supply managers. Primary interviews with isotope ratio instrumentation technicians, GMP compliance officers at radiopharmaceutical manufacturers, and national laboratory contracting officers combined with secondary validation from FDA 483 inspection observations, EMA GMP inspection reports, and customs trade data for deuterated solvent imports. Bottom-up volume estimates from individual facility throughput and top-down cross-checks against national research funding allocations established triangulation boundaries.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation by isotope category, end-user vertical, application protocol, and detection technology platform, with regional regulatory cluster as an additional dimension. CAGRs were derived from fitted growth curves anchored to documented procurement contract values and facility capacity expansion announcements. Industry-specific forecast inputs included DOE national laboratory budget appropriations and CDSCO API approval velocity indices.
The analysis sits within stated boundaries; outcomes outside sustained academic research funding levels or stable enrichment facility operating rates would require recalibration. Forecasts reflect assumptions about laser enrichment technology maturation timelines and continued GMP regulatory tightening trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Epoxidized Soybean Oil Market