
 Mequinol Market | 2026-2036
Mequinol Market Size, Share, and Industry Trends Forecast 2026-2036
Mequinol Market Insights
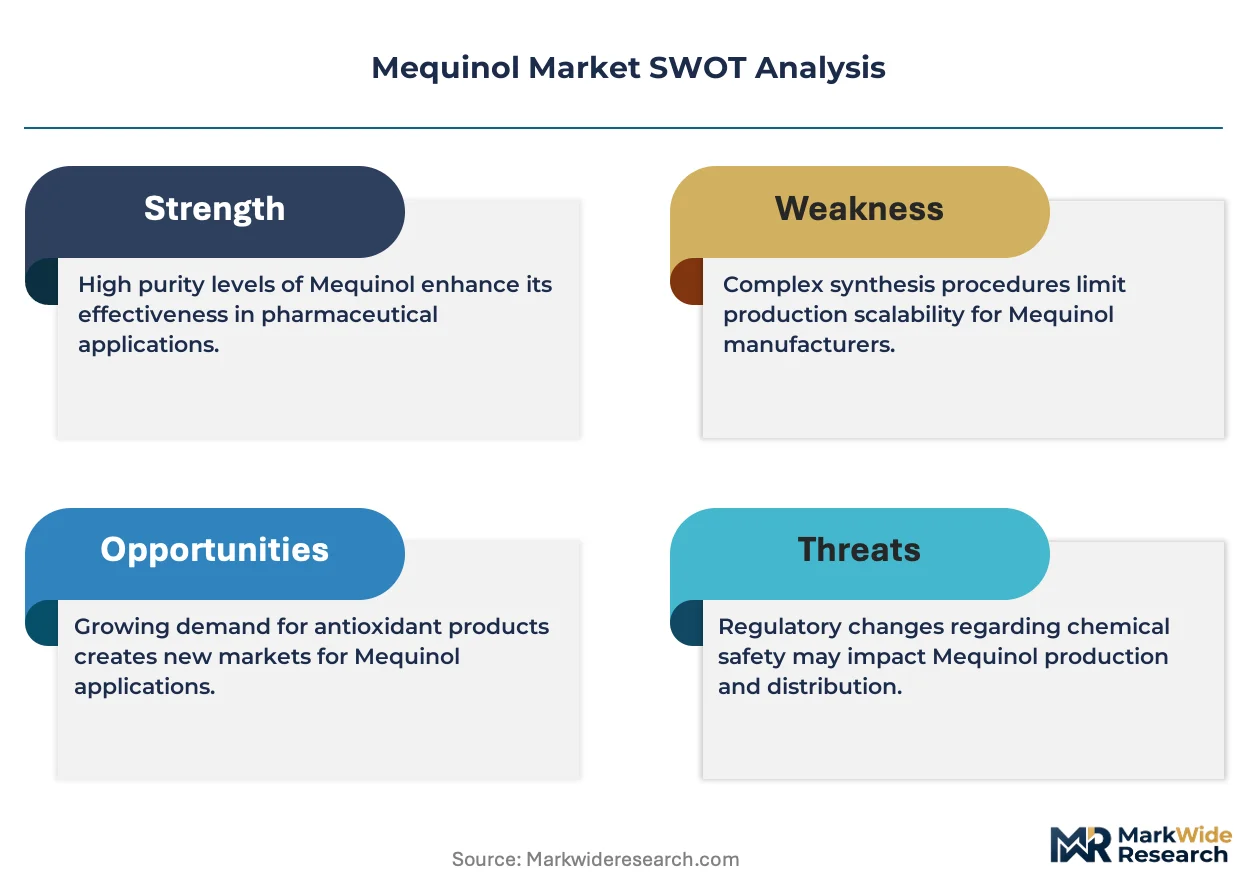
Specialty chemical producers in China and India is broadening upstream access to mequinol precursors. Syensqo leverages backward integration into phenol derivative chains to secure feedstock reliability. Merck sustains European pharmaceutical-grade certification that anchors premium positioning. Brother Enterprises Holding Co. Ltd. dominates bulk active pharmaceutical ingredient output for Asian dermatology formulators.
Mequinol, or 4-methoxyphenol, functions as a depigmenting agent and polymerization inhibitor with a molecular formula of C7H8O2 and melting point near 55°C. Cosmetic applications lead volume consumption through topical cream and serum formats targeting hyperpigmentation disorders. Dermatological treatment channels command superior margins due to prescription-grade purity requirements and clinician oversight. Hair growth applications represent an emerging segment where mequinol serves as a cofactor in follicle stimulation protocols.
FDA oversight governs mequinol concentration limits in over-the-counter cosmetic preparations in the United States, while REACH registration mandates toxicity documentation for European chemical imports. EMA guidelines further restrict prescription-grade mequinol formulations to licensed dermatological practitioners. Stakeholders must monitor evolving purity standards across multiple regulatory jurisdictions to sustain market access and avoid formulation reformulation costs.
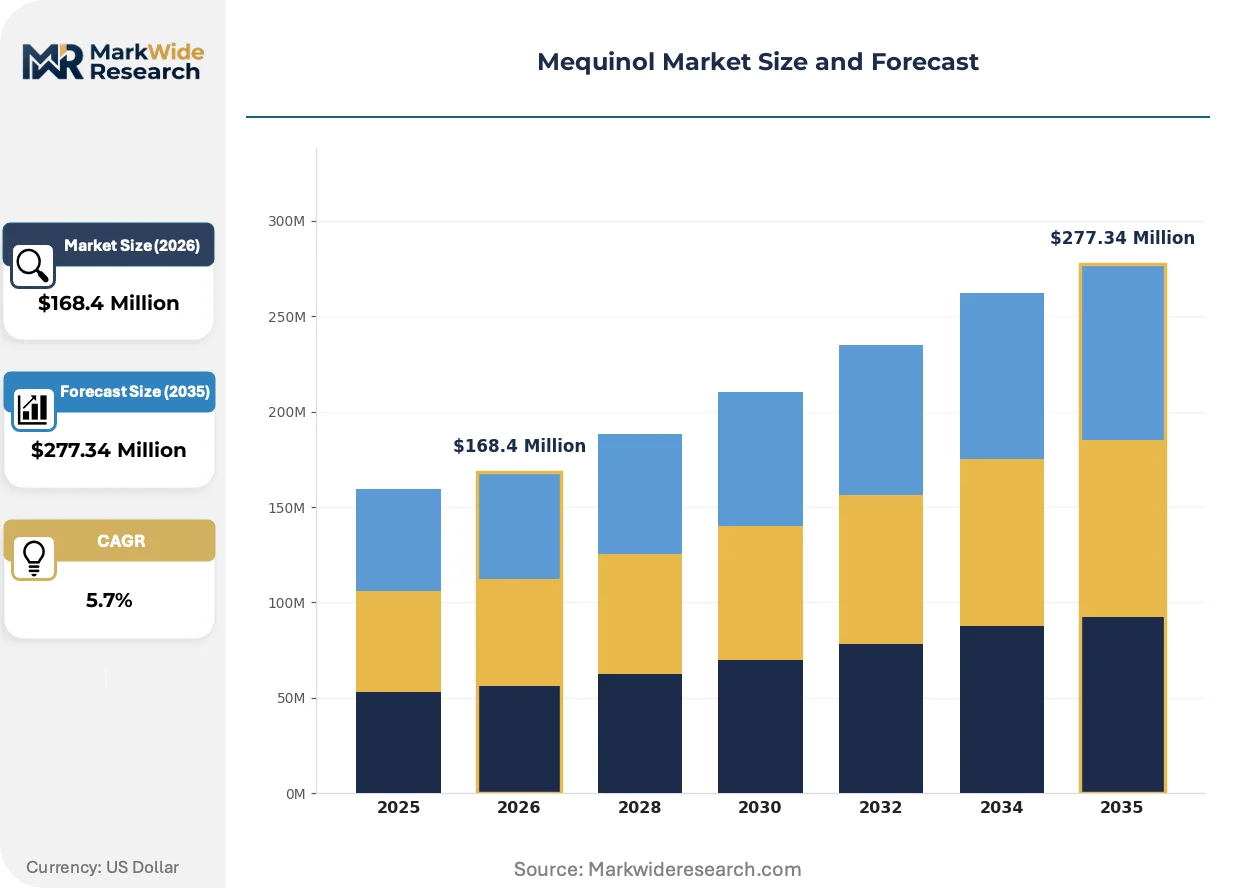
Market Dynamics
REACH and RoHS compliance requirements in Europe are forcing reformulation investments across the mequinol supply chain, while FDA concentration limits in the United States reshape product development priorities for cosmetic and dermatological applications.
Growth Catalysts
- Dermatological treatment protocols:Prescription-grade depigmentation therapies in clinical settings drive premium-grade demand. Clinician oversight ensures sustained volume through therapeutic channels.
- REACH registration mandates:European chemical import documentation requirements elevate barrier-to-entry for non-compliant suppliers. Certified producers capture expanded market access.
- Polymerization inhibitor applications:Industrial chemical manufacturing in Asia-Pacific absorbs technical-grade output. Specialty polymer production lines require consistent antioxidant feedstock.
Market Restraints
- Phenol derivative feedstock volatility:Crude oil-linked aromatic chemical pricing compresses margin predictability for mequinol manufacturers. Backward integration into phenol chains mitigates exposure.
- Supplier concentration in East Asia:Bulk active pharmaceutical ingredient production clusters in China and India create geographic risk. Single-source dependencies amplify disruption vulnerability.
- Hydroquinone substitution pressure:Established depigmentation agents compete on cost in emerging markets. Price-sensitive cosmetic formulators switch where regulatory thresholds permit.
Strategic Opportunities
- Follicle stimulation protocols:Hair growth applications represent nascent demand expansion. Mequinol cofactor functionality opens aesthetic medicine channels beyond pigmentation.
- EMA prescription-grade pathways:Licensed dermatological practitioner restrictions create premium positioning. Compliance investment separates pharmaceutical-grade from cosmetic-grade suppliers.
- Direct-to-clinic distribution models:Cosmetic clinic channels in the United States bypass traditional wholesale structures. Manufacturer-clinic relationships capture margin otherwise lost to intermediaries.
Industry Challenges
- Multi-jurisdiction purity standard harmonization:FDA, EMA, and national pharmaceutical regulators impose divergent analytical specifications. Reformulation costs accumulate across export markets.
- Pharmaceutical-grade certification timelines:GMP compliance documentation delays market entry for new production facilities. Capital remains committed during extended approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mequinol Market |
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $277.34 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Cream, Serum, Lotion, Solution Application: Cosmetic, Dermatological Treatment, Hair Growth, Skin Lightening End User: Individuals, Dermatologists, Cosmetic Clinics, Aesthetic Professionals Distribution Channel: Online Retail, Pharmacies, Beauty Stores, Hospitals |
| Companies Covered | Syensqo, Kishida Chemical Co.,Ltd., Merck, Brother Enterprises Holding Co. Ltd., Sheerherb Biological Technology Co., Ltd., MUBY CHEMICALS, Camlin Fine Sciences Ltd., Manus Aktteva Biopharma LLP, Clean Science and Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mequinol Market Trends and Innovations
Microencapsulation technologies are expanding into topical delivery systems, while regulatory data requirements intensify and procurement patterns shift toward certified single-source relationships.
Liposomal encapsulation systems for mequinol are expanding into high-end cosmetic formulations. Premium skincare brands in South Korea and Japan adopt these delivery mechanisms to enhance stability and reduce irritation potential. The technology is expanding into dermatological-grade products previously limited to conventional cream bases.
REACH toxicity documentation mandates now require extended ecotoxicological datasets for phenol derivative imports into Europe. ECHA evaluation deadlines compress registration preparation windows for Asian chemical exporters. Small-volume specialty producers face consolidation pressure or partnership requirements to share testing costs.
Cosmetic clinic procurement departments now prioritize suppliers with dual FDA-EMA certification over price-competitive alternatives. United States dermatology practices consolidate vendor lists to reduce compliance audit burden. Certificate-of-analysis consistency outweighs marginal cost savings in purchasing decisions.
Mequinol Market Segmentation
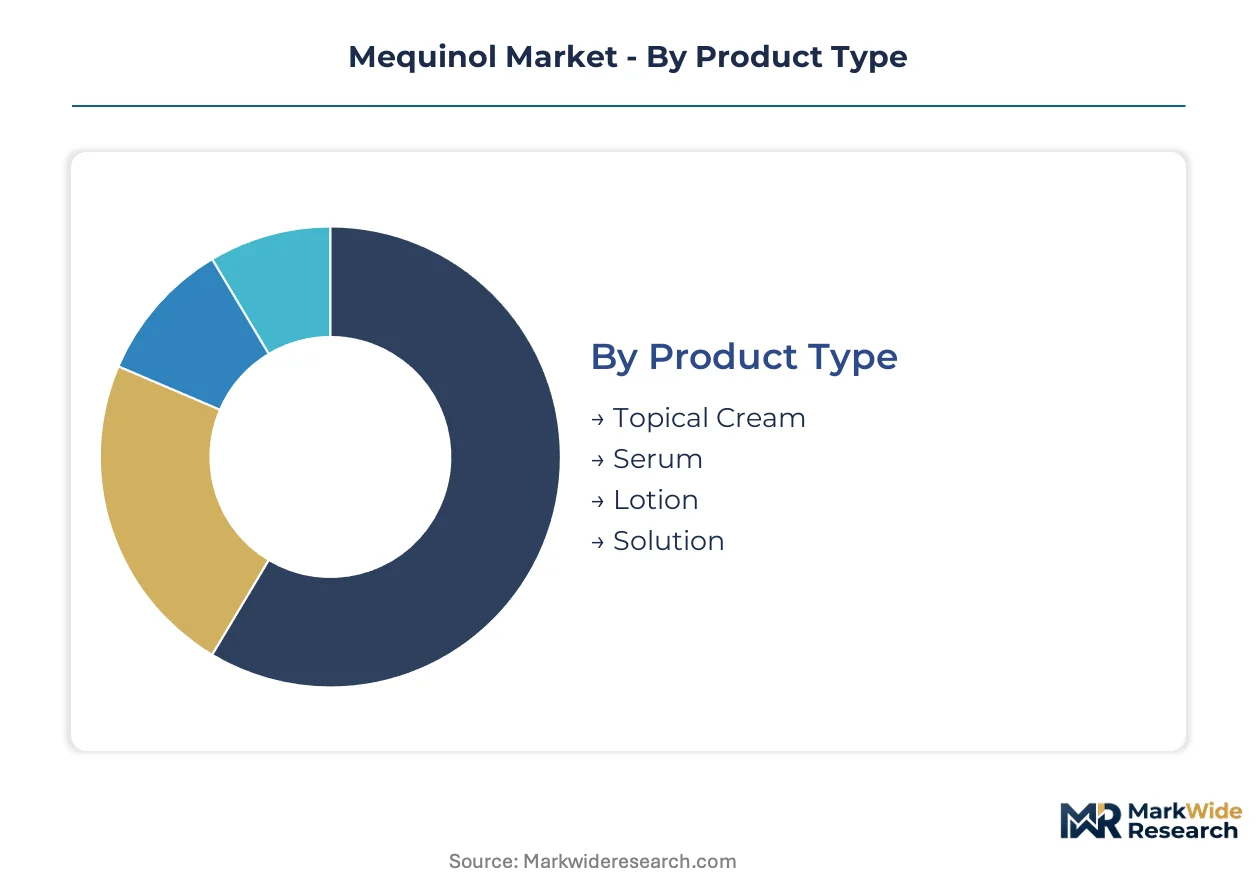
Mequinol's dual identity as both pharmaceutical-grade depigmenting agent and industrial polymerization inhibitor fragments demand across radically different customer specifications. Formulators must navigate purity grades spanning cosmetic over-the-counter thresholds to prescription-grade clinician protocols. Segmentation clarity determines which production assets and certification investments align with specific revenue pools.
Product Type:
Customization intensity spans from mass-manufactured solutions to precision-formulated serums requiring stability engineering and encapsulation technology.
- Topical Cream:Oil-in-water emulsions dominate mass-market cosmetic distribution through pharmacy and retail channels. United States cosmetic clinics absorb the largest volume of prescription-grade cream formulations due to FDA concentration oversight and clinician-mediated dispensing requirements. Cream bases accommodate higher mequinol loadings while maintaining oxidative stability through antioxidant co-formulation.
- Serum:Aqueous or hydro-alcoholic vehicles demand sophisticated stabilization protocols given mequinol's phenolic susceptibility to oxidation. South Korean and Japanese premium skincare brands drive serum innovation through liposomal encapsulation systems that enhance dermal penetration and reduce irritation potential. Serum formats command superior unit economics in aesthetic medicine channels.
- Lotion:Lower viscosity vehicles suit larger body-surface-area applications in institutional dermatological settings. Lotion formulations spread across European hospital procurement systems where REACH-compliant documentation accompanies bulk purchasing agreements.
- Solution:Simplest vehicle composition serves industrial polymerization inhibitor applications and technical-grade cosmetic manufacturing. Solution formats concentrate in Asian bulk active pharmaceutical ingredient production for downstream formulator processing.
Leading the category by volume: Topical Cream. Expanding most quickly: Serum.
Application:
Margin structure inverts across this dimension, with industrial applications absorbing technical-grade output at commodity economics while clinical protocols sustain premium pricing through regulatory capture.
- Cosmetic:Over-the-counter hyperpigmentation products operate under FDA concentration ceilings and state-level cosmetic manufacturing licenses. Cosmetic applications generate the highest absolute volume but compress margins through retail channel markups and competitive substitution pressure from hydroquinone alternatives.
- Dermatological Treatment:Prescription-grade depigmentation protocols require pharmaceutical manufacturing certifications and clinician oversight. EMA restrictions in Europe limit distribution to licensed practitioners, creating artificial scarcity that sustains price premiums. Dermatological channels absorb the purest mequinol grades with certificate-of-analysis documentation for every lot.
- Hair Growth:Emerging cofactor applications in follicle stimulation protocols represent nascent demand expansion beyond traditional pigmentation indications. Hair growth applications concentrate in United States aesthetic medicine practices experimenting with combination therapies.
- Skin Lightening:Distinct from general hyperpigmentation treatment, skin lightening applications target elective aesthetic outcomes rather than pathological conditions. Regulatory scrutiny intensifies in this space, with some jurisdictions restricting marketing claims or available concentrations.
Generating the highest margins: Dermatological Treatment. Climbing the fastest: Hair Growth.
End User:
Procurement sophistication escalates from individual self-selection through institutional purchasing departments with audit-grade compliance requirements.
- Individuals:Direct consumers purchase through retail and online channels with minimal technical guidance. Individual buyers demonstrate high price sensitivity and limited loyalty, switching between brands based on packaging claims and promotional pricing.
- Dermatologists:Licensed practitioners prescribe and dispense prescription-grade formulations with therapeutic oversight. United States dermatology practices increasingly consolidate vendor relationships to reduce compliance documentation burdens, favoring suppliers with dual FDA-EMA certification.
- Cosmetic Clinics:United States cosmetic clinic channels bypass traditional wholesale structures through direct manufacturer relationships. Clinic procurement departments prioritize certificate-of-analysis consistency over marginal cost savings, creating defensible positions for certified suppliers.
- Aesthetic Professionals:Intermediate tier encompassing nurse practitioners, physician assistants, and licensed aestheticians operating under physician supervision. This segment fragments across state-level scope-of-practice regulations and facility licensing requirements.
Capturing the steepest expansion trajectory: Cosmetic Clinics. Representing the largest addressable population: Individuals.
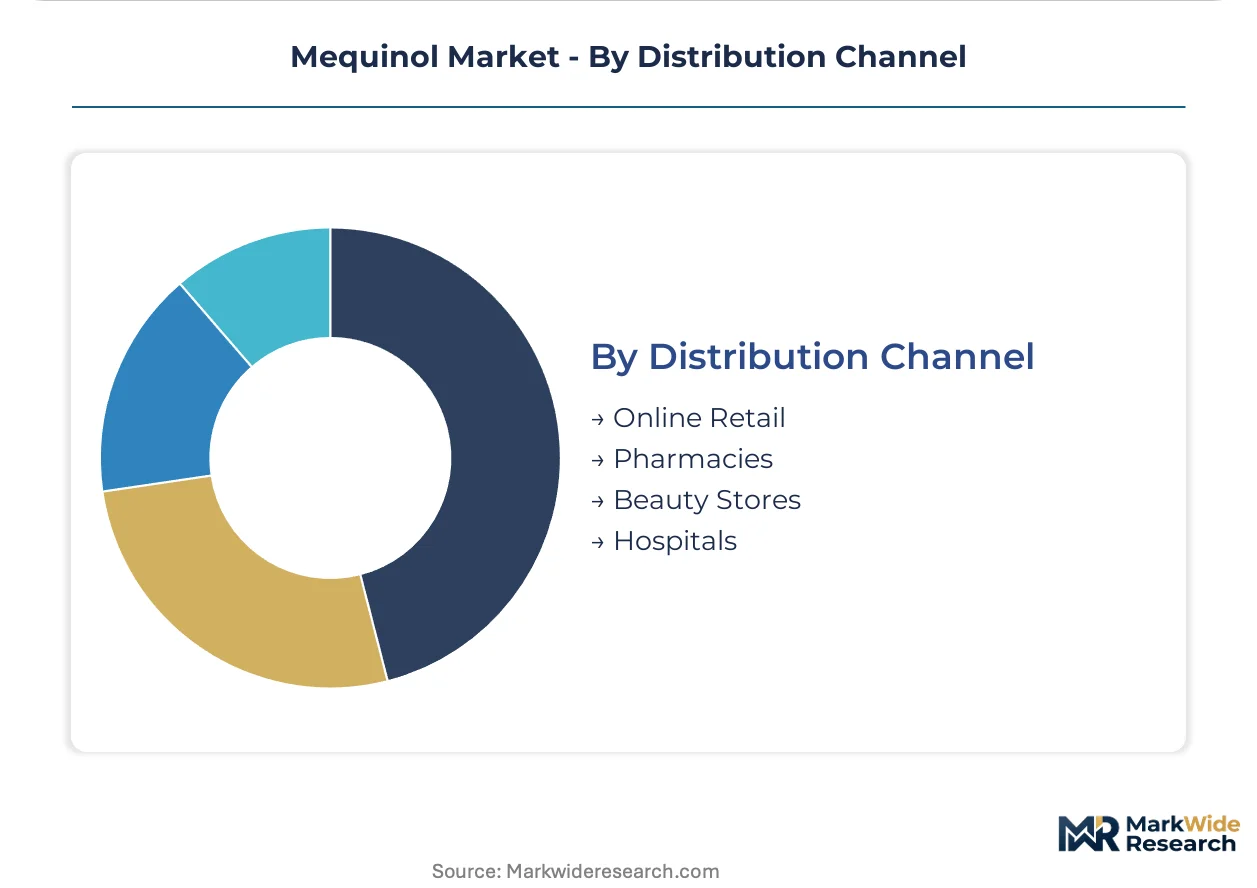
Distribution Channel:
Channel selection determines regulatory exposure, with hospital and pharmacy formats demanding pharmaceutical-grade documentation unavailable to beauty retail or unmediated online sellers.
- Online Retail:E-commerce platforms aggregate fragmented consumer demand but introduce counterfeiting risks and temperature-control failures during shipping. Online channels concentrate in direct-to-consumer cosmetic brands with subscription replenishment models.
- Pharmacies:Brick-and-mortar and mail-order pharmacy networks handle both over-the-counter cosmetic grades and prescription dermatological formulations. Pharmacy procurement systems require lot-level traceability and recall readiness protocols.
- Beauty Stores:Specialty retail environments emphasize experiential purchasing and brand storytelling. Beauty store channels suit premium serum and cream formats with packaging differentiation and in-store demonstration capabilities.
- Hospitals:Institutional procurement systems absorb lotion and solution formats for inpatient dermatological protocols. Hospital channels demand the most extensive documentation, including REACH toxicity datasets for European facilities and FDA drug establishment registration for United States acute care settings.
Commanding the highest throughput: Pharmacies. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phenol derivative production clusters in East Asia anchor mequinol feedstock availability, while regulatory divergence across North America and Europe fragments formulation standards and compliance investments.
United States
FDA concentration limits for over-the-counter cosmetic preparations and cosmetic clinic procurement consolidation drive prescription-grade demand. The agency's oversight of depigmentation therapies ensures clinician-mediated dispensing dominates therapeutic channels. New Jersey and North Carolina chemical manufacturing corridors absorb technical-grade imports for downstream pharmaceutical processing.
Germany
REACH registration mandates and ECHA toxicity documentation requirements elevate barrier-to-entry for phenol derivative imports. The country's pharmaceutical manufacturing base in Ludwigshafen and Leverkusen sustains demand for certified feedstock in dermatological formulations. German chemical distributors increasingly require dual FDA-EMA certification from Asian suppliers.
China
Bulk active pharmaceutical ingredient production concentrates in Zhejiang and Jiangsu provinces where phenol derivative supply chains integrate backward into petrochemical feedstock. NMPA pharmaceutical-grade certification timelines compress margin windows for domestic exporters. Shandong specialty chemical producers are expanding technical-grade output for polymerization inhibitor applications.
India
CDSCO pharmaceutical manufacturing licenses and state-level cosmetic production permits fragment regulatory compliance across Maharashtra and Gujarat production zones. Mumbai and Ahmedabad dermatology formulators source mequinol for hyperpigmentation therapies targeting domestic and export markets. Indian chemical producers are capturing share in technical-grade segments through cost-competitive phenol derivative processing.
South Korea
MFDS cosmetic ingredient safety assessments and premium skincare brand demand for liposomal encapsulation technologies drive high-purity imports. Seoul and Gyeonggi-do aesthetic medicine clusters absorb serum-format mequinol for hyperpigmentation protocols. South Korean formulators are pioneering stability-engineered delivery systems that reduce oxidation susceptibility in aqueous vehicles.
Mequinol Market Competitive Landscape
Global majors compete with regional champions across certification tiers, with pharmaceutical-grade producers facing divergent FDA and EMA documentation requirements while technical-grade suppliers compete on phenol derivative cost structures. The vendor base stratifies into three archetypes: backward-integrated phenol derivative producers, pharmaceutical-grade certification specialists, and bulk active pharmaceutical ingredient fabricators. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into hair growth cofactor applications.
Within the certification-specialist tier, Merck exemplifies European pharmaceutical-grade positioning through EMA-anchored quality systems, while Syensqo occupies the backward-integrated archetype with captive phenol derivative supply chains. Brother Enterprises Holding Co. Ltd. represents the scale-driven bulk producer segment serving Asian dermatology formulators with technical-grade output.
| Leading Market Players |
|---|
| Syensqo |
| Kishida Chemical Co.,Ltd. |
| Merck |
| Brother Enterprises Holding Co. Ltd. |
| Sheerherb Biological Technology Co., Ltd. |
| MUBY CHEMICALS |
| Camlin Fine Sciences Ltd. |
| Manus Aktteva Biopharma LLP |
| Clean Science and Technology Limited |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap phenol derivative producers in East Asia anchor supply discipline through captive feedstock positions, translating upstream control into pricing power across pharmaceutical-grade and technical-grade tiers. Their ownership structures resist quarterly margin pressure, enabling long-term contract stability that shapes competitive pricing behavior for downstream formulators.
Pricing Analysis
Certificate-of-analysis bundling separates premium-grade suppliers from unbundled technical-grade competitors, with dual FDA-EMA certification commanding substantial premiums over single-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and regulatory documentation depth. Pricing pressure stems from hydroquinone substitution in emerging markets where regulatory thresholds permit lower-cost depigmentation agents. Cosmetic clinic procurement departments demonstrate lowest price sensitivity, prioritizing lot-to-lot consistency over marginal cost savings.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Shanghai coordinate hub-and-spoke patterns for phenol derivative feedstock flowing to formulation facilities. Bulk active pharmaceutical ingredient production concentrates in China, India, and Germany, drawing from crude oil-linked aromatic chemical inputs including phenol, methanol, and catalyst systems. Single-source vulnerability amplifies disruption risk where Zhejiang and Jiangsu province clusters dominate technical-grade output. Distribution runs through direct-to-clinic relationships in the United States alongside traditional pharmaceutical wholesale networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mequinol market functions as a vertical-integration race where backward control into phenol derivative chains determines feedstock security and margin predictability. Players are pursuing upstream captive supply as the decisive lever separating sustainable premium positioning from commodity-grade exposure.
For Market Incumbents: Hedge against phenol derivative feedstock volatility through backward integration into aromatic chemical production or long-term offtake agreements with Shandong and Zhejiang suppliers. Defensive consolidation around dual FDA-EMA certification protects premium positioning as EMA documentation requirements tighten entry barriers for uncertified competitors. For New Entrants and Emerging Players: Cosmetic clinic direct-distribution partnerships in the United States offer the most penetrable white-space target, bypassing wholesale intermediaries that dominate established channels. Hair growth cofactor applications represent underdeveloped demand expansion beyond traditional pigmentation indications, with aesthetic medicine practices experimenting with combination therapies. For Investors and Strategic Acquirers: REACH registration deadline acceleration is the leading indicator that consolidation pressure will intensify for small-volume specialty producers lacking testing cost-sharing partnerships. Acquisition targets with captive phenol derivative supply and existing EMA quality systems offer superior long-term viability through regulatory capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Derivatives | Syensqo's captive supply chain secures feedstock reliability against crude oil-linked volatility. |
| Dual FDA-EMA Certification Investment | Merck's pharmaceutical-grade positioning anchors premium pricing through regulatory documentation depth. |
| Direct-to-Clinic Distribution Expansion | United States cosmetic clinic relationships capture margin otherwise lost to wholesale intermediaries. |
| Liposomal Encapsulation Technology Adoption | South Korean premium skincare brands pioneer stability-engineered delivery systems reducing oxidation susceptibility. |
| Hair Growth Cofactor Application Development | Aesthetic medicine channels in the United States open demand expansion beyond pigmentation indications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with plant managers at phenol derivative facilities, procurement leads at dermatology formulators, distribution channel partners in pharmaceutical wholesale, and technical R&D directors at encapsulation technology developers. ECHA registration databases, FDA drug establishment records, CDSCO manufacturing licenses, and SEC 10-K disclosures from listed chemical producers provided validation layers. Bottom-up volume aggregation across grade tiers reconciled with top-down market sizing from trade flow analysis.
Data-stream reconciliation across production volume, import-export flows, and end-use consumption patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include purity grade tier, application channel, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical trade data adjusted for capacity expansion announcements and regulatory timeline shifts. Phenol derivative pricing indices and REACH registration completion rates served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including force majeure disruptions at Zhejiang production clusters, abrupt REACH substance restriction amendments, and currency fluctuation impacts on Asian export competitiveness. Forecasts reflect documented assumptions around regulatory timeline adherence and capacity utilization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market