
 Advertising-Based Video on Demand Market | 2026-2036
Advertising-Based Video on Demand Market Size, Share, and Industry Trends Forecast 2026-2036
Advertising-Based Video on Demand Market Analytics
Connected TV advertising inventory is tilting decisively from subscription-funded toward ad-supported monetization models. YouTube, LLC leverages its Google Ads integration to dominate programmatic video ad buying across living-room screens. Roku, Inc. anchors its position through proprietary operating system control and first-party viewer data from The Roku Channel. Pluto TV competes by extending its free linear-style channels across multiple OEM platforms and FAST distribution deals.
Advertising-Based Video on Demand refers to streaming video services that deliver content to viewers without subscription fees, instead monetizing through inserted advertisements served via programmatic or direct-sold campaigns, typically measured by impressions completed and frequency-capped per viewer session. The primary commercial purpose is to capture cord-cutter and cord-never audiences unreachable through traditional broadcast while offering advertisers granular targeting and attribution. Free Ad-Supported Streaming currently occupies the largest share of service type revenue as consumers trade subscription fatigue for intermittent ad exposure. Over-the-Top delivery leads the delivery model landscape, though Hybrid approaches combining linear and on-demand elements are gaining traction among platforms seeking to replicate cable's passive viewing experience. Home Users represent the dominant user type, yet Corporates are emerging as a specialized segment for internal communications and training content monetization.
The Federal Communications Commission shapes market access through political advertising disclosure rules and children's programming requirements that AVOD platforms must navigate. The European Union's Digital Services Act and GDPR impose content moderation and data handling standards that restrict personalized ad targeting precision across member states. India's Ministry of Information and Broadcasting and the Telecom Regulatory Authority of India exercise overlapping jurisdiction over content classification and advertising time limits on streaming services. Stakeholders must monitor how fragmented national regulations around data localization and content quotas will force platform architecture decisions and geographic service segmentation.
Market Dynamics
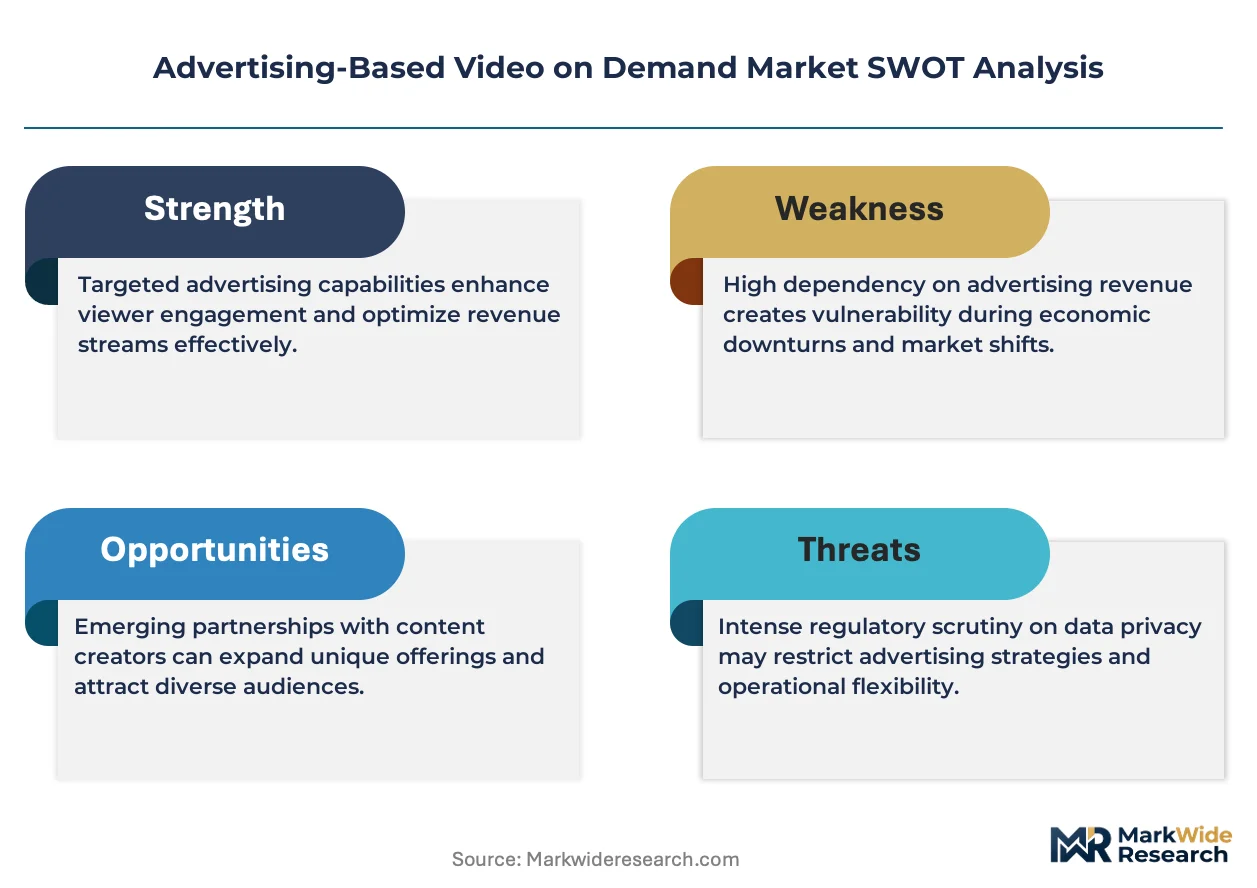
Programmatic advertising infrastructure is consolidating around first-party data assets as third-party cookie deprecation forces AVOD platforms to rebuild targeting capabilities on authenticated viewer relationships.
Growth Catalysts
- EU Digital Services Act compliance:Platforms investing in content moderation tools ahead of enforcement deadlines are capturing brand safety budgets from risk-averse advertisers seeking verified inventory.
- Connected TV penetration:Smart TV OEMs pre-installing AVOD applications are reducing customer acquisition costs for ad-supported services across living-room screens.
- Programmatic guaranteed deals:Automated buying workflows are displacing manual insertion orders, compressing sales cycles and unlocking mid-market advertiser participation.
Market Restraints
- GDPR consent friction:European viewers must explicitly authorize data processing, degrading addressable match rates and depressing CPM realization in member states.
- Server-side ad insertion costs:Latency requirements for live streaming demand specialized CDN infrastructure, elevating technology spend versus client-side alternatives.
- Measurement fragmentation:Disconnected currency providers Nielsen, iSpot, and VideoAmp produce conflicting reach metrics, complicating cross-platform campaign planning.
Strategic Opportunities
- Brazil programmatic infrastructure:MercadoLibre and local DSPs are building demand-side depth that AVOD platforms can tap for Portuguese-language inventory monetization.
- Shoppable video integration:Product discovery layers embedded in streaming interfaces are converging entertainment and commerce, opening direct-response advertiser segments.
- Corporate training verticals:Enterprises are licensing white-label AVOD architectures for internal communications, creating recurring SaaS revenue streams beyond consumer advertising.
Industry Challenges
- Ad operations talent scarcity:Programmatic video specialists command premium compensation, constraining platform expansion velocity in secondary markets.
- Legacy broadcast integration:Media conglomerates operating dual linear and streaming stacks face workflow duplication, delaying unified yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advertising-Based Video on Demand Market |
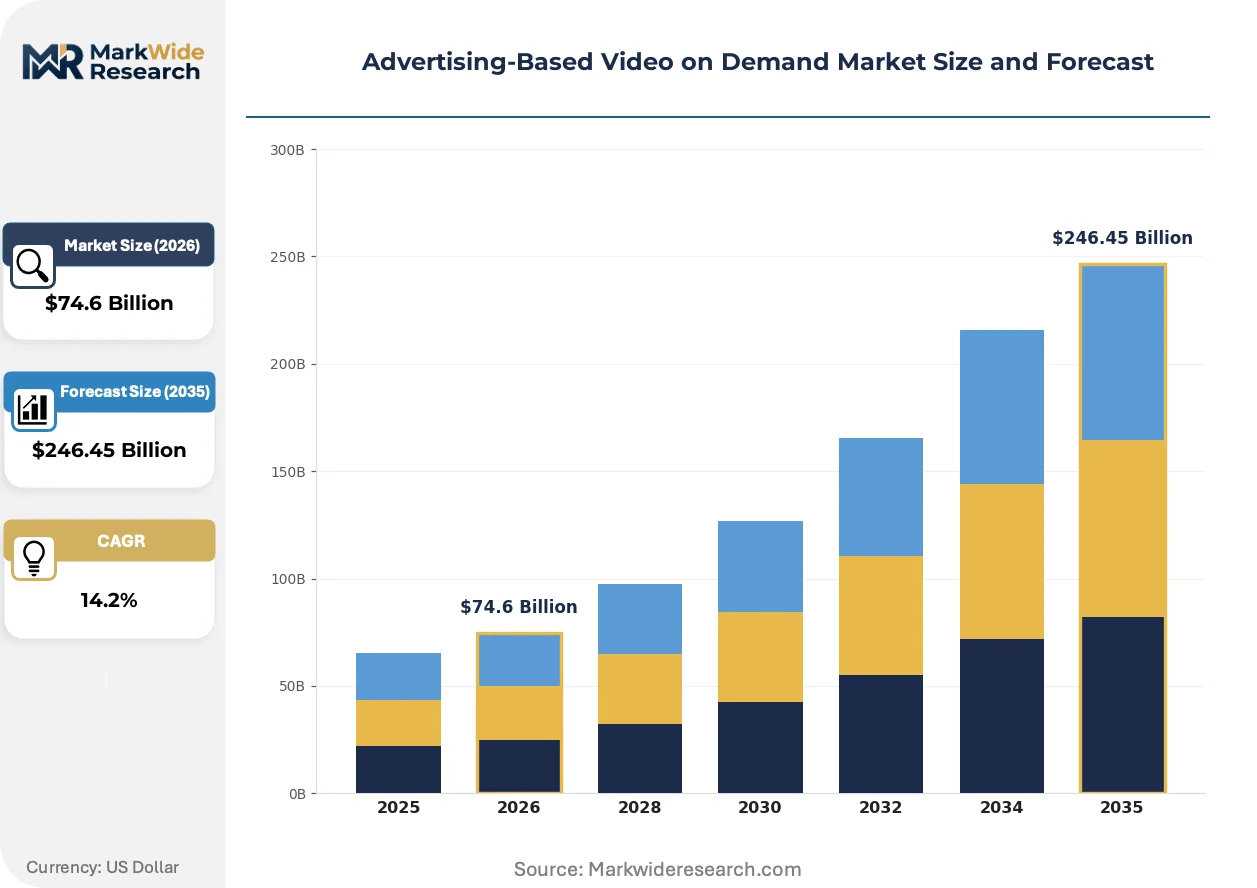
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $246.45 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transactional Video on Demand, Subscription Video on Demand, Free Ad-Supported Streaming, Premium Video on Demand Content Type: Movies, TV Shows, Documentaries, Sports User Type: Home Users, Educational Institutions, Corporates, Government Agencies Delivery Model: Over-the-Top, Direct-to-Consumer, Hybrid, Linear |
| Companies Covered | Roku, Inc., YouTube, LLC, Hulu, LLC, Pluto TV, Amazon Freevee, Tubi TV, The Roku Channel, Peacock, Xumo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advertising-Based Video on Demand Market Evolving Landscape
Artificial intelligence is restructuring how AVOD platforms match inventory to advertiser intent, compressing the path from content consumption to commercial impression.
Server-side ad insertion technology is hybridizing live and on-demand workflows, enabling seamless pod replacement across programming types. Broadcasters migrating sports rights to streaming are adopting these unified pipelines to preserve frame-accurate cue tone fidelity. The result collapses previously separate engineering teams and infrastructure contracts into single-platform architectures.
India's Ministry of Information and Broadcasting content classification mandates are forcing platform localization investments. Streaming services must deploy age-gating interfaces and parental controls that satisfy self-regulatory body compliance before licensing theatrical releases. Domestic platforms are responding faster than multinational entrants, capturing regional language content exclusives.
Advertiser procurement patterns are gravitating toward outcome-based guarantees that tie payment to verified business metrics rather than completed views. Consumer brands in the CPG sector are piloting these structures for product launch campaigns, pressuring platforms to integrate attribution data from retail loyalty programs. Brazil and Mexico exhibit the fastest migration toward these performance-linked contracts.
Advertising-Based Video on Demand Market Segmentation
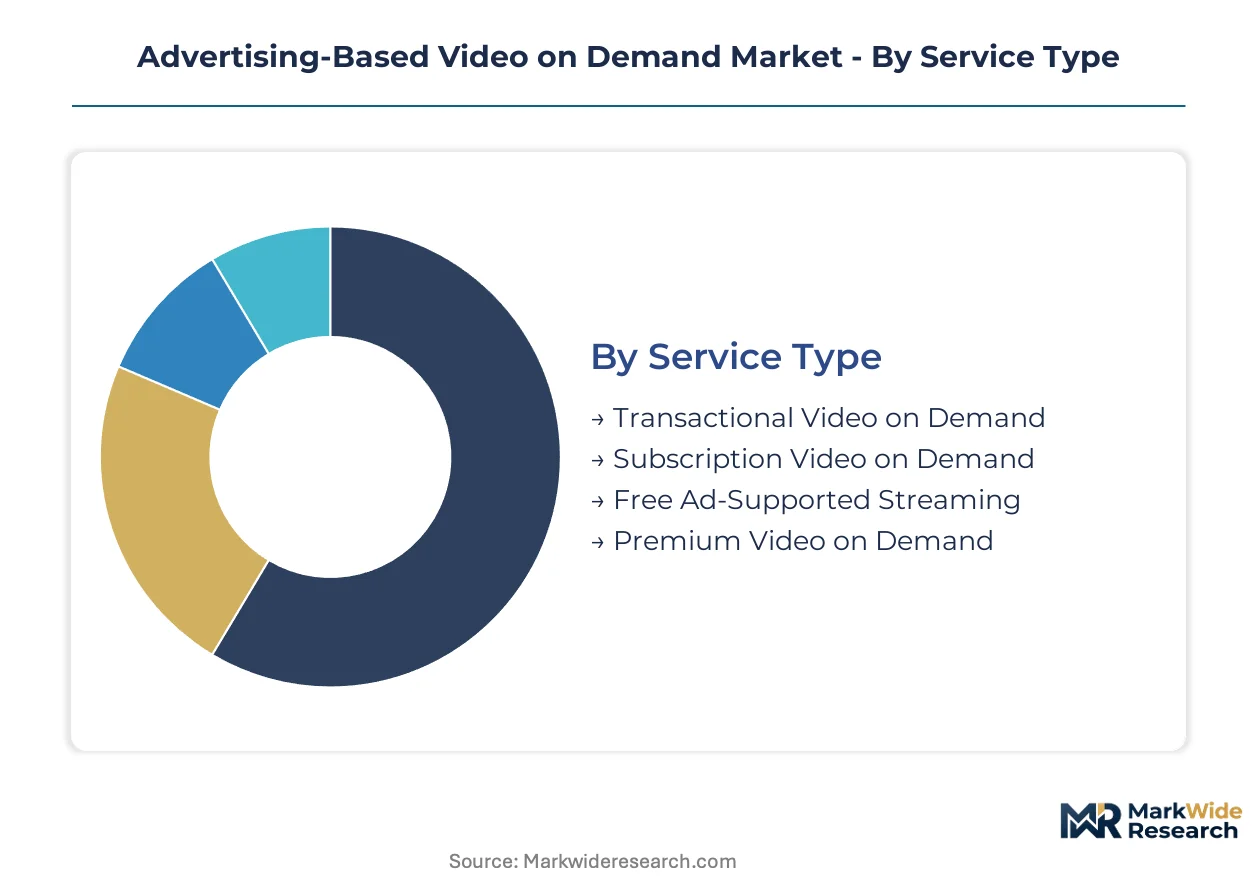
Segmentation in the AVOD market reveals how monetization mechanics, content formats, and delivery infrastructure align with distinct viewer behaviors and advertiser requirements. Each dimension exposes different cost structures, addressable audience pools, and technical dependencies that shape platform strategy.
Service Type:
AVOD platforms deploy across a use-case spectrum spanning impulse purchases, recurring subscriptions, ad-supported free tiers, and premium early-access windows.
- Free Ad-Supported Streaming:Delivers linear-style channel bundles and on-demand libraries without subscription barriers, monetizing exclusively through programmatic and direct-sold advertising. Demand concentrates among cord-cutters in the United States, India, and Brazil as subscription fatigue drives viewer migration toward zero-cost alternatives with tolerable ad loads.
- Subscription Video on Demand:Combines monthly fees with reduced or tiered advertising exposure, typically offering ad-light or ad-free premium tiers alongside discounted ad-supported options. Advertiser interest clusters around these hybrid subscribers who demonstrate higher lifetime value and brand engagement metrics than purely free users.
- Transactional Video on Demand:Enables single-title rental or purchase without ongoing commitment, embedding pre-roll or mid-roll ads to subsidize lower per-title pricing. Studios leverage this format for theatrical windowing and catalog monetization of older releases.
- Premium Video on Demand:Provides early access to theatrical releases at elevated price points, occasionally incorporating limited advertising to offset production marketing costs. This segment serves event-viewing occasions and franchise releases where fan urgency overrides price sensitivity.
Established volume favors Free Ad-Supported Streaming; emerging adoption favors hybrid Subscription Video on Demand tiers with ad-supported options.
Content Type:
Content investment priorities reflect production cost differentials, licensing leverage, and advertiser category alignment across programming genres.
- TV Shows:Serialized episodic content generates sustained viewer retention and repeat session frequency, enabling higher ad inventory density per user. Binge-release models and weekly drops both attract distinct advertiser budgets from CPG brands seeking sustained reach.
- Movies:Feature-length content commands premium CPMs for theatrical tie-in campaigns and automotive brand associations, though inventory is constrained by lower per-title rewatch rates. Library depth and exclusive licensing deals differentiate platform positioning.
- Documentaries:Niche but high-engagement programming attracts educated demographics and cause-aligned advertisers, with lower production costs enabling volume experimentation.
- Sports:Live event programming delivers scarce, high-attention inventory with deterministic audiences, though rights costs and server-side ad insertion infrastructure demands elevate platform investment thresholds.
TV Shows dominate inventory volume; Sports commands the steepest CPM expansion trajectory as live streaming scales.
User Type:
Customer segmentation separates consumer entertainment demand from institutional applications with distinct procurement workflows and content moderation requirements.
- Home Users:Individual households consuming entertainment content across connected TVs, mobile devices, and desktop browsers, generating the core advertising revenue base for AVOD platforms. This segment's fragmentation across devices complicates frequency capping and attribution modeling.
- Corporates:Enterprises licensing white-label streaming architectures for internal communications, training content distribution, and town hall broadcasts, creating SaaS revenue streams beyond consumer advertising. Compliance requirements around data residency and access logging differentiate vendor selection.
- Educational Institutions:Universities and K-12 systems utilizing ad-supported or institutionally licensed content for curriculum supplementation, with COPPA and GDPR-K constraints limiting targeting precision for underage viewers.
- Government Agencies:Public sector entities deploying secure streaming for citizen communications, emergency broadcasts, and archival access, prioritizing content authenticity verification and infrastructure resilience.
Home Users anchor current revenue; Corporates are climbing the fastest as internal communications budgets shift from legacy video conferencing to streaming-native platforms.
Delivery Model:
Infrastructure architecture choices determine content control, data ownership, and partnership dependencies across the distribution stack.
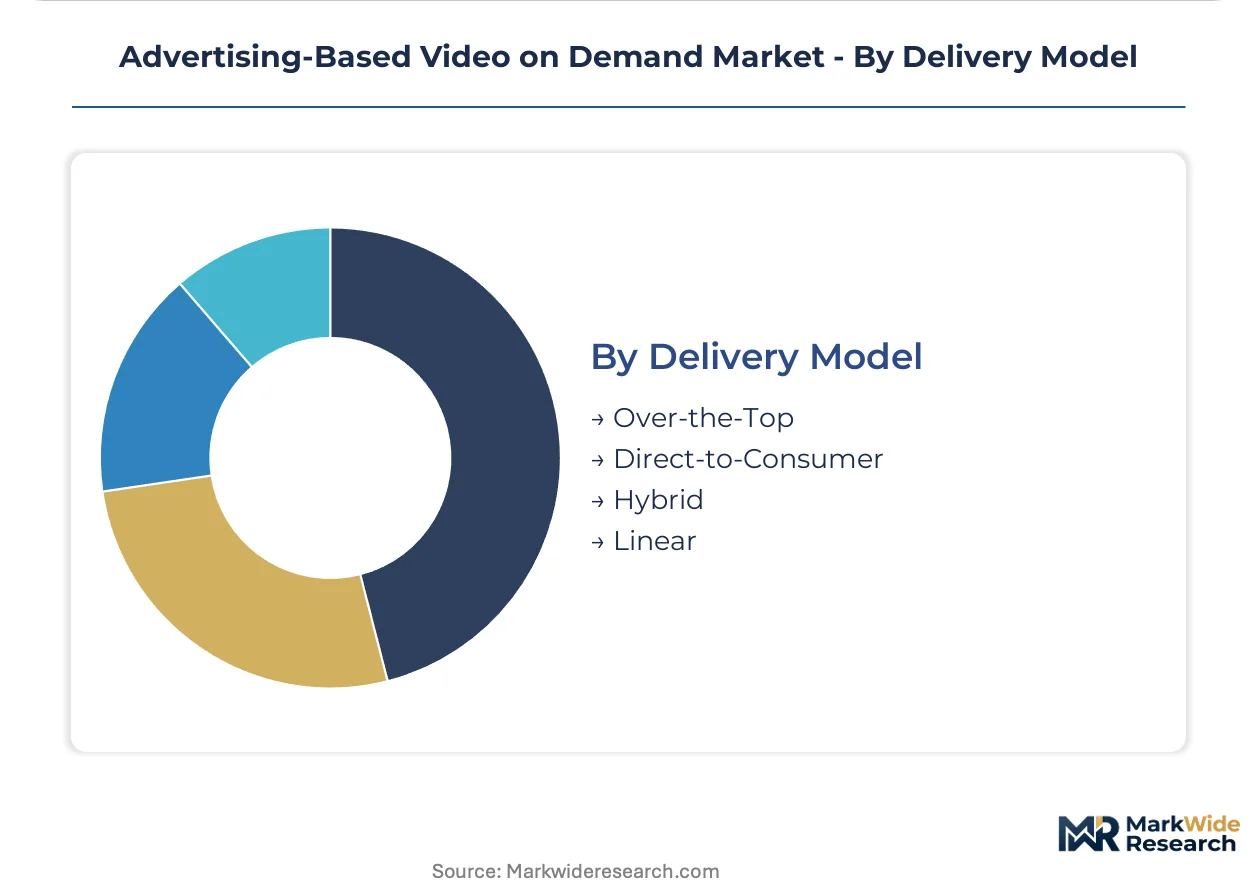
- Over-the-Top:Internet-delivered streaming bypassing traditional broadcast and cable distribution, enabling direct viewer relationships and first-party data capture. This model dominates AVOD scale as smart TV penetration and broadband expansion reduce technical barriers.
- Hybrid:Combines linear scheduled programming with on-demand libraries, replicating cable's passive viewing experience while preserving digital advertising targeting. FAST channel integrations and vMVPD partnerships extend reach without proprietary infrastructure.
- Direct-to-Consumer:Platform-owned apps and websites maintaining exclusive control over user experience, subscription billing, and advertising yield. Higher customer acquisition costs are offset by superior data granularity and margin retention.
- Linear:Traditional scheduled broadcast delivered through digital simulcast or vMVPD carriage, preserving existing content workflows while accessing streaming advertising budgets. This model is contracting as pure-play AVOD platforms capture migrating viewership.
Over-the-Top commands established deployment; Hybrid models are gaining share fastest as platforms seek to reduce churn through passive viewing habit formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertisers in the United States command CPM premiums three to four times higher than Brazilian inventory, yet São Paulo's programmatic infrastructure is compressing that gap faster than European regulators allow. This pricing-power asymmetry shapes where platforms deploy server-side ad insertion capacity and which markets attract shoppable video pilots first.
United States
Cord-cutter migration and connected TV penetration drive inventory expansion, with the FCC's political advertising disclosure rules and children's programming requirements forcing platform compliance investments. Los Angeles and New York anchor content production and ad tech development clusters where studios and demand-side platforms co-locate engineering teams.
India
Regional language content consumption and mobile-first streaming create addressable audience scale unmatched outside China, while TRAI advertising time limits and Ministry of Information and Broadcasting content classification mandates require localized interface investments. Mumbai and Bengaluru concentrate platform headquarters and self-regulatory body engagement where domestic services capture theatrical windowing exclusives faster than multinational entrants.
Brazil
MercadoLibre's retail media expansion and local DSP development deepen demand-side liquidity for Portuguese-language inventory, with ANVISA pharmaceutical advertising standards and consumer protection codes governing permissible creative categories. São Paulo's ad tech corridor attracts platform technical operations as performance-linked contracts displace impression-based buying.
Germany
GDPR consent friction degrades addressable match rates to levels that depress CPM realization versus comparable Northern European markets, yet the country's broadcast heritage sustains hybrid linear-on-demand viewer habits. Berlin and Cologne cluster public broadcaster streaming pivots and ad tech vendors rebuilding targeting on authenticated first-party relationships rather than third-party signals.
United Kingdom
Ofcom's prominence and due prominence rules for public service broadcasters extend to streaming simulcasts, shaping how platforms sequence advertising pods around news and current affairs content. London concentrates European headquarters for multinational AVOD services and the advertising agencies that place cross-border campaigns across Commonwealth language markets.
Advertising-Based Video on Demand Market Competitive Landscape
Digital-native platforms and legacy media conglomerates split the market between first-party data scale and content library depth. Consolidation pressure concentrates around connected TV operating system control and exclusive sports rights, with tiered competition separating global reach players from regional language specialists and hardware-anchored services. Dominant competitive moves include M&A to secure proprietary data assets and strategic partnerships with smart TV OEMs for pre-installation distribution.
Within the hardware-anchored tier, Roku, Inc. and YouTube, LLC exemplify divergent approaches to living-room screen monetization, with the former leveraging operating system control and the latter deploying search and retail media integration. Pluto TV occupies a position in the free linear-style channel segment, extending FAST distribution across multiple OEM platforms without proprietary device requirements. These three represent how platform architecture choices around data ownership and delivery infrastructure create defensible competitive positions.
| Leading Market Players |
|---|
| Roku, Inc. |
| YouTube, LLC |
| Hulu, LLC |
| Pluto TV |
| Amazon Freevee |
| Tubi TV |
| The Roku Channel |
| Peacock |
| Xumo |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber routes and CDN edge node placement costs determine how AVOD platforms tier their infrastructure investments, concentrating server-side ad insertion capacity in markets where advertiser CPMs justify latency-sensitive spend while pushing standard on-demand delivery toward commodity cloud regions.
Pricing Analysis
The customization-premium spread separates programmatic guaranteed deals from remnant auction inventory, with first-party data-enriched targeting commanding substantial markups over contextual-only placements. Price differentiation rests on authenticated viewer match rates and content exclusivity, particularly for live sports where deterministic audiences attract scarce inventory premiums. Pricing pressure intensifies in European markets where GDPR consent friction degrades addressable match rates. Mid-market advertisers exhibit highest price sensitivity, while CPG brands with outcome-based campaign structures demonstrate lowest sensitivity to CPM fluctuations.
Supply Chain Analysis
Supplier-financing arrangements through cloud infrastructure providers extend payment terms for compute-intensive transcoding and ad decisioning workloads, preserving platform cash flow for content licensing commitments. Geographic supply concentration centers on the United States, Ireland, and Singapore for hyperscale data center capacity. Raw material dependencies include fiber optic bandwidth, GPU acceleration hardware, and specialized CDN edge server deployments. Single-source vulnerability runs through smart TV operating system gatekeepers who control pre-installation distribution. Distribution runs through programmatic pipes, direct agency relationships, and retail media networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as subscription fatigue fragments viewer loyalty across multiple free tiers, creating niches for specialized content verticals and regional language services to capture underserved audience segments without competing head-on with generalist platforms.
For Market Incumbents: Build first-party data moats through authenticated viewer relationships and proprietary device graphs, insulating targeting capabilities from third-party signal deprecation. Consolidate FAST channel distribution through exclusive OEM pre-installation agreements. Expand server-side ad insertion infrastructure into Brazil and India where programmatic liquidity is deepening fastest. For New Entrants and Emerging Players: Build out corporate training verticals and white-label streaming architectures for enterprise internal communications, where procurement cycles favor specialized vendors over consumer platforms. Target educational institutions with COPPA-compliant, curriculum-aligned content bundles. Pursue sponsorship-funded local news as a go-to-market angle in mid-sized US media markets where broadcast heritage creates content cost advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with authenticated viewer scale and proprietary delivery infrastructure over pure content aggregators. Long-term viability hinges on operating system control or exclusive sports rights that lock in recurring advertiser commitments. Acquisition target archetype: regional AVOD services with theatrical windowing exclusives and self-regulatory body compliance infrastructure. Signal to watch: consolidation of measurement currency around a single verified provider.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Investment | Authenticated viewer relationships rebuild targeting precision as third-party cookies deprecate across Chrome and Safari. |
| Server-Side Ad Insertion Scale-Up | Unified pipelines for live and on-demand collapse engineering duplication while preserving frame-accurate cue tone fidelity for sports. |
| Smart TV OEM Pre-Installation Partnership | Roku, Samsung, and LG operating system control reduces customer acquisition costs and locks out competing services. |
| Regional Language Content Exclusive Licensing | Domestic platforms in India and Brazil capture theatrical windowing faster than multinational entrants constrained by localization timelines. |
| Corporate Training Vertical Expansion | White-label AVOD architectures for enterprise internal communications generate recurring SaaS revenue beyond consumer advertising cyclicality. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with AVOD platform executives, programmatic advertising specialists, and connected TV OEM partnership leads, combined with validation against TRAI advertising guidelines, FCC political disclosure filings, and EU Digital Services Act compliance documentation. Secondary sources included SEC filings from listed streaming services, hyperscaler capex disclosures for cloud infrastructure trends, and Nielsen alternative measurement provider competitive filings. Bottom-up inventory modeling and top-down advertising spend allocation triangulated market sizing.
Forecast inputs considered service type adoption curves, content licensing cost trajectories, and programmatic infrastructure penetration across the analysis window. Segmentation dimensions modeled included delivery model architecture, user type procurement workflows, and regional regulatory cluster stringency. CAGRs derived from logistic adoption curves for connected TV penetration crossed with advertiser budget shift elasticity estimates. Industry-specific inputs incorporated server-side ad insertion technology cost decline curves and self-regulatory body compliance timeline impacts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by retail media networks or smart TV OEMs launching proprietary ad-supported services would shift outcomes. Macroeconomic advertising recession, regulatory acceleration of data localization mandates, or breakthrough in privacy-preserving targeting technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Media Streaming Market