
 Global Transactional Video on Demand Market | 2026-2036
Global Transactional Video on Demand Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transactional Video on Demand Market Foresight
4K HDR premium-tier streaming is redrawing revenue expectations for transactional releases. Apple Inc. leverages its device ecosystem to anchor premium pricing for iTunes purchases. Amazon.com, Inc. sustains competitive rental volumes through Prime Video integration with its logistics and payment infrastructure. Warner Bros. Discovery, Inc. differentiates by controlling theatrical-to-digital windowing across its studio catalog.
Transactional Video on Demand denotes a digital content distribution model where consumers pay for individual title access without ongoing subscription commitments, typically delivered via adaptive bitrate streaming protocols supporting resolutions from 720p to 4K HDR with DRM encryption. Its primary commercial purpose is to monetize new release and catalog content outside subscription bundles while preserving per-title revenue visibility for rights holders. Movies dominate transaction volume as day-and-date theatrical releases compress, while Smart TVs anchor device compatibility due to built-in app ecosystems and superior display fidelity. Pay-Per-View and Pay-Per-Rental payment models capture the majority of consumer spend as flexibility outweighs ownership preferences in most markets.
The FCC in the United States governs net neutrality principles that affect streaming quality-of-service agreements between platforms and internet service providers. The EU AI Act and GDPR impose content recommendation transparency and personal data handling requirements on platforms operating across European member states. India's TRAI and BIS shape local platform obligations through broadband quality mandates and digital content standardization. Stakeholders must monitor evolving content licensing frameworks and data localization requirements as regulatory fragmentation intensifies platform compliance costs.
Market Dynamics
Compression of theatrical-to-digital release windows is restructuring content monetization economics, forcing studios to recalibrate per-title pricing power against subscription bundling gravity.
Growth Catalysts
- 4K HDR codec proliferation:Hardware decode support in Smart TV chipsets from MediaTek and Amlogic is lowering bandwidth costs for premium-tier streams. India and Brazil are seeing accelerated device refresh cycles.
- Germany's KBA content integrity mandates:Platform liability frameworks for digital distribution are clarifying rights-holder revenue transparency obligations. This reduces contractual friction for cross-border catalog licensing.
- Mobile wallet integration:India's UPI and Brazil's Pix are embedding one-click rental flows into carrier billing systems. Transaction abandonment rates are compressing in these payment ecosystems.
Market Restraints
- CDN egress cost volatility:Peering disputes between tier-1 ISPs in the United States and streaming platforms are injecting uncertainty into per-stream delivery economics.
- Codec licensing concentration:Patent pools administered by MPEG LA and Access Advance in the United States and Japan are extracting fixed per-device royalties that inflate Smart TV manufacturing costs.
- Subscription bundle substitution:Disney+ and Netflix hybrid tiers in the United States and Western Europe are capturing day-and-date releases that previously supported transactional pricing premiums.
Strategic Opportunities
- Indonesia's underpenetrated broadband:Palapa Ring fiber completion is creating first-time addressable households for 4K streams outside Java's urban core.
- EU AI Act recommendation transparency:Content discovery algorithms face audit requirements that favor independent title surfacing over catalog concentration. Niche distributors gain visibility leverage.
- Edge compute and 5G broadcast convergence:South Korea's KT and SK Telecom are trialing multicast delivery for live events, reducing last-mile congestion for concurrent release windows.
Industry Challenges
- DRM interoperability fragmentation:Widevine, FairPlay, and PlayReady implementation inconsistencies across Smart TV firmware versions are elevating customer service costs for platform operators.
- Content localization pipeline bottlenecks:Dubbing and subtitling capacity constraints in Thai, Vietnamese, and Bahasa Indonesia are delaying catalog availability in Southeast Asian markets.
- Legacy payment reconciliation systems:Studio royalty accounting platforms built for physical media are misaligning with real-time streaming transaction data, creating audit disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transactional Video on Demand Market |
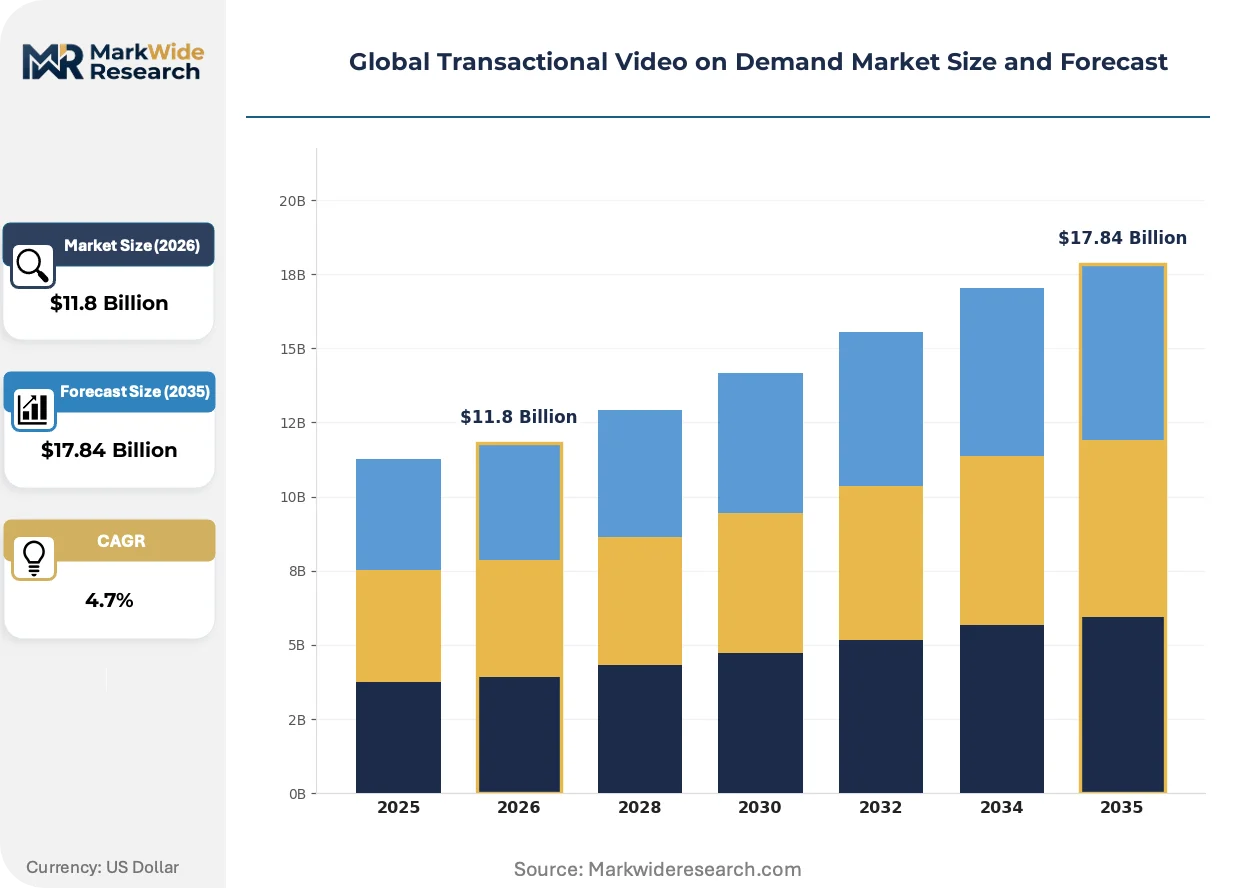
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Documentaries, Sports Events, Music Videos, Educational Programs Device Compatibility: Smartphones, Smart TVs, Tablets, Desktops, Streaming Media Players, Gaming Consoles Payment Model: Pay-Per-View, Pay-Per-Rental, Pay-Per-Download, Prepaid Credit, Subscription Add-ons, One-Time Purchase End User Category: Individual Consumers, Small Businesses, Educational Institutions, Hospitality Providers, Event Organizers, Content Creators |
| Companies Covered | Amazon.com, Inc., Apple Inc., Google Inc., Netflix Inc., The Walt Disney Company, Warner Bros. Discovery, Inc., Brightcove Inc., Limelight Networks, Redbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transactional Video on Demand Market Shifts & Advancements
Adaptive streaming architectures and regulatory transparency mandates are converging to reshape how content reaches end-users. Platform engineering priorities are pivoting toward latency reduction and algorithmic accountability.
AV1 codec deployment is bifurcating hardware-accelerated decode capability between premium Smart TV SoCs and legacy devices lacking DSP support. Amazon and Google are prioritizing AV1 for their ad-supported tiers to reduce CDN bills, while Apple maintains HEVC dominance for its purchased-content ecosystem. This codec divergence is fragmenting encoding pipelines and elevating storage costs for multi-format masters.
France's CNIL enforcement actions on recommendation algorithm explainability are compelling platforms to disclose ranking factors for promoted titles. The industrial consequence is engineering resource reallocation toward audit trails and user control interfaces. European operators are most affected, with Netflix and Amazon deploying localized transparency dashboards ahead of formal deadlines.
Day-and-date release fatigue among theatrical exhibitors is compressing exclusive window commitments in the United States and South Korea. Major studios are responding with variable pricing experiments, testing 48-hour rental windows against traditional 30-day purchase options. Consumer elasticity varies by genre, with franchise properties retaining purchase preference while mid-budget dramas migrate toward rental-only positioning.
Global Transactional Video on Demand Market Segmentation
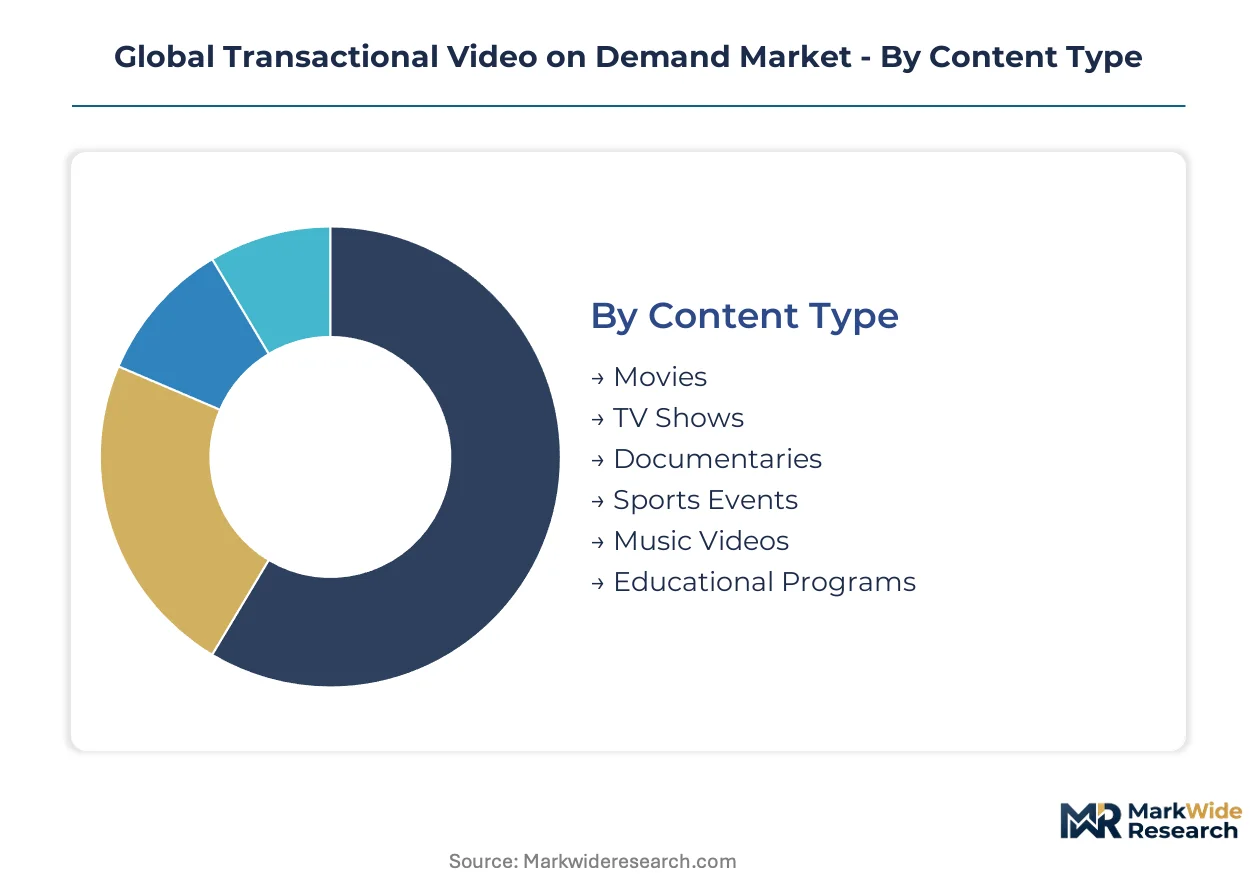
Transactional Video on Demand monetization varies sharply across content formats, device ecosystems, payment preferences, and buyer types. Platform operators must align encoding pipelines, DRM configurations, and pricing mechanics to each segment's distinct technical and commercial requirements.
Content Type:
Movies and episodic series flow through distinct windowing strategies, with theatrical distributors prioritizing premium-tier streams while catalog content supports volume-driven rental economics.
- Movies:Day-and-date releases with theatrical windows command premium purchase pricing on Smart TV platforms. Major studios concentrate new-release investment in the United States, China, and India where broadband infrastructure supports 4K HDR delivery without buffering abandonment.
- TV Shows:Episodic content typically deploys through rental-only positioning given lower per-episode perceived value versus film purchases. Binge-release patterns in South Korea and Japan are compressing individual episode transaction volumes in favor of season bundles.
- Documentaries:Niche factual content attracts concentrated demand from educational and institutional buyers with higher price tolerance for perpetual licensing.
- Sports Events:Live transactional access requires sub-10-second latency architectures and multicast CDN support, limiting viable platforms to those with edge compute infrastructure.
- Music Videos:Short-form musical content competes with ad-supported streaming tiers, constraining per-transaction pricing power to promotional bundles.
- Educational Programs:Structured learning content integrates with institutional procurement systems, requiring SCORM compliance and usage analytics dashboards.
By volume, Movies leads. By expansion trajectory, Sports Events is climbing the fastest as live rights holders experiment with direct-to-consumer bypass of traditional broadcast carriage.
Device Compatibility:
Hardware decode capabilities and screen real estate determine codec selection, with premium 4K HDR streams requiring HEVC or AV1 support absent from legacy device generations.
- Smart TVs:Built-in app ecosystems from Samsung, LG, and Sony anchor the majority of 4K HDR transactions due to superior display fidelity and hardware-accelerated decode. India's accelerating Smart TV refresh cycles are expanding addressable households for premium-tier purchases outside metro centers.
- Smartphones:Mobile-optimized streams at 720p-1080p dominate rental volume in India and Brazil where UPI and Pix integration compress transaction friction. Small screen size constrains purchase preference toward lower price points versus living room viewing.
- Tablets:Mid-tier resolution positioning attracts travel and commute viewing occasions with moderate pricing tolerance between smartphone and Smart TV tiers.
- Desktops:Browser-based playback persists for professional and educational use cases requiring multitasking alongside content consumption.
- Streaming Media Players:Roku, Amazon Fire TV, and Apple TV devices aggregate fragmented Smart TV firmware ecosystems, reducing platform engineering overhead for DRM certification.
- Gaming Consoles:PlayStation and Xbox installations deliver high-ARPU male-skewing demographics for action and sports content with purchase preference over rental.
Smart TVs capture the highest revenue per transaction. Smartphones are gaining share fastest as mobile payment infrastructure matures in emerging markets.
Payment Model:
Consumer flexibility preferences versus ownership psychology segment payment behavior, with rental models dominating price-sensitive markets and purchase models retaining franchise property enthusiasts.
- Pay-Per-View:Live event access commands premium pricing for sports and concert broadcasts with temporal exclusivity. South Korea's KT and SK Telecom multicast trials are reducing per-stream delivery costs for concurrent viewing spikes.
- Pay-Per-Rental:48-hour access windows dominate transaction volume in Western Europe and North America where subscription fatigue increases appetite for unbundled content. France's CNIL transparency mandates are elevating platform engineering costs for recommendation-driven discovery.
- Pay-Per-Download:Offline storage for air travel and connectivity-limited environments retains niche demand despite streaming dominance.
- Prepaid Credit:Wallet-based systems in Southeast Asia reduce payment card abandonment through carrier billing integration.
- Subscription Add-ons:Amazon Prime Video Channels and Apple TV app integrations capture incremental spend from existing subscription relationships.
- One-Time Purchase:Perpetual library access retains strongest demand for Disney and Marvel franchise properties with repeat-viewing value.
Pay-Per-Rental leads by transaction volume. Subscription Add-ons are expanding most quickly as platforms leverage existing payment relationships.
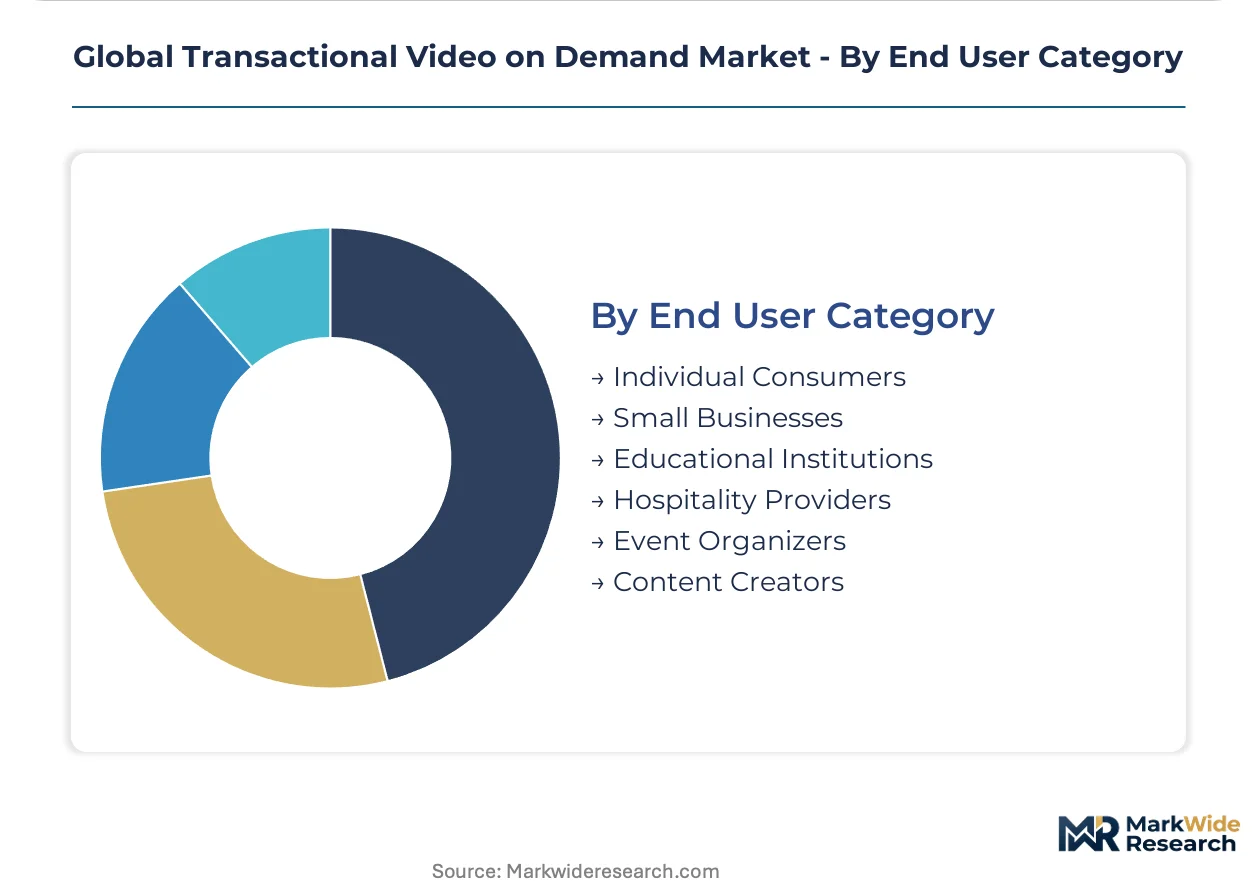
End User Category:
B2B procurement patterns diverge from consumer behavior through volume licensing, usage reporting requirements, and extended payment terms.
- Individual Consumers:Discretionary entertainment spend drives the majority of transactional volume with highest price sensitivity and platform-switching behavior. Germany's KBA content integrity mandates are clarifying rights-holder revenue transparency for cross-border licensing.
- Small Businesses:Background entertainment and customer-facing display licensing requires commercial-use rights with higher per-title costs than consumer equivalents.
- Educational Institutions:K-12 and university procurement requires perpetual licensing with public performance rights and curriculum alignment metadata.
- Hospitality Providers:Hotel and cruise line in-room entertainment demands studio-grade DRM with centralized billing reconciliation across property portfolios.
- Event Organizers:Temporary public screening licenses for pop-up cinemas and community venues require short-term rights windows with location-based restrictions.
- Content Creators:Stock footage and licensed music video procurement for derivative works demands clear rights chains and indemnification clauses.
Individual Consumers dominate by transaction count. Educational Institutions are gaining share fastest as remote learning infrastructure investment persists post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure investments cluster in markets where broadband penetration and mobile payment maturity overlap. The United States, China, India, South Korea, and Germany each concentrate distinct competitive advantages across content licensing, device manufacturing, and regulatory frameworks.
United States
FCC net neutrality principles shape streaming quality-of-service negotiations between platforms and tier-1 ISPs. The agency's 2023 restoration of Title II classification reopens peering dispute resolution pathways. Los Angeles and New York anchor studio headquarters for day-and-date release windowing decisions.
China
MIIT broadband quality mandates and SAMR platform antitrust enforcement compress margins for domestic streaming operators. GB standards for 4K HDR transmission equipment accelerate Smart TV refresh cycles in coastal provinces. Shenzhen's hardware ecosystem supplies MediaTek and Amlogic chipsets for global TV manufacturers.
India
TRAI broadband infrastructure directives and BIS digital content standardization create compliance thresholds for foreign platform entry. UPI wallet integration reduces transaction abandonment in tier-2 cities. Mumbai's production clusters feed regional language dubbing pipelines for Southeast Asian expansion.
South Korea
KT and SK Telecom multicast trials for live sports delivery reduce CDN congestion during concurrent viewing spikes. MFDS content classification rules apply to streaming platform recommendation algorithms. Seoul's 5G broadcast convergence labs test edge compute architectures for sub-10-second latency.
Germany
KBA content integrity mandates clarify platform liability for cross-border catalog licensing transparency. GDPR enforcement through Hamburg's data protection authority elevates engineering costs for algorithmic explainability. Bavaria's media technology clusters develop DRM interoperability solutions for Smart TV firmware fragmentation.
Global Transactional Video on Demand Market Competitive Landscape
Concentration sits with vertically integrated technology platforms that control device ecosystems, payment infrastructure, and content libraries. Three archetypes dominate: hardware-anchored premium pricing operators, logistics-integrated volume players, and studio-controlled windowing specialists. Competitive moves center on theatrical-to-digital window compression and multicast delivery infrastructure partnerships.
Within the hardware-anchored tier, Apple Inc. exemplifies premium-tier positioning through its device ecosystem integration. Amazon.com, Inc. occupies the logistics-integrated volume position, leveraging Prime Video's payment infrastructure. Warner Bros. Discovery, Inc. represents studio-controlled windowing specialization across theatrical and digital release management.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Google Inc. |
| Netflix Inc. |
| The Walt Disney Company |
| Warner Bros. Discovery, Inc. |
| Brightcove Inc. |
| Limelight Networks |
| Redbox |
| Others |
Supply & Pricing Matrix
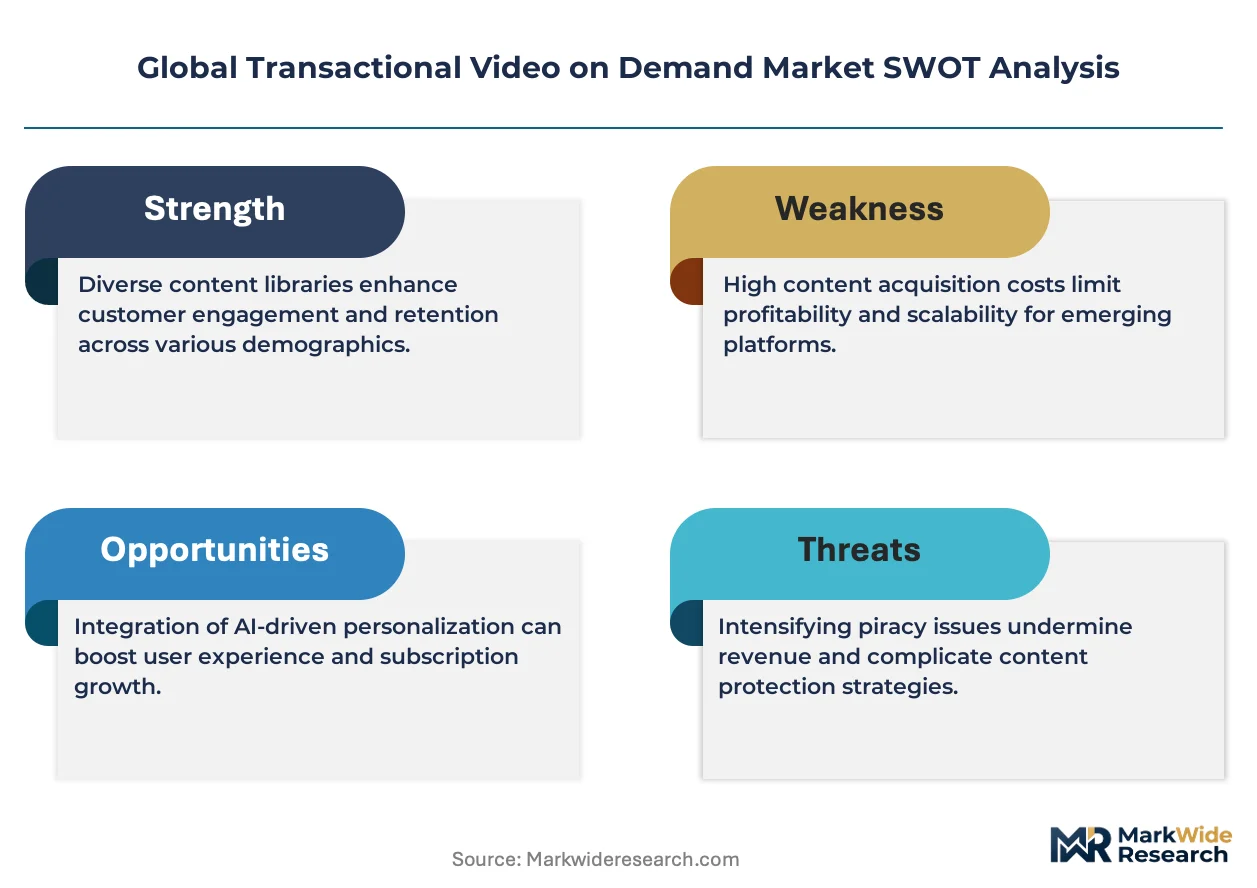
AV1 codec substitution for HEVC is simultaneously redrawing encoding cost geography and compressing premium-tier pricing power as platforms dual-track format pipelines to serve fragmented device ecosystems.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure through compliance cost allocation across European operations. Three-tier pricing structure across premium, standard, and economy levels separates 4K HDR purchases from HD rentals from mobile-optimized streams. Price differentiation rests on DRM certification grade and hardware decode capability. Pricing pressure stems from subscription bundle substitution as Disney+ and Netflix hybrid tiers capture day-and-date releases. Individual consumers show highest price sensitivity, while hospitality providers demonstrate lowest sensitivity due to commercial-use licensing requirements.
Supply Chain Analysis
China and Taiwan anchor global Smart TV chipset fabrication through MediaTek and Amlogic SoC production. The supply chain draws from silicon wafer inputs, HEVC and AV1 patent licensing pools, and CDN edge server deployments. Single-source vulnerability concentrates in MPEG LA and Access Advance codec royalty administration. Distribution runs through OEM direct contracts with Samsung, LG, and Sony for built-in app ecosystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
4K HDR streaming compression standards and mobile wallet proliferation are disrupting content monetization economics, creating asymmetric opportunity windows across device ecosystems and payment infrastructure.
For Market Incumbents: Consolidate control over theatrical-to-digital windowing decisions to defend per-title revenue visibility against subscription bundle gravity. Deepen backward integration into Smart TV firmware certification pipelines to reduce DRM interoperability fragmentation costs. Prioritize edge compute infrastructure partnerships with KT and SK Telecom to capture live sports multicast delivery advantages. For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated broadband markets outside Java's urban core where Palapa Ring fiber completion creates first-time addressable households. Target educational institutional procurement with SCORM-compliant learning content and usage analytics dashboards. Leverage carrier billing integration through prepaid credit systems to compress transaction abandonment in Southeast Asian markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional streaming platforms holding fragmented catalog licensing positions across European markets. Long-term viability hinges on regulatory compliance infrastructure as GDPR enforcement and AI Act transparency mandates elevate fixed engineering costs. Watch for FCC net neutrality rulemaking shifts as signal for peering dispute resolution pathways that reshape CDN cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Multicast CDN Infrastructure Partnership | KT and SK Telecom trials reduce last-mile congestion for concurrent live sports releases. |
| Mobile Wallet Integration | UPI and Pix embedding compresses transaction abandonment rates in India and Brazil. |
| Codec Pipeline Diversification | AV1 deployment for ad-supported tiers reduces bandwidth costs while maintaining HEVC for premium purchases. |
| Algorithmic Transparency Dashboard Deployment | Netflix and Amazon localize interfaces ahead of CNIL enforcement deadlines in France. |
| Educational Content Licensing Expansion | SCORM compliance and perpetual licensing models capture institutional procurement post-pandemic. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with streaming platform executives, content licensing directors, Smart TV OEM procurement managers, and CDN infrastructure engineers. Secondary validation drew from FCC net neutrality filings, EMA and GDPR regulatory databases, TRAI broadband directives, and SEC 10-K disclosures from major platform operators. Bottom-up transaction volume modeling triangulated against top-down market sizing from hardware shipment data and payment flow analysis.
Across the analysis window, forecasts segment by content type, device compatibility, payment model, and end user category with regional regulatory cluster overlays. CAGRs derive from installed base projections for 4K HDR-capable devices, mobile payment penetration curves, and theatrical window compression timelines. Inputs include broadband quality mandates from India's TRAI, Smart TV refresh cycle data from China's MIIT, and multicast delivery trial results from South Korea's KT.
Decision-makers should treat outputs as directional under assumptions of stable net neutrality frameworks and continued mobile wallet adoption; material deviation in CDN peering disputes or codec royalty restructuring would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement patterns and hardware decode capability deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Streaming Spending Market