
 Over the Top (OTT) Services Market | 2026-2036
Over the Top (OTT) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Top (OTT) Services Market Intelligence
The rise of original content creation by Media Producers is rebalancing the traditional licensing model within the OTT services ecosystem. The Walt Disney Company leverages its vast intellectual property portfolio across its streaming platforms. Netflix, Inc. specializes in producing a high volume of original international content to attract diverse audiences. Amazon.com, Inc. integrates its Prime Video service into its broader e-commerce and hardware ecosystem, creating a sticky user base.
Over the Top (OTT) services refer to the direct delivery of media content to viewers via the internet, bypassing traditional broadcast, cable, and satellite television platforms. Effective service delivery relies on a robust Content Delivery Network (CDN) to minimize latency and ensure high-quality streaming. Video Streaming constitutes the largest segment by service type, driven by subscription-based models. The adoption of AI-based Analytics is critical for personalizing user experience and optimizing content discovery across various distribution channels like Smart TVs and mobile apps.
The European Union's Digital Services Act imposes new content moderation and transparency rules on large platforms. In the United States, the Federal Communications Commission (FCC) policies on net neutrality affect how internet service providers manage OTT data traffic. China's MIIT enforces strict licensing and content standards for all digital media providers operating within its borders. Platform operators must navigate these divergent national content regulations and data privacy laws to sustain user growth.
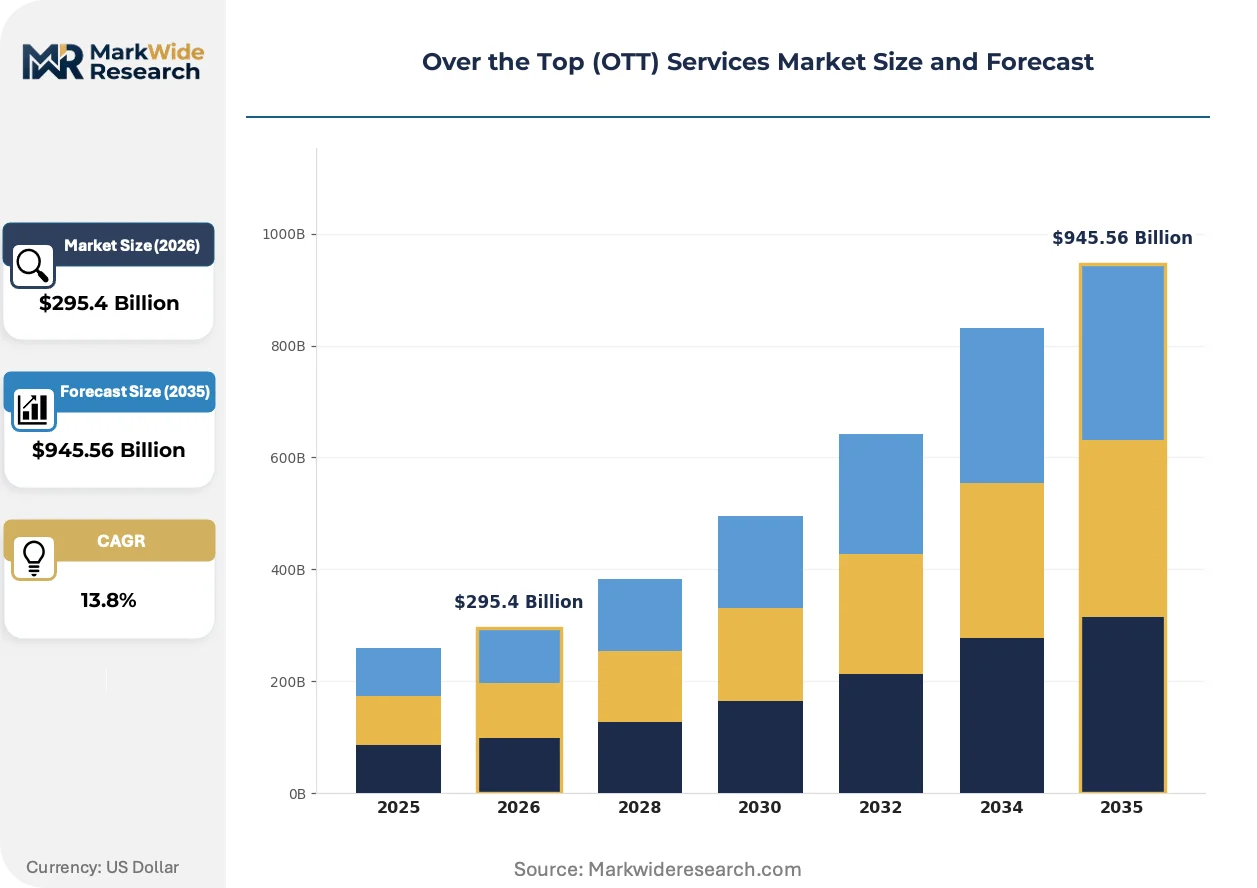
Market Dynamics
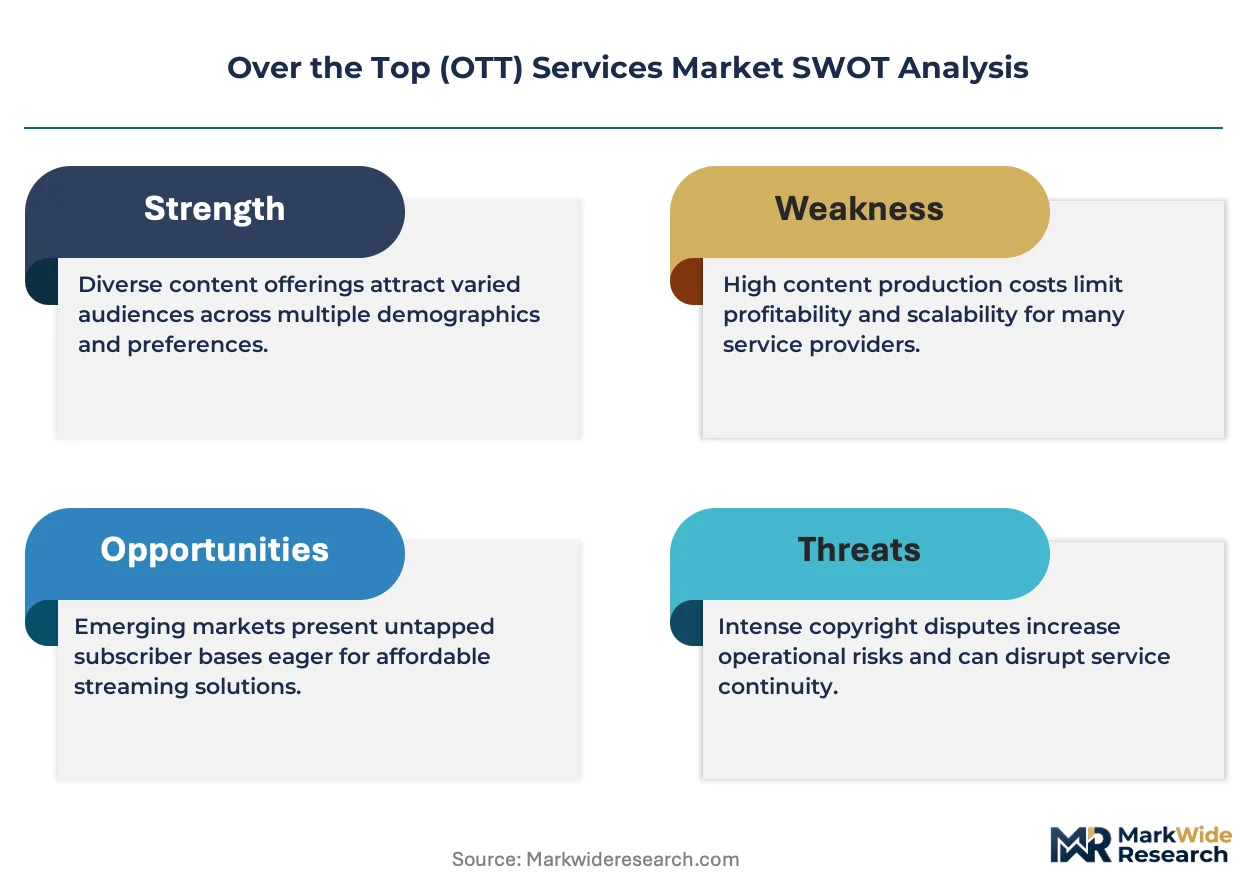
The fundamental dynamic shaping the market is the strategic pivot from content licensing to in-house original content production. This shift intensifies competition for intellectual property, creative talent, and production resources, directly influencing platform differentiation and long-term user retention.
Growth Catalysts
- 5G Network Expansion:The rollout of 5G infrastructure in countries like South Korea and the United States enables higher-fidelity streaming, including 4K and interactive formats, and reduces latency for mobile viewers.
- Creator Economy Tools:The expansion of platforms and services supporting independent content creators provides a continuous stream of fresh, diverse material, attracting niche audiences away from traditional media sources.
- Digital Infrastructure Policies:Government programs in markets such as India and Brazil aimed at increasing internet penetration and affordability are creating millions of new potential subscribers for OTT services.
Market Restraints
- Content Production Costs:Escalating budgets for premium original series and films create significant financial barriers to entry and pressure subscription pricing, limiting affordability in price-sensitive regions.
- Bandwidth Inconsistency:In many developing economies, limited and unreliable internet infrastructure constrains the delivery of high-definition content, leading to poor user experience and capping service adoption.
- Regulatory Fragmentation:Navigating disparate content censorship rules, such as those enforced by China's MIIT, and data governance laws, like the EU's Digital Services Act, complicates global operations.
Strategic Opportunities
- Interactive Entertainment Integration:The convergence of streaming video with gaming functionalities offers a new frontier for user engagement, including interactive narratives and live event integration on platforms.
- Niche Content Verticals:There is significant white space for specialized OTT services focused on underserved segments like professional education, wellness and fitness coaching, or faith-based programming.
- Bundled Service Offerings:In markets across Latin America, opportunities exist to bundle OTT subscriptions with telecommunication services, creating value and increasing stickiness for both service providers.
Industry Challenges
- Digital Piracy and Account Sharing:The unauthorized distribution of copyrighted content and widespread password sharing continue to cause substantial revenue loss, requiring constant investment in digital rights management and security technologies.
- Subscriber Churn Management:High competition leads to a constant battle to retain subscribers. Platforms face the challenge of continuously delivering value to prevent users from canceling services after watching specific content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Top (OTT) Services Market |
| Market Size in 2026 | $295.4 Billion |
| Market Size in 2035 | $945.56 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Voice Calling, Messaging, Music Streaming, Cloud Storage Technology: IPTV, CDN, Cloud Computing, Edge Computing, AI-based Analytics End User: Individual Consumers, Small Businesses, Educational Institutions, Media Producers, Content Creators Distribution Channel: Mobile Apps, Smart TVs, Web Browsers, Set-Top Boxes, Gaming Consoles |
| Companies Covered | Netflix, Inc., Amazon.com, Inc., Google LLC, Apple Inc., The Walt Disney Company, Hulu, LLC, Roku, Inc., Tencent Holdings Ltd, Warner Bros. Discovery, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Top (OTT) Services Market Strategic Shifts & Innovations
The industrialization of the content pipeline, from automated post-production to AI-driven discovery, defines the current innovation cycle. Platforms are evolving from simple content libraries into sophisticated, data-driven entertainment ecosystems that personalize the entire user journey at a global scale.
Advanced video compression codecs like AV1 are becoming critical for efficient data delivery. CDN providers and streaming platforms are widely implementing these technologies to reduce bandwidth consumption while maintaining visual quality. This development is modularizing the video delivery chain, allowing for dynamic, real-time adaptation of stream quality based on individual user network conditions and device capabilities.
Regulatory frameworks are imposing new operational requirements on platforms. India's Information Technology Rules mandate a tiered grievance redressal structure and specific content classification systems for OTT providers. This action forces all services operating in the country to appoint local compliance officers and align their libraries with prescribed age-rating and content-type descriptors.
Consumer viewing habits are shifting toward more fragmented and on-demand consumption patterns. This change disrupts the primacy of feature-length films and linear schedules, with short-form series and user-generated clips gaining traction. The behavioral shift is most pronounced in mobile-first markets like Brazil and Indonesia, where content is often consumed in shorter bursts throughout the day.
Over the Top (OTT) Services Market Segmentation
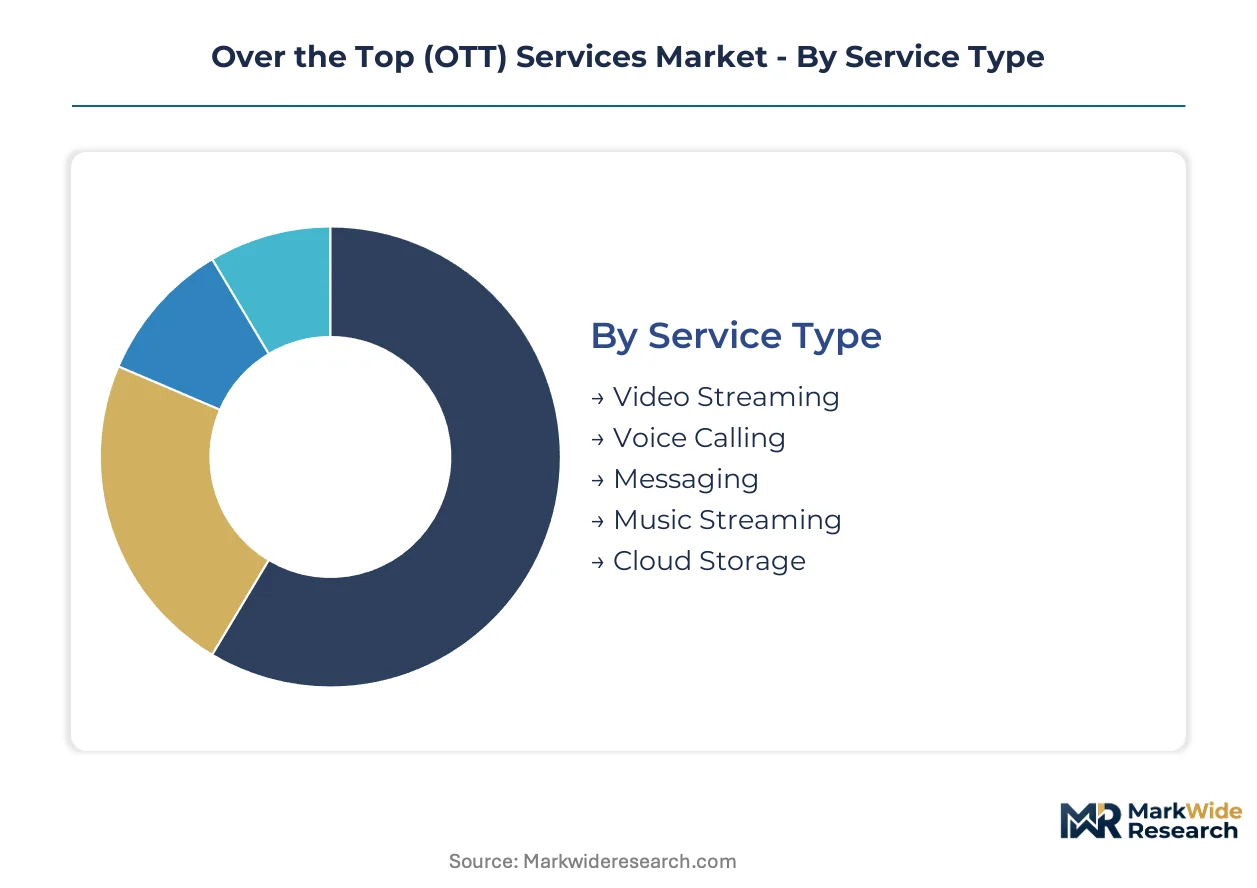
The Over the Top (OTT) Services Market segmentation reflects the diverse ways content reaches consumers and the underlying technologies enabling this delivery. Understanding these segments clarifies the varied business models and operational complexities within the ecosystem. This analysis highlights key areas of innovation and user engagement across different service types and distribution channels.
Service Type:
The functional specification of services defines how users interact with digital media and communication platforms.
- Video Streaming:This segment encompasses the direct delivery of media content to viewers via the internet, bypassing traditional broadcast or cable infrastructure. Demand concentrates in markets with high mobile penetration, such as India and Brazil, driven by compelling subscription-based models.
- Voice Calling:Internet-based communication services, often integrated into broader applications, facilitate real-time audio conversations.
- Messaging:This segment provides real-time text, multimedia, and group communication functionalities, frequently bundled within larger social or content platforms.
- Music Streaming:This service type offers on-demand access to vast audio libraries, often featuring personalized playlists and offline listening capabilities. Demand is strong in mobile-first markets, where users seek curated auditory experiences.
- Cloud Storage:Provides remote data storage and access for users, allowing content to be saved and retrieved across multiple devices.
Mature deployment sits with Video Streaming. Newer deployment is concentrated in Cloud Storage.
Technology:
The underlying application of technology dictates the performance, scalability, and intelligence of OTT service delivery.
- IPTV:Delivers television programming over Internet Protocol networks, frequently managed by telecommunication providers for a controlled viewing experience.
- CDN:A Content Delivery Network comprises a geographically distributed group of servers working together to provide fast delivery of internet content. Global platforms requiring low latency and high availability across diverse user bases rely heavily on CDNs.
- Cloud Computing:Provides scalable and flexible infrastructure for content storage, processing, and application hosting, supporting dynamic content libraries.
- Edge Computing:Processes data closer to the source of generation, minimizing latency and bandwidth use for real-time applications like interactive streaming.
- AI-based Analytics:Employs machine learning algorithms to process vast amounts of user data, generating insights for content personalization and operational optimization. Platforms aiming for personalized user experiences and optimized content recommendations utilize AI-based analytics.
The operational efficiency of platforms is significantly enhanced by CDN, while user engagement is refined through AI-based Analytics.
End User:
The customer type accessing OTT services shapes content development, platform features, and monetization strategies.
- Individual Consumers:These are direct recipients of OTT content for personal entertainment, education, or communication purposes. Diverse demographics seeking personalized viewing experiences across mobile and living room devices form a large part of this segment.
- Small Businesses:Utilize OTT platforms for internal communication, marketing campaigns, or specialized training programs tailored to their operational needs.
- Educational Institutions:Leverage streaming technologies for remote learning, digital lectures, and hosting extensive online content libraries for students and faculty.
- Media Producers:Companies involved in the creation and distribution of professional-grade film, television, and audio content, often partnering with OTT platforms.
- Content Creators:Individuals or small teams producing original digital media for distribution, often through user-generated content platforms or independent channels. Platforms expanding creator economy tools to attract fresh, diverse material target content creators.
Market expansion is primarily driven by the needs of Individual Consumers, with significant innovation stemming from the activities of Content Creators.
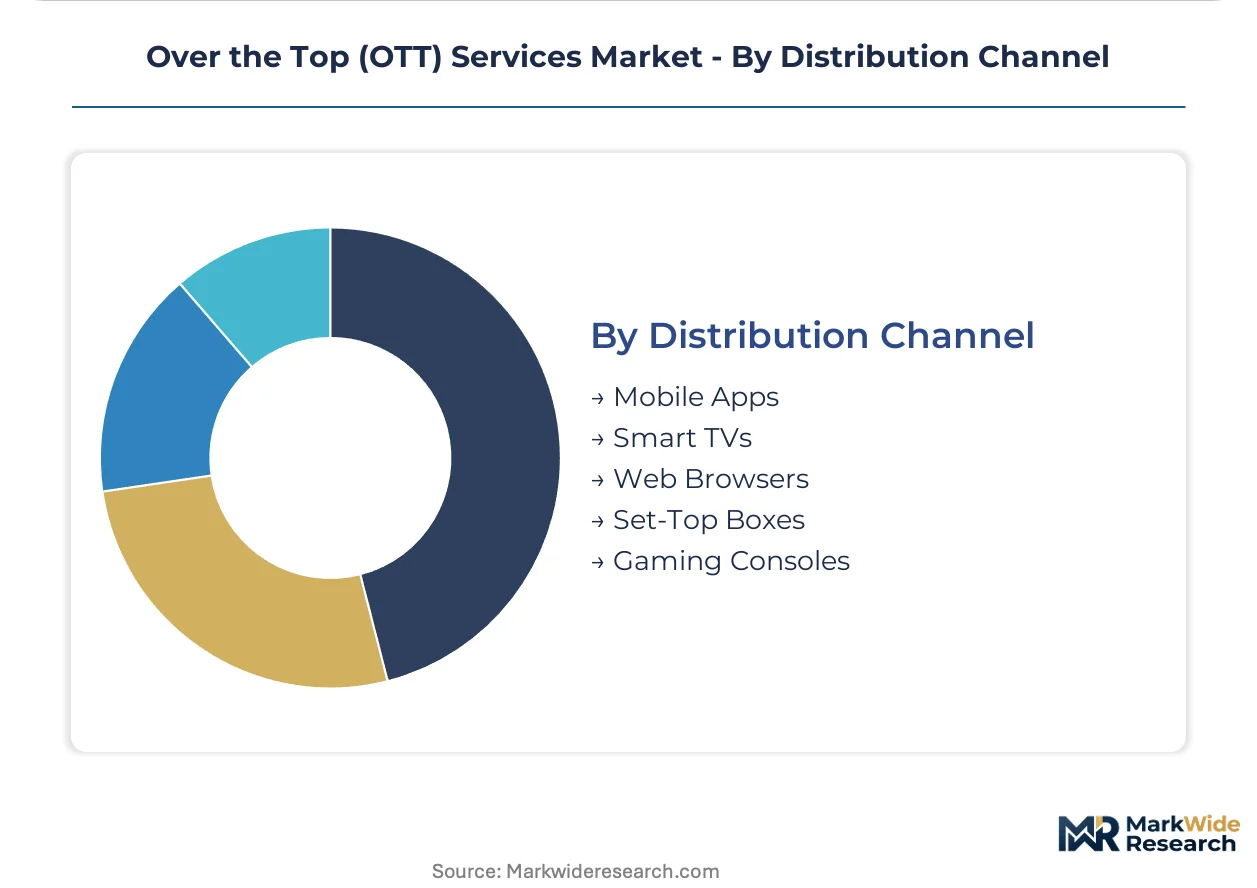
Distribution Channel:
The access modality determines how users consume OTT content, influencing device compatibility and user interface design.
- Mobile Apps:Dedicated software applications designed for smartphones and tablets, providing direct access to OTT services. Mobile-first markets like Brazil and Indonesia show high engagement, especially for short-form content consumption.
- Smart TVs:Internet-connected televisions integrating streaming platforms directly, offering a seamless viewing experience from the living room. Developed markets with high broadband penetration support high-fidelity streaming on Smart TVs.
- Web Browsers:Provide access to OTT services via standard internet navigation on computers and other web-enabled devices.
- Set-Top Boxes:External hardware devices connecting traditional televisions to internet-based content and streaming services.
- Gaming Consoles:Offer integrated media consumption alongside interactive gaming experiences, expanding their utility beyond traditional gaming.
The largest user base accesses services through Mobile Apps, while the living room experience is increasingly dominated by Smart TVs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Internet City, as a prominent digital free zone, fosters a concentration of digital service providers, creating a hub for OTT innovation. This environment attracts both established platforms and emerging content creators. Such strategic zones contribute significantly to regional market development and technological advancement.
United States
The United States drives demand for high-fidelity streaming, supported by widespread 5G infrastructure and a large consumer base. Federal Communications Commission (FCC) policies on net neutrality affect how internet service providers manage OTT data traffic. Los Angeles, California, remains a global content production hub, continually supplying new material for streaming platforms.
India
India's market expansion is fueled by high mobile penetration and government programs aimed at increasing internet affordability. The Information Technology Rules mandate specific content classification systems for OTT providers. Bengaluru's tech ecosystem supports numerous content delivery network (CDN) operations, ensuring efficient streaming services across the country.
China
In China, a massive digital consumer base and robust domestic content creation sustain market growth. The Ministry of Industry and Information Technology (MIIT) enforces strict licensing and content standards for all digital media providers. Shanghai hosts major digital media providers, navigating complex regulatory landscapes for content distribution.
Brazil
Brazil experiences significant demand from mobile-first consumers, benefiting from government initiatives to expand internet access. National policies aimed at increasing internet penetration and affordability are creating millions of new potential subscribers. São Paulo serves as a key hub for telecommunication services, facilitating bundled OTT subscriptions for consumers.
Germany
Germany benefits from a developed market with high broadband penetration, driving demand for premium and localized content. The European Union's Digital Services Act imposes new content moderation and transparency rules on large platforms operating within its borders. Berlin's vibrant startup scene includes numerous content tech companies, developing innovative streaming solutions.
Over the Top (OTT) Services Market Key Industry Players
Top-tier vendors anchor the global streaming landscape, while a diverse array of specialized and regional players cater to niche audiences. Strategic archetypes include global content powerhouses, regional specialists, and technology enablers. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand content libraries.
Global content powerhouses like Netflix, Inc. exemplify the direct-to-consumer model, leveraging vast original content investments. Amazon.com, Inc. represents a diversified e-commerce giant integrating streaming into a broader ecosystem, creating significant user stickiness. The Walt Disney Company, an Inc.-structured entity, anchors the intellectual property-driven strategy, monetizing its extensive character catalog across multiple platforms. These entities continuously refine their content acquisition and distribution strategies.
| Leading Market Players |
|---|
| Netflix, Inc. |
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| The Walt Disney Company |
| Hulu, LLC |
| Roku, Inc. |
| Tencent Holdings Ltd |
| Warner Bros. Discovery, Inc. |
Cost & Logistics Intelligence
Individual Consumers' demand for personalized content drives a subscription-based pricing model across the Over the Top (OTT) Services Market. This consumer-centric approach influences content acquisition and production strategies, creating a feedback loop between user preferences and supply chain investments.
Pricing Analysis
Premium pricing for exclusive content and ad-free tiers reflects a lead-time driven strategy, while entry-level subscriptions offer discounted access to a broader library. Subscription-based models dominate, with price differentiation stemming from content exclusivity and streaming quality (e.g., 4K resolution). Pricing pressure stems from content production costs and intense competition among platforms, requiring continuous value delivery. Individual Consumers in emerging markets like India and Brazil exhibit higher price sensitivity, prioritizing affordable access over premium features, unlike developed market users.
Supply Chain Analysis
Reverse logistics for content, such as archiving and rights management, forms a crucial part of the digital supply chain. Content creation concentrates in established media hubs like Los Angeles, United States, and Shanghai, China, leveraging creative talent and production infrastructure. The supply chain depends on advanced video compression codecs and Content Delivery Networks (CDNs) for efficient global distribution. A structural risk involves regulatory fragmentation, where disparate national content standards, such as those from China's MIIT, complicate content localization and global delivery. Distribution runs through a direct-to-consumer model via mobile apps and Smart TVs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Over the Top (OTT) Services Market is undergoing a consolidation play, as escalating content production costs pressure smaller, undifferentiated players to exit or merge.
For Market Incumbents: Hedge against content commoditization by investing in proprietary intellectual property and fostering unique interactive entertainment formats. This strategy counters the threat of subscriber churn driven by content hopping across platforms. Leveraging AI-based analytics for hyper-personalization acts as a critical lever, deepening user engagement and retention against emerging niche competitors.
For New Entrants and Emerging Players: Enter via underserved niche content verticals, such as professional education or specialized fitness coaching, where existing platforms lack depth. Target specific geographic white spaces with high mobile penetration and low broadband infrastructure, like rural India. A freemium go-to-market angle, offering basic content for free to build an audience before introducing premium tiers, can attract initial users.
For Investors and Strategic Acquirers: The window for entry favors acquirers seeking technology enablers or specialized content libraries that offer defensible intellectual property. Long-term viability hinges on platforms that demonstrate sustainable user growth through unique content and robust technological infrastructure, rather than aggressive, unsustainable content spending. The signal to watch is the shift in subscriber acquisition cost trends, indicating market saturation or new growth opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Original Content Production | Drives platform differentiation and reduces reliance on costly licensed content from third-party studios. |
| Invest in Advanced CDN Infrastructure | Ensures high-quality streaming and minimizes latency for a global user base across diverse network conditions. |
| Develop Interactive Entertainment Features | Increases user engagement and time spent on platform, fostering a more immersive content experience. |
| Form Bundled Service Partnerships | Creates value for consumers and enhances subscriber stickiness by integrating with telecommunication providers. |
| Acquire Niche Content Verticals | Expands market reach into underserved segments, attracting specialized audiences away from mainstream offerings. |
Research Approach
Document review covered publicly available financial statements, regulatory filings with the Federal Communications Commission (FCC) and India's Information Technology Rules, complemented by interviews with content production executives, platform engineers, and digital marketing specialists. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation verified data accuracy and market sizing across various segments.
The quantitative model produced market projections for the Over the Top (OTT) Services Market across the analysis window, segmented by service type (e.g., video streaming, music streaming), technology (e.g., CDN, AI-based analytics), and distribution channel (e.g., mobile apps, Smart TVs). Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected future adoption rates. Key forecast inputs included internet penetration rates in developing economies and 5G network expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unforeseen technological disruptions. Forecasts reflect assumptions documented through extensive primary and secondary research. Practitioners should monitor global content licensing costs and evolving national content regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Latin America OTT Platform Market