
 Global Cloud Video Streaming Market | 2026-2036
Global Cloud Video Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Video Streaming Market Analysis
Asset-light infrastructure leasing and usage-based project finance is fragmenting competitive dynamics across the cloud video streaming ecosystem. Amazon Web Services leverages its hyperscale data center footprint to dominate enterprise-grade streaming workloads. Google sustains competitive pressure through deep integration of encoding and distribution layers within its cloud-native stack. Akamai Technologies anchors its position through edge-computing density that minimizes latency for live broadcasters.
Cloud video streaming encompasses the delivery of encoded audiovisual content over internet protocol networks using adaptive bitrate protocols, with primary commercial purpose spanning entertainment consumption, enterprise communications, and educational distribution. HTTP Live Streaming and MPEG-DASH represent the dominant technical standards, with WebRTC gaining traction for sub-second latency use cases including live auctions and interactive broadcasts. The SVOD segment retains the largest revenue pool as subscription fatigue pushes platforms toward hybrid monetization models combining advertising and transactional tiers. Enterprise end users represent the fastest-expanding demand vertical as organizations replace legacy video conferencing with integrated streaming workflows.
The FCC in the United States governs net neutrality and broadband infrastructure rules that directly affect streaming quality-of-service guarantees, while the EU AI Act and GDPR impose algorithmic transparency and cross-border data handling requirements on content recommendation engines. Brazil's ANATEL enforces local data residency mandates that shape provider architecture decisions across Latin American deployments. Stakeholders must monitor evolving spectrum allocation and content licensing frameworks as sovereign governments assert greater control over digital media distribution.
Market Dynamics
Adaptive bitrate protocols and edge-computing density are compressing infrastructure ownership models, forcing providers to lease rather than build captive delivery networks.
Growth Catalysts
- EU AI Act compliance mandates:Content moderation and algorithmic transparency requirements are expanding demand for sovereign cloud deployments across European enterprise video platforms.
- Enterprise learning verticals:Corporate training departments are replacing legacy video conferencing with integrated streaming workflows, pulling infrastructure spend toward unified communications.
- Brazil's ANATEL data residency rules:Local storage requirements are accelerating provider investment in São Paulo and Rio de Janeiro edge nodes.
Market Restraints
- Energy input cost volatility:Hyperscale data center power consumption exposes streaming margins to electricity price swings in markets with constrained renewable supply.
- Encoder supply concentration:Advanced video coding hardware fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for live broadcasters.
- WebRTC latency floor:Sub-second delivery protocols face fundamental bandwidth constraints in emerging markets with asymmetric broadband topology.
Strategic Opportunities
- India's underserved Tier-2 cities:Vernacular-language streaming demand in Lucknow, Indore, and Coimbatore outpaces localized infrastructure deployment.
- Interactive commerce integration:Live auction platforms and shoppable video are converging WebRTC streaming with real-time payment rails.
- GDPR Article 17 data portability:Right-to-erasure workflows are creating managed services demand for automated content lifecycle governance.
Industry Challenges
- Codec engineering talent scarcity:Deep expertise in AV1 and VVC compression algorithms concentrates within semiconductor vendors, limiting in-house optimization.
- Cross-border licensing complexity:Sports and entertainment rights fragmentation across national broadcasters obstructs unified global distribution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Video Streaming Market |
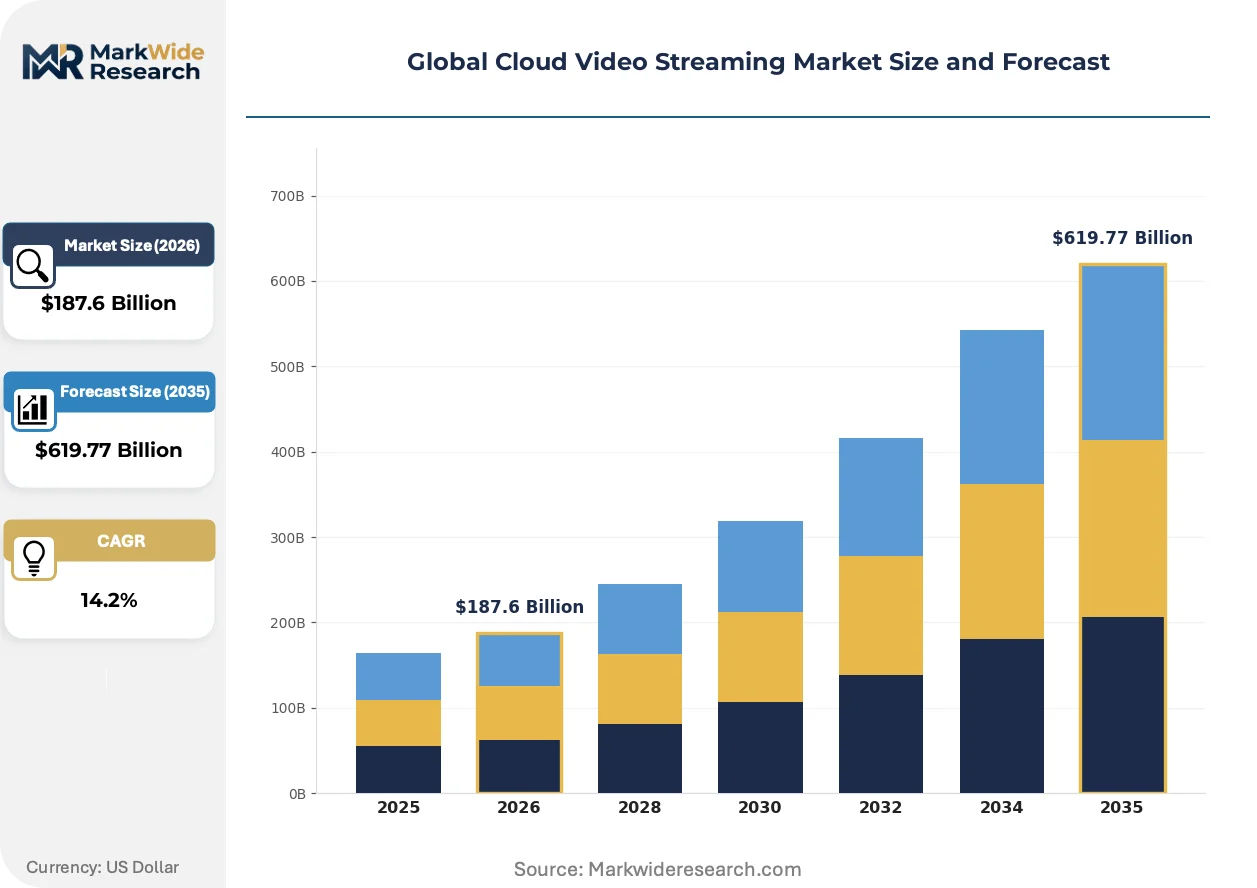
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: SVOD, AVOD, TVOD, Hybrid End User: Consumers, Enterprises, Educational Institutions, Broadcasters Technology: HTTP Live Streaming, MPEG-DASH, WebRTC, RTMP Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing |
| Companies Covered | Amazon Web Services, Akamai Technologies, IBM, Google, Kaltura, Wowza Media Systems, Brightcove, Cisco Systems, Haivision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Video Streaming Market Emerging Trajectories
Containerized encoding and serverless delivery architectures are decoupling software from hardware investment, compressing capital requirements for market entry.
Software-defined content delivery networks are virtualizing last-mile distribution by abstracting edge server management into API-driven orchestration layers. Mid-market broadcasters in Southeast Asia are adopting these stacks fastest, bypassing multi-year infrastructure buildouts. This compression of fixed costs is virtualizing competitive barriers that previously favored hyperscale incumbents.
The EU AI Act's algorithmic transparency mandates are forcing recommendation engine disclosures that expose proprietary ranking methodologies. Streaming platforms serving European audiences must now document content moderation decision trees and bias testing protocols. Entertainment services with opaque curation systems face the steepest compliance retrofit costs.
Enterprise procurement teams are unbundling encoding, storage, and distribution contracts that were previously consolidated with single vendors. Fortune 500 technology departments now source point solutions through cloud marketplaces rather than negotiating comprehensive platform agreements. This pattern is most pronounced in United States financial services, where procurement autonomy has devolved to individual business units.
Global Cloud Video Streaming Market Segmentation
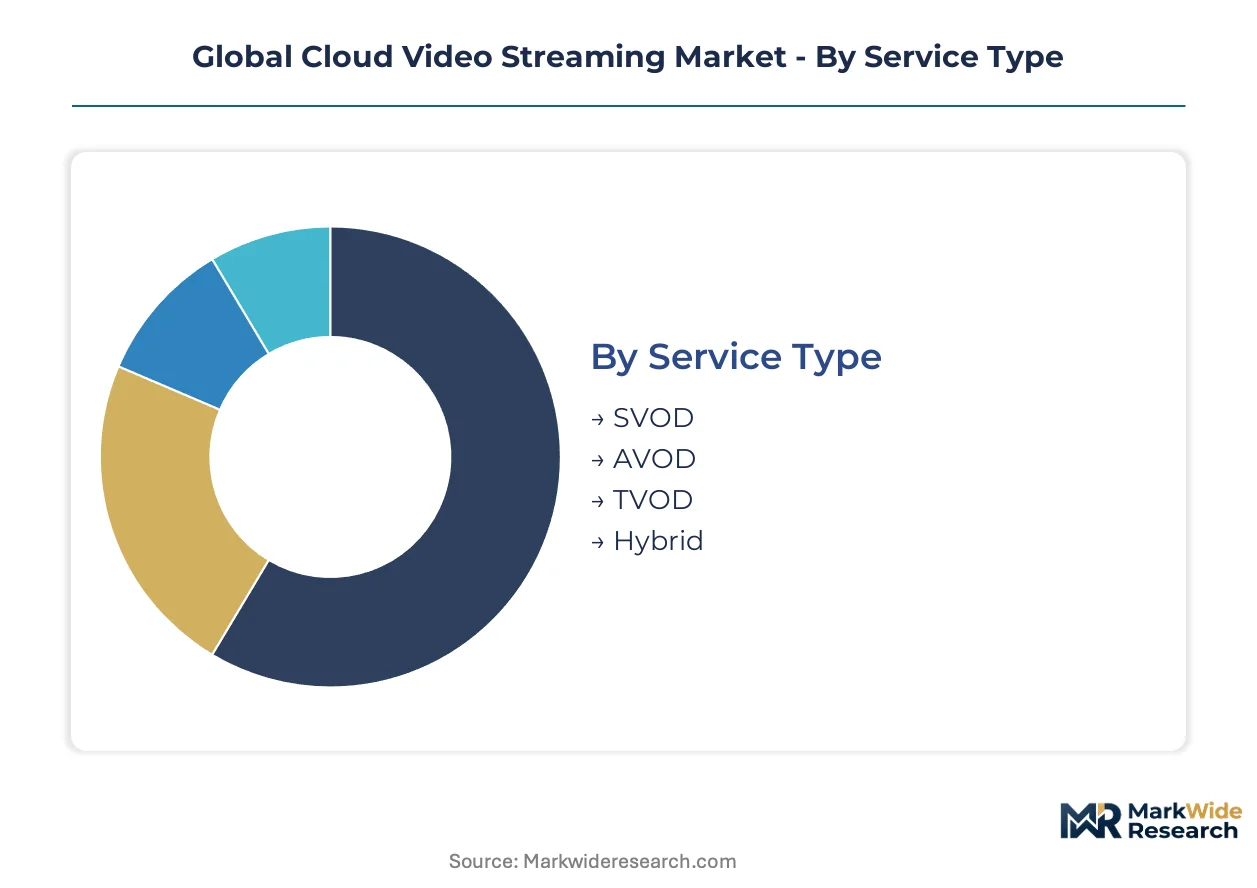
Cloud video streaming segmentation reveals how monetization models, infrastructure choices, and audience targets fragment capital allocation across the value chain. Each dimension carries distinct margin profiles and regulatory exposure that reshape provider strategy.
Service Type:
Monetization mechanics span recurring subscriptions, advertising-supported access, transactional purchases, and blended revenue architectures.
- SVOD:Subscription-based access to on-demand libraries dominates revenue pools across mature markets. Netflix and Disney+ deployments in the United States anchor infrastructure spend, though churn management costs erode lifetime value metrics.
- AVOD:Advertising-supported tiers monetize price-sensitive audiences through programmatic insertion and targeted pre-roll. Demand concentrates in India and Brazil where disposable income constraints limit subscription penetration.
- TVOD:Transactional rental and purchase models capture event-driven consumption around theatrical windows and live sports. Premium releases in Saudi Arabia and UAE drive regional platform investment.
- Hybrid:Blended subscription-advertising tiers optimize yield across audience microsegments. European broadcasters under GDPR constraints favor this flexibility for consent-based personalization.
Established volume favors SVOD; emerging adoption favors Hybrid.
End User:
Customer archetypes determine latency requirements, security protocols, and integration complexity.
- Consumers:Individual households demand 4K HDR playback across smart TVs, mobile devices, and gaming consoles. Binge-viewing patterns in South Korea and Japan strain peak bandwidth allocation.
- Enterprises:Corporate communications and all-hands broadcasts require SSO integration and audit logging. Financial services firms in the United Kingdom and Germany drive sovereign cloud deployments under GDPR Article 32.
- Educational Institutions:Universities and K-12 districts deploy lecture capture and flipped classroom workflows. Brazil's federal universities under ANATEL mandates accelerate local edge investment.
- Broadcasters:Traditional media companies migrate linear channels to IP delivery while maintaining SLA guarantees for live news and sports. Public broadcasters in France and Canada face distinct funding constraints.
Enterprise procurement expands most quickly; Consumer saturation compresses pricing power.
Technology:
Protocol selection governs latency floors, device compatibility, and encoding efficiency tradeoffs.
- HTTP Live Streaming:Apple's adaptive bitrate standard dominates iOS and macOS ecosystems with AES-128 encryption. Broadcasters targeting Apple TV penetration in the United States and Australia standardize on this stack.
- MPEG-DASH:The ISO-standardized alternative enables codec-agnostic delivery across Android and smart TV platforms. European operators under ETSI mandates favor DASH for interoperability certification.
- WebRTC:Sub-second latency protocol enables interactive use cases including live auctions and telemedicine. South Korean e-commerce platforms deploy WebRTC for flash sale events.
- RTMP:Legacy Real-Time Messaging Protocol persists in ingest workflows from hardware encoders. Taiwan-based manufacturing clusters sustain residual demand for RTMP-compatible production gear.
MPEG-DASH commands standardization momentum; WebRTC gains share fastest in latency-sensitive verticals.
Deployment:
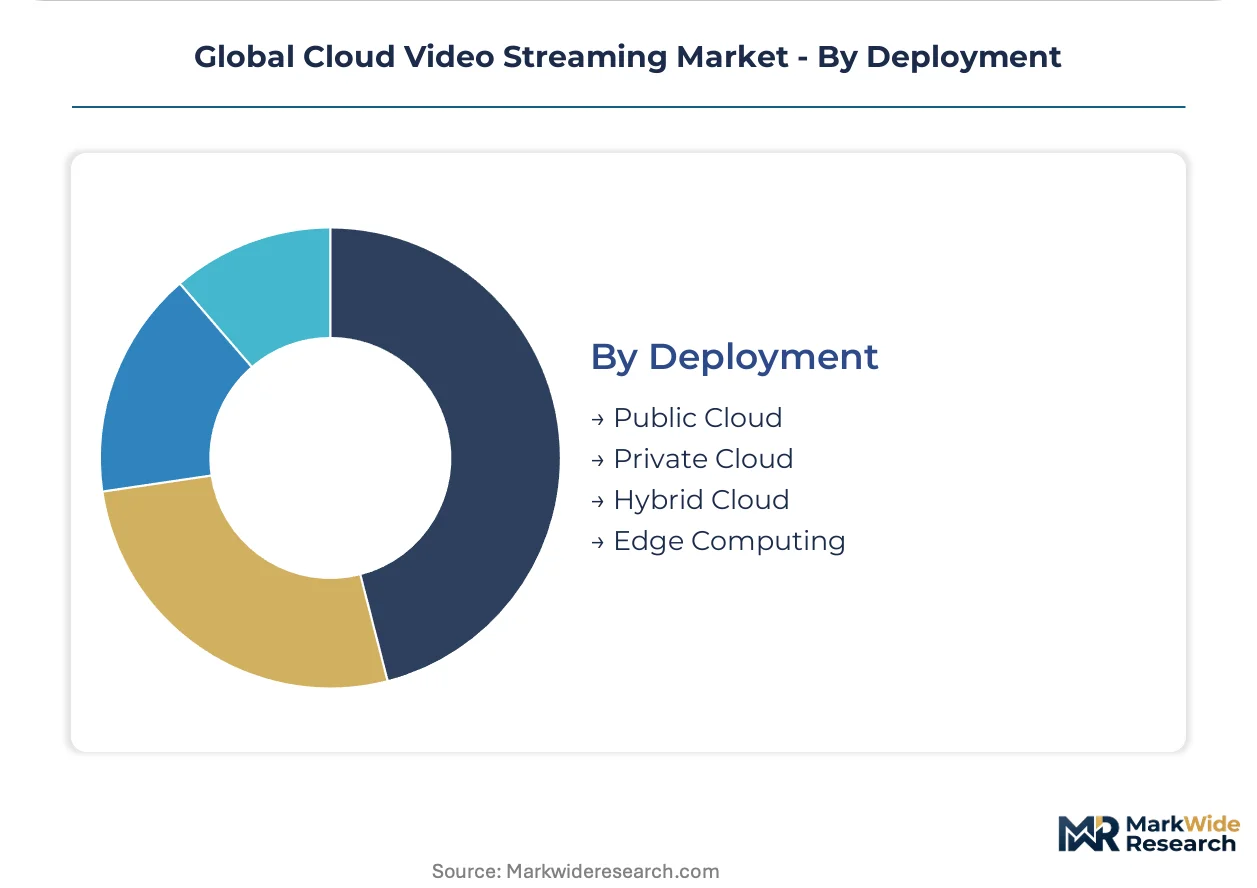
Infrastructure topology determines data residency compliance, burst elasticity, and operational control boundaries.
- Public Cloud:Hyperscale rental of compute and storage minimizes capital commitment for seasonal demand spikes. Indian SVOD platforms leverage Mumbai and Chennai regions for monsoon-season viewership surges.
- Private Cloud:Captive data centers satisfy security requirements for defense contractors and classified content. UAE government broadcasters mandate private deployment for national security programming.
- Hybrid Cloud:Split architectures place sensitive workloads on-premises while bursting transcoding to public infrastructure. German automotive manufacturers adopt this model for IP protection of training content.
- Edge Computing:Distributed micro-data centers within 50km of end users minimize last-mile latency. Brazilian providers deploy São Paulo and Rio de Janeiro nodes under ANATEL local presence rules.
Public Cloud absorbs volume growth; Edge Computing climbs fastest where latency SLAs harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in financial services and broadcast media drive infrastructure investment across sovereign markets. Regulatory fragmentation around data residency and content licensing shapes provider architecture decisions. Demand clusters in markets with accelerating direct-to-consumer platform buildouts and stringent compliance mandates.
United States
FCC net neutrality rules and broadband infrastructure subsidies determine streaming quality-of-service guarantees for broadcasters. The SEC's disclosure requirements for publicly traded platforms influence transparency standards for algorithmic recommendation systems. Los Angeles and New York media clusters anchor content production workflows that feed hyperscale delivery networks.
India
TRAI's OTT regulations and data localization guidelines reshape platform compliance costs for domestic and foreign operators. Tier-2 cities including Lucknow, Indore, and Coimbatore generate vernacular-language streaming demand that outpaces localized edge infrastructure deployment. Mumbai and Chennai hyperscale regions absorb monsoon-season viewership surges through burst elasticity contracts.
Brazil
ANATEL enforces local data residency mandates that accelerate provider investment in São Paulo and Rio de Janeiro edge nodes. Federal university systems under national connectivity programs drive demand for lecture-capture and flipped-classroom streaming workflows. The São Paulo metropolitan cluster concentrates broadcast migration from linear to IP delivery infrastructure.
Germany
GDPR Article 32 security requirements and EU AI Act algorithmic transparency mandates impose compliance retrofit costs on entertainment platforms. Automotive manufacturers in Baden-Württemberg adopt hybrid cloud architectures for IP protection of training content. Frankfurt's data center density supports sovereign cloud deployments for financial services streaming workloads.
South Korea
MFDS-equivalent content rating frameworks and KCC broadcasting standards govern platform operational requirements. E-commerce platforms deploy WebRTC infrastructure for flash sale events and interactive commerce integration. Seoul's technology corridor concentrates encoding optimization talent and semiconductor-adjacent video processing development.
Global Cloud Video Streaming Market Vendor Landscape
Channel-controlling players compete with product-specialist players across infrastructure, platform, and application layers. Hyperscale cloud providers dominate compute and storage rental, while edge-computing specialists and encoding-technology vendors occupy narrower vertical positions. Strategic archetypes include full-stack platform operators, point-solution infrastructure vendors, and workflow-integrated software providers. Competitive moves concentrate on geographic edge expansion and sovereign compliance certification.
Within the hyperscale infrastructure tier, Amazon Web Services and Google exemplify channel-controlling archetypes through data center footprint and cloud-native stack integration. Akamai Technologies occupies a position representing edge-computing density specialization for latency-sensitive broadcasters. IBM and Cisco Systems sit within the enterprise-integrated workflow segment, anchoring unified communications procurement decisions. Kaltura represents the vertical-focused platform archetype serving educational and corporate training deployments.
| Leading Market Players |
|---|
| Amazon Web Services |
| Akamai Technologies |
| IBM |
| Kaltura |
| Wowza Media Systems |
| Brightcove |
| Cisco Systems |
| Haivision |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific fiber routes connecting Los Angeles to Singapore and Hong Kong transmit encoded video traffic that incurs bandwidth costs indexed to electricity futures in California and Singapore. This corridor's volatility compresses margins for streaming providers serving Southeast Asian markets while amplifying price differentiation between premium low-latency tiers and standard adaptive bitrate delivery.
Pricing Analysis
Cost-plus contracts with hyperscale cloud providers index compute rental to regional electricity benchmarks and interconnection fees. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade SLA guarantees from enterprise training deployments and consumer entertainment tiers. Price differentiation hinges on latency SLAs and data residency certification levels, with GDPR-compliant sovereign cloud deployments commanding substantial premiums. Cost compression in the standard tier intensifies because Indian and Brazilian platforms negotiate burst-elasticity contracts that commoditize baseline encoding capacity. Enterprise financial services buyers exhibit lowest price sensitivity due to regulatory compliance requirements, while AVOD platforms in emerging markets resist subscription pricing entirely.
Supply Chain Analysis
Contract manufacturing concentration for advanced video encoding hardware rests with Taiwan Semiconductor Manufacturing and Samsung Foundry, which fabricate AV1 and VVC codec accelerators. Geographic supply concentration centers on Taiwan, South Korea, and Japan for semiconductor components, with China dominating edge server assembly and Brazil emerging as a regional integration hub under ANATEL local content rules. Raw material dependencies include silicon wafers, high-bandwidth memory modules, and specialized power management integrated circuits. Single-source vulnerability in Taiwan-based encoder fabrication threatens live broadcaster supply continuity during geopolitical disruptions. Distribution runs through hyperscale cloud marketplaces, direct OEM procurement for private cloud deployments, and systems integrators serving hybrid enterprise workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement consolidation across Fortune 500 technology departments has shifted buyer power toward decentralized cloud marketplace sourcing, fragmenting vendor negotiation leverage that previously favored comprehensive platform contracts.
For Market Incumbents: Entrench position through sovereign cloud certification investments in Frankfurt, São Paulo, and Mumbai to satisfy data residency mandates from GDPR, ANATEL, and TRAI. Acquire encoding optimization talent pools in South Korea's Seoul corridor to defend against WebRTC latency improvements from semiconductor-adjacent competitors. Prioritize backward integration into edge server manufacturing partnerships that bypass Taiwan supply concentration risks. For New Entrants and Emerging Players: India's Tier-2 cities including Lucknow, Indore, and Coimbatore present vernacular-language streaming demand that outpaces localized infrastructure deployment. Target educational institutions in Brazil's federal university system with lecture-capture workflows that bypass incumbent broadcast licensing complexity. Pursue channel partnerships with regional systems integrators rather than direct hyperscale competition. For Investors and Strategic Acquirers: Edge-computing specialists with ANATEL, GDPR, and TRAI compliance certifications represent the most defensible acquisition archetype as data residency rules harden. Long-term viability requires exposure to enterprise verticals replacing legacy video conferencing with integrated streaming workflows. Monitor hyperscaler capex allocation to Mumbai, São Paulo, and Frankfurt regions as inflection indicators for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 32 and EU AI Act compliance unlocks financial services procurement in Frankfurt. |
| Edge Node Expansion | São Paulo and Rio de Janeiro deployments satisfy ANATEL data residency for Brazilian broadcasters. |
| Codec Optimization Partnership | Seoul-based semiconductor collaboration accelerates AV1 encoding efficiency for live sports tiers. |
| Enterprise Workflow Integration | SSO and audit logging capabilities capture corporate training budgets from legacy conferencing vendors. |
| Interactive Commerce Platform | WebRTC integration with real-time payment rails serves South Korean flash sale and auction verticals. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, TRAI regulatory filings, and EU AI Act implementation guidance. Interviews with cloud platform engineers, enterprise IT procurement officers, streaming operations directors, and broadcast technology consultants informed demand-side validation. Secondary sources include SEC 10-K infrastructure spend disclosures, ANATEL spectrum allocation records, and ETSI interoperability certification databases. Bottom-up encoding capacity modeling triangulates against top-down addressable market sizing across service type and deployment topology segments.
Forecast inputs include hyperscale region expansion timelines, enterprise video conferencing replacement cycles, and regulatory compliance retrofit cost curves across the projection horizon. Segmentation dimensions span monetization model, end-user archetype, protocol technology, and infrastructure deployment topology. CAGRs derive from elasticity-adjusted capacity buildout trajectories and substitution effects between public cloud and edge computing configurations. Industry-specific inputs incorporate WebRTC latency floor constraints in asymmetric broadband markets and encoder hardware fabrication capacity utilization.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign cloud specialists or WebRTC-native entrants would shift outcomes beyond modeled ranges. Regulatory acceleration in India, Brazil, or EU jurisdictions could compress compliance timelines. Quarterly review of hyperscaler regional capex allocation, TRAI OTT enforcement actions, and Taiwan semiconductor capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market